
Market Overview
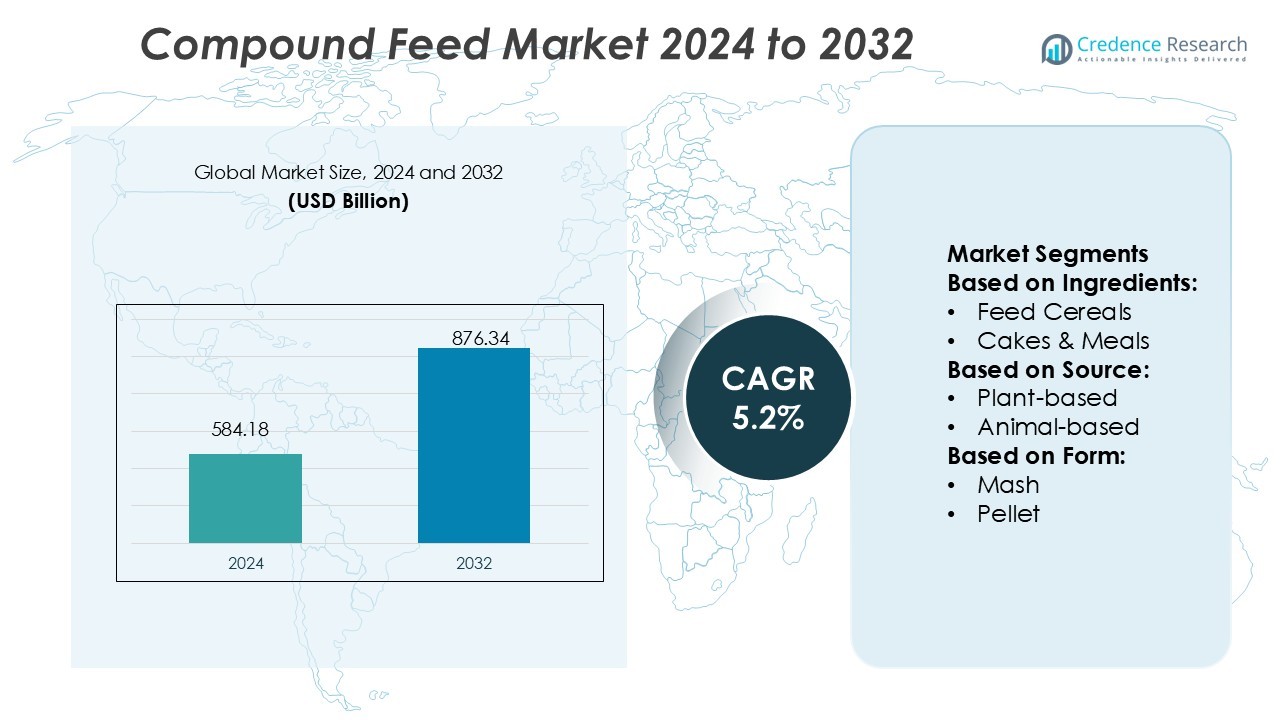
Compound Feed Market size was valued USD 584.18 billion in 2024 and is anticipated to reach USD 876.34 billion by 2032, at a CAGR of 5.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Compound Feed Market Size 2024 | USD 584.18 Billion |
| Compound Feed Market, CAGR | 5.2% |
| Compound Feed Market Size 2032 | USD 876.34 Billion |
The Compound Feed Market is driven by key players such as Cargill Incorporated, Archer Daniels Midland Company (ADM), Charoen Pokphand Group, Land O’ Lakes, Alltech, Guangdong Haid Group, Roquette, Kent Nutrition Group, Feed One Co., and Indian Broiler Group Pvt Ltd. These companies focus on innovation in feed formulation, sustainable ingredient sourcing, and advanced animal nutrition solutions to strengthen their global presence. Strategic expansions, technological integration, and R&D investments remain central to their growth strategies. Asia-Pacific leads the global Compound Feed Market with a 38% share in 2024, driven by high livestock production, strong government support, and rapid adoption of advanced feed technologies across major economies such as China, India, and Vietnam.
Market Insights
- The Compound Feed Market was valued at USD 584.18 billion in 2024 and is projected to reach USD 876.34 billion by 2032, registering a CAGR of 5.2% during the forecast period.
- Market growth is driven by rising livestock production and growing demand for high-quality meat, dairy, and aquaculture products worldwide.
- Technological advancements in feed formulation, precision nutrition, and automation are enhancing feed efficiency and reducing production costs.
- Asia-Pacific leads the global market with a 38% share, followed by Europe and North America, supported by large-scale poultry and cattle farming.
- The feed cereals segment dominates with a 43% share due to its high nutritional value and cost-effectiveness, while major players such as Cargill, ADM, and Charoen Pokphand Group focus on sustainable sourcing, R&D investments, and digital feed management to strengthen their global competitiveness.
Market Segmentation Analysis:
By Ingredients
Feed cereals dominated the Compound Feed Market with a 43% share in 2024. This dominance stems from high nutrient density, affordability, and widespread availability of corn, wheat, and barley. The segment’s growth is driven by increasing livestock production and the rising use of fortified cereal blends for better feed conversion efficiency. Cakes and meals follow closely, supported by expanding oilseed processing industries, while supplements and animal by-products contribute to improved animal health and productivity through enhanced nutrient absorption and digestibility.
- For instance, Cargill recently opened a new retail feed facility in Granger, Washington, which can produce and package 120,000 tons of animal feed annually, utilizing advanced systems like AI-based bag sealing assurance, ultra-low tolerance mixing, and full automation across production lines.
By Source
Plant-based feed sources accounted for a dominant 61% share of the Compound Feed Market in 2024. The demand is primarily driven by sustainability goals and the lower cost of plant-derived proteins such as soybean, corn, and wheat bran. These ingredients ensure balanced amino acid content and support efficient livestock weight gain. In contrast, animal-based feeds continue to serve niche segments, providing essential nutrients like omega-3 fatty acids, but face limitations due to fluctuating raw material prices and strict regulatory norms in several regions.
- For instance, Haid Group holds more than 200 patents covering areas like plant protein processing, enzyme hydrolysis, and feed additive technologies, highlighting its innovation in animal nutrition and health.
By Form
Pellet form feed led the market with a 52% share in 2024, supported by its uniform texture, improved digestibility, and ease of storage and transport. The segment’s popularity is growing among commercial poultry and cattle producers due to reduced wastage and consistent nutrient distribution. Mash and crumble forms retain steady demand in small-scale and starter feed applications, where flexibility and affordability are key. The adoption of pelleted feeds is further driven by automated feeding systems that improve operational efficiency in large-scale livestock farms.
Key Growth Drivers
Rising Livestock Production and Meat Consumption
Growing global demand for meat and dairy products is fueling livestock production, directly boosting compound feed consumption. Rising incomes, urbanization, and changing dietary habits in emerging economies are key contributors. Poultry and swine sectors account for major feed demand, while aquaculture feed is gaining momentum. The drive to enhance animal productivity and ensure consistent nutrient intake supports the widespread use of scientifically formulated compound feed across regions.
- For instance, Kent Nutrition Group’s Product Development Center (PDC) sits on almost 800 acres and comprises five species- and life-stage-specific research units, enabling large-scale, controlled feeding trials.
Technological Advancements in Feed Formulation
Innovations in feed formulation, precision nutrition, and enzyme integration are transforming the compound feed industry. Advanced feed additives such as probiotics, amino acids, and enzymes help optimize feed conversion ratios, reducing feed costs. Automation in feed mills and data-driven monitoring systems improve quality consistency and production efficiency. These advancements enable manufacturers to deliver nutrient-balanced feed tailored to specific livestock requirements, enhancing overall animal health and profitability.
- For instance, CP Foods partnered with VEGA in 2024 to install radar sensor systems across 14 feed factories in Thailand, Vietnam, the Philippines, and Cambodia, enabling real-time monitoring of raw material levels in silos to avoid stockouts and overflows.
Government Support and Sustainable Feed Practices
Government policies promoting sustainable livestock farming and feed efficiency are driving market growth. Subsidies for feed production, investments in R&D, and sustainable sourcing initiatives encourage adoption of compound feed. The focus on reducing methane emissions and improving nutrient utilization aligns with environmental goals. Companies are increasingly using eco-friendly ingredients, such as plant-based proteins and insect meal, to meet sustainability standards and consumer expectations for responsible food production.
Key Trends & Opportunities
Shift Toward Functional and Specialty Feed Additives
There is a growing trend toward incorporating functional additives like probiotics, prebiotics, and enzymes to enhance gut health and immunity. Producers are investing in customized formulations for poultry, dairy, and aquaculture to improve performance and reduce antibiotic dependency. The rise of organic and non-GMO feed options also presents opportunities for niche growth. This shift reflects the industry’s move toward precision nutrition and health-focused animal diets.
- For instance, Alltech published a meta-analysis covering 25 studies across 11 countries and 10,307 broiler birds showing that inclusion of their yeast cell wall extract Mycosorb® under mycotoxin stress improved survivability and performance while reducing carbon footprint.
Digitalization and Smart Feed Management
Feed manufacturers are adopting digital tools for production optimization, inventory management, and predictive analytics. IoT-enabled sensors and AI-based systems help track feed quality and animal performance in real time. These technologies reduce resource wastage and enhance operational efficiency. The integration of automation in feed mills, combined with cloud-based monitoring, provides significant opportunities for scaling productivity and ensuring consistent quality across global operations.
- For instance, Givaudan's Taste & Wellbeing division delivers a large volume of unique natural flavor and functional ingredient formulations, supporting its leadership in the naturals space. The company manages over 300,000 customer briefs and submissions annually across its business units.
Key Challenges
Volatility in Raw Material Prices
Fluctuating prices of raw materials such as corn, soybean, and fishmeal pose major challenges for feed manufacturers. Supply chain disruptions, climate variability, and trade restrictions further intensify cost pressures. These price swings impact profitability and hinder stable feed pricing for farmers. Companies are adopting ingredient diversification and long-term sourcing contracts to mitigate these risks and maintain market stability.
Regulatory Constraints and Environmental Concerns
Stringent feed safety and environmental regulations limit ingredient flexibility and increase compliance costs. Regions like Europe and North America enforce strict controls on antibiotic usage, waste management, and emission levels. Meeting these standards requires continuous investment in sustainable practices and product innovation. Balancing profitability with compliance and sustainability remains a key challenge for compound feed producers worldwide.
Regional Analysis
North America
North America held a 24% share of the global Compound Feed Market in 2024, supported by large-scale livestock farming and strong demand for high-quality meat and dairy products. The United States leads the region with advanced feed manufacturing technologies and widespread adoption of precision nutrition practices. Rising awareness of animal health and sustainable farming further drives feed innovation. Canada and Mexico contribute steadily through expanding poultry and swine production. Growing investments in automated feed mills and nutritional research continue to enhance productivity and competitiveness across the region.
Europe
Europe accounted for a 27% share of the Compound Feed Market in 2024, driven by stringent regulations promoting animal welfare and sustainable agriculture. Major producers such as Germany, France, and the Netherlands dominate regional output. The region focuses heavily on reducing antibiotic use and increasing organic feed adoption. Technological advancements in feed processing and ingredient traceability are strengthening supply chains. Growing demand for specialty feed formulations tailored to dairy cattle and poultry continues to support steady market expansion despite regulatory challenges and fluctuating raw material costs.
Asia-Pacific
Asia-Pacific led the Compound Feed Market with a dominant 38% share in 2024, fueled by rapid growth in livestock and aquaculture production. China, India, and Vietnam are key contributors, driven by urbanization, rising income levels, and growing meat consumption. Feed manufacturers are expanding production capacity and adopting advanced feed formulations to meet diverse nutritional requirements. Government initiatives supporting food security and sustainable farming also strengthen market growth. Expanding poultry and aquaculture industries, combined with rising feed exports, make Asia-Pacific the most dynamic region in the global market.
Latin America
Latin America represented an 8% share of the global Compound Feed Market in 2024, primarily driven by Brazil, Argentina, and Mexico. The region benefits from abundant raw materials, such as soybean meal and corn, making feed production cost-effective. Expanding cattle and poultry farming industries, coupled with growing meat exports, are supporting feed demand. Government incentives for livestock productivity improvement and the adoption of fortified feed formulations further contribute to market growth. However, challenges like limited infrastructure and price fluctuations in feed grains remain key barriers to expansion.
Middle East & Africa
The Middle East & Africa captured a 3% share of the Compound Feed Market in 2024, with increasing investments in modern livestock production. Countries such as Saudi Arabia, South Africa, and Egypt are focusing on improving feed self-sufficiency and reducing import dependency. Rapid population growth and rising meat consumption are key demand drivers. Feed producers are introducing nutrient-enriched formulations to enhance livestock performance in arid conditions. Despite infrastructural limitations and fluctuating feed costs, ongoing investments in sustainable agriculture and feed technology continue to boost regional growth potential.
Market Segmentations:
By Ingredients:
- Feed Cereals
- Cakes & Meals
By Source:
- Plant-based
- Animal-based
By Form:
- Mash
- Pellet
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Compound Feed Market is characterized by strong competition among leading players including Cargill Incorporated, Guangdong Haid Group, Kent Nutrition Group, Land O’ Lakes, Charoen Pokphand Group, Feed One Co., Alltech, Indian Broiler Group Pvt Ltd, Roquette, and Archer Daniels Midland Company (ADM). The Compound Feed Market is highly competitive, driven by continuous innovation, capacity expansion, and sustainability initiatives. Companies are focusing on optimizing feed efficiency through advanced formulations, digital monitoring, and precision nutrition. The market is witnessing increased investments in automation and data-driven feed production to improve quality control and reduce operational costs. Sustainability remains a key priority, with producers adopting plant-based proteins, eco-friendly additives, and traceable ingredient sourcing. Strategic partnerships, mergers, and acquisitions are common as companies aim to expand their global footprint and strengthen distribution networks. This competitive environment encourages continuous improvement in nutritional value, cost efficiency, and product differentiation.
Key Player Analysis
- Cargill Incorporated
- Guangdong Haid Group
- Kent Nutrition Group
- Land O’ Lakes
- Charoen Pokphand Group
- Feed One Co.
- Alltech
- Indian Broiler Group Pvt Ltd
- Roquette
- Archer Daniels Midland Company (ADM)
Recent Developments
- In July 2025, Cargill, Incorporated, has reached an agreement to sell its Malaysian animal feed subsidiary, Cargill Feed Sdn Bhd, to CAB Cakaran Corporation Berhad.The acquisition enables CAB to integrate feed production into its poultry operations, reducing its dependence on external feed suppliers.
- In March 2025, Indian Poultry Alliance (IPA), a subsidiary of the Allana Group, has acquired Kwality Animal Feeds Pvt. Ltd. for Rs. 300 crore with an additional Rs. 200 crore metric tons of annual pelleting capacity and a 12-state distribution footprint.
- In September 2024, The Hershey Company declared a new addition to its Kit Kat lineup: Kit Kat Vanilla. The brand's new flavor features crisp wafers enrobed in vanilla-flavored crème. It is now available in standard and king sizes at retailers nationwide.
- In April 2024, according to the company, Glanbia PLC is growing its better nutrition platforms by acquiring Flavor Producers LLC from Aroma Holding Co., LLC. for an initial plus deferred consideration.
Report Coverage
The research report offers an in-depth analysis based on Ingredients, Source, Form and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The compound feed market will expand with growing global demand for meat and dairy products.
- Precision nutrition and smart feed technologies will improve feed efficiency and animal performance.
- Sustainable and plant-based feed ingredients will gain higher adoption across all livestock sectors.
- Investments in automation and digital monitoring will enhance production accuracy and consistency.
- Government initiatives supporting food security and animal welfare will strengthen market stability.
- Rising demand for aquaculture and poultry feed will drive innovation in feed formulations.
- Functional additives such as probiotics and enzymes will replace antibiotic-based growth promoters.
- Strategic collaborations between feed producers and farmers will improve supply chain integration.
- Climate-resilient feed solutions will become a major focus to address raw material volatility.
- Expansion in emerging economies will create new opportunities for local and global feed manufacturers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Compound Feed Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Compound Feed Market projected to grow between 2025 and 2032?
Which Compound Feed Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Compound Feed Market?
Who are the leading companies in the Compound Feed Market?
Which region commanded the largest share of the Compound Feed Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 584.18 billion → 2032: USD 876.34 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Compound Feed Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Compound Feed Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Compound Feed Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Compound Feed Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Compound Feed Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Compound Feed Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Compound Feed Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Compound Feed Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 584.18 billion → 2032: USD 876.34 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Compound Feed Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Compound Feed Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Compound Feed Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Compound Feed Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

