
Market Overview
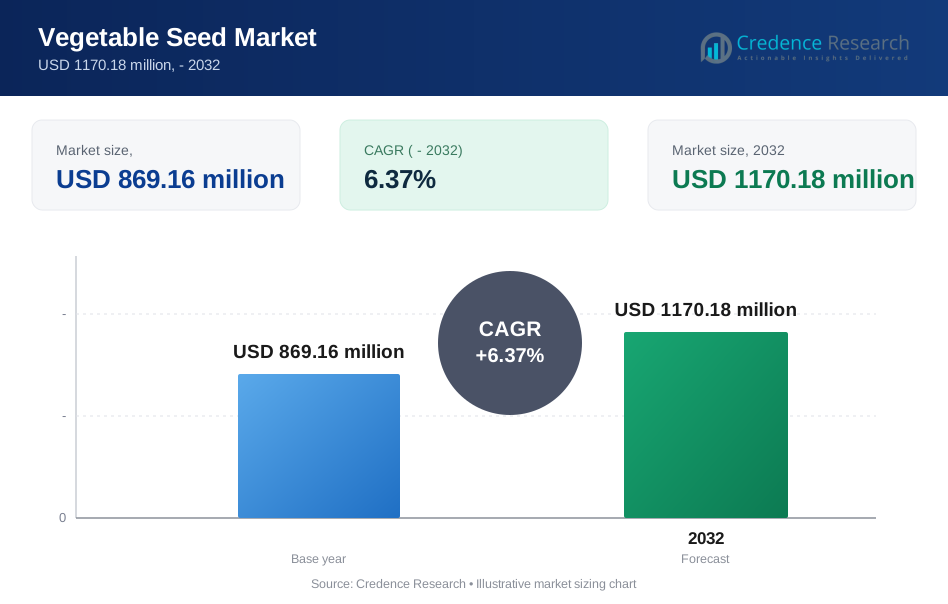
Vegetable Seed Market size was valued USD 869.16 million in 2024 and is anticipated to reach USD 1333.89 million by 2032, at a CAGR of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vegetable Seed Market Size 2024 | USD 869.16 Million |
| Vegetable Seed Market, CAGR | 5.5% |
| Vegetable Seed Market Size 2032 | USD 1333.89 Million |
The vegetable seed market is shaped by leading players such as FMC Corporation, Bayer AG, Kaveri Seeds, Enza Zaden, Groupe Limagrain, BASF SE, East-West Seeds, Corteva Agriscience, Advanta Seeds - UPL, and DLH, all of whom focus on innovation, hybrid development, and global expansion strategies. These companies invest heavily in R&D to deliver high-yielding, disease-resistant, and climate-resilient seed varieties, ensuring strong competitiveness worldwide. Regionally, Asia-Pacific leads the market with a 35% share, driven by extensive farming areas, high vegetable consumption, and government support for hybrid seed adoption, positioning it as the dominant hub for future growth.
Market Insights
- The Vegetable Seed Market was valued at USD 869.16 million in 2024 and is projected to reach USD 1333.89 million by 2032, growing at a CAGR of 5.5%.
- Rising demand for nutrient-rich vegetables and adoption of hybrid and organic seeds are key drivers fueling growth across global markets.
- A major trend is the integration of biotechnology and precision agriculture, enabling high-yielding, disease-resistant, and climate-resilient seed varieties.
- Competitive dynamics are shaped by players such as FMC Corporation, Bayer AG, BASF SE, and others, focusing on R&D, innovation, and regional expansion despite challenges like high production costs and strict regulatory barriers.
- Asia-Pacific leads the market with 35% share, followed by North America at 28% and Europe at 24%, while conventional seeds dominate with the largest segment share, supported by strong farmer adoption for stable yields and affordability.
Market Segmentation Analysis:
By Crop Family
The brassicas segment, led by cauliflower and broccoli, holds the largest market share within the vegetable seed market. Their dominance is supported by rising global demand for nutrient-rich vegetables and their suitability for large-scale commercial farming. Growing health awareness, dietary diversification, and expansion in high-value export markets also drive adoption. Cabbage and carrots maintain strong regional demand, but cauliflower and broccoli lead due to higher profitability per hectare, hybrid variety development, and wider adaptability to changing climates, strengthening their position as the dominant crop family segment.
- For instance, Bayer’s Seminis® Pennybridge broccoli hybrid requires 31,000–39,000 seeds per acre in warm climates; it has maturity of 80 days; its bead structure is fine-medium, and field trials show tighter florets and improved yield potential compared to variety BC1611.
By Form
The inorganic seeds segment dominates the market, holding a major share due to their affordability, accessibility, and consistent yield performance. Farmers prefer inorganic seeds because they offer higher production efficiency, resilience against diseases, and adaptability to diverse growing conditions. Organic seeds are expanding at a faster pace, driven by consumer demand for chemical-free produce and supportive organic farming policies. However, the larger share of inorganic seeds is sustained by their ability to deliver reliable output, essential for meeting global food security needs and large-scale commercial farming operations.
- For instance, Kaveri Seeds, a major Indian seed company, offers the hybrid maize variety "Kaveri-50" as part of its multi-crop portfolio. The company leverages its extensive network of over 65,000 retailers to supply a wide range of seeds, including maize, to farmers across India.
By Trait
Conventional seeds account for the largest market share, supported by their widespread acceptance, cost-effectiveness, and suitability across diverse farming practices. Farmers favor conventional varieties due to ease of cultivation, stable yields, and reduced regulatory challenges compared to genetically modified seeds. GM seeds are gaining traction in selective regions, offering resistance to pests and climate stress, but adoption remains limited due to strict regulations and consumer concerns. The dominant role of conventional seeds is reinforced by ongoing improvements in hybrid breeding technologies, ensuring better disease resistance and higher productivity.

Key Growth Drivers
Rising Demand for Nutrient-Rich Crops
The vegetable seed market is driven by increasing consumer preference for nutrient-rich, fresh produce that supports healthy lifestyles. Growing awareness of plant-based diets, coupled with demand for antioxidant-rich vegetables like broccoli, carrots, and spinach, enhances seed sales. Expansion in retail and online grocery platforms further accelerates accessibility to diverse vegetable varieties. This rising demand encourages farmers to adopt improved seed varieties with higher nutritional value and better yield potential, making nutrient-focused cultivation a central driver of market growth.
- For instance, Enza Zaden tested its baby spinach varieties ‘Crosstrek’, ‘Traverse’, and ‘Acadia’ under nitrogen levels of 0, 30, 60, 90, 120, and 150 mg/L in soilless substrate. ‘Crosstrek’ achieved a fresh mass of 921.4 g/m² at 120 mg/L, with significantly higher levels of β-carotene and lutein compared to lower nitrogen treatments.
Expansion of Commercial Farming Practices
Large-scale commercial farming significantly boosts the vegetable seed market by emphasizing hybrid varieties and high-yielding crops. The adoption of advanced irrigation systems, precision agriculture, and protected cultivation techniques enables farmers to maximize productivity from quality seeds. Favorable government policies, subsidies, and programs promoting modern agriculture further stimulate seed demand. Export-oriented cultivation of crops such as cauliflower, broccoli, and carrots also drives growth, as farmers prioritize seeds that deliver uniformity, disease resistance, and superior quality for international markets.
- For instance, at its Nunhems facility in ‘s-Gravenzande, Netherlands, BASF achieved a tomato yield of 121 kilograms per square metre under a hybrid LED+HPS lighting regimen delivering 300 µmol light intensity, showing about 40% higher yield than baseline trials without that regime.
Advancements in Seed Breeding Technologies
Technological innovations in seed breeding, including hybridization and biotechnology, are reshaping the vegetable seed market. Breeding programs now focus on disease resistance, climate adaptability, and extended shelf life to improve farmer profitability. Companies are also investing in molecular breeding and marker-assisted selection to accelerate the development of high-performance seed varieties. These advancements reduce crop losses, enhance output quality, and meet consumer expectations for sustainability. The rapid pace of R&D ensures that improved seed traits remain a consistent growth driver in the global market.
Key Trends & Opportunities
Shift Toward Sustainable and Organic Farming
The growing adoption of sustainable and organic farming creates new opportunities for the vegetable seed market. Rising consumer demand for chemical-free produce encourages farmers to opt for organic-certified seed varieties. Governments and private organizations are supporting organic transitions through subsidies and certification programs, expanding the availability of organic seeds. Seed companies are increasingly developing eco-friendly varieties that require fewer agrochemicals while maintaining strong yield performance, positioning sustainability as both a market trend and a long-term growth opportunity.
- For instance, East-West Seed implemented its SmartFarm digital system across over 24,000 acres of seed production farmland in six Asian regions, improving production accuracy with 96% on-time completion of crop protocols.
Expansion of Precision Agriculture and Digital Tools
The integration of precision agriculture and digital tools is becoming a major trend, optimizing vegetable seed performance. Farmers use data-driven platforms, sensors, and IoT solutions to determine the best seed varieties suited for specific soil and climate conditions. This shift enhances efficiency in input management and reduces production costs while ensuring higher output. Seed companies benefit from providing tailored solutions aligned with precision farming needs, opening new opportunities for growth and innovation in high-value crop seed development.
- For instance, Corteva’s the Pioneer Seeds app has exceeded 20,000 users, making it the largest app launched by Corteva.The app allows farmers to predict crop yields up to two months before harvest.
Key Challenges
High Production and R&D Costs
The vegetable seed market faces challenges due to the high costs of seed production and research investments. Developing hybrid and biotech seeds requires extensive trials, advanced facilities, and significant funding. These costs increase product prices, making advanced seed varieties less accessible for small-scale farmers. Moreover, the long development cycle for new varieties limits the speed of innovation. Balancing affordability with advanced features remains a key challenge for both seed companies and growers in maintaining competitiveness.
Regulatory Barriers and Consumer Resistance to GM Seeds
Strict regulations and consumer skepticism surrounding genetically modified (GM) seeds create barriers for market expansion. Many regions enforce rigorous approval processes, delaying commercialization and raising compliance costs for seed producers. Consumer resistance, driven by concerns about food safety and environmental impacts, further restricts adoption. These regulatory and societal constraints limit the potential benefits of GM traits such as pest resistance and climate adaptability. Overcoming these barriers requires effective communication, transparent practices, and supportive regulatory frameworks.
Regional Analysis
North America
North America holds a significant share of the vegetable seed market, accounting for 28% in 2024. The region’s growth is driven by large-scale adoption of hybrid seeds, advanced agricultural technologies, and high demand for diverse vegetable varieties. The United States leads the market due to its strong commercial farming sector, while Canada shows steady growth supported by organic farming practices and government-backed sustainability programs. Rising consumer preference for nutrient-rich and chemical-free produce further boosts seed adoption. Continuous investments in biotechnology and seed R&D strengthen North America’s position as a key market for innovation and quality-driven seed solutions.
Europe
Europe represents 24% of the vegetable seed market, supported by strong demand for organic and sustainable farming practices. Countries such as the Netherlands, France, and Germany dominate production with advanced seed breeding technologies and export-oriented cultivation. Regulatory frameworks promoting reduced chemical usage encourage greater adoption of organic-certified and hybrid seeds. Growing consumer focus on fresh, high-quality produce and increasing greenhouse farming activities also contribute to expansion. Europe’s competitive seed industry, combined with continuous innovation in disease-resistant and high-yielding varieties, ensures the region maintains a robust position in global vegetable seed production and consumption.
Asia-Pacific
Asia-Pacific leads the global vegetable seed market, commanding 35% share in 2024, making it the largest regional contributor. China and India are the dominant markets, fueled by vast agricultural lands, high vegetable consumption, and government initiatives promoting hybrid seeds. Rising income levels, urbanization, and dietary diversification are increasing demand for nutrient-rich vegetables, further stimulating seed adoption. The region also benefits from strong investments in seed breeding and growing use of protected cultivation methods. Asia-Pacific’s expanding role in exports and emphasis on productivity improvement positions it as the primary growth hub for the vegetable seed industry.
Latin America
Latin America accounts for 8% of the vegetable seed market, with Brazil and Mexico serving as key contributors. The region’s growth is fueled by the rising adoption of hybrid seeds and increasing demand for high-value vegetable exports. Favorable climatic conditions and government support for agricultural modernization encourage widespread seed adoption. Farmers in the region are shifting toward advanced cultivation methods, including greenhouse farming, to maximize yield and quality. Growing consumer awareness of health benefits associated with vegetables further strengthens market growth. Despite challenges like limited access to advanced technologies, Latin America shows steady expansion prospects.
Middle East & Africa
The Middle East & Africa holds 5% of the vegetable seed market, reflecting gradual but consistent growth. Rising demand for fresh produce, coupled with government investments in food security and modern farming practices, supports market development. Countries like South Africa, Saudi Arabia, and the UAE are increasingly adopting hybrid and organic seeds to meet nutritional needs and reduce import dependency. Water scarcity and arid conditions encourage the use of advanced seed varieties adapted to climate challenges. Although market share is smaller compared to other regions, supportive policies and growing agricultural innovation enhance future prospects for the region.
Market Segmentations:
By Crop Family:
- Cabbage
- Carrot
By Form:
- Organic
- Inorganic
By Trait:
- Genetically modified
- Conventional
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The vegetable seed market players such as FMC Corporation, Bayer AG, Kaveri Seeds, Enza Zaden, Groupe Limagrain, BASF SE, East-West Seeds, Corteva Agriscience, Advanta Seeds - UPL, and DLH. The vegetable seed market is defined by continuous innovation, technological advancements, and strong global distribution networks. Companies focus on developing high-yielding, disease-resistant, and climate-resilient varieties to meet rising demand for nutrient-rich and sustainable crops. Hybrid seed development, molecular breeding, and biotechnology remain central strategies to improve productivity and quality. Investments in research and development, coupled with collaborations and acquisitions, are strengthening market positions across regions. Additionally, growing emphasis on organic and eco-friendly seed varieties highlights the industry’s response to changing consumer preferences, ensuring long-term competitiveness and market expansion.
Key Player Analysis
- FMC Corporation
- Bayer AG
- Kaveri Seeds
- Enza Zaden
- Groupe Limagrain
- BASF SE
- East-West Seeds
- Corteva Agriscience
- Advanta Seeds - UPL
- DLH
Recent Developments
- In April 2025, Bayer Vegetable Seeds, under its Seminis and De Ruiter brands, worked on providing innovative solutions to promote sustainable agriculture. They focused on advancing a carbon-zero future, supporting higher-yielding crops with fewer resources, and empowering smallholder farmers.
- In February 2025, Namdhari Seeds announced the acquisition of 100% of the open field vegetable seed business of Axia Vegetable Seeds. The acquisition included crops such as tomatoes, peppers, melons, and cucumbers, marketed under the US Agriseeds brand in multiple regions. As part of the deal, Catalyst Seeds, New World Seeds, and California Hybrids became part of Namdhari Seeds.
- In January 2025, Syngenta Crop Protection announced the divestment of its FarMore Technology Vegetable Seed Treatment Platform in the U.S. to Gowan SeedTech LLC. The transaction included the transfer of trademarks, recipes, registrations, and other assets, with Syngenta agreeing to continue supplying its proprietary seed treatment products to Gowan.
- In August 2024, BASF announced the upcoming launch of two new high‑performance InVigor® hybrid canola varieties for the 2025 growing season in Australia. These varieties combine PodGuard®, LibertyLink®, and TruFlex traits, offering improved yield potential, shatter tolerance, and flexible weed control options for growers.
Report Coverage
The research report offers an in-depth analysis based on Crop Family, Form, Trait and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The vegetable seed market will expand with rising demand for nutrient-rich vegetables.
- Hybrid seed adoption will increase as farmers seek higher yields and disease resistance.
- Organic seed demand will grow with consumer preference for chemical-free produce.
- Biotechnology and molecular breeding will drive faster development of resilient varieties.
- Precision agriculture tools will enhance seed performance and optimize crop management.
- Climate-adapted seed varieties will gain importance to address changing weather conditions.
- Export-oriented vegetable cultivation will boost demand for uniform and high-quality seeds.
- Investments in research and development will strengthen innovation in seed traits.
- Partnerships and acquisitions will shape global competitiveness among seed companies.
- Sustainable farming initiatives will continue to create long-term opportunities for seed producers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Weight Training Bench Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Weight Training Bench Market projected to grow between 2025 and 2032?
Which Weight Training Bench Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vegetable Seed Market?
Who are the leading companies in the Vegetable Seed Market?
Which region commanded the largest share of the Vegetable Seed Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vegetable Seed Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vegetable Seed Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 869.16 million → 2032: USD 1170.18 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vegetable Seed Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vegetable Seed Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vegetable Seed Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vegetable Seed Market Drivers
- 3.3 Vegetable Seed Market Restraints & Challenges
- 3.4 Vegetable Seed Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vegetable Seed Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vegetable Seed Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vegetable Seed category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vegetable Seed Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vegetable Seed Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vegetable Seed market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vegetable Seed Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vegetable Seed Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vegetable Seed Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vegetable Seed (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vegetable Seed Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vegetable Seed Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vegetable Seed Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vegetable Seed Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vegetable Seed Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vegetable Seed Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vegetable Seed Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vegetable Seed Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vegetable Seed Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
