
Market Overview
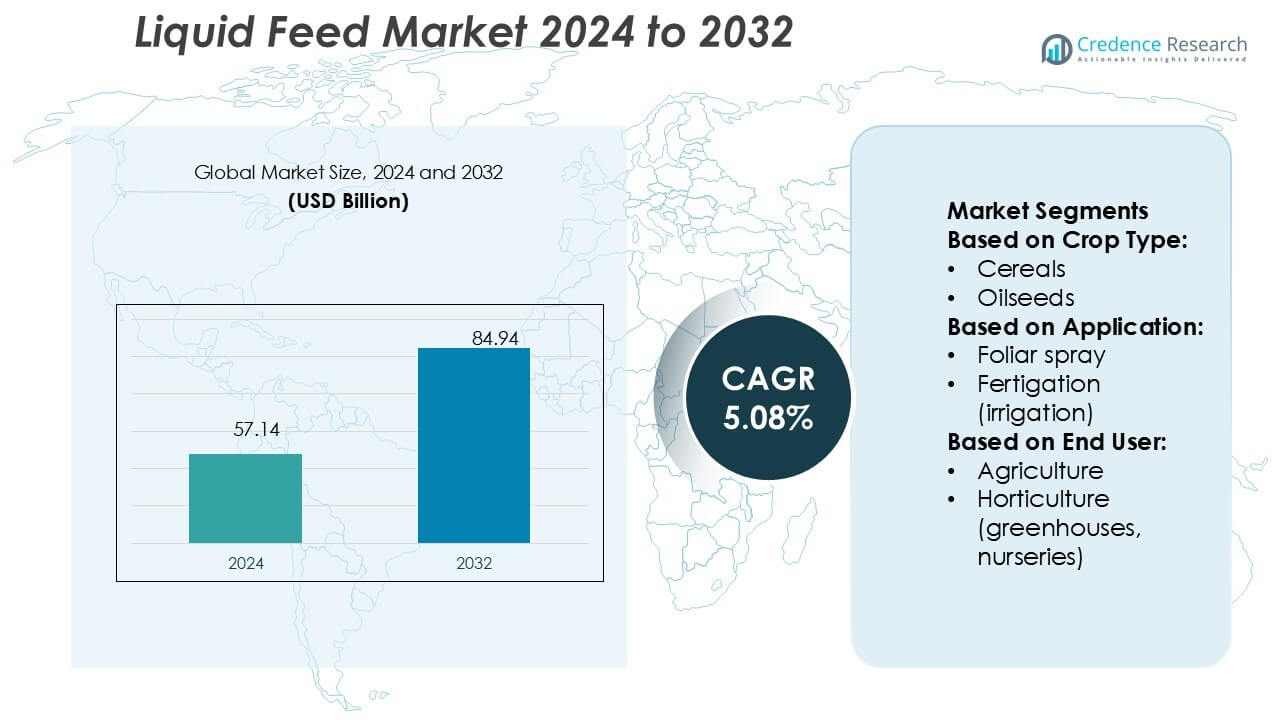
Liquid Feed Market size was valued USD 57.14 billion in 2024 and is anticipated to reach USD 84.94 billion by 2032, at a CAGR of 5.08% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Liquefied Petroleum Gas Storage Market Size 2024 | USD 57.14 Billion |
| Liquefied Petroleum Gas Storage Market, CAGR | 5.08% |
| Liquefied Petroleum Gas Storage Market Size 2032 | USD 84.94 Billion |
The liquid feed market is characterized by strong competition among top players, including EuroChem Group, Nutri-Tech Solutions Pty Ltd, ICL, FoxFarm Soil & Fertilizer Co, Nutrien Ltd., CSBP, Compo Expert, IFFCO, BMS Micro-Nutrients NV, and K+S Aktiengesellschaft. These companies focus on fortified formulations, sustainable innovations, and advanced distribution strategies to strengthen their global presence. Nutrien Ltd. and EuroChem Group leverage extensive networks, while Compo Expert and ICL emphasize specialized blends to meet diverse nutritional requirements. Regionally, Asia-Pacific leads the market with a 34% share in 2024, supported by rapid livestock growth, strong manufacturing capacity, and rising protein consumption across China, India, and Australia.
 Market Insights
- The liquid feed market size was USD 57.14 billion in 2024 and is projected to reach USD 84.94 billion by 2032, growing at a CAGR of 5.08%.
- Rising demand for livestock productivity and fortified nutritional blends is driving adoption across agriculture, dairy, and poultry segments.
- Asia-Pacific leads with a 34% share in 2024, while North America follows with 28%, supported by advanced livestock farming practices.
- Strong competition among players such as Nutrien Ltd., EuroChem Group, and ICL shapes the market through product innovation and sustainable feed solutions.
- Volatility in raw material prices and strict regulatory compliance remain key restraints, but ongoing investments in sustainable formulations and precision feeding create new growth opportunities.
Market Segmentation Analysis:
By Crop Type
Cereals dominate the liquid feed market with a 39% share in 2024, driven by their large-scale cultivation and high nutrient demands. Farmers adopt liquid feeds for cereals to enhance growth efficiency, boost yield, and improve soil fertility management. Oilseeds also contribute significantly, supported by expanding demand for protein-rich crops in food and biofuel industries. Fruits and vegetables, along with horticultural plants, are niche users, mainly benefiting from targeted nutrient delivery and quality enhancement. This segmentation reflects how staple crops continue to drive consistent demand for liquid feed solutions.
- For instance, ICL introduced eqo.x, a biodegradable controlled-release coating for urea that boosts nutrient use efficiency by up to 80%, degrades faster, and provides predictable nutrient release for open-field applications.
By Application
Fertigation leads with 41% share due to its efficiency in nutrient application through irrigation systems. The method reduces nutrient loss, enhances absorption, and supports water conservation practices in modern agriculture. Foliar spray remains a strong secondary segment, favored for immediate nutrient uptake and visible plant response. Soil drench is applied for targeted root-zone feeding, while seed treatment plays a smaller but strategic role in boosting early germination. The dominance of fertigation highlights the growing preference for precision farming techniques that align with sustainable practices and productivity gains.
- For instance, AmeriGas a part of UGI Corporation, AmeriGas indeed operates a vast network. Recent UGI financial filings confirm a network of approximately 1,380 propane distribution locations serving customers across the United States.
By End User
Agriculture accounts for the largest share at 47%, reflecting the high demand for liquid feed across staple food and cash crop farming. Farmers rely on liquid fertilizers to enhance crop yield and meet the rising food security needs globally. Horticulture, particularly greenhouses and nurseries, forms the second key segment, leveraging liquid feeds for ornamental plants and specialty crops. Turf and lawn care contribute steadily, supported by demand from landscaping and sports facilities. The segmental dominance of agriculture underscores its central role in shaping demand for nutrient-efficient feed products.
Key Growth Drivers
Rising Demand for Efficient Crop Nutrition
The growing emphasis on improving agricultural productivity drives the liquid feed market. Farmers adopt liquid feed solutions due to their quick absorption and higher nutrient availability compared to traditional solid fertilizers. This efficiency results in enhanced crop yield, reduced nutrient losses, and lower operational costs. Rising global food demand intensifies the need for optimized cultivation methods, positioning liquid feed as a cost-effective solution. Governments promoting sustainable agricultural practices further strengthen adoption, creating long-term opportunities for market expansion across multiple crop categories.
- For instance, Nutrien’s retail arm markets its Riser® in-furrow nutrition system for row crops, which applies micronutrient blends (e.g., zinc, boron) at a rate of 2.0 to 5.0 gallons (approximately 7.6 to 18.9 liters) per acre along with base fertilizer, ensuring forage or feed crops receive balanced nutrition early in growth.
Expansion of Livestock and Dairy Farming
The global increase in livestock production supports the demand for liquid feed formulations. Liquid feed supplements help improve digestion, enhance feed conversion rates, and support animal growth and milk production. With rising meat and dairy consumption in emerging economies, producers adopt advanced feeding methods to ensure consistent quality and yield. Liquid feed also aids in improving animal health, reducing mortality, and increasing overall farm profitability. Strategic adoption of fortified blends to meet nutritional gaps is a key factor driving growth in the livestock sector.
- For instance, during a pilot program in Western Australia, CSBP, in partnership with Telstra, installed more than 150 IoT sensors on the fertilizer storage tanks of 26 growers.
Technological Advancements in Feed Formulation
Continuous innovation in liquid feed formulation plays a major role in market growth. Companies develop customized blends enriched with vitamins, trace minerals, and amino acids tailored to specific animal requirements. Advancements in biotechnology improve digestibility and reduce anti-nutritional factors, boosting performance outcomes. Precision feeding systems enable farmers to deliver exact nutrient doses, reducing waste and optimizing feed efficiency. These innovations, combined with digital monitoring technologies, enhance farm productivity and sustainability, attracting investments from both established manufacturers and agri-tech startups globally.
Key Trends & Opportunities
Shift Toward Sustainable and Eco-Friendly Solutions
Sustainability emerges as a core trend in the liquid feed market. Producers focus on environmentally friendly formulations using bio-based additives and natural raw materials. This shift aligns with consumer preferences for sustainable farming and government policies targeting reduced environmental impact. Opportunities arise for companies innovating with organic-certified feed solutions and low-carbon production methods. The sustainability trend is expected to strengthen global adoption, particularly in developed markets emphasizing eco-label certifications and green farming initiatives.
- For instance, Compo Expert began sourcing 25 % of its ammonia demand in low-carbon form from Q2 2024, a measure projected to avoid 15,000 tonnes CO₂ emissions annually.
Growth of Precision Agriculture and Smart Farming
The integration of liquid feed with precision farming technologies opens new opportunities. Smart sensors and automated irrigation systems allow targeted application of liquid feed directly to crops or livestock. This reduces nutrient wastage, enhances soil fertility, and optimizes input costs. Farmers benefit from real-time monitoring, ensuring improved efficiency and yields. The expansion of digital agriculture platforms accelerates adoption, especially in regions investing in agri-tech infrastructure. Precision agriculture strengthens the role of liquid feed as a strategic tool for sustainable intensification.
- For instance, IFFCO’s cloud-based IFFCO Kisan Uday platform now manages data for 2,500 IFFCO Kisan drones, enabling farmers to book, view, and control nano-fertilizer spraying operations in real time.
Expanding Adoption in Horticulture and Turf Management
Beyond agriculture and livestock, liquid feed sees growing use in horticulture and turf care. Greenhouses, nurseries, and turf managers adopt liquid feed for ornamental plants, flowers, and lawns due to its rapid absorption and visible results. Rising urban landscaping and commercial green space projects further expand this niche. Companies offering specialized formulations for non-traditional crops can capture significant market share. This trend diversifies demand sources, reducing dependency on traditional farming and opening new revenue streams for manufacturers.
Key Challenges
Volatility in Raw Material Prices
The market faces challenges due to fluctuations in prices of essential raw materials such as molasses, grains, and oilseed byproducts. Supply chain disruptions and global trade restrictions often increase costs, impacting production margins. Manufacturers struggle to maintain competitive pricing, especially in price-sensitive emerging markets. Volatility in raw material supply also limits consistent product availability. Addressing this challenge requires strategic sourcing, contract farming, and diversification of raw material inputs to ensure stability and reduce dependency on single sources.
Regulatory and Quality Compliance Barriers
Strict regulations on animal feed safety and environmental standards pose barriers for producers. Different countries enforce varying compliance norms on feed additives, nutrient composition, and labeling requirements. Non-compliance risks product recalls, reputational damage, and financial penalties. Meeting these standards increases operational costs for small and mid-sized players. Additionally, concerns regarding contamination, adulteration, or misuse of additives can restrict market expansion. Companies must invest in quality testing, certifications, and transparent supply chains to maintain credibility and regulatory approval across regions.
Regional Analysis
North America
North America holds a 28% share of the liquid feed market in 2024, supported by large-scale livestock production and advanced agricultural practices. The U.S. dominates due to high beef and dairy consumption, alongside strong adoption of nutritional feed supplements. Regulatory support for sustainable farming and precision feeding further accelerates adoption. Canada and Mexico contribute through expanding poultry and swine production. Investments in R&D for fortified blends and molasses-based feed additives strengthen the region’s position. The growing demand for premium meat and dairy ensures steady growth, making North America a critical hub for innovation and commercialization in liquid feed solutions.
Europe
Europe accounts for a 22% market share in 2024, driven by the region’s strong livestock sector and sustainable farming policies. Countries like Germany, France, and Spain lead adoption, with demand focused on dairy cattle and swine. The European Union’s strict feed safety regulations encourage the use of high-quality, traceable liquid feed supplements. Rising consumer demand for organic and ethically produced meat and dairy also supports market expansion. Investments in eco-friendly formulations and molasses alternatives align with the EU’s sustainability goals. With a focus on regulatory compliance and innovation, Europe maintains steady growth across diverse agricultural systems.
Asia-Pacific
Asia-Pacific leads the liquid feed market with a 34% share in 2024, driven by rapid population growth and rising protein consumption. China, India, and Australia dominate due to expanding livestock production and increasing adoption of fortified liquid feed blends. Strong manufacturing capacity and government-backed initiatives to improve food security further drive demand. The region’s poultry, aquaculture, and dairy industries show significant growth, supported by urbanization and higher disposable incomes. Increasing adoption of precision feeding technologies enhances productivity. Asia-Pacific’s dynamic growth trajectory positions it as the fastest-growing market, attracting heavy investments from both local manufacturers and multinational feed companies.
Latin America
Latin America represents a 10% share of the liquid feed market in 2024, with Brazil and Argentina as leading contributors. The region’s expanding beef and poultry industries generate high demand for nutritional feed solutions. Brazil, one of the world’s largest beef exporters, drives adoption of molasses-based and vitamin-fortified liquid feed. Growing aquaculture in Chile further supports market expansion. Despite challenges from economic volatility, demand remains stable due to increasing exports and domestic consumption. Rising adoption of sustainable agricultural practices and regional production partnerships provides opportunities for manufacturers to strengthen presence and address the needs of large-scale livestock farmers.
Middle East & Africa (MEA)
The Middle East & Africa accounts for a 6% share of the liquid feed market in 2024, with growth led by countries such as South Africa, Saudi Arabia, and Egypt. Rising demand for poultry and dairy products fuels adoption of liquid feed supplements, especially in arid regions where efficient nutrient delivery is essential. Government initiatives to boost food self-sufficiency and investments in livestock production support market development. However, limited local production capacity increases reliance on imports. With gradual adoption of fortified blends and improved distribution channels, MEA presents emerging opportunities for global players targeting untapped livestock and dairy markets.
Market Segmentations:
By Crop Type:
- Cereals
- Oilseeds
By Application:
- Foliar spray
- Fertigation (irrigation)
By End User:
- Agriculture
- Horticulture (greenhouses, nurseries)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The competitive landscape of the liquid feed market features leading players such as EuroChem Group, Nutri-Tech Solutions Pty Ltd, ICL, FoxFarm Soil & Fertilizer Co, Nutrien Ltd., CSBP, Compo Expert, IFFCO, BMS Micro-Nutrients NV, and K+S Aktiengesellschaft. The liquid feed market is highly competitive, driven by continuous innovation, product diversification, and regional expansion strategies. Companies focus on developing nutrient-rich formulations that enhance livestock performance, improve digestion, and support higher yields in meat and dairy production. Growing emphasis on sustainability encourages the introduction of eco-friendly blends using bio-based inputs and traceable supply chains. Advanced feed technologies, including precision nutrition and fortified additives, create differentiation among market participants. Strong investment in research, farmer partnerships, and global distribution networks further intensifies competition, with players aiming to capture emerging opportunities across agriculture, horticulture, and livestock sectors worldwide.
Key Player Analysis
- EuroChem Group
- Nutri-Tech Solutions Pty Ltd
- FoxFarm Soil & Fertilizer Co
- Nutrien Ltd.
- CSBP
- Compo Expert
- IFFCO
- BMS Micro-Nutrients NV
- K+S Aktiengesellschaft
Recent Developments
- In May 2025, Liquiadubos just announced the inauguration of its new liquid fertilizer plant in Ferreira do Alentejo, Portugal. It will be creating cutting-edge NPK-supported liquid fertilizers that aim to support olive and almond crops. The company will be investing heavily in environmental sustainability as well as focusing on reducing the import dependency. It will supply the Portuguese market with advanced fertilizers manufactured locally.
- In August 2024, Rallis India Limited launched a new water-soluble fertilizer called AQUAFERT fertigation Tomato. The fertilizer is designed to significantly boost the yield of tomato crops and comes in three grades.
- In July 2024, Nano Fertilizer Usage Promotion Maha Abhiyan by selecting 200 model nano village clusters in Haryana was launched by the Indian Farmers Fertiliser Cooperative Limited (IFFCO).
- In December 2023, ADM has reached an agreement to acquire PT Trouw Nutrition Indonesia, a subsidiary of Nutreco in Indonesia. This acquisition aims to enhance ADM's premix production capabilities, positioning the company to provide localized solutions and customized services in the region.
Report Coverage
The research report offers an in-depth analysis based on Crop Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The liquid feed market will continue to expand with rising global demand for animal protein.
- Adoption of fortified feed blends will grow as farmers seek better livestock productivity.
- Precision agriculture and smart farming technologies will enhance nutrient delivery efficiency.
- Sustainable and eco-friendly formulations will gain traction in developed and emerging markets.
- Investments in R&D will drive innovations in customized and targeted liquid feed solutions.
- Expansion in aquaculture and poultry farming will create new growth opportunities.
- Regulatory compliance and quality assurance will remain key priorities for market players.
- Strategic collaborations and partnerships will strengthen global distribution networks.
- Emerging economies will witness strong demand due to increasing food security needs.
- Digital platforms and data-driven insights will support future adoption of liquid feed solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Livestock and Dairy Farming
Global increases in livestock and dairy production are fueling demand for liquid feed supplements that improve animal health, feed conversion, and productivity. As meat and dairy consumption rises, especially in emerging economies, producers are adopting advanced liquid feed solutions to ensure consistent quality and yield.
Technological Advancements in Feed Formulation
Continuous innovation in liquid feed formulations, including the development of customized blends with vitamins, trace minerals, and amino acids, is enhancing nutrient delivery and absorption. Precision feeding systems and digital monitoring technologies are enabling more efficient and sustainable farm management.
Shift Toward Sustainable and Eco-Friendly Solutions
Growing consumer and regulatory emphasis on sustainability is driving the adoption of bio-based, low-carbon, and organic-certified liquid feed products. Companies are investing in environmentally friendly formulations and traceable supply chains to meet evolving market and policy requirements.
Growth of Precision Agriculture and Smart Farming
The integration of liquid feed with precision agriculture technologies, such as smart sensors and automated irrigation, allows for targeted nutrient application, reducing waste and optimizing input costs. This trend is particularly strong in regions investing in agri-tech infrastructure.
Rising Demand for Efficient Crop Nutrition
Farmers are increasingly turning to liquid feed solutions for their rapid absorption and higher nutrient availability compared to traditional solid fertilizers. This results in improved crop yields, reduced nutrient losses, and lower operational costs, supporting global food security initiatives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Liquid Feed Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Liquid Feed Market projected to grow between 2025 and 2032?
Which Liquid Feed Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Liquid Feed Market?
Who are the leading companies in the Liquid Feed Market?
Which region commanded the largest share of the Liquid Feed Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Agriculture
- 1.2.2 Horticulture (greenhouses, nurseries)
- 1.2.3 Turf & Lawn Care
- 1.3 By Crop Type
- 1.3.1 Cereals
- 1.3.2 Oilseeds
- 1.3.3 Fruits & Vegetables
- 1.3.4 Horticultural Plants
- 1.4 By Application
- 1.4.1 Fertigation (irrigation)
- 1.4.2 Foliar Spray
- 1.4.3 Soil Drench
- 1.4.4 Seed Treatment
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 57.14 billion → 2032: USD 84.94 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Liquid Feed Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Liquid Feed Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Liquid Feed Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Liquid Feed Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Liquid Feed Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Liquid Feed Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Liquid Feed Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Liquid Feed Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 57.14 billion → 2032: USD 84.94 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Liquid Feed Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Agriculture
- 12.3.7.2 Horticulture (greenhouses, nurseries)
- 12.3.7.3 Turf & Lawn Care
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Crop Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cereals
- 12.4.7.2 Oilseeds
- 12.4.7.3 Fruits & Vegetables
- 12.4.7.4 Horticultural Plants
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fertigation (irrigation)
- 12.5.7.2 Foliar Spray
- 12.5.7.3 Soil Drench
- 12.5.7.4 Seed Treatment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Liquid Feed End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Liquid Feed Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Liquid Feed Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Liquid Feed Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 EuroChem Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Nutri-Tech Solutions Pty Ltd
- 18.4 ICL
- 18.5 FoxFarm Soil & Fertilizer Co
- 18.6 Nutrien Ltd.
- 18.7 CSBP
- 18.8 Compo Expert
- 18.9 IFFCO
- 18.10 BMS Micro-Nutrients NV
- 18.11 K+S Aktiengesellschaft
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

