
Users trade up to long-acting contraceptive methods
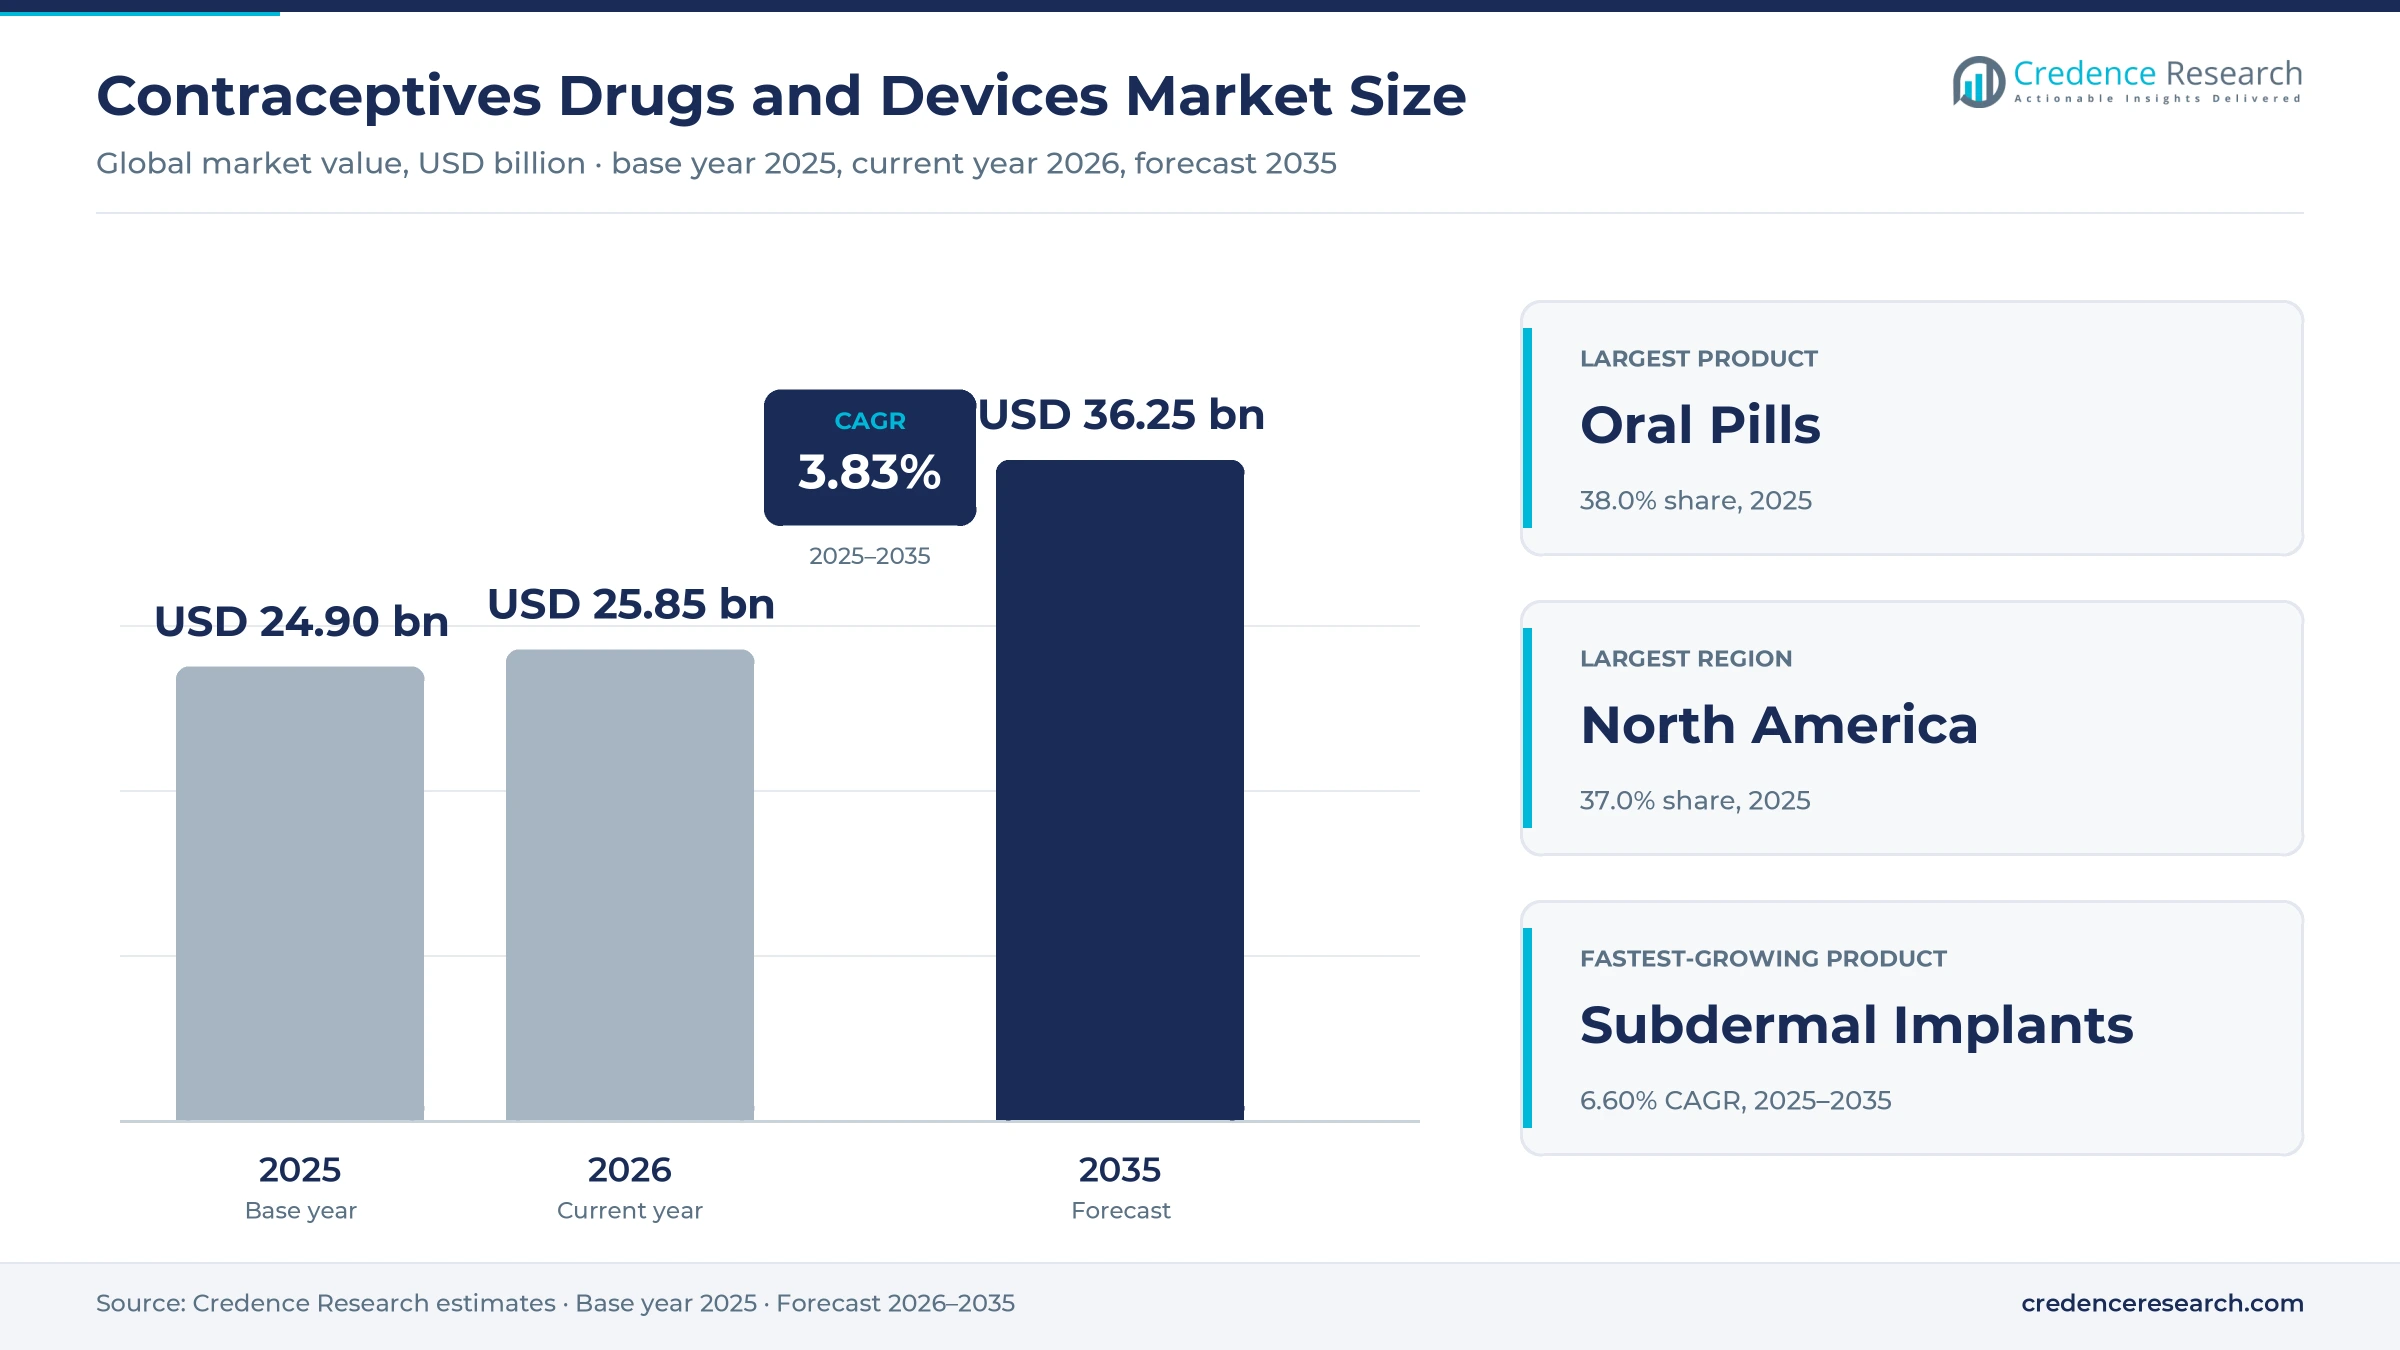
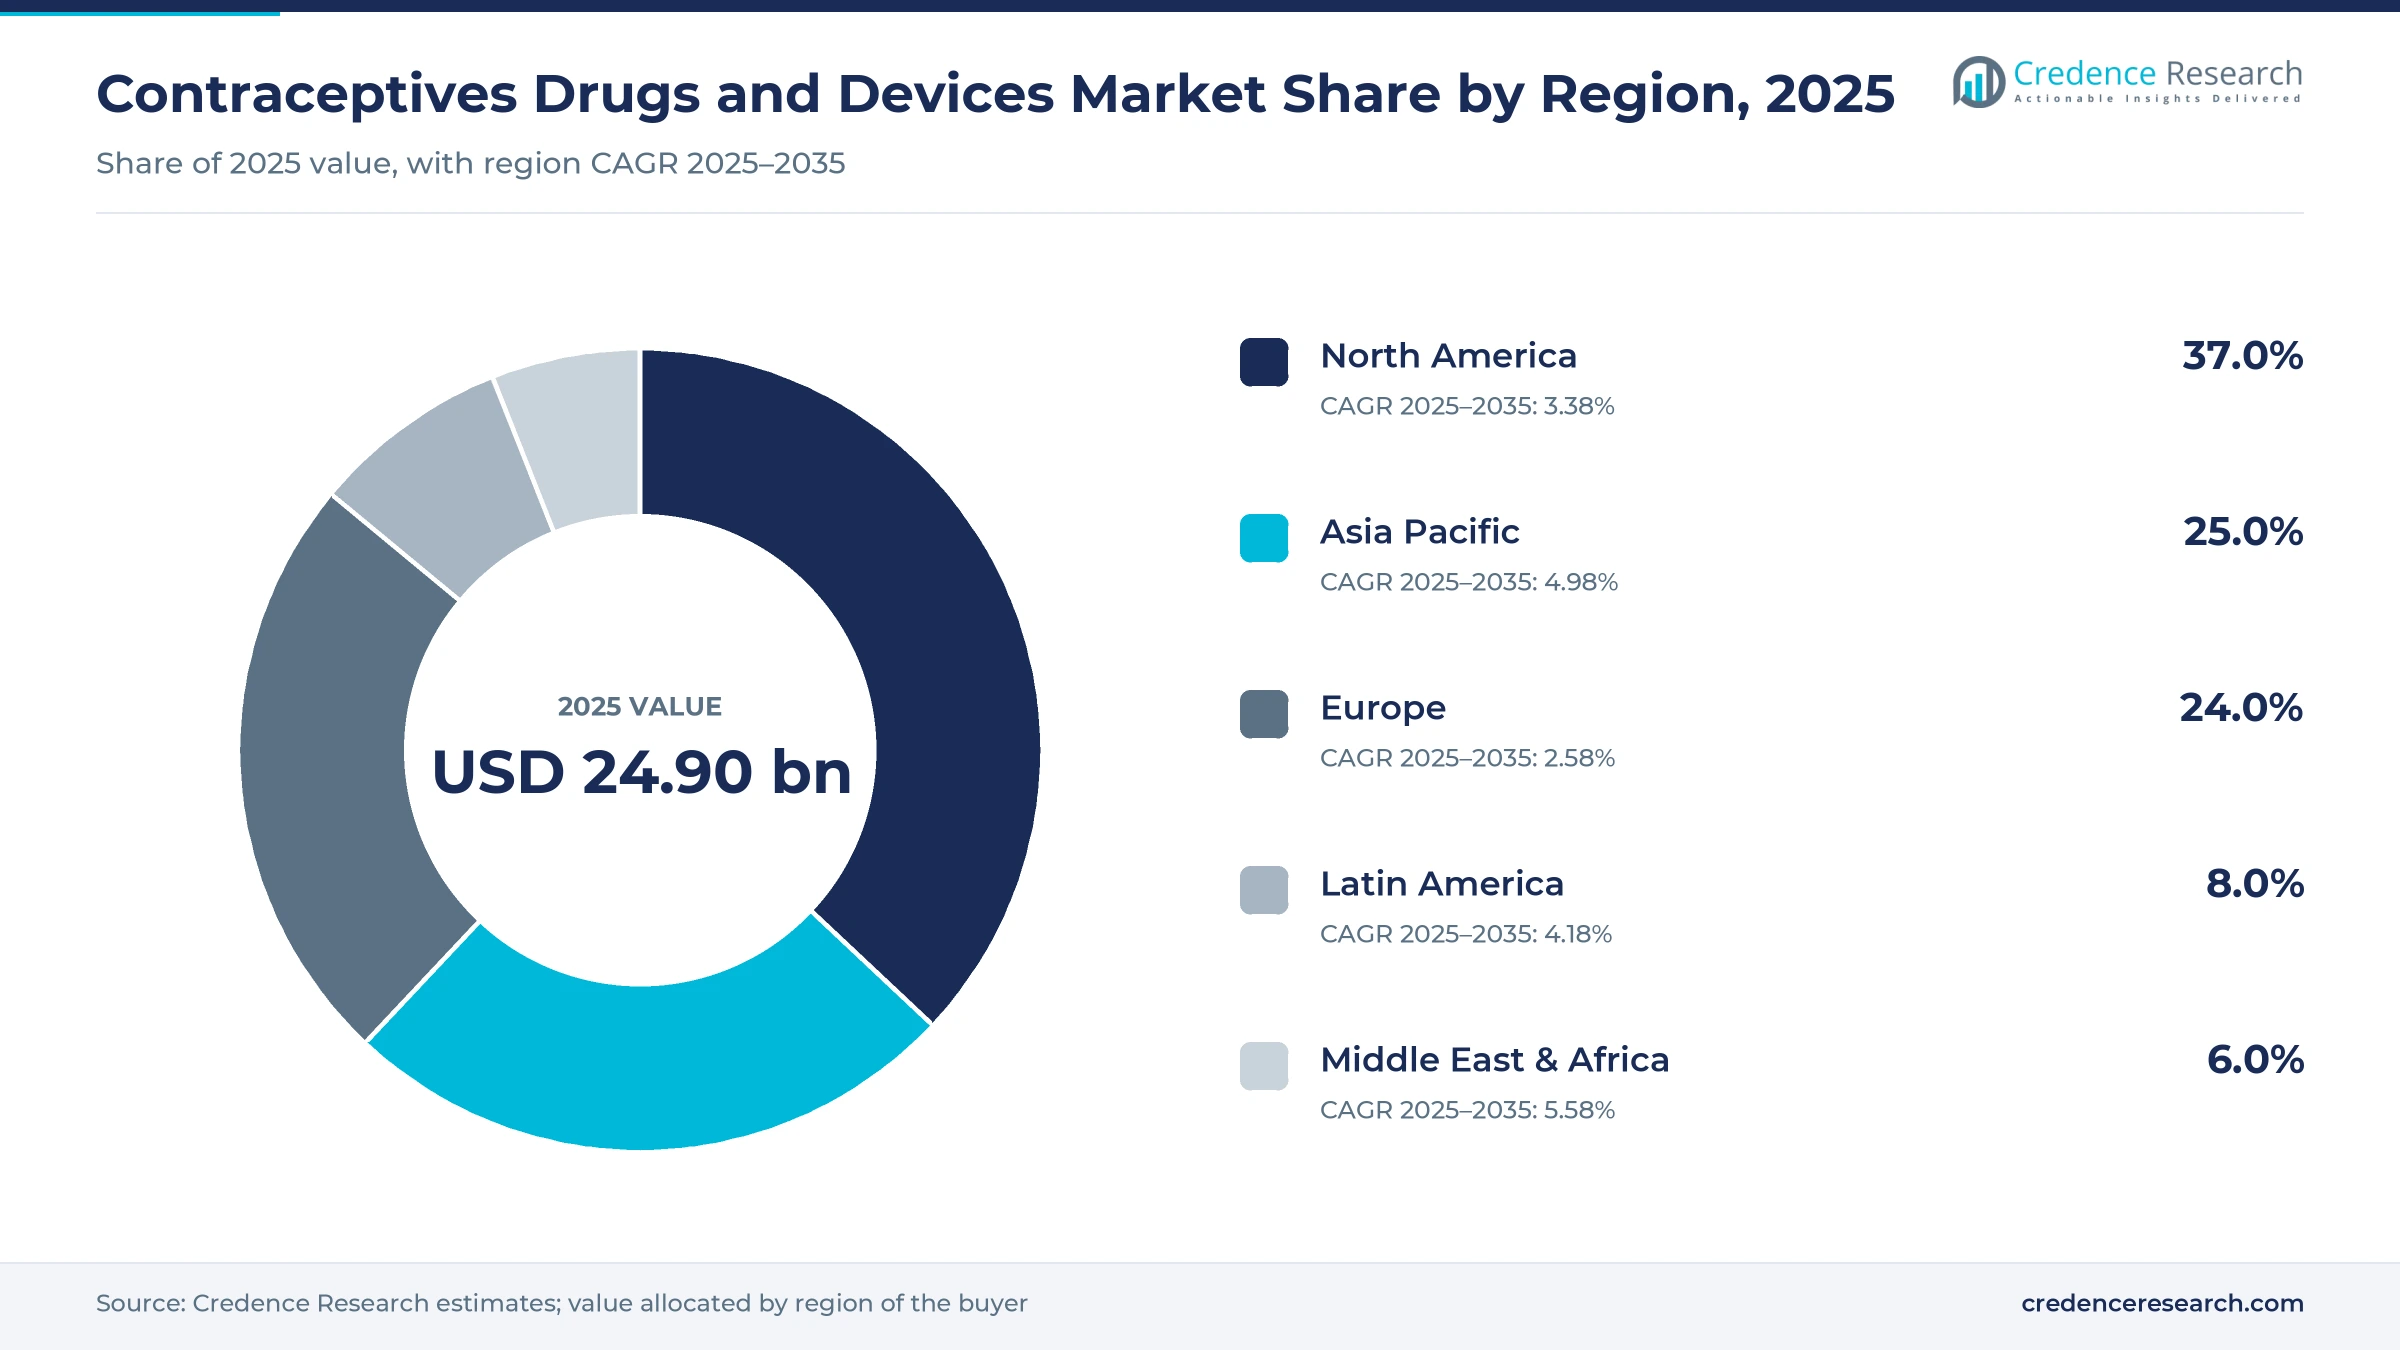
The contraceptives drugs and devices market was valued at USD 24.90 billion in 2025 and is projected to increase from USD 25.85 billion in 2026 to USD 36.25 billion by 2035, registering a CAGR of 3.83% during 2025–2035. User numbers grow slowly, roughly with the population of women aged 15 to 49, so value growth comes mainly from women switching from generic daily pills to hormonal IUDs and implants that cost more upfront and last for years. The WHO counts 164 million women with an unmet need for contraception, most of them in low-income countries where ministries and donors do the buying. North America held the largest regional share, 37.0% in 2025, because the United States pays the highest prices for branded pills, rings and hormonal IUDs. The main regulatory change is the U.S. approval in January 2026 that extended the Nexplanon implant from three to up to five years of use.
Why does the contraceptive method mix matter more than user numbers?
A woman who moves from a generic pill to a hormonal IUD or an implant raises manufacturer revenue at once, because the device price covers 3 to eight years of protection. Price erosion, however, pulls the other way, because most pill molecules are off patent and public tenders push implant and injectable prices down. In high-income countries patients, insurers and pharmacies pay list prices, while in low-income countries ministries, the UNFPA and donors buy by tender at the lowest prices in the market.
The scope covers 6 product groups, namely oral contraceptive pills, male and female condoms, hormonal and copper intrauterine devices, etonogestrel and levonorgestrel implants, injectables and other methods such as vaginal rings, patches, emergency pills and spermicides. It excludes sterilization and vasectomy procedures, cycle-tracking apps and retail margins above the manufacturer price.
Contraceptives Drugs and Devices Market Insights
- The contraceptives drugs and devices market is projected to rise from USD 25.85 billion in 2026 to USD 36.25 billion by 2035, a 3.83% CAGR, as users move toward long-acting methods.
- North America held 37.0% of 2025 value, the largest regional share, because U.S. buyers pay the highest prices for branded pills, rings and hormonal IUDs.
- Oral contraceptive pills accounted for 38.0% of 2025 value, the largest product group, because users buy a pack every month despite heavy generic competition.
- Self-care is changing distribution, as over-the-counter pills, pharmacist prescribing and subscriptions make online and telehealth the fastest-growing channel at 7.19% a year through 2035.
- In July 2026, Bayer signed an agreement bringing Apollo-managed funds into its long-acting contraceptives business as minority investors, a sign of investor appetite for IUD franchises.
Daily pills hold value while implants and telehealth grow
Oral pills lead the product mix while subdermal implants grow fastest
Based on product, the market is categorized into oral contraceptive pills, condoms, intrauterine devices, subdermal implants, injectables and other methods. Oral pills led with 38.0% of 2025 value, because they are the most used reversible method in high-income countries and Latin America and users buy a pack every month. Subdermal implants grow fastest at 6.60% a year, helped by the five-year Nexplanon label and public-sector demand for low-cost levonorgestrel rods in Africa.
Retail pharmacies lead end users while online and telehealth grow fastest
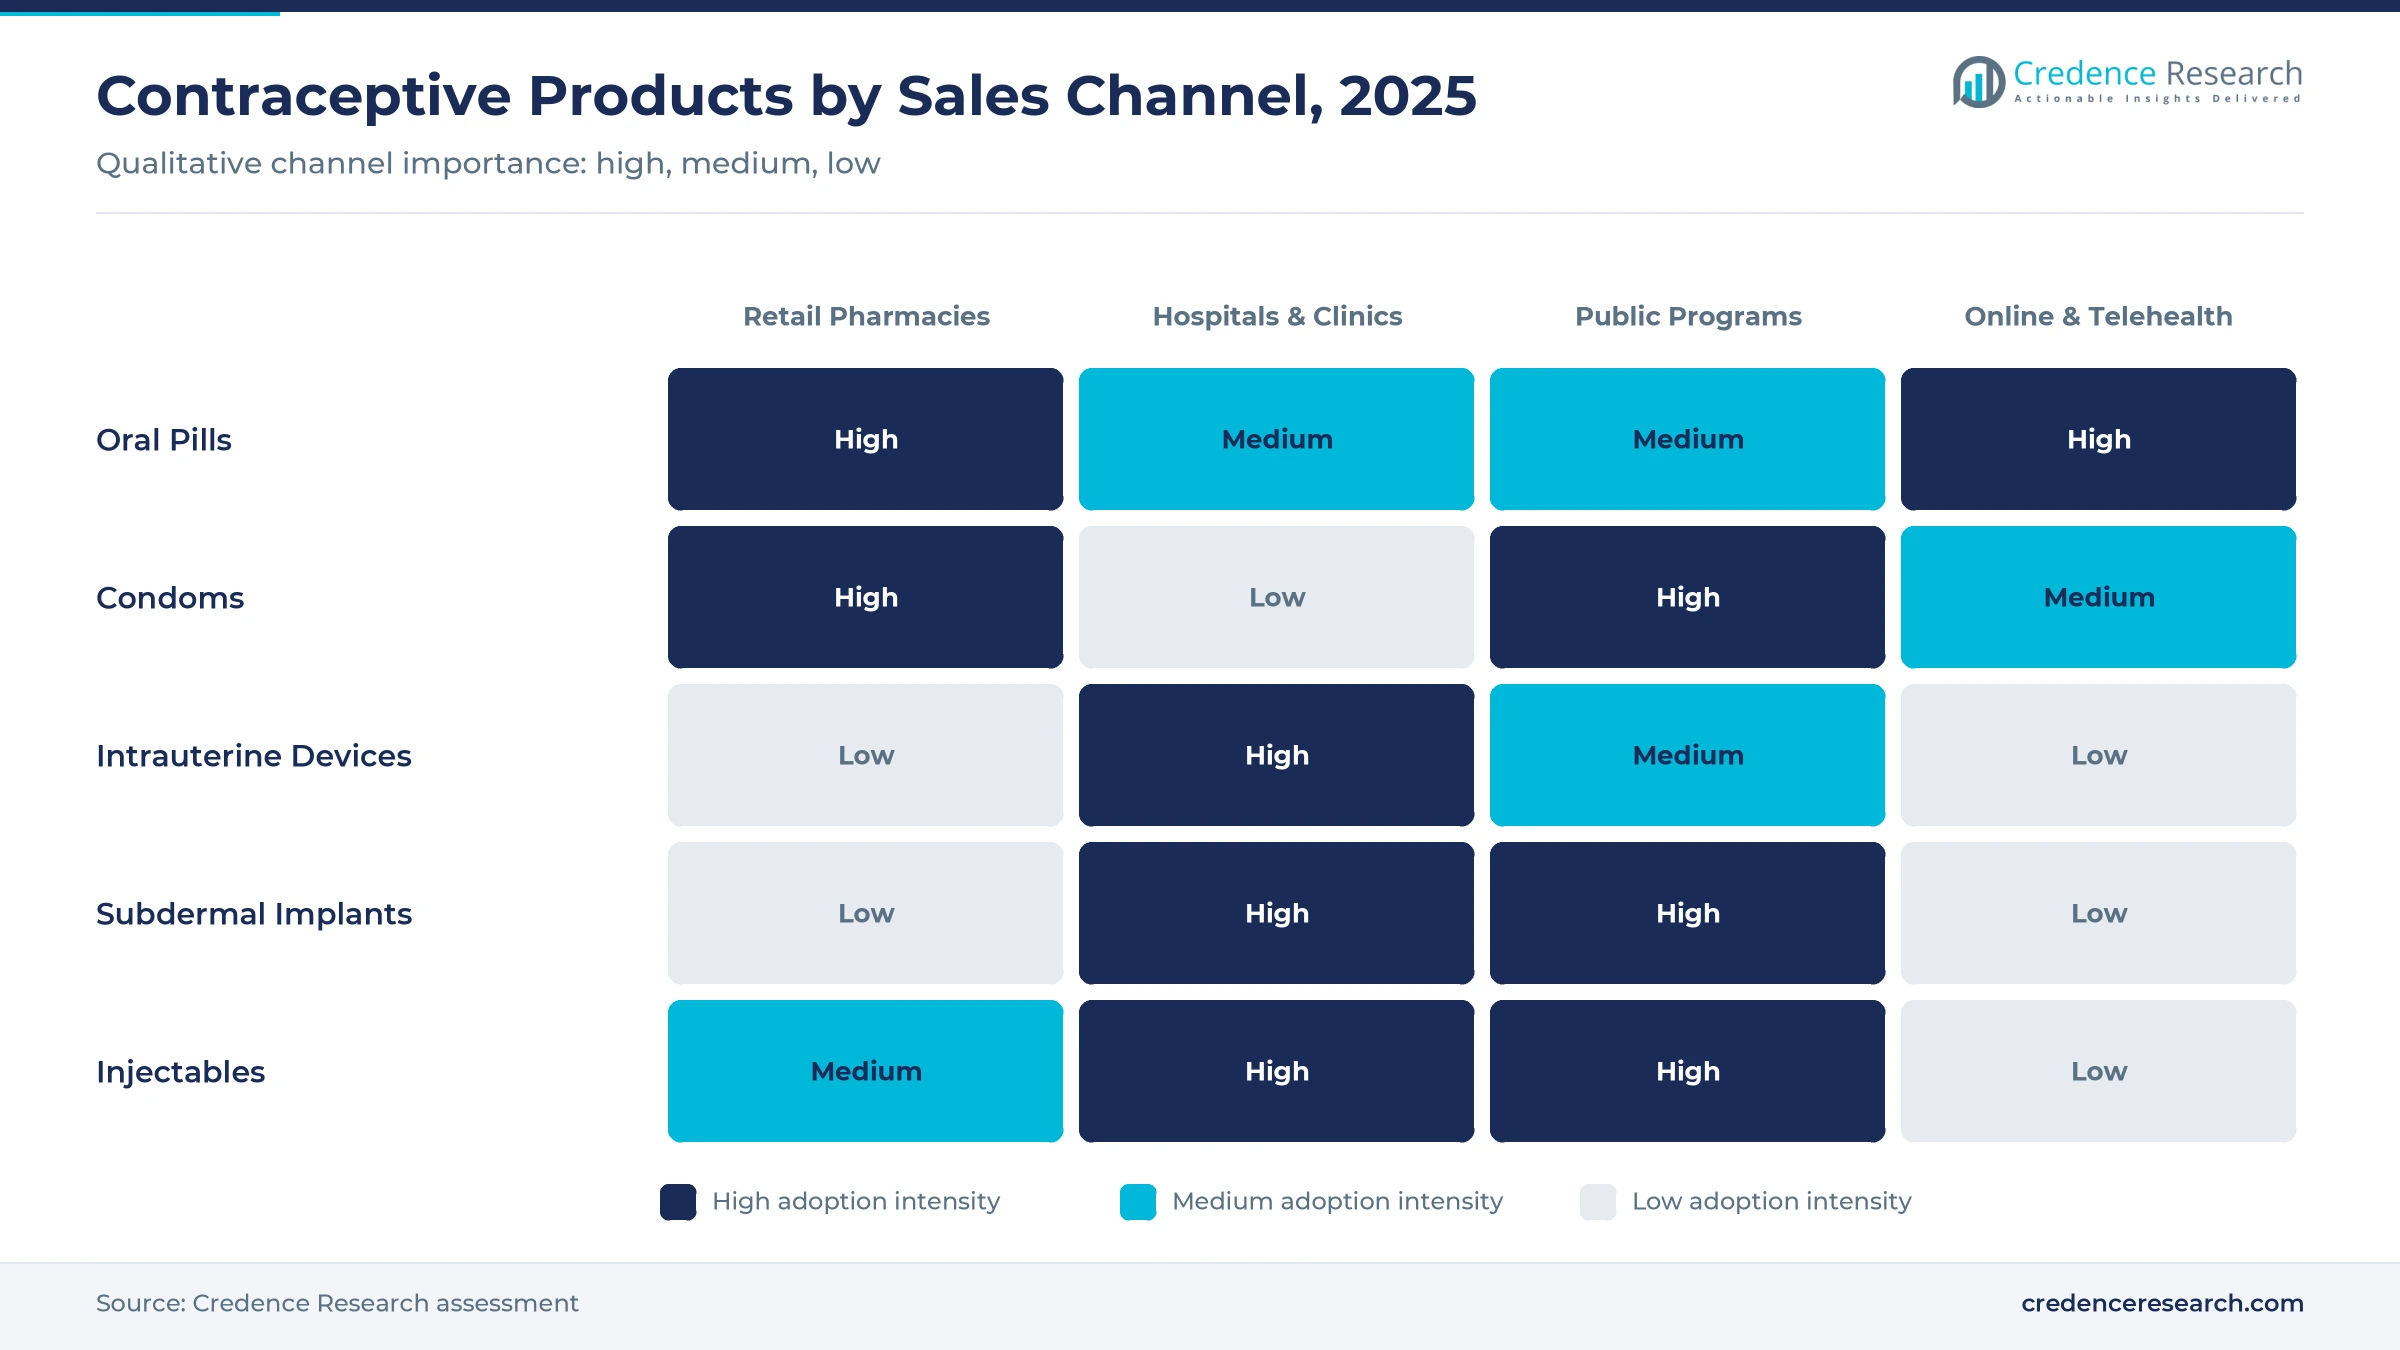
Based on end user, the market is categorized into retail pharmacies, hospitals and clinics, mass retail and convenience, public-sector and NGO programs, and online and telehealth. Retail pharmacies led with 35.5% of 2025 value, as they dispense most pills, rings, patches and emergency pills. Online and telehealth grows fastest at 7.19% a year, because telehealth prescribing and subscriptions remove the monthly pharmacy trip, which favors brands that sell direct and track refills.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Product | Oral Contraceptive Pills | 38.0% | Subdermal Implants | 6.60% |
| By End User | Retail Pharmacies | 35.5% | Online & Telehealth | 7.19% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Implant labels, unmet need and pharmacy access lift spending
Five-year implant labels raise the value of each long-acting insertion
In January 2026, the FDA approved a label extending Nexplanon from 3 to up to five years of use, according to Organon, and the extension trial reported no pregnancies in years 4 and 5. Mirena already carries an 8-year label, and in May 2026 Organon announced U.K. approval of the 5-year Nexplanon label. Longer labels raise lifetime value per insertion and strengthen clinical guidance that presents long-acting methods as first-line options, so implants grow fastest at 6.60% a year.
164 million women with unmet need keep public demand growing
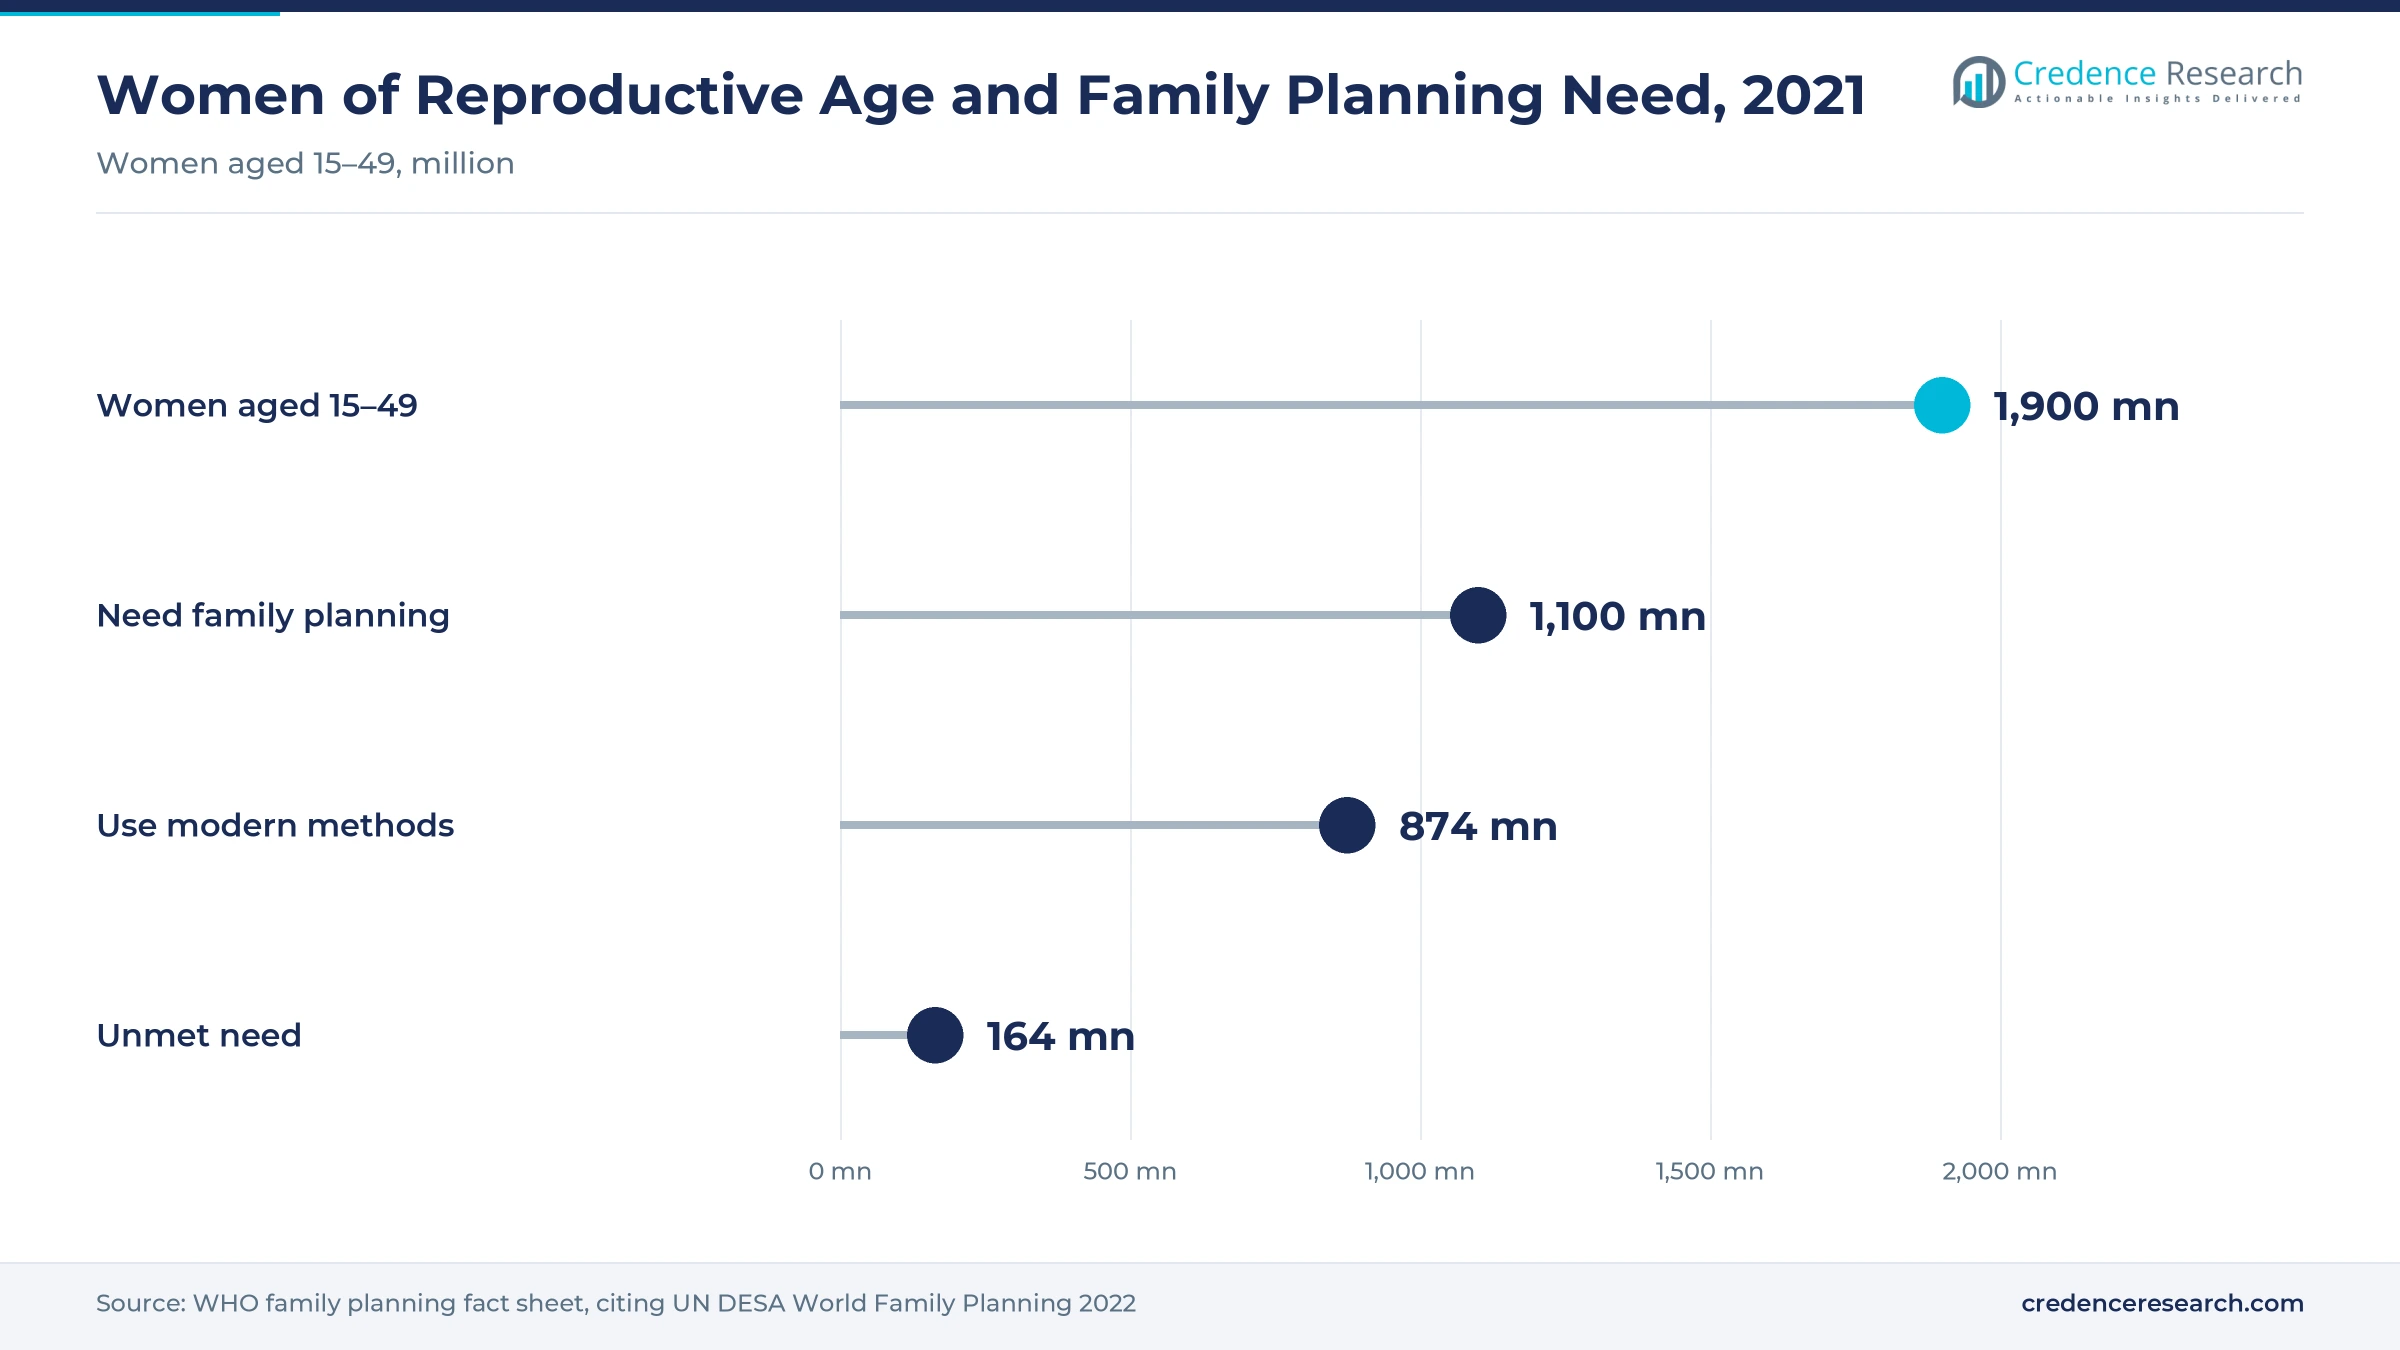
Of 1.9 billion women aged 15 to 49 in 2021, 1.1 billion needed family planning, 874 million used modern methods and 164 million had an unmet need, according to the World Health Organization. Most of that gap sits in sub-Saharan Africa, South Asia and parts of the Middle East, where each point of modern contraceptive prevalence adds buyers of injectables, implants and pills through public channels. The Middle East & Africa grows fastest at 5.58% a year.
Over-the-counter pills and pharmacist prescribing shorten the path to purchase
Women increasingly obtain contraception without a clinic visit, since Perrigo's Opill sells as a daily progestin-only pill without prescription in the United States and pharmacist prescribing is allowed in many U.S. states. The U.K., for its part, sells a progestogen-only pill from behind the pharmacy counter, and in October 2025, Japan approved a switch to non-prescription sale for the Norlevo emergency pill. These routes favor retail pharmacies and the fast-growing online and telehealth channel.
Condoms remain the only mass-market method that also blocks infection
Condoms are the only widely sold method that also protects against sexually transmitted infections, and syphilis and gonorrhea rates remain high in many countries. Premium thin, textured and non-latex condoms sell at a clear price premium in North America, Europe and East Asia, while large public tenders keep the low end of the market busy. Male demand in the 10-year forecast rests on condoms, because no male drug is expected to reach the market before the early 2030s.
Private equity and hormone-free devices reshape the mix
Private capital increasingly buys into hormonal IUD franchises
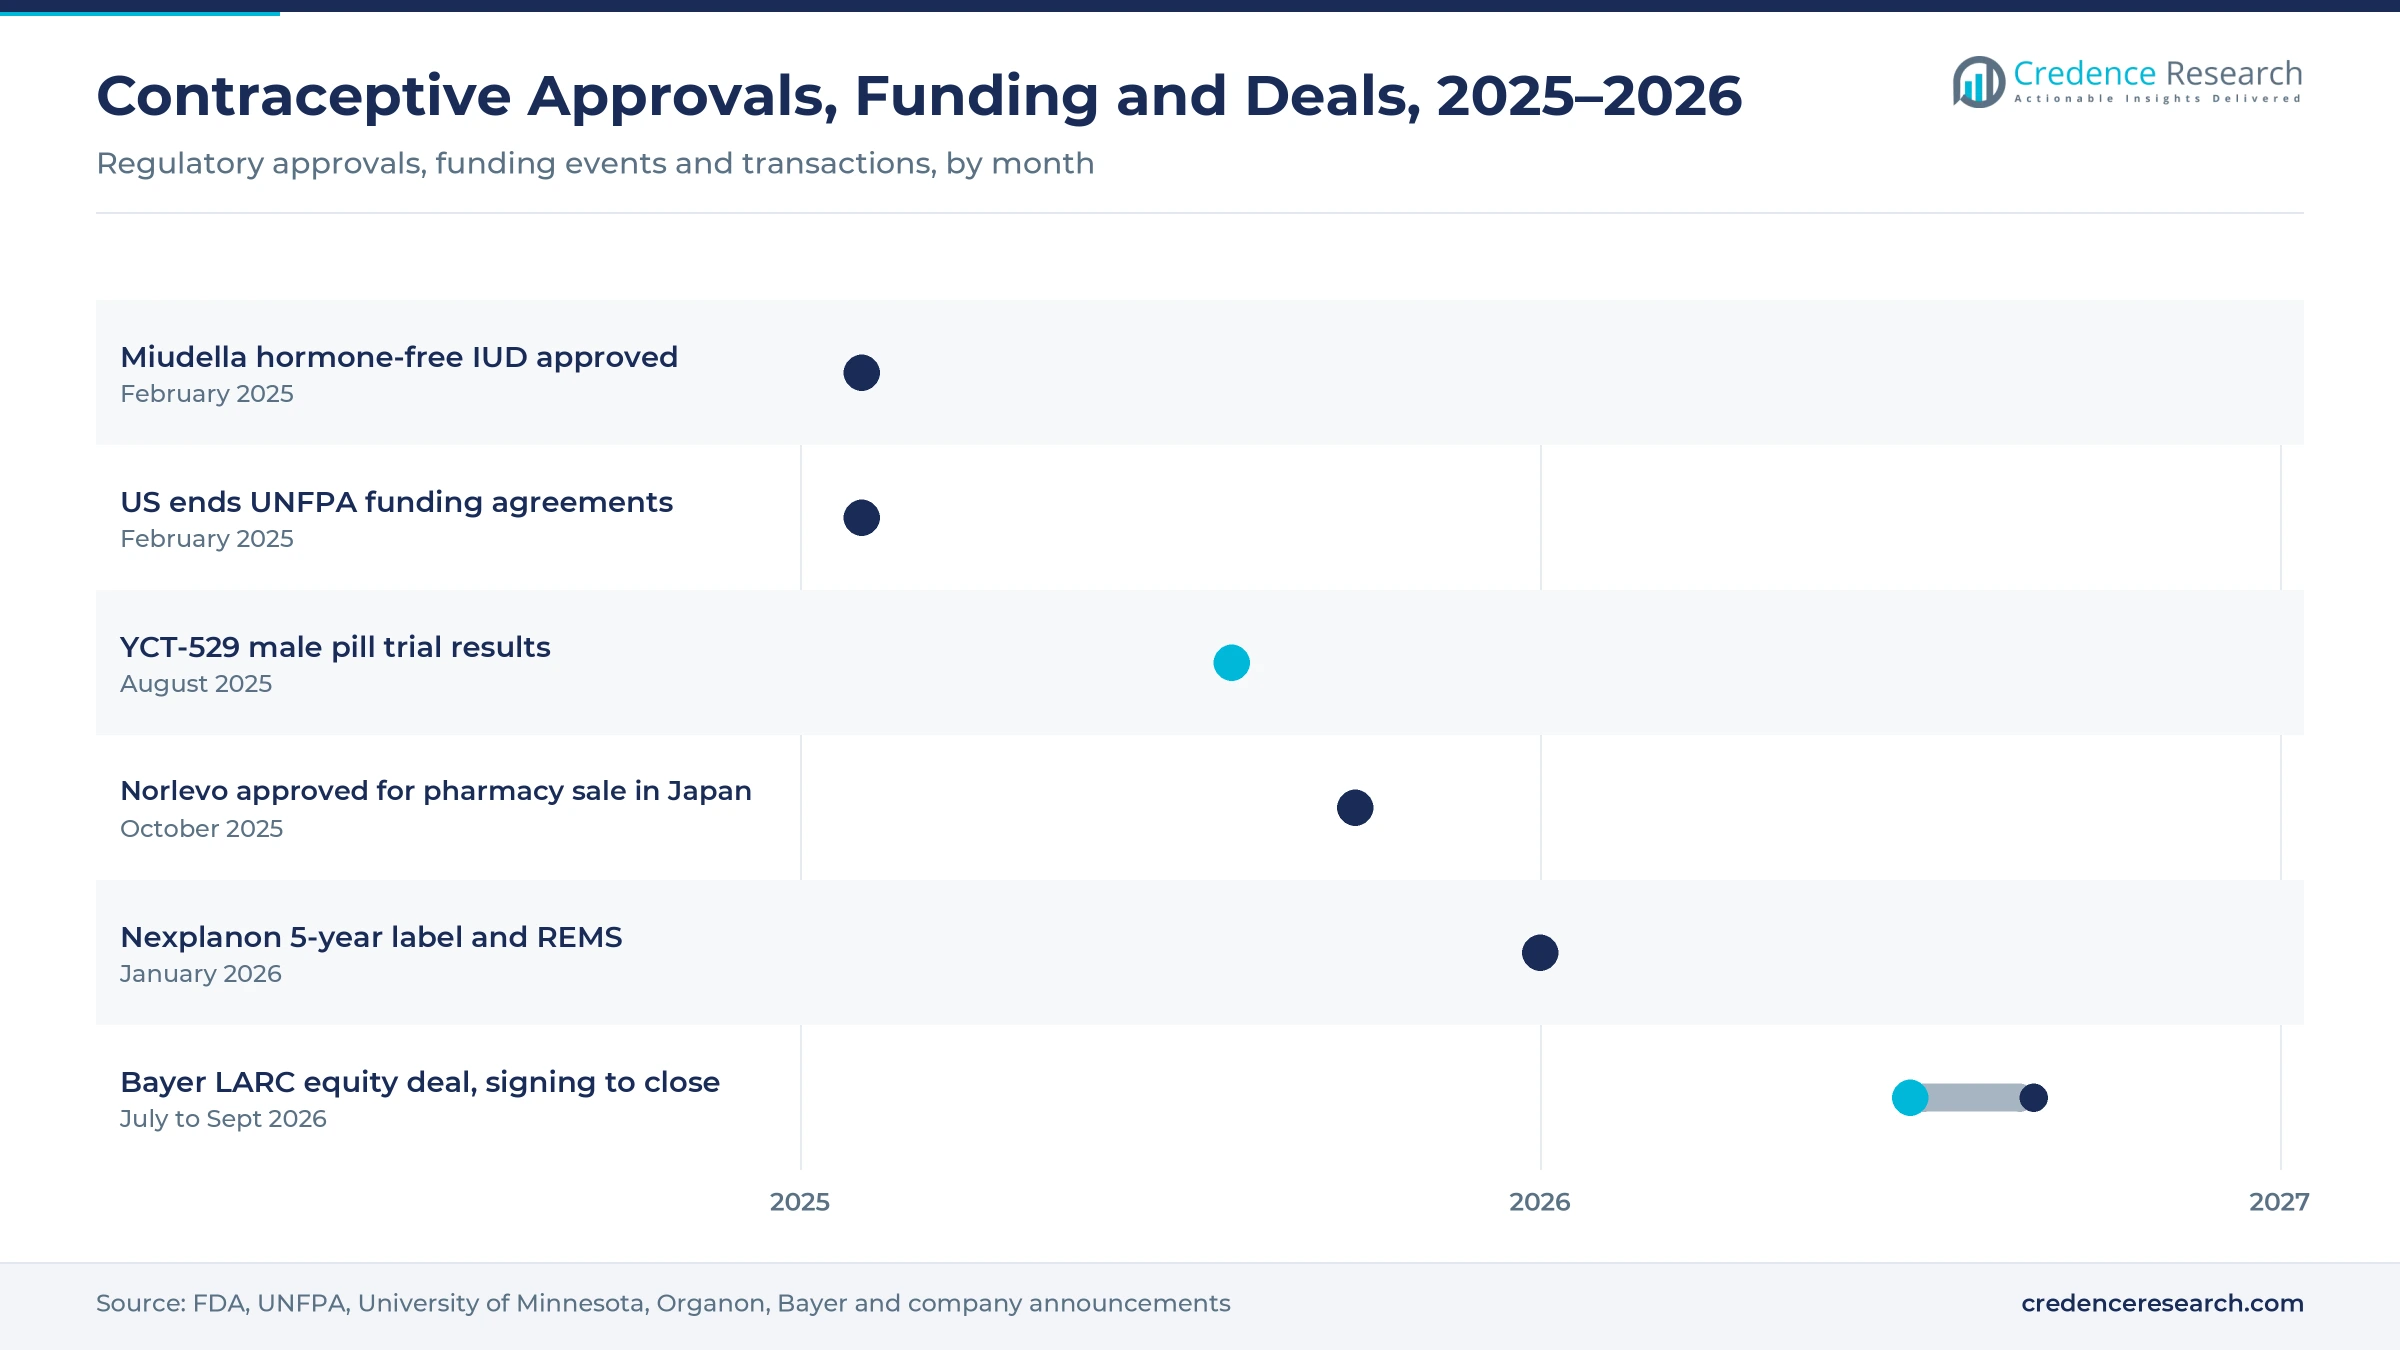
On July 10, 2026, Bayer signed an agreement under which Apollo-managed funds take a minority, non-controlling stake in a new entity holding its long-acting reversible contraceptives business, according to Bayer. Bayer keeps a majority stake and full operational control, and the deal was expected to close in the third quarter of 2026; Apollo reported the closing in September 2026 with KKR participating. Outside investors treat hormonal IUDs such as Mirena and Kyleena as durable, cash-generating assets.
Hormone-free devices return to the market
In February 2025, the FDA approved Sebela's Miudella, a low-dose copper intrauterine system for up to three years and the first new hormone-free IUD in the United States in more than 40 years. A share of women in Europe and North America have moved away from hormones toward copper IUDs, condoms or fertility-awareness methods. Hormone-free copper devices and gels answer that demand in both regions.
Self-injection and domestically funded public programs open an opportunity
Subcutaneous DMPA in a prefilled device, such as Pfizer's Sayana Press, lets women inject themselves every three months at home, which cuts clinic visits in Africa and Asia. In December 2025, CHAI and the Reproductive Health Supplies Coalition released their 11th Family Planning Market Report, calling the dismantling of USAID a major inflection point while noting rising domestic financing. Low-cost generic implants and injectables gain most from that shift toward domestic budgets.
Male methods and direct-to-consumer channels offer a growth opportunity
In August 2025, the University of Minnesota reported that YCT-529, a hormone-free male pill, was well tolerated in its first human trial, and a second study found doses of up to 180 milligrams well tolerated for at least 28 days, according to the University of Minnesota College of Pharmacy. A launch before the early 2030s is unlikely, but telehealth subscriptions already give brands direct data on adherence and switching.
Donor cuts, generic pricing and hormone fears restrain value
Donor funding cuts leave gaps in public supply
In February 2025, the UNFPA said the U.S. government had terminated all its funding agreements with the agency, covering 48 grants mainly in crisis settings, and the U.S. had long been one of the largest funders of contraceptive commodities through USAID. Public-sector and NGO programs are the slowest-growing end-user channel as a result. Ministries in Africa and Asia are taking on more of the bill, which favors pooled procurement and the lowest-cost generic implants and injectables.
Generic competition keeps pill prices falling
Nearly all major pill molecules are generic, and in the United States, insurers must cover contraception without cost sharing, which pushes plans toward the cheapest generic version of each formulation, so pills hold 38.0% of 2025 value but grow more slowly than the market. Viatris and other generic houses supply most of that volume. Branded makers respond with newer estrogens such as estetrol, sold as Nextstellis by Mayne Pharma, which compete on tolerability rather than price.
Safety concerns push some users away from hormones
Venous thromboembolism risk with some combined pills, mood side effects and studies linking hormonal contraception to a small rise in breast cancer risk all shape prescribing. Some women in Europe and North America have stopped using hormones, which slows pill, ring and patch sales in the 2 highest-income regions. Suppliers mitigate the risk with progestin-only and low-dose options, hormone-free copper devices and clearer counseling materials that help clinicians match each woman to a method.
Insertion training and shifting access rules slow long-acting uptake
Implants and IUDs need trained providers, and the Nexplanon approval added a REMS program that certifies providers for insertion and removal, building on a clinical training program in place since 2006. As a result, uptake of implants and IUDs slows where clinicians are scarce. Access rules also change with governments, from limits on adolescent access to cuts in public funding. Suppliers respond with training partnerships, task sharing with nurses and midwives, and self-administered injectables that need no insertion.
U.S. prices lead while sub-Saharan Africa adds users fastest
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| North America | 37.0% | 3.38% |
| Asia Pacific | 25.0% | 4.98% |
| Europe | 24.0% | 2.58% |
| Latin America | 8.0% | 4.18% |
| Middle East & Africa | 6.0% | 5.58% |
North America combines the highest prices with no-cost-sharing coverage
North America held 37.0% of 2025 value and grows at 3.38% a year. The United States has the highest prices for branded pills, rings and hormonal IUDs, and insurance rules that remove cost sharing keep long-acting method use high. The 5-year Nexplanon label and its REMS program took effect in 2026, and the over-the-counter Opill pill and telehealth subscriptions add growth at the margin. Generic substitution in pills is the main drag on regional value.
Asia Pacific splits into IUDs in China, condoms in Japan and injectables in South Asia
Asia Pacific held 25.0% of 2025 value and grows at 4.98% a year. China is the largest user of IUDs, Japan and South Korea are large condom markets served by makers such as Okamoto Industries, and Indonesia, India, Bangladesh and the Philippines drive injectable and implant demand. Karex in Malaysia, meanwhile, supplies private labels and public tenders. Japan's October 2025 approval of over-the-counter Norlevo opens pharmacy access to emergency contraception in a large, under-served market.
Europe sees falling pill use and reimbursement limits hold growth down
Europe held 24.0% of 2025 value and grows at 2.58% a year, the slowest regional rate. Pill use is falling in several countries as women move to IUDs or hormone-free methods, and national reimbursement holds prices down. The U.K. sells a progestogen-only pill from behind the pharmacy counter and approved the 5-year Nexplanon label in May 2026. Bayer, based in Germany and Reckitt, owner of Durex, anchor the regional supply base for hormonal devices and condoms.
Latin America and the Middle East & Africa add the most new users through public programs
Latin America held 8.0% of 2025 value and grows at 4.18% a year, as Brazil and Mexico are large pill and injectable markets and public programs expand implant access for adolescents. The Middle East & Africa held 6.0% of 2025 value and is the fastest-growing region at 5.58% a year. Sub-Saharan Africa has the widest gap between demand and modern method use, and injectables and implants lead uptake there.
Implant labels and a LARC equity deal mark 2025–2026
| Development | Status and market relevance |
|---|---|
| In September 2026, Apollo reported closing the investment of its managed funds in the entity holding Bayer's long-acting contraceptives business, with KKR participating. | Closed. Confirms investor appetite for hormonal IUD franchises. |
| In July 2026, Bayer signed an agreement to bring Apollo-managed funds into a new entity holding its long-acting reversible contraceptives business as minority investors. | Signed. Bayer keeps majority ownership and full operational control. |
| In January 2026, the FDA approved Organon's application extending Nexplanon to up to five years of use, with a new REMS program for insertion and removal. | Approved. Raises lifetime value per implant and tightens training rules. |
| In October 2025, Japan approved Aska Pharmaceutical's Norlevo emergency contraceptive for non-prescription sale, distributed by Daiichi Sankyo Healthcare. | Approved. Opens pharmacy access in a large, under-served market. |
| In February 2025, the FDA approved Sebela's Miudella, a hormone-free low-dose copper intrauterine system for up to three years. | Approved. First new hormone-free IUD in the U.S. in more than 40 years. |
Longer labels and hormone-free designs define innovation
- Longer labels now let Nexplanon carry up to five years and Mirena up to eight years, raising the value of each insertion and lowering cost per year of protection.
- Hormone-free designs such as low-dose copper systems like Miudella and non-hormonal gels serve women who avoid hormones, while YCT-529 tests a hormone-free route for men.
- Self-administration with prefilled subcutaneous DMPA lets women inject at home every three months, which cuts clinic visits in public programs.
- Digital access through telehealth prescribing, pharmacy apps and subscriptions delivers pills, rings and patches by mail and gives brands adherence data.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Pharma franchises, condom brands and generics divide supply
Three groups supply the market, starting with research-based drug makers that own the leading long-acting and branded franchises. Bayer sells the Mirena and Kyleena hormonal IUDs, the Jadelle implant and the Yaz and Yasmin pill families. Organon sells Nexplanon and NuvaRing, CooperSurgical sells the Paragard copper IUD and Pfizer makes Depo-Provera and Sayana Press. Consumer health companies own the large condom brands, led by Reckitt's Durex and Church & Dwight's Trojan, with Okamoto Industries strong in Japan and Karex a major contract maker. Generic and specialty makers, including Viatris, Perrigo, Mayne Pharma and Sebela Pharmaceuticals, supply most pill volume and newer niche products. Credence Research estimates that the 10 largest suppliers hold under half of global value. Hormonal IUDs and implants are concentrated, while pills and condoms are fragmented, and REMS training rules raise entry barriers in implants.
Companies profiled and their roles
| Company | Type | Role in the market |
|---|---|---|
| Bayer | Research-based pharma | Mirena, Kyleena and Jaydess IUDs, Jadelle implant, Yaz and Yasmin pills |
| Organon | Research-based pharma | Nexplanon implant, NuvaRing and pill brands |
| CooperSurgical | Women’s health device maker | Paragard copper IUD in the United States |
| Pfizer | Research-based pharma | Depo-Provera and subcutaneous Sayana Press injectables |
| Reckitt | Consumer health | Durex, the largest global condom brand |
| Church & Dwight | Consumer health | Trojan, the leading U.S. condom brand |
| Okamoto Industries | Condom maker | Leading condom maker in Japan |
| Karex | Contract condom maker | Private-label and public-tender condoms from Malaysia |
| Viatris | Generic maker | Generic oral contraceptives in the U.S. and Europe |
| Perrigo | Consumer health | Opill over-the-counter progestin-only pill |
| Mayne Pharma | Specialty pharma | Nextstellis estetrol-based pill in the U.S. |
| Sebela Pharmaceuticals | Specialty pharma | Miudella low-dose copper intrauterine system |
Method mix, not user growth, sets the pace for value
Credence Research's view is that the contraceptives drugs and devices market is large and mature, but its value is moving from cheap daily pills toward methods that last for years. That switch, more than new users, sets the growth rate. The largest new revenue lies in implants, hormonal and copper IUDs, self-injectables and telehealth. The main strategic risk is public funding, since donor cuts can stall supply in the regions with the most unmet need. Investors should watch label extensions, REMS rules and domestic procurement budgets.
Values built method by method from use and price data
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built method by method from United Nations contraceptive-use data and an annual manufacturer spend per user, separating list prices from tender prices; segment and regional splits are Credence Research estimates. Supporting evidence comes from WHO and UNFPA data, public procurement market reports, regulatory approvals and company disclosures.
Long-acting methods and domestic budgets shape the outlook
Through 2035, contraceptive value will keep shifting from generic pills toward implants, IUDs and self-injectables, while pills remain the largest single product group. Telehealth and pharmacy access will take a larger part of distribution in high-income countries. Asia Pacific and the Middle East & Africa will add most new users, funded increasingly by domestic budgets rather than donors. A male product, by contrast, is unlikely before the early 2030s. The pace will depend on public funding, label extensions and how quickly hormone-free options win prescribers.
Frequently Asked Questions
What was the size of the contraceptives drugs and devices market in 2025?
What is the forecast value and CAGR of the contraceptives drugs and devices market?
What drives demand for contraceptives drugs and devices?
Which region holds the largest share of the contraceptives drugs and devices market?
Which product leads the contraceptives drugs and devices market?
Who are the major companies in the contraceptives drugs and devices market?
How did the 2025 U.S. aid cuts affect contraceptive supply?
Is a male contraceptive pill coming to market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Oral Contraceptive Pills
- 1.2.2 Condoms
- 1.2.3 Intrauterine Devices
- 1.2.4 Other Methods
- 1.2.5 Subdermal Implants
- 1.2.6 Injectables
- 1.3 By End User
- 1.3.1 Retail Pharmacies
- 1.3.2 Hospitals & Clinics
- 1.3.3 Mass Retail & Convenience
- 1.3.4 Public-Sector & NGO Programmes
- 1.3.5 Online & Telehealth
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 24.90 billion → 2035: USD 36.25 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Contraceptives Drugs and Devices Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Contraceptives Drugs and Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Contraceptives Drugs and Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Contraceptives Drugs and Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Contraceptives Drugs and Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Contraceptives Drugs and Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Contraceptives Drugs and Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Contraceptives Drugs and Devices Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 24.90 billion → 2035: USD 36.25 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Contraceptives Drugs and Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Oral Contraceptive Pills
- 12.3.7.2 Condoms
- 12.3.7.3 Intrauterine Devices
- 12.3.7.4 Other Methods
- 12.3.7.5 Subdermal Implants
- 12.3.7.6 Injectables
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Retail Pharmacies
- 12.4.7.2 Hospitals & Clinics
- 12.4.7.3 Mass Retail & Convenience
- 12.4.7.4 Public-Sector & NGO Programmes
- 12.4.7.5 Online & Telehealth
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Contraceptives Drugs and Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Contraceptives Drugs and Devices Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Contraceptives Drugs and Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Contraceptives Drugs and Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bayer
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Organon
- 18.4 Reckitt
- 18.5 Church & Dwight
- 18.6 CooperSurgical
- 18.7 Pfizer
- 18.8 Viatris
- 18.9 Perrigo
- 18.10 Karex
- 18.11 Okamoto Industries
- 18.12 Mayne Pharma
- 18.13 Sebela Pharmaceuticals
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

