
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Contractual Cleaning Services Market Size 2024 | USD 181,625 Million |
| Contractual Cleaning Services Market, CAGR | 4.8% |
| Contractual Cleaning Services Market Size 2032 | USD 264,280.96 Million |
Market Overview
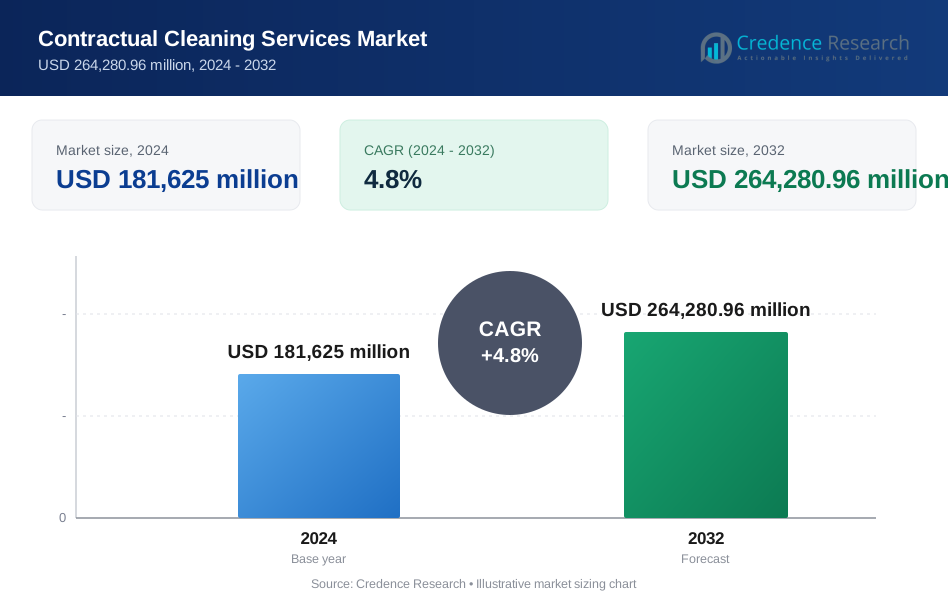
The Contractual Cleaning Services Market is projected to grow from USD 181,625 million in 2024 to USD 264,280.96 million by 2032, registering a compound annual growth rate (CAGR) of 4.8% during the forecast period.
The Contractual Cleaning Services Market is driven by the increasing demand for professional cleaning services across various sectors, including commercial, residential, and industrial. Rapid urbanization, coupled with the rise in hygiene awareness post-pandemic, has significantly boosted the adoption of these services. The integration of eco-friendly cleaning solutions and advanced technologies such as robotic cleaners and IoT-enabled monitoring systems are key trends transforming the industry. Businesses are increasingly outsourcing cleaning tasks to ensure compliance with stringent hygiene and safety regulations, while reducing operational costs. The growing presence of specialized service providers offering customized cleaning solutions for healthcare, hospitality, and educational institutions is also propelling market growth. Additionally, the expansion of e-commerce platforms has enhanced the accessibility of contractual cleaning services, allowing for streamlined bookings and competitive pricing. These factors collectively underscore the market's steady growth trajectory.
The Contractual Cleaning Services Market exhibits strong regional dynamics, with North America and Asia-Pacific emerging as pivotal markets. North America, led by the United States, dominates the market due to high adoption rates in commercial and industrial sectors, stringent hygiene regulations, and technological advancements such as robotic cleaning systems. Asia-Pacific, the fastest-growing region, is driven by rapid urbanization, industrial expansion, and rising consumer awareness about hygiene in countries like China and India. Key players such as Sodexo, ISS AS, Compass Group plc, and Aramark Corporation lead the market with their comprehensive service portfolios and global presence. Additionally, regional players like Mitie Group plc and CleanNet USA Inc. contribute significantly by catering to localized demands. These companies focus on innovation and sustainability, reinforcing their competitive edge in the evolving cleaning services landscape.
Market Drivers
Rising Awareness of Hygiene and Sanitation
The increasing emphasis on maintaining hygiene and sanitation standards is a primary driver for the Contractual Cleaning Services Market. The COVID-19 pandemic underscored the importance of cleanliness in preventing disease transmission, prompting businesses, institutions, and households to adopt professional cleaning services. Enhanced public awareness about the health benefits of a clean environment has further fueled the demand for these services. For instance, a report by the World Health Organization (WHO) highlights the critical role of hygiene in controlling the spread of infectious diseases, which has significantly increased the demand for professional cleaning services. This trend is particularly strong in healthcare and hospitality sectors, where hygiene compliance is critical to operational success.
Outsourcing for Cost Efficiency
Organizations across various industries are increasingly outsourcing their cleaning needs to contractual service providers to optimize operational efficiency and reduce overhead costs. By outsourcing, businesses can focus on core competencies while ensuring that cleaning tasks are handled professionally. For instance, a study by the University of Nairobi found that outsourcing cleaning services significantly improved cost efficiency and service quality for the institution. The flexibility offered by contractual arrangements, such as customizable service plans and scalable solutions, makes them attractive to companies aiming to manage resources more effectively.
Adoption of Sustainable Cleaning Solutions
The shift towards environmentally friendly practices has significantly influenced the cleaning services market. Customers are increasingly seeking service providers that use eco-friendly cleaning agents and sustainable practices to minimize environmental impact. For instance, the U.S. Environmental Protection Agency (EPA) has reported a growing adoption of green cleaning practices among businesses aiming to reduce their environmental footprint. This demand has driven providers to innovate and incorporate green cleaning solutions into their offerings, creating a competitive edge. Regulatory pressures to adopt environmentally conscious methods further bolster this trend, particularly in developed markets.
Technological Advancements and Automation
The integration of advanced technologies such as robotic cleaning devices, IoT-enabled monitoring systems, and AI-based scheduling tools is reshaping the cleaning services landscape. These technologies enhance efficiency, reduce manual labor, and ensure consistency in service quality. Automation has become particularly important in large-scale facilities like airports and shopping malls, where maintaining cleanliness at high standards is challenging. For instance, a report by the International Federation of Robotics (IFR) highlights the increasing use of robotic cleaners in commercial spaces, which has significantly improved cleaning efficiency and consistency. The adoption of these technologies by service providers is driving their growth and market differentiation.
Market Trends
Growing Demand for Specialized Cleaning Services
The Contractual Cleaning Services Market is witnessing a notable shift towards specialized cleaning solutions tailored to specific sectors. Industries such as healthcare, hospitality, and education require stringent hygiene standards, driving the demand for targeted services like medical-grade sanitation, hotel room cleaning, and classroom disinfection. For instance, a report by the World Health Organization (WHO) highlights the critical role of specialized cleaning in maintaining hygiene standards in healthcare settings, which has significantly increased the demand for professional cleaning services. This trend has prompted service providers to diversify their offerings and invest in training specialized staff to cater to unique customer needs effectively.
Emphasis on Eco-Friendly Cleaning Practices
Environmental sustainability has become a central focus in the cleaning industry, with increasing demand for eco-friendly solutions. Service providers are adopting biodegradable cleaning agents, energy-efficient equipment, and water-saving technologies to reduce their environmental footprint. For instance, the U.S. Environmental Protection Agency (EPA) has reported a growing adoption of green cleaning practices among businesses aiming to reduce their environmental footprint. This aligns with customer preferences and regulatory mandates for sustainable practices. The adoption of green cleaning methods not only enhances brand reputation but also attracts environmentally conscious clientele.
Integration of Technology and Automation
Technological advancements are transforming the operational dynamics of the contractual cleaning industry. Robotic cleaners, IoT-enabled devices, and AI-based scheduling systems are being widely adopted to improve efficiency and precision. These technologies allow service providers to offer seamless, high-quality solutions, particularly in large-scale and high-traffic environments like shopping malls and airports. For instance, a report by the International Federation of Robotics (IFR) highlights the increasing use of robotic cleaners in commercial spaces, which has significantly improved cleaning efficiency and consistency. Additionally, digital platforms and mobile apps are streamlining service booking and real-time monitoring, enhancing customer convenience and satisfaction.
Rise of Subscription-Based Models
The growing preference for subscription-based contractual cleaning services reflects a shift towards long-term service agreements. Businesses and households alike find value in consistent, scheduled cleaning services, which ensure sustained cleanliness and hygiene. Subscription models also offer cost benefits and flexibility, making them increasingly popular among clients. Service providers are leveraging this trend to build lasting customer relationships and ensure steady revenue streams. For instance, a report by Analytica Global highlights the rising popularity of subscription-based cleaning services, offering customers the convenience and consistency of regular cleaning and maintenance. This model is gaining traction globally, supported by the increasing adoption of digital service platforms.
Market Challenges Analysis
Intense Competition and Market Fragmentation
The Contractual Cleaning Services Market faces significant challenges due to intense competition and market fragmentation. The presence of numerous small and medium-sized enterprises (SMEs), alongside established players, creates a highly competitive environment. This competition often results in price wars, which can erode profit margins and impact service quality. Additionally, the lack of standardization in service offerings poses a challenge for customers seeking consistent and reliable solutions. Market fragmentation makes it difficult for new entrants and smaller players to establish a foothold, particularly in regions dominated by well-established providers. To remain competitive, businesses must continuously innovate and differentiate their services, which can be resource-intensive. With numerous players entering the market due to low barriers to entry, companies must not only compete on price but also strive to differentiate themselves through quality service. This competition can lead to price wars that further strain profit margins, compelling businesses to make tough decisions regarding staffing and service quality.
Workforce Management and Retention Issues
Managing and retaining a skilled workforce is a persistent challenge for service providers in the cleaning industry. High employee turnover rates, coupled with the physically demanding nature of cleaning jobs, contribute to workforce instability. Recruiting and training staff to deliver specialized services, such as medical-grade cleaning or eco-friendly solutions, requires significant investment. Additionally, fluctuations in demand for cleaning services-such as during off-peak seasons or economic downturns-can lead to staffing inefficiencies and operational disruptions. Service providers must balance cost management with employee satisfaction by offering competitive wages, benefits, and training opportunities to retain skilled workers and ensure service quality. These challenges highlight the need for innovative strategies to address workforce-related issues effectively. As businesses navigate these multifaceted challenges, those that leverage technology effectively and prioritize sustainable practices are likely to gain a competitive edge in the market.
Market Segmentation Analysis:
By Service Type
The Contractual Cleaning Services Market is segmented into various service types, including floor cleaning, window cleaning, carpet and upholstery cleaning, and others. Floor cleaning services dominate the market, driven by the widespread demand for maintaining hygiene in commercial and residential spaces. Window cleaning services are gaining traction, particularly in urban areas with high-rise buildings where professional expertise is required. Carpet and upholstery cleaning is also witnessing steady growth due to the increasing adoption of professional services for maintaining aesthetics and indoor air quality. Specialized cleaning services, such as medical-grade and industrial cleaning, are emerging as key growth areas, catering to sectors with specific hygiene requirements.
By End Use
The market is further categorized based on end-use industries, including residential, commercial, and industrial sectors. The commercial segment leads the market, encompassing offices, retail spaces, healthcare facilities, and educational institutions, all of which prioritize cleanliness to ensure safety and enhance brand reputation. The industrial segment is expanding due to the rising demand for cleaning services in manufacturing units, warehouses, and factories to maintain operational efficiency and compliance with safety standards. Meanwhile, the residential segment is experiencing notable growth as urban households increasingly rely on professional services for convenience and quality assurance. The growing emphasis on hygiene across all end-use sectors underscores the importance of tailored cleaning solutions to address specific needs effectively.
Segments:
Based on Service Type:
- Exterior
- Parking Lot
- Street
- Window
- Other Exterior
- Interior
-
- Floor & Corridor
- Lobby
- Other Interior
- Fabric Cleaning
-
- Carpets
- Upholstery
- Restoration & Remediation Services
- Swimming Pool & Maintenance
Based on End Use:
- Residential
-
- Individual Houses
- Apartments
- Commercial
-
- Educational Institutions
- Hotels and Restaurants
- Healthcare and Medical
- Retail Outlets
- Corporate Offices
- Others (Financial Institutions)
- Industrial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the global Contractual Cleaning Services Market, accounting for 35% of the total market revenue in 2024. This dominance is attributed to the region’s well-established infrastructure, high standards of cleanliness, and a strong presence of leading service providers. The United States drives market growth with its extensive commercial and industrial sectors, including healthcare, retail, and education, which heavily rely on professional cleaning services to ensure compliance with stringent hygiene regulations. Additionally, rising awareness about workplace health and safety has prompted organizations to invest in outsourced cleaning services to enhance employee well-being and customer satisfaction. For instance, The adoption of cutting-edge technologies, such as robotic cleaning devices, IoT-enabled systems, and AI-driven scheduling tools, further elevates service efficiency and effectiveness in North America. Canada also contributes to regional growth through its expanding urbanization, rising demand for sustainable cleaning solutions, and increasing investments in public infrastructure maintenance. North America’s focus on environmental sustainability has driven a surge in eco-friendly practices, with service providers incorporating biodegradable cleaning agents and energy-efficient equipment. This blend of technological advancement and environmental consciousness positions North America as a leading force in the global cleaning services industry.
Asia-Pacific
Asia-Pacific is emerging as the fastest-growing region, expected to capture a substantial market share of 28% by 2032. The region’s rapid urbanization and industrialization have created a burgeoning demand for contractual cleaning services, particularly in countries like China, India, and Japan. These nations are witnessing significant growth in commercial spaces, shopping malls, hospitals, and manufacturing facilities, driving the need for specialized and large-scale cleaning solutions. For instance, The influx of international cleaning service providers has introduced advanced cleaning technologies and methodologies, enhancing service quality and efficiency in the region. Governments in Asia-Pacific are also playing a pivotal role in market expansion through initiatives aimed at improving public hygiene and sanitation. Programs to modernize public infrastructure, such as airports, railways, and educational institutions, have further boosted the adoption of professional cleaning services. The industrial sector, including manufacturing and logistics, relies increasingly on these services to maintain productivity and comply with regulatory standards. Moreover, rising consumer awareness about hygiene and health, along with a growing middle-class population, has spurred demand for residential cleaning services. With a focus on delivering cost-effective yet high-quality solutions, Asia-Pacific is poised to emerge as a key growth driver for the global Contractual Cleaning Services Market.
Key Player Analysis
- Jani-King International Inc.
- Compass Group plc
- ChemDry
- ISS AS
- Jan-Pro Systems International
- The Clean Space
- Sodexo
- Aramark Corporation
- Mitie Group plc
- Terminix International Company Limited
Competitive Analysis
The Contractual Cleaning Services Market is highly competitive, with leading players such as Sodexo, ISS AS, Compass Group plc, ABM Industries Inc., and Aramark Corporation driving innovation and market expansion. These companies leverage their extensive global networks, advanced technological integrations, and diverse service portfolios to maintain a strong competitive edge. They focus on offering tailored solutions across various sectors, including commercial, industrial, and residential spaces, ensuring compliance with stringent hygiene and safety standards. Strategic partnerships, mergers, and acquisitions are key strategies employed to expand market presence and enhance service capabilities. For instance, a report by the European Cleaning Journal highlights how ISS AS has implemented advanced robotic cleaning technologies to enhance service efficiency and quality. Additionally, the integration of sustainable practices, such as eco-friendly cleaning agents and energy-efficient processes, has become a critical differentiator for these players. This intense competition compels all market participants to continuously innovate and deliver high-quality, cost-effective solutions to retain and grow their customer base.
Recent Developments
- In September 2024, OCS UK & I, a subsidiary of OCS Group Holdings Ltd., acquired Exclusive Services Group, a leading contract cleaning provider in the UK and Ireland. This acquisition strengthens OCS's presence in key sectors and supports its goal of doubling revenue in the region over the next five years.
- In March 2023, 4M Building Solutions announced that it purchased Capital Services. Commercial office complexes, hospitals, and governmental institutions are among the company's clientele, and it specializes in construction cleaning.
- In April 2022, KBS, backed by Cerberus Capital Management, acquired Kimco, a commercial cleaning and facility maintenance provider. The move expands KBS’s service portfolio in the business and industrial sectors, aiming to enhance operational efficiency and industry standards.
- In October 2022, SBFM signed a five-year contract with PureGym to provide commercial cleaning services across all UK locations. PureGym, headquartered in Leeds, plans to double its clubs globally to over 1,000 by 2030.
Market Concentration & Characteristics
The Contractual Cleaning Services Market is moderately fragmented, with a mix of global leaders and regional players competing to capture market share. Key players like Sodexo, ISS AS, and Compass Group plc dominate the landscape, leveraging their extensive resources, advanced technologies, and diverse service portfolios to establish a strong foothold. At the same time, numerous small and medium-sized enterprises cater to local demands, offering tailored and cost-effective solutions. The market is characterized by intense competition, driven by innovation, price sensitivity, and the growing emphasis on eco-friendly and technology-integrated services. Specialized services such as medical-grade cleaning and industrial sanitation are emerging as significant differentiators, catering to niche markets. The increasing focus on long-term contracts and subscription-based models reflects a shift toward sustained client relationships and steady revenue streams. This dynamic environment encourages continuous improvement and adaptation to evolving customer preferences and regulatory standards.
Report Coverage
The research report offers an in-depth analysis based on Service Type, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily, driven by increasing demand for professional cleaning services across commercial, industrial, and residential sectors.
- Integration of advanced technologies like robotic cleaners and IoT-enabled systems will enhance service efficiency and drive adoption.
- Eco-friendly and sustainable cleaning solutions will gain prominence as environmental concerns and regulations intensify globally.
- Subscription-based models are likely to become more popular, offering cost-effective and consistent services for long-term clients.
- Expansion in emerging economies, particularly in Asia-Pacific, will create significant growth opportunities for service providers.
- Specialized cleaning services for sectors like healthcare and education will see rising demand due to stringent hygiene requirements.
- Workforce management and training will remain critical for maintaining service quality and meeting customer expectations.
- Strategic mergers and acquisitions will drive market consolidation and help companies expand their geographic presence.
- Growing urbanization and industrialization will increase demand for large-scale cleaning solutions in high-traffic areas.
- Increased focus on regulatory compliance and safety standards will shape service offerings and market dynamics.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Contractual Cleaning Services Market?
What factors are driving the growth of the Contractual Cleaning Services Market?
What are the key segments within the Contractual Cleaning Services Market?
What are some challenges faced by the Contractual Cleaning Services Market?
Who are the major players in the Contractual Cleaning Services Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Contractual Cleaning Services Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Contractual Cleaning Services Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 181,625 million → 2032: USD 264,280.96 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Contractual Cleaning Services Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Contractual Cleaning Services Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Contractual Cleaning Services Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Contractual Cleaning Services Market Drivers
- 3.3 Contractual Cleaning Services Market Restraints & Challenges
- 3.4 Contractual Cleaning Services Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Contractual Cleaning Services Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Contractual Cleaning Services Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Contractual Cleaning Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Contractual Cleaning Services Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Contractual Cleaning Services Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Contractual Cleaning Services market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Contractual Cleaning Services Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Contractual Cleaning Services Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Contractual Cleaning Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Contractual Cleaning Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Contractual Cleaning Services Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Contractual Cleaning Services Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Contractual Cleaning Services Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Contractual Cleaning Services Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Contractual Cleaning Services Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Contractual Cleaning Services Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Contractual Cleaning Services Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Contractual Cleaning Services Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Contractual Cleaning Services Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
