
Market Overview
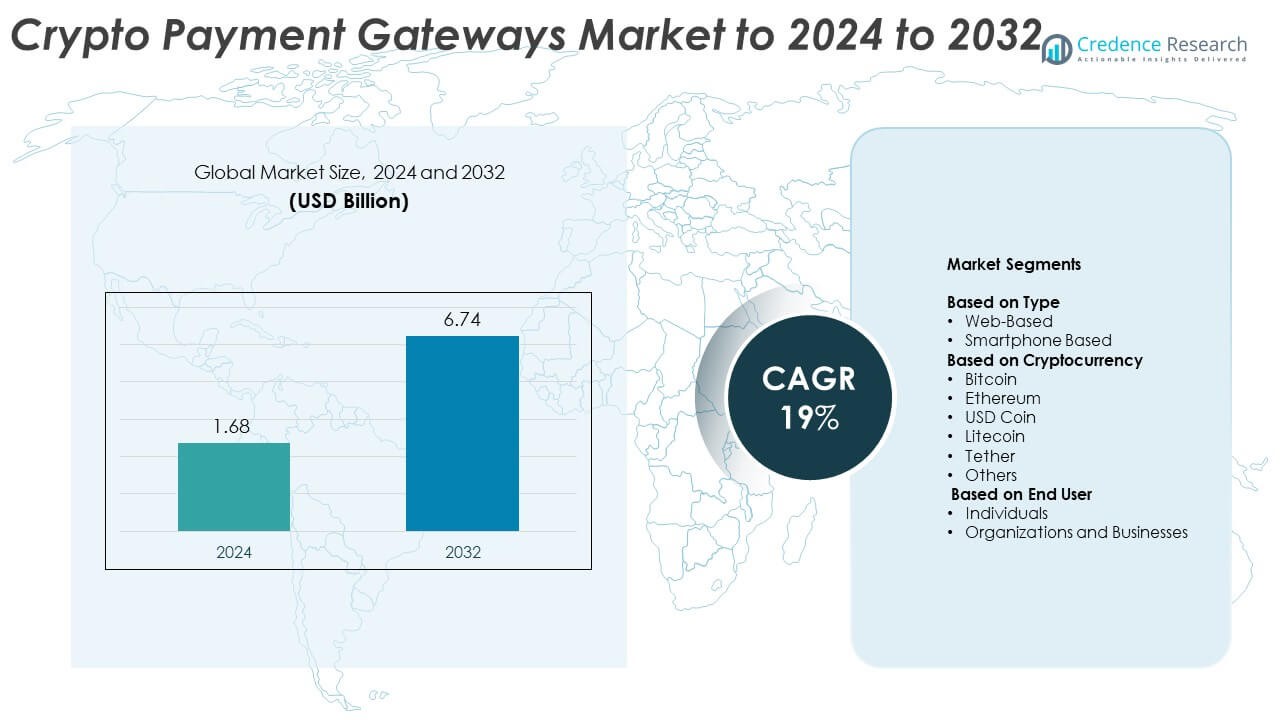
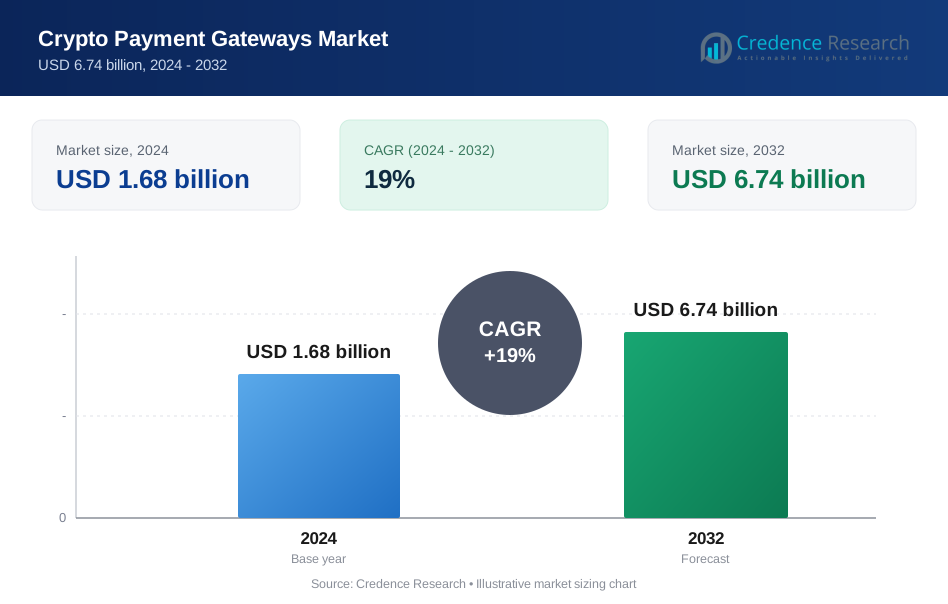
The Crypto Payment Gateways Market size was valued at USD 1.68 billion in 2024 and is anticipated to reach USD 6.74 billion by 2032, at a CAGR of 19% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Crypto Payment Gateways Market Size 2024 | USD 1.68 Billion |
| Crypto Payment Gateways Market, CAGR | 19% |
| Crypto Payment Gateways Market Size 2032 | USD 6.74 Billion |
The crypto payment gateways market is led by prominent players such as BitPay, Coinbase Commerce, PayPal (Crypto Integration), CoinGate, Crypto.com Pay, CoinPayments, Alchemy Pay, and TripleA. These companies are driving innovation through secure blockchain-based transaction platforms, real-time settlement systems, and multi-currency support. They focus on enhancing merchant adoption by offering low-fee and high-speed payment solutions tailored for global e-commerce and fintech ecosystems. Regionally, North America dominated the market in 2024 with a 38% share, supported by strong regulatory frameworks, technological maturity, and high cryptocurrency acceptance among businesses and consumers.
Market Insights
- The crypto payment gateways market was valued at USD 1.68 billion in 2024 and is projected to reach USD 6.74 billion by 2032, growing at a CAGR of 19%. • Market growth is driven by rising digital currency adoption, expanding e-commerce integration, and increasing demand for decentralized low-cost payment systems. • Trends include rapid adoption of stablecoins, integration with Web3 and DeFi platforms, and increasing use of mobile-based crypto payment applications. • Competition is intensifying as leading players invest in blockchain infrastructure, compliance-driven platforms, and partnerships with fintech and e-commerce providers. • North America dominated the market with a 38% share in 2024, followed by Europe with 29% and Asia-Pacific with 25%, while the web-based segment led by type with a 63% share due to its strong adoption in global online transactions.
Market Segmentation Analysis:
By Type
The web-based segment dominated the crypto payment gateways market in 2024 with a 63% share. This dominance stems from its widespread use in e-commerce and online retail platforms. Web-based gateways offer easy API integration, faster transaction verification, and high scalability for businesses handling global payments. The growing adoption of online payment systems among SMEs further strengthens this segment. Smartphone-based gateways are growing rapidly, driven by the expansion of mobile wallets and decentralized finance (DeFi) applications that enhance real-time crypto transactions and user convenience.
- For instance, BitPay processed 608 000 crypto transactions in 2024.
By Cryptocurrency
Bitcoin led the market with a 48% share in 2024 due to its strong liquidity, global acceptance, and reliability as a store of value. Many merchants and payment processors prefer Bitcoin for cross-border payments owing to its high transaction security and brand trust. Ethereum follows closely, benefiting from its smart contract support and DeFi ecosystem integration. Meanwhile, stablecoins such as USD Coin and Tether are gaining traction for minimizing volatility risks, especially in corporate and B2B transactions, enhancing transparency and transaction predictability.
- For instance, Binance Pay's crypto payment users grew to 41.7 million in 2024, a threefold increase from the previous year.
By End User
Organizations and businesses held a 71% market share in 2024, driven by the growing adoption of blockchain-based payment solutions in e-commerce, gaming, travel, and digital services. Businesses increasingly integrate crypto gateways to reduce transaction fees, accelerate settlement times, and attract tech-savvy consumers. The rise of cross-border trade and Web3 adoption further supports enterprise usage. The individual segment is expanding as digital wallets and mobile-based crypto apps simplify everyday transactions, enabling retail users to make small-scale crypto payments and peer-to-peer transfers with greater ease and security.
Key Growth Drivers
Expanding Global Adoption of Digital Currencies
The rapid acceptance of cryptocurrencies as a legitimate payment method is fueling market growth. Businesses across e-commerce, travel, and retail sectors are increasingly integrating crypto gateways to attract digital-first consumers. The growing acceptance of Bitcoin, Ethereum, and stablecoins for international transactions reduces currency conversion fees and enhances settlement speed. Governments in regions such as Europe and Asia-Pacific are also exploring regulatory clarity, encouraging mainstream adoption of crypto payments. This global acceptance is creating a scalable foundation for market expansion and higher transaction volumes.
- For instance, Circle's stablecoin, USDC, recorded over $20 trillion in cumulative lifetime transaction volume in 2024, with its monthly transaction volume reaching $1 trillion in November of that year alone.
Integration with E-Commerce and Fintech Platforms
Integration of crypto payment gateways with e-commerce and fintech platforms is a major growth catalyst. Companies are embedding blockchain-based gateways within online stores, offering secure and transparent transactions. Payment processors now support plugins for Shopify, WooCommerce, and other platforms, making crypto acceptance effortless for merchants. The surge in digital retail activity and preference for decentralized transactions are reinforcing this integration. The trend enhances user trust, boosts transaction efficiency, and aligns with the growing global movement toward borderless digital commerce.
- For instance, according to BitPay's "Decrypted 2024" report, payments for luxury goods and jewelry increased by 39% in 2024, while payments for gold and precious metals rose by 205%.
Rising Preference for Decentralized and Low-Fee Transactions
Increasing dissatisfaction with high fees and intermediaries in traditional payment systems is driving crypto gateway adoption. Users and merchants benefit from lower transaction costs, faster settlement times, and improved transparency through blockchain validation. The shift toward decentralized finance (DeFi) further promotes gateways that bypass centralized banks. As organizations focus on operational efficiency and cost reduction, crypto payment solutions are emerging as a preferred alternative for cross-border trade and online commerce, enabling global transactions with greater financial autonomy.
Key Trends & Opportunities
Adoption of Stablecoins for Payment Stability
The use of stablecoins such as USD Coin and Tether is a major trend reshaping the market. These assets minimize volatility risks that often discourage merchants from accepting crypto payments. Stablecoins allow real-time settlement without exposure to rapid price swings, supporting business-to-business transactions and recurring payments. Financial institutions and payment providers are developing stablecoin-based gateways that offer security, compliance, and ease of integration, strengthening the market’s credibility and expanding its use in mainstream financial and commercial ecosystems.
- For instance, Tether's USDT had an average daily trading volume of approximately $45 billion during part of 2024.
Integration of Web3 and DeFi Ecosystems
The fusion of Web3 and DeFi technologies with crypto payment gateways is creating new growth opportunities. Decentralized applications and smart contracts are being embedded into payment solutions, enabling automated settlements and lending services. This integration enhances transparency, reduces human error, and opens avenues for tokenized loyalty programs and metaverse-based payments. As enterprises explore blockchain interoperability, Web3-enabled gateways are positioned to redefine online commerce by merging decentralized identity, secure transactions, and programmable payment mechanisms.
- For instance, Alchemy Pay deployed its Web3 payment gateway supporting over 300 DeFi tokens across 173 countries in 2024.
Increasing Mobile Payment Penetration
The rising adoption of mobile-based crypto payment applications is reshaping transaction behavior. Advancements in smartphone-based wallets and NFC-enabled payments allow users to transact directly with cryptocurrencies at retail points or online stores. Enhanced security through biometric authentication and private key management strengthens user trust. This shift toward mobile-first payments aligns with the expanding smartphone user base and promotes accessibility, particularly in developing economies where mobile devices act as the primary access point for digital financial services.
Key Challenges
Regulatory Uncertainty and Compliance Barriers
The absence of uniform global regulations remains a critical challenge for crypto payment gateways. Varying compliance standards across countries hinder cross-border adoption and create operational risks for service providers. Issues like anti-money laundering (AML) obligations, taxation ambiguity, and crypto asset classification create uncertainty among investors and merchants. This fragmented regulatory landscape limits financial institutions from fully engaging in crypto transactions. Market growth depends heavily on future regulatory harmonization and clearer guidelines supporting digital currency payments globally.
Security Threats and Transaction Volatility
Cybersecurity risks and transaction volatility continue to threaten market stability. Crypto gateways remain prime targets for hacking, phishing, and malware attacks due to their digital nature. Despite advancements in blockchain security, wallet breaches and key management vulnerabilities persist. Additionally, the fluctuating value of cryptocurrencies discourages small and medium enterprises from accepting crypto payments. Continuous investment in encryption technologies, two-factor authentication, and cold storage solutions is essential to maintaining merchant confidence and sustaining transaction reliability.
Regional Analysis
North America
North America held a 38% share of the crypto payment gateways market in 2024, driven by widespread adoption of cryptocurrencies among merchants and fintech firms. The United States leads with strong blockchain infrastructure, regulatory clarity, and integration of crypto payment options in e-commerce and online gaming sectors. Increasing institutional investment and acceptance of stablecoins also support market growth. Canada’s expanding digital payment ecosystem and favorable startup environment further strengthen regional demand. Major players are focusing on compliance-driven gateway platforms to meet evolving security and transparency requirements.
Europe
Europe accounted for 29% of the market share in 2024, supported by progressive crypto regulations and rising adoption in financial services. The United Kingdom, Germany, and Switzerland are at the forefront due to strong fintech innovation and increasing acceptance of crypto-based payments in retail and travel. The European Union’s MiCA regulation is fostering confidence among payment providers and investors. Growing collaborations between banks and blockchain companies are promoting seamless integration of digital currencies into mainstream financial systems, enhancing the region’s position in global crypto transactions.
Asia-Pacific
Asia-Pacific captured a 25% market share in 2024, emerging as the fastest-growing regional market. Countries such as Japan, Singapore, and South Korea are leading adoption through supportive regulatory frameworks and active fintech ecosystems. The region benefits from high mobile payment penetration and growing interest in decentralized finance solutions. China’s digital yuan initiative and India’s evolving stance on blockchain are influencing market development. Expanding cryptocurrency acceptance among merchants and the rise of crypto-based remittances are key factors driving continuous growth across the Asia-Pacific region.
Middle East & Africa
The Middle East and Africa held a 5% market share in 2024, with increasing adoption driven by financial inclusion initiatives and cross-border payment needs. The United Arab Emirates and Saudi Arabia are advancing blockchain integration through government-led digital transformation strategies. Africa, led by Nigeria and South Africa, is witnessing rapid uptake of crypto gateways for remittances and small business transactions. Limited banking access in rural areas encourages the use of blockchain-based financial solutions. Continuous investment in fintech infrastructure is expected to strengthen regional crypto payment adoption.
Latin America
Latin America accounted for 3% of the global market share in 2024, supported by growing acceptance of digital currencies to counter inflation and transaction inefficiencies. Brazil, Mexico, and Argentina are key markets driving regional expansion. Increased use of Bitcoin and stablecoins for daily transactions is improving financial accessibility among unbanked populations. Fintech startups and retail businesses are introducing crypto payment options to attract tech-savvy consumers. Although regulatory uncertainty persists, collaborations between payment processors and blockchain providers are gradually enhancing trust and stability in crypto-based payment systems.
Market Segmentations:
By Type
- Web-Based
- Smartphone Based
By Cryptocurrency
- Bitcoin
- Ethereum
- USD Coin
- Litecoin
- Tether
- Others
By End User
- Individuals
- Organizations and Businesses
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The crypto payment gateways market features leading players such as BitPay, Coinbase Commerce, PayPal (Crypto Integration), CoinGate, Crypto.com Pay, CoinPayments, Alchemy Pay, and TripleA. The competitive landscape is defined by constant innovation in blockchain-based transaction processing, wallet integration, and security enhancements. Companies focus on developing multi-currency gateways, real-time settlement solutions, and compliance-driven payment systems to meet global standards. Strategic collaborations with fintech providers, banks, and e-commerce platforms are expanding user adoption and transaction volumes. Firms emphasize offering low-fee, high-speed payment options to attract merchants and enterprises transitioning to digital payments. Continuous investment in technology infrastructure, fraud prevention, and cross-border settlement capabilities is driving market consolidation. The competition is further intensifying as emerging players enter the space with region-specific payment models and API-integrated solutions, fostering greater accessibility and scalability across industries.
Key Player Analysis
- BitPay
- Coinbase Commerce
- PayPal (Crypto Integration)
- CoinGate
- com Pay
- CoinPayments
- Alchemy Pay
- TripleA
Recent Developments
- In 2025, Alchemy Pay Launched a fiat-to-RWA (Real World Asset) platform with support for Visa, Mastercard, and xStocks, bridging traditional finance and crypto.
- In 2025, PayPal announced the launch of "Pay with Crypto" for U.S. merchants, allowing them to accept payments from over 100 different cryptocurrencies through popular wallets like Coinbase and MetaMask.
- In 2023, BitPay Partnered with Banxa to expand its crypto payment access across dozens of countries.
Report Coverage
The research report offers an in-depth analysis based on Type, Cryptocurrency, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue expanding as more businesses adopt blockchain-based payment systems.
- Integration of crypto gateways with mainstream e-commerce platforms will become standard practice.
- Stablecoins will gain broader use for reducing volatility in daily transactions.
- Governments will introduce clearer regulations to support cross-border crypto payments.
- Mobile-based crypto payment applications will dominate small and peer-to-peer transactions.
- Partnerships between fintech firms and traditional banks will accelerate crypto payment innovation.
- Advancements in blockchain security will strengthen user trust and transaction safety.
- DeFi and Web3 technologies will enhance automation and transparency in crypto payments.
- Institutional investors will increasingly back crypto gateway providers to diversify payment infrastructure.
- Global consumer demand for low-cost, borderless payments will sustain long-term market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Crypto Payment Gateways Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Crypto Payment Gateways Market projected to grow between 2025 and 2032?
Which Crypto Payment Gateways Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Crypto Payment Gateways Market?
Who are the leading companies in the Crypto Payment Gateways Market?
Which region commanded the largest share of the Crypto Payment Gateways Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.68 billion → 2032: USD 6.74 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Crypto Payment Gateways Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Crypto Payment Gateways Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Crypto Payment Gateways Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Crypto Payment Gateways Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Crypto Payment Gateways Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Crypto Payment Gateways Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Crypto Payment Gateways Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Crypto Payment Gateways Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.68 billion → 2032: USD 6.74 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Crypto Payment Gateways Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Crypto Payment Gateways Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Crypto Payment Gateways Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Crypto Payment Gateways Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
