
Market overview
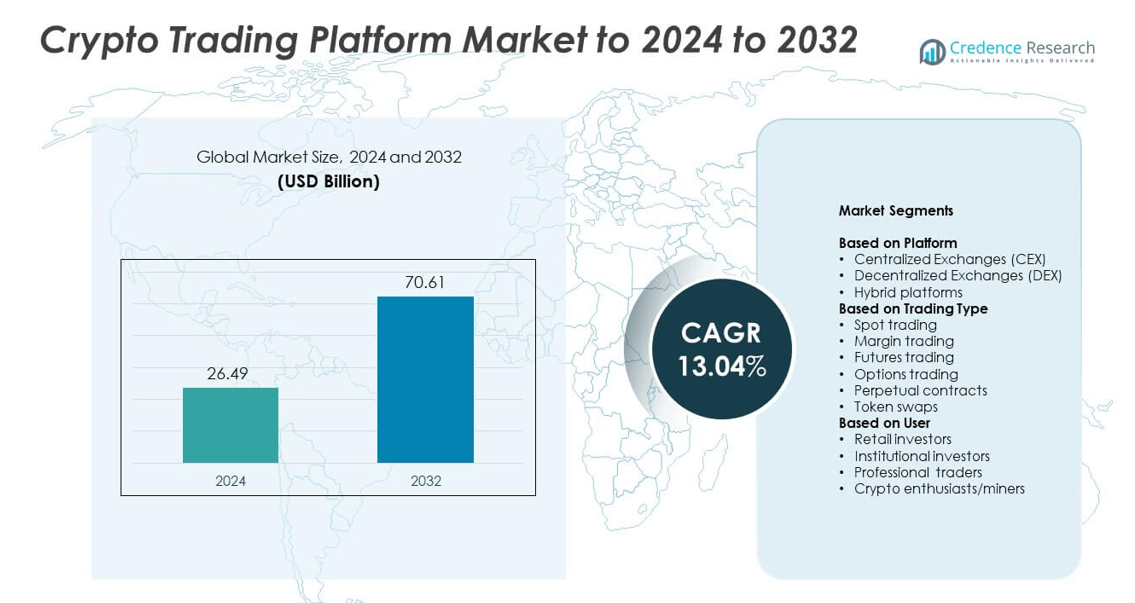
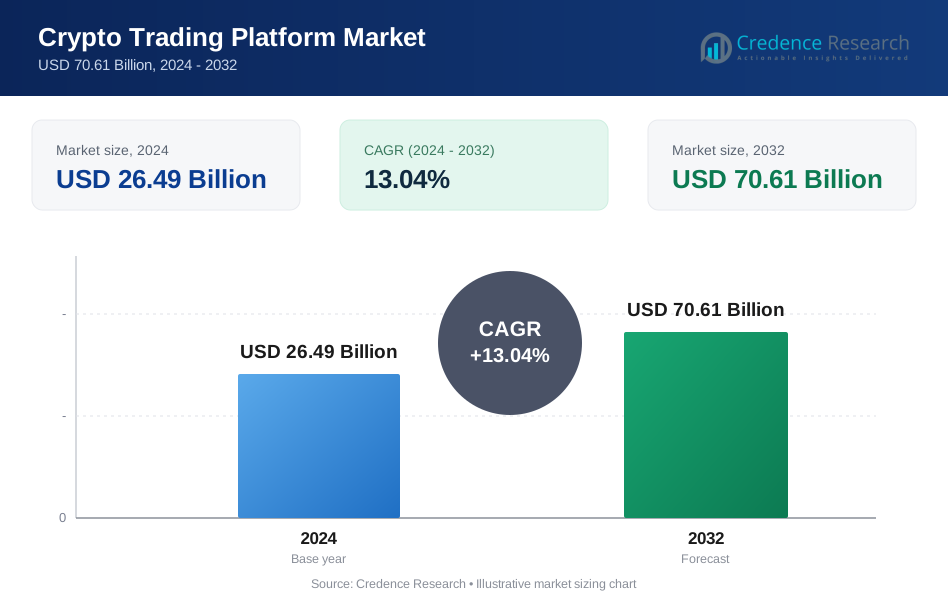
Crypto Trading Platform Market size was valued USD 26.49 Billion in 2024 and is anticipated to reach USD 70.61 Billion by 2032, at a CAGR of 13.04% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Crypto Trading Platform Market Size 2024 | USD 26.49 Billion |
| Crypto Trading Platform Market, CAGR | 13.04% |
| Crypto Trading Platform Market Size 2032 | USD 70.61 Billion |
The global crypto trading platform market is led by major players such as Coinbase, Binance, Bitstamp, Bybit, Gemini, Gate.io, Bitfinex, Cex.io, Crypto.com, Delta Exchange India, and Arkham. These companies dominate through advanced trading infrastructure, high liquidity, and strong compliance with regulatory standards. Their focus on AI-driven analytics, cross-chain interoperability, and secure custody solutions strengthens user confidence and trading efficiency. North America emerged as the leading region with a 35% market share in 2024, driven by strong institutional participation, established financial infrastructure, and favorable regulatory frameworks supporting both centralized and decentralized trading ecosystems.
Market Insights
- The global crypto trading platform market was valued at USD 26.49 Billion in 2024 and is projected to reach USD 70.61 Billion by 2032, growing at a CAGR of 13.04%.
- Market growth is driven by rising institutional adoption, technological advancements, and expanding regulatory frameworks supporting secure trading environments.
- Key trends include the rise of decentralized and hybrid exchanges, integration of AI-driven trading systems, and increasing tokenization of traditional assets.
- The market is highly competitive, with exchanges focusing on user security, liquidity depth, and multi-chain interoperability to gain advantage.
- North America led with a 35% share in 2024, followed by Asia Pacific with 25% and Europe with 20%, while Latin America and the Middle East & Africa accounted for 12% and 8%, respectively.
Market Segmentation Analysis:
By Platform
Centralized Exchanges (CEX) dominated the crypto trading platform market with a 67% share in 2024. The dominance is driven by high liquidity, user-friendly interfaces, and integrated security measures offered by platforms such as Binance, Coinbase, and Kraken. Centralized platforms attract both new and experienced traders through advanced trading tools and customer support. The availability of fiat gateways and compliance with regulatory standards further enhances their reliability. Growth in institutional adoption and regulatory clarity continues to strengthen the CEX segment’s market leadership.
- For instance, according to a CoinGecko report published in February 2025, Binance's annual cumulative trading volume in 2024 was approximately $7.35 trillion
By Trading Type
Spot trading held the largest share of 48% in 2024, driven by its simplicity and direct ownership benefits. Retail and professional investors favor spot markets for immediate settlement without leverage risks. Platforms like Binance and Coinbase facilitate high-volume spot transactions supported by transparent pricing and real-time order books. The integration of mobile trading apps and API-driven systems enhances accessibility and trading speed. Increasing crypto adoption and stablecoin usage continue to fuel growth in spot trading activity across global markets.
- For instance, according to Coinbase's Q4 2024 shareholder letter, the total spot trading volume for the entire quarter was $439 billion
By User
Retail investors accounted for a 52% share of the crypto trading platform market in 2024. This dominance is supported by the rise of mobile-based applications, social trading features, and easy onboarding processes. Exchanges such as eToro and OKX attract retail traders through copy trading tools, educational resources, and gamified interfaces. Growing awareness of cryptocurrency investment potential and decreasing transaction fees encourage broader participation. The introduction of secure wallets and regulatory compliance standards further boosts confidence among individual investors.
Key Growth Drivers
Rising Institutional Adoption of Digital Assets
Institutional participation is accelerating the expansion of crypto trading platforms. Major financial institutions, hedge funds, and asset managers are integrating cryptocurrencies into diversified portfolios. This shift drives demand for secure, compliant, and scalable trading infrastructure. Platforms are introducing custody solutions and advanced analytics to support high-volume trades. Institutional entry has also increased market liquidity and transparency, creating greater investor confidence. As regulatory frameworks evolve globally, the institutional segment is expected to further strengthen the market’s long-term stability and growth.
- For nstance,In its market statistics release on January 3, 2025, CME Group reported a record annual average daily volume (ADV) of 16,000 Bitcoin futures contracts for the full year 2024.
Expansion of Regulatory Clarity and Compliance
Improved regulatory oversight across major economies is fueling market confidence. Governments and financial authorities are establishing guidelines to prevent fraud, enhance KYC/AML standards, and protect investors. Exchanges compliant with these standards gain higher user trust and attract global participation. Regulatory alignment in countries like the U.S., Singapore, and the EU fosters innovation and institutional entry. Clear legal frameworks are also driving mergers, partnerships, and platform upgrades, helping the crypto trading ecosystem mature while ensuring operational transparency.
- For instance, Bitstamp holds over 50 licenses and registrations globally, supporting compliant access across multiple jurisdictions
Technological Advancements in Trading Infrastructure
The adoption of AI, blockchain analytics, and algorithmic trading is transforming crypto platforms. Enhanced automation and real-time data analytics enable faster execution and accurate price discovery. Platforms leverage smart contracts and decentralized protocols to improve transparency and reduce counterparty risk. Innovations such as layer-2 scaling solutions lower transaction costs and increase trading speed. These technological developments enhance platform efficiency, strengthen user experience, and attract diverse participants, including retail and institutional traders, driving overall market expansion.
Key Trends & Opportunities
Integration of DeFi and Cross-Chain Trading
Cross-chain interoperability and decentralized finance (DeFi) integration are creating new opportunities for seamless trading. Users can now trade tokens across multiple blockchain networks without relying on intermediaries. Platforms offering hybrid models that combine CEX liquidity with DEX flexibility are gaining popularity. This approach improves asset mobility and reduces transaction friction. Growing demand for decentralized liquidity pools and yield-generating products continues to reshape how users interact with crypto trading ecosystems.
- For instance, as of October 2024, Uniswap introduced in-app bridging across 9 networks, including Ethereum, Base, and Arbitrum, to enable seamless asset movement.
Growth of Tokenized Assets and Derivatives
Tokenization of traditional assets such as stocks, bonds, and commodities is expanding the scope of crypto trading. Exchanges offering tokenized derivatives enable investors to diversify portfolios and hedge risks efficiently. The popularity of perpetual contracts and crypto futures among professional traders further boosts market liquidity. This trend is supported by innovations in smart contract automation and blockchain-based asset issuance, bridging traditional finance and digital asset trading ecosystems.
- For instance, as of September 2025, WisdomTree offers at least 14 SEC-registered tokenized funds to investors, with the 14th fund, the WisdomTree Private Credit and Alternative Income Digital Fund (CRDT), launched on September 12, 2025
Key Challenges
Regulatory Uncertainty Across Jurisdictions
Inconsistent global regulations remain a major obstacle to crypto market expansion. Varying compliance standards across countries limit platform scalability and cross-border trading. Sudden policy changes, such as trading bans or taxation shifts, disrupt market operations. Platforms must continuously adapt to evolving requirements, increasing operational costs. The absence of unified global standards creates compliance risks and slows institutional participation, affecting overall market confidence and growth.
Cybersecurity Risks and Exchange Vulnerabilities
Crypto trading platforms remain prime targets for cyberattacks and data breaches. Despite advanced encryption and multi-factor authentication, exchange vulnerabilities lead to significant asset losses and reputational damage. Hack incidents undermine investor trust, especially among institutional clients. Platforms are investing heavily in blockchain analytics, cold storage solutions, and zero-trust frameworks to enhance defense mechanisms. However, the rising sophistication of cyber threats continues to pose a persistent challenge to secure trading operations.
Regional Analysis
North America
In 2024 the North America region accounted for approximately 35 % of the global crypto trading platform market share. The region’s lead stems from a mature financial infrastructure, high institutional adoption, and regulatory clarity that promotes platform confidence and scalability. Large-scale platforms and exchanges are headquartered in the United States, supporting heavy volumes and innovation in derivatives and tokenised assets. Advanced custody and trading services, combined with strong retail uptake, bolster the region’s dominance and position it as a key growth hub.
Europe
Europe held an estimated market share of around 20 % in 2024 for crypto trading platforms. This region benefits from the rollout of frameworks such as the Markets in Crypto-Assets regulation, which enhances transparency and trust among users and institutions. Growing interest in decentralised finance protocols and mature capital markets drive platform adoption across major countries like Germany, the United Kingdom and France. The regulatory push and broad institutional participation position Europe for solid expansion although the share trails North America.
Asia Pacific
Asia Pacific captured roughly 25 % of the global market in 2024, making it the second-largest regional segment. Rapid digital adoption, strong participation from retail users, and a surge in crypto innovations in countries such as South Korea, Japan and Singapore underpin the region’s growth. While regulation remains uneven, the scale of populations, mobile penetration and blockchain talent emphasise Asia Pacific’s importance. Platforms focusing on cross-chain liquidity and regional partnerships stand to accelerate further adoption.
Latin America
Latin America accounted for about 12 % of the crypto trading platform market in 2024 and is growing rapidly. The region’s demand is driven by high inflation economies, stablecoin usage, and fintech collaborations enabling crypto access in under-banked populations. Brazil leads the market share within Latin America, and regulatory advances along with mobile onboarding capabilities bolster platform expansion. The relatively smaller absolute size compared with developed regions masks strong potential for growth.
Middle East & Africa
The Middle East & Africa (MEA) region held approximately 8 % of the global crypto trading platform market in 2024. Growth is supported by government-backed digital-asset initiatives, favourable tax regimes in key hubs such as UAE, and increasing institutional interest in the Gulf region. However, infrastructure limitations, regulatory divergence and lower overall market maturity compared with developed regions temper the share. Nonetheless, MEA is emerging as a strategic frontier for platforms seeking new user bases.
Market Segmentations:
By Platform
- Centralized Exchanges (CEX)
- Decentralized Exchanges (DEX)
- Hybrid platforms
By Trading Type
- Spot trading
- Margin trading
- Futures trading
- Options trading
- Perpetual contracts
- Token swaps
By User
- Retail investors
- Institutional investors
- Professional traders
- Crypto enthusiasts/miners
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The crypto trading platform market is highly competitive, featuring key players such as Coinbase, Binance, Bitstamp, Bybit, Gemini, Gate.io, Bitfinex, Cex.io, Crypto.com, Delta Exchange India, and Arkham. The market is defined by continuous innovation, strong liquidity networks, and rapid technological integration to attract both retail and institutional investors. Companies focus on advanced trading engines, enhanced security protocols, and user-friendly interfaces to strengthen customer retention. Regulatory compliance, particularly across major markets like the U.S., EU, and Asia, has become a critical differentiator among leading platforms. Many exchanges are expanding into derivatives, staking, and DeFi-integrated services to diversify revenue streams. Partnerships with payment gateways, blockchain developers, and financial institutions are increasing to improve operational efficiency and accessibility. Moreover, the rise of AI-driven trading tools and mobile applications continues to shape the user experience, making the market increasingly dynamic and innovation-centric.
Key Player Analysis
Recent Developments
- In 2025, Coinbase relaunched its services in India and invested in the local exchange CoinDCX.
- In 2024, Arkham Intelligence to launch a US spot trading platform, restricted by state regulations
- In 2024, Binance successfully re-entered the Indian market by registering with the Financial Intelligence Unit (FIU) after previously being banned.
Report Coverage
The research report offers an in-depth analysis based on Platform, Trading Type, User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Institutional participation will continue to expand, enhancing liquidity and market depth.
- Regulatory frameworks will become more unified, improving compliance and investor protection.
- AI-driven analytics will enhance automated trading and risk management capabilities.
- Cross-chain interoperability will enable seamless trading across multiple blockchain networks.
- The rise of tokenized assets will bridge traditional finance and crypto ecosystems.
- Decentralized exchanges will gain traction as users seek greater control and transparency.
- Enhanced cybersecurity measures will strengthen platform trust and reliability.
- Integration of stablecoins will promote smoother settlement and reduced volatility.
- Mobile-first trading solutions will attract wider participation from retail investors.
- Strategic partnerships between fintechs and banks will accelerate mainstream crypto adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Crypto Trading Platform Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Crypto Trading Platform Market projected to grow between 2025 and 2032?
Which Crypto Trading Platform Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Crypto Trading Platform Market?
Who are the leading companies in the Crypto Trading Platform Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Crypto Trading Platform Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Crypto Trading Platform Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 26.49 Billion → 2032: USD 70.61 Billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Crypto Trading Platform Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Crypto Trading Platform Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Crypto Trading Platform Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Crypto Trading Platform Market Drivers
- 3.3 Crypto Trading Platform Market Restraints & Challenges
- 3.4 Crypto Trading Platform Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Crypto Trading Platform Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Crypto Trading Platform Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Crypto Trading Platform category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Crypto Trading Platform Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Crypto Trading Platform Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Crypto Trading Platform market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Crypto Trading Platform Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Crypto Trading Platform Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Crypto Trading Platform Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Crypto Trading Platform (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Crypto Trading Platform Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Crypto Trading Platform Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Crypto Trading Platform Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Crypto Trading Platform Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Crypto Trading Platform Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Crypto Trading Platform Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Crypto Trading Platform Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Crypto Trading Platform Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Crypto Trading Platform Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
