
Market Overview
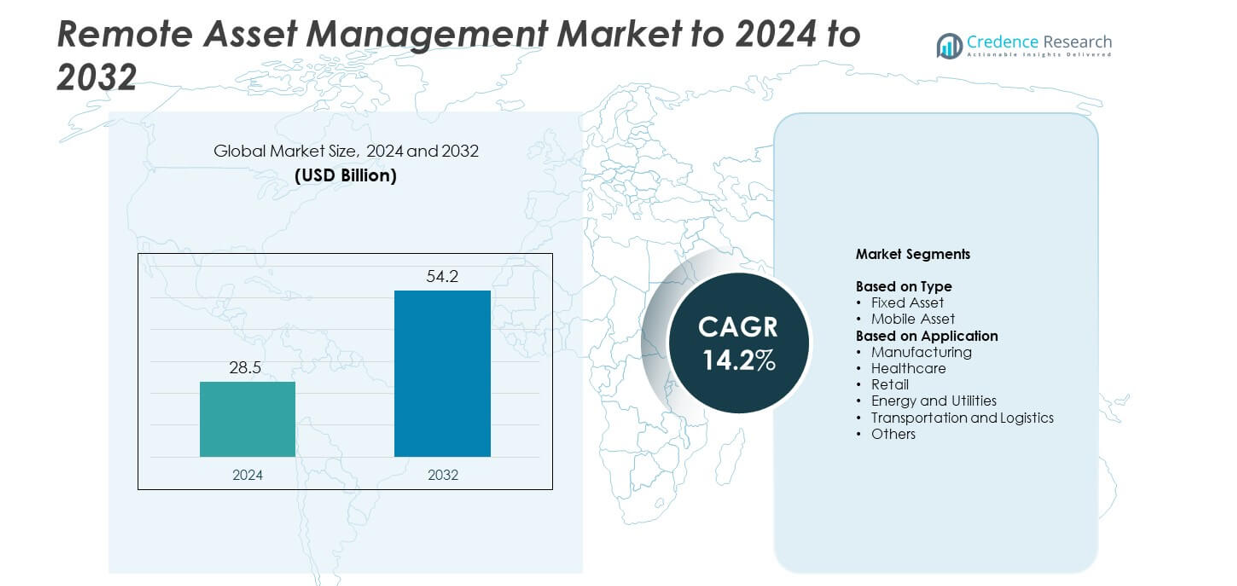
The Remote Asset Management Market size was valued at USD 28.5 billion in 2024 and is anticipated to reach USD 54.2 billion by 2032, at a CAGR of 14.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Remote Asset Management Market Size 2024 | USD 28.5 billion |
| Remote Asset Management Market, CAGR | 14.2% |
| Remote Asset Management Market Size 2032 | USD 54.2 billion |
The Remote Asset Management Market is dominated by major players such as Siemens, ABB, Cisco, Schneider Electric, Emerson, and Honeywell, which lead through advanced IoT integration, cloud-based analytics, and predictive maintenance solutions. These companies focus on expanding digital service portfolios, improving real-time monitoring accuracy, and enabling AI-driven asset optimization. Strategic collaborations and technology partnerships continue to strengthen their global footprint. North America accounted for the largest market share of 37% in 2024, supported by early digital adoption, robust industrial infrastructure, and growing investments in connected asset ecosystems across energy, manufacturing, and logistics sectors.
Market Insights
- The remote asset management market was valued at USD 28.5 billion in 2024 and is projected to reach USD 54.2 billion by 2032, growing at a CAGR of 14.2%.
- Growing adoption of IoT, AI, and predictive maintenance technologies drives demand for real-time asset tracking and operational efficiency.
- Integration of edge computing and 5G connectivity is transforming remote monitoring by enabling faster data processing and improved accuracy.
- The market is highly competitive, with players focusing on advanced analytics, cloud-based solutions, and cross-industry collaborations to strengthen global reach.
- North America led the market with a 37% share in 2024, followed by Asia Pacific at 30% and Europe at 25%, while the mobile asset segment accounted for the dominant 63% share.
Market Segmentation Analysis:
By Type
The mobile asset segment dominated the remote asset management market with a 63% share in 2024. This dominance is driven by the widespread adoption of IoT-enabled tracking and telematics solutions for vehicles, machinery, and logistics fleets. Companies are integrating GPS and cloud-based analytics to monitor equipment performance and reduce downtime. The growing need for real-time asset visibility and operational efficiency across industries further accelerates mobile asset adoption. Demand is increasing across transportation, construction, and logistics sectors where remote monitoring enhances productivity and safety.
- For instance, Powerfleet reported 2.8 million subscribed units in FY 2025 after a 4× expansion.
By Application
The energy and utilities segment held the leading share of 34% in 2024, driven by large-scale integration of remote monitoring systems in power generation, oil and gas, and water management operations. Utilities use sensor-based networks and predictive maintenance platforms to reduce equipment failures and improve resource utilization. Automation and IoT-driven analytics allow operators to monitor distributed assets such as transformers and pipelines in real time. Increasing digitalization of grid systems and renewable energy facilities continues to strengthen this segment’s dominance in remote asset management adoption.
- For instance, Itron's CityEdge portfolio, unveiled in October 2024, builds on the company's established presence of more than 270 million IoT endpoints deployed globally to over 8,000 customers in more than 100 countries.
Key Growth Drivers
Rising Deployment of IoT and Cloud Technologies
Widespread IoT adoption and cloud-based data management are driving the remote asset management market. Connected devices enable real-time tracking and predictive maintenance across industries such as energy, manufacturing, and logistics. Cloud integration allows seamless access to operational data and improves decision-making efficiency. Enterprises are increasingly investing in digital monitoring platforms to enhance visibility, reduce maintenance costs, and extend equipment life. The expanding use of smart sensors and analytics platforms continues to fuel IoT-driven asset intelligence globally.
- For instance, Cisco IoT Control Center manages about 270 million+ device connections for 32k+ enterprises.
Increasing Focus on Predictive Maintenance
The growing emphasis on predictive maintenance is a major catalyst for market expansion. Companies are implementing advanced analytics and AI algorithms to detect anomalies and forecast equipment failures before breakdowns occur. This reduces unplanned downtime, minimizes repair costs, and improves asset reliability. Industrial operators in manufacturing and utilities increasingly rely on automated monitoring tools for maintenance scheduling. Predictive asset management enhances operational efficiency and ensures continuous service availability, supporting the industry’s long-term growth.
- For instance, Siemens reports up to a 50% reduction in unplanned downtime and an 85% improvement in forecasting accuracy after PdM adoption.
Growing Adoption Across Industrial Verticals
Expanding applications across sectors such as oil and gas, utilities, healthcare, and transportation are strengthening market growth. Organizations deploy remote monitoring systems to manage distributed assets, track performance, and comply with safety standards. In energy and utilities, remote management supports smart grid modernization and renewable integration. In healthcare, it aids in medical equipment tracking and uptime optimization. The cross-industry applicability of remote asset solutions positions it as a key enabler of digital transformation.
Key Trends and Opportunities
Integration of Artificial Intelligence and Edge Computing
AI and edge computing are transforming remote asset management by enabling faster and smarter decision-making at the source. Edge devices process data locally, reducing latency and bandwidth use. This supports real-time analytics and improves the responsiveness of monitoring systems. AI algorithms enhance fault detection accuracy and optimize asset utilization. As industries adopt automation and smart infrastructure, the convergence of AI and edge technologies presents strong growth opportunities for advanced asset management platforms.
- For instance, after acquiring Ericsson’s IoT units in 2023, Aeris has built upon its combined capabilities and now serves thousands of enterprises across industries like automotive, utilities, and healthcare. According to company information from October 2025, Aeris connected 93 million IoT devices and served 7,000 enterprise customers across more than 100 countries and nearly 30 mobile network operator partners.
Expansion of 5G Connectivity for Real-Time Monitoring
The rollout of 5G networks is creating new opportunities for remote asset management applications. Ultra-low latency and high-speed communication enable continuous data transmission from assets in motion or located in remote areas. This allows industries such as logistics, mining, and energy to monitor assets with high precision. Enhanced connectivity supports more complex IoT ecosystems, facilitating the integration of autonomous systems and real-time diagnostics. 5G is emerging as a key enabler for next-generation asset intelligence.
- For instance, AT&T’s FirstNet serves 7.8 million connections across about 30,600 agencies, underpinning mission-critical asset communications.
Shift Toward Sustainability and Energy Efficiency
Rising environmental awareness is pushing industries to adopt sustainable asset management solutions. Companies are integrating energy-efficient sensors, optimizing asset lifecycles, and reducing carbon footprints through digital monitoring. Smart platforms help track emissions, resource consumption, and operational efficiency. Renewable energy operators use remote monitoring to ensure optimal output and compliance with environmental goals. The focus on sustainability and green operations is creating long-term opportunities for eco-efficient asset management solutions.
Key Challenges
High Implementation and Integration Costs
The initial investment required for deploying remote asset management systems remains a major challenge. Costs associated with IoT sensors, communication networks, software integration, and staff training can be substantial for small and mid-sized enterprises. Legacy infrastructure often needs upgrades to support real-time data connectivity, further increasing expenses. Despite strong ROI potential, budget limitations and long payback periods restrict adoption in cost-sensitive industries, slowing overall market penetration.
Data Security and Privacy Concerns
Rising cyber threats and data breaches pose serious risks to remote asset management systems. The collection and transmission of sensitive operational data across cloud networks increase vulnerability to unauthorized access. Industries such as energy and healthcare face strict compliance requirements, making data protection critical. Companies must invest in encryption, authentication, and secure communication protocols to safeguard connected assets. Ongoing concerns about cybersecurity readiness remain a key restraint for widespread deployment.
Regional Analysis
North America
In 2024, North America captured around 37 % of the global remote asset management market. This region leads thanks to advanced infrastructure, strong IoT adoption and widespread use of cloud analytics. Organizations leverage remote monitoring for fleets, utilities and manufacturing assets to drive productivity and reduce downtime. The presence of major technology providers and early uptake of predictive maintenance solutions further support growth. As industrial digitalisation ramps up, North America remains the largest regional contributor and a benchmark for solution maturity.
Europe
Europe accounted for approximately 25 % of the remote asset management market in 2024. Growth is supported by Industry 4.0 initiatives, regulatory drivers for sustainability and strong digital trend uptake among manufacturing and utilities firms. Countries such as Germany and the UK lead the region in asset-monitoring deployments that emphasise real-time analytics and lifecycle optimisation. While technological maturity is high, variable infrastructure across countries may affect uniform adoption. Overall Europe holds a significant share and continues shifting toward integrated IoT-enabled asset ecosystems.
Asia Pacific
The Asia Pacific region held close to 30 % of the market share in 2024 and is projected to record the highest growth rate through the forecast period. Governments and enterprises in China, India and Japan are investing in IoT, cloud and smart-asset infrastructure at scale. Rapid industrialisation, expansion of logistics networks and rollout of renewable energy assets create strong demand for remote asset management. The combination of large emerging markets and rapid technology acceptance positions Asia Pacific as a key growth region in the global market.
Middle East & Africa
Middle East & Africa together held about 5 % of the global market in 2024. The region’s market is driven by infrastructure development, oil & gas sector investments and growing adoption of monitoring solutions in utilities and transport. Challenges such as connectivity, regulatory fragmentation and investment constraints moderate growth. Nonetheless, as digitalisation progresses and government initiatives for smart cities gain pace, MEA shows promising potential for increased uptake of remote asset management solutions.
Latin America
Latin America represented roughly 3 % of the remote asset management market in 2024. Its growth is propelled by expansion in mining, oil & gas and transportation sectors that require remote monitoring across wide-spread assets. Adoption is slower than in mature markets due to lower infrastructure maturity, budget limitations and less vendor presence. However, increasing foreign investment in industrial digitisation and fleet tracking solutions offers prospects for accelerated growth in the coming years.
Market Segmentations:
By Type
- Fixed Asset
- Mobile Asset
By Application
- Manufacturing
- Healthcare
- Retail
- Energy and Utilities
- Transportation and Logistics
- Others
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The Remote Asset Management Market is led by major players such as Siemens, ABB, Cisco, Bosch Software Innovations, Aspen Technology, Schneider Electric, Emerson, General Electric, Honeywell, Rockwell Automation, AVEVA, IBM, SAP SE, AT&T, PTC, Hitachi, Infosys, and OSIsoft. The market remains highly competitive, with participants focusing on digital innovation, advanced IoT integration, and AI-based analytics to enhance real-time monitoring capabilities. Companies are prioritizing partnerships and cloud-based solutions to expand their service portfolios and strengthen market presence. Continuous investment in predictive maintenance technologies and edge computing solutions supports better operational efficiency and reliability. Vendors are also adopting subscription-based models and data-driven service frameworks to improve customer retention and recurring revenue streams. Strategic mergers, platform integrations, and industry collaborations are further reshaping the competitive environment, as firms aim to deliver scalable, secure, and interoperable solutions that meet the growing demand for digital asset visibility and lifecycle optimization across industrial sectors.
Key Player Analysis
- Siemens
- ABB
- Cisco
- Bosch Software Innovations
- Aspen Technology
- Schneider Electric
- Emerson
- General Electric
- Honeywell
- Rockwell Automation
- AVEVA
- IBM
- SAP SE
- AT&T
- PTC
- Hitachi
- Infosys
- OSIsoft
Recent Developments
- In 2024, IBM Introduced a generative AI assistant to Maximo, enabling natural language conversations with data and streamlining work orders.
- In 2023, PTC integrated its ThingWorx platform with other technologies, particularly ServiceMax and Servigistics, to provide customers with more comprehensive, end-to-end solutions for remote asset management.
- In 2023, Cisco introduces new cloud services in IoT Operations Dashboard to increase industrial asset visibility, securely manage assets from anywhere and provide Industrial Internet of Things (IoT) customers with a seamless path to cloud automation for Operational Technology (OT) teams.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Remote asset management adoption will rise with wider IoT and AI integration across industries.
- Predictive maintenance solutions will become standard for reducing downtime and improving asset lifespan.
- Cloud-based platforms will dominate due to scalability, real-time access, and lower infrastructure costs.
- 5G deployment will enhance connectivity, enabling faster and more reliable asset data transmission.
- Energy and utilities will remain the leading application segment driven by grid modernization efforts.
- Asia Pacific will emerge as the fastest-growing region due to industrial automation and digital investments.
- Edge computing will gain traction for real-time analytics and reduced data latency in monitoring systems.
- Sustainability initiatives will encourage adoption of energy-efficient and low-emission asset management solutions.
- Integration with blockchain will improve data security, transparency, and traceability across asset networks.
- Partnerships between IoT providers and industrial enterprises will accelerate innovation and market expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Remote Asset Management Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Remote Asset Management Market projected to grow between 2025 and 2032?
Whi.ch Remote Asset Management Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Remote Asset Management Market?
Who are the leading companies in the Remote Asset Management Market?
6. Which region commanded the largest share of the Remote Asset Management Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 28.5 billion → 2032: USD 54.2 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Remote Asset Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Remote Asset Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Remote Asset Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Remote Asset Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Remote Asset Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Remote Asset Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Remote Asset Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Remote Asset Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 28.5 billion → 2032: USD 54.2 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Remote Asset Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Remote Asset Management Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Remote Asset Management Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Remote Asset Management Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

