
Cutaneous Fibrosis Treatment Market Overview:
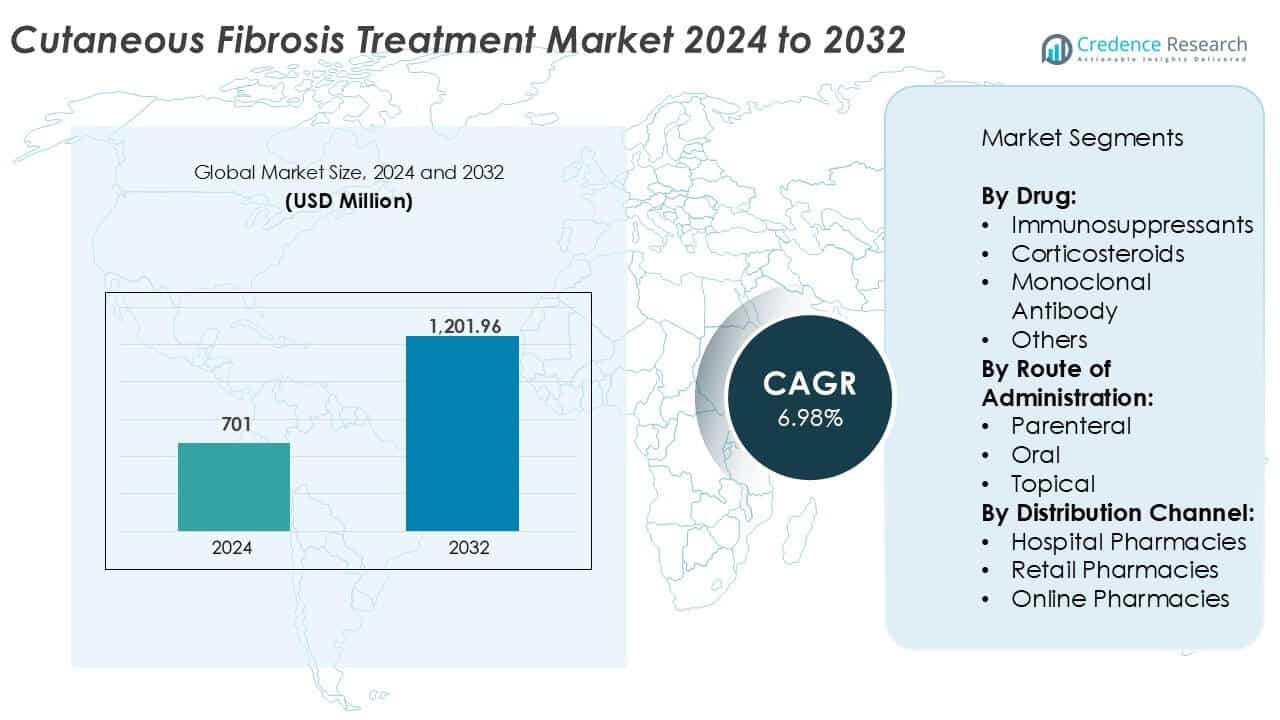
The Cutaneous Fibrosis Treatment market size was valued at USD 701 million in 2024 and is anticipated to reach USD 1,201.96 million by 2032, at a CAGR of 6.98% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cutaneous Fibrosis Treatment Market Size 2024 | USD 701 million |
| Cutaneous Fibrosis Treatment Market, CAGR | 6.98% |
| Cutaneous Fibrosis Treatment Market Size 2032 | USD 1,201.96 million |
The Cutaneous Fibrosis Treatment market is led by major pharmaceutical companies with strong expertise in autoimmune and rare disease therapies. Key players include Novartis AG, Pfizer, Sanofi, F. Hoffmann-La Roche (Genentech), AbbVie, Amgen, Bristol-Myers Squibb, and Johnson & Johnson Services. These companies focus on immunosuppressants, corticosteroids, and advanced biologics, supported by robust clinical pipelines and global distribution networks. North America dominates the market, holding approximately 38% of the global share, driven by high disease awareness, advanced healthcare infrastructure, and strong reimbursement support for biologic therapies. Europe follows with a solid presence, while Asia Pacific shows rising participation due to expanding patient access and improving diagnostic capabilities. Competitive strength depends on innovation, regulatory approvals, and access to specialty care channels.
Cutaneous Fibrosis Treatment Market Insights
- The market reached USD 701 million in 2024 and will grow to USD 1,201.96 million by 2032, at a 6.98% CAGR, driven by chronic skin fibrosis demand.
- Rising cases of autoimmune disorders, including systemic sclerosis, drive steady demand for immunosuppressants, which hold the largest drug segment share at over 40%.
- Increased adoption of biologics, clinical trials for antifibrotic pathways, and hospital-based parenteral therapies define current market trends.
- Leading players such as Novartis, Pfizer, Sanofi, and Roche compete through biologic innovation, orphan drug strategies, and expanded specialty distribution.
- High therapy costs, limited early diagnosis, and biologic access barriers restrain growth, while North America leads with ~38% share, followed by Europe at ~27%, Asia Pacific at ~20%, and the remaining share across Latin America and the Middle East & Africa.
Cutaneous Fibrosis Treatment Market Segmentation Analysis:
By Type
Immunosuppressants dominated the drug segment in the Cutaneous Fibrosis Treatment market, accounting for the highest revenue share in 2024. These drugs reduce abnormal immune responses and are widely used in treating scleroderma and other fibrosis-related skin disorders. Their efficacy in controlling inflammation and halting disease progression makes them a preferred option among physicians. Corticosteroids followed as the second most utilized class due to their rapid anti-inflammatory action. Monoclonal antibodies are gaining momentum, especially in clinical settings, for their targeted mechanism of action. Advancements in biologics are expected to expand the monoclonal antibody sub-segment over the forecast period.
- For instance, Roche’s CellCept (mycophenolate mofetil) is prescribed at doses up to 3,000 mg per day and demonstrated reduced skin thickness scores in systemic sclerosis trials.
By Route of Administration
Parenteral administration held the largest market share in 2024, driven by its rapid onset of action and improved bioavailability in treating moderate to severe cutaneous fibrosis cases. Hospital settings frequently rely on injectable immunosuppressants and biologics for acute management. Oral therapies followed due to their ease of use and patient compliance in long-term treatment regimens. The topical route remains limited to mild cases and adjunct therapies. Rising demand for self-administration options is expected to support the development of convenient parenteral formulations, including pre-filled syringes and autoinjectors, enhancing their market penetration further.
- For instance, Actemra is administered as a 162 mg subcutaneous injection weekly or 8 mg/kg intravenous infusion every four weeks. Oral therapies support long-term disease control.
By Distribution Channel
Hospital pharmacies emerged as the leading distribution channel, contributing the largest revenue share in 2024, mainly due to the high volume of prescriptions for parenteral drugs and biologics administered in inpatient and outpatient settings. These facilities offer a controlled environment for specialized treatment protocols. Retail pharmacies ranked second, supported by the increasing adoption of oral medications for chronic management. Online pharmacies are gaining traction, particularly for repeat prescriptions and hard-to-find formulations. The growing trend toward digital health platforms and e-commerce integration is expected to boost the online segment’s growth throughout the forecast period.
Cutaneous Fibrosis Treatment Market Key Growth Drivers
Rising Prevalence of Autoimmune and Fibrotic Skin Disorders
The increasing global incidence of autoimmune disorders such as systemic sclerosis, localized scleroderma, and chronic graft-versus-host disease significantly drives demand for cutaneous fibrosis treatment. These conditions often result in progressive skin thickening, leading to both functional and cosmetic complications. According to the Scleroderma Foundation, over 300,000 individuals in the U.S. are affected by scleroderma. As awareness rises, more patients seek early medical attention, leading to higher treatment uptake. Advancements in diagnostics also contribute to earlier disease identification, particularly in moderate cases that previously went undiagnosed. Clinicians now use skin scoring systems and imaging tools more effectively, enhancing diagnosis and treatment planning. This growing patient population supports sustained growth across drug classes such as immunosuppressants and biologics. Healthcare systems in developed markets increasingly fund these therapies, strengthening adoption.
- For instance, the Scleroderma Foundation reports over 300,000 diagnosed scleroderma patients in the United States.
Advancements in Biologic Therapies and Targeted Monoclonal Antibodies
The shift toward targeted treatment approaches is a major growth factor in this market. Monoclonal antibodies and biologic agents offer improved specificity by acting on cytokines and immune pathways central to fibrosis development. Drugs such as tocilizumab (IL-6 inhibitor) and rituximab (anti-CD20) show clinical promise in improving skin symptoms in systemic sclerosis patients. Positive trial outcomes continue to expand usage beyond immunosuppressants. This growing biologic pipeline encourages investment from both established and emerging pharma companies. Regulatory bodies, including the FDA and EMA, grant orphan designations and fast-track approvals to encourage innovation. The expansion of clinical trials targeting rare fibrotic skin conditions adds to the evidence base. Biologics, though costlier, provide long-term disease control, supporting their preference in advanced or unresponsive cases. As treatment guidelines evolve, biologics are expected to capture a larger share of the therapeutic landscape.
- For instance, Roche’s Actemra reduced modified Rodnan Skin Score by 6.14 points over 48 weeks in phase III systemic sclerosis trials.
Increasing Healthcare Access and Reimbursement in Developed and Emerging Regions
Improved healthcare access, insurance coverage, and reimbursement for rare and chronic skin conditions fuel the cutaneous fibrosis treatment market. In high-income regions, national health services and private insurers cover immunosuppressants and corticosteroids, and increasingly fund high-cost monoclonal therapies. Programs such as Medicare and Medicaid in the U.S. include coverage for systemic sclerosis-related treatments, encouraging uptake among elderly and low-income patients. Meanwhile, emerging economies are investing in rare disease management infrastructure and expanding public health funding. The World Health Organization’s emphasis on skin health and disability reduction supports access to advanced care in lower-income countries. Hospital expansions and specialty dermatology clinics improve drug availability across Tier 2 and Tier 3 cities. As dermatologists and rheumatologists gain deeper disease knowledge, prescription rates rise. Collectively, these factors ensure consistent demand and expanding market penetration.
Cutaneous Fibrosis Treatment Market Key Trends & Opportunities
Rise in Clinical Trials and Research for Novel Fibrosis Pathways
The cutaneous fibrosis space is witnessing a surge in clinical trials targeting fibrotic signaling pathways, such as TGF-β, IL-13, and PDGF. These trials aim to validate next-generation drug candidates with disease-modifying potential. Biotech firms increasingly collaborate with academic institutions to explore rare cutaneous fibrosis subsets and comorbidities. Additionally, pharmaceutical pipelines now focus on dual-acting compounds that combine anti-inflammatory and antifibrotic mechanisms. This expands opportunities for personalized medicine approaches in treating skin fibrosis. Emerging biomarkers such as skin gene expression profiles and serum fibrosis markers improve patient stratification, enabling better trial designs. Increased funding from rare disease consortia and patient advocacy groups accelerates R&D timelines. As trial success rates improve, more first-in-class therapies are expected to receive regulatory approval, unlocking new commercial segments for targeted therapeutics.
- For instance, Boehringer Ingelheim’s BI 1015550 inhibits PDE4B and entered phase II trials for fibrotic diseases with twice oral dosing of 18 mg.
Digital Health Integration and Remote Patient Monitoring Tools
The integration of digital tools for monitoring skin fibrosis progression presents new market opportunities. Dermatologists now adopt imaging software, skin scoring apps, and remote consultations to manage patients in rural and underserved regions. Wearable technologies that track skin elasticity and temperature changes are being tested in academic trials. Teledermatology platforms help reduce diagnostic delays and streamline therapy follow-up, particularly in chronic or relapsing cases. Pharmaceutical companies are also leveraging mobile health apps for patient education, symptom tracking, and treatment adherence. These digital interventions support real-world evidence collection for drug efficacy, expanding post-market surveillance insights. With regulatory support for telehealth infrastructure and reimbursement in countries like the U.S., Germany, and Japan, digital health is expected to become a core component of cutaneous fibrosis disease management in the coming years.
Cutaneous Fibrosis Treatment Market Key Challenges
Limited Disease Awareness and Delayed Diagnosis
Despite increasing research, public and primary care awareness of cutaneous fibrosis remains limited. Symptoms often overlap with more common skin disorders, leading to misdiagnosis or delayed referrals to specialists. General practitioners and non-specialist clinicians may fail to recognize early-stage fibrosis, particularly in localized or pediatric cases. This diagnostic delay hampers timely treatment initiation, allowing disease progression that complicates management. Patients often receive inappropriate therapies initially, impacting outcomes and increasing costs. Rural healthcare systems and undertrained staff exacerbate this issue in developing nations. Even in advanced markets, referral wait times to rheumatologists or dermatologists may exceed six months. Addressing this challenge requires enhanced physician training, public health campaigns, and early screening programs, particularly in high-risk populations. Without systematic efforts, diagnosis lags will continue to restrict market growth.
High Cost and Limited Access to Biologic Therapies
While biologics hold strong therapeutic promise, their high cost limits accessibility for a significant portion of patients. Many monoclonal antibodies used in cutaneous fibrosis are off-label, and reimbursement frameworks may not fully support their use. Out-of-pocket expenses often deter patient adherence, especially in middle-income regions. Patent-protected drugs with limited biosimilar competition further raise cost barriers. Health systems with budget constraints prioritize cheaper corticosteroids or immunosuppressants, even when less effective in resistant cases. Logistics around cold chain storage and infusion facility requirements also limit biologic deployment in rural or under-resourced healthcare settings. Although some pharmaceutical companies offer patient support programs, these remain insufficient to ensure long-term affordability. Expanding biosimilar development, insurance coverage, and government subsidy programs will be critical to overcoming this pricing challenge.
Cutaneous Fibrosis Treatment Market Regional Analysis
North America
North America held the largest share of the Cutaneous Fibrosis Treatment market in 2024, accounting for over 38% of global revenue. The dominance stems from advanced healthcare infrastructure, high awareness levels, and access to biologic and immunosuppressive therapies. The U.S. drives regional growth with strong reimbursement support and clinical trial activity targeting systemic sclerosis and chronic graft-versus-host disease. Key pharmaceutical players maintain a strong presence through specialty distribution and hospital networks. Ongoing research into monoclonal antibodies and early adoption of digital dermatology tools continue to reinforce market leadership across North American countries.
Europe
Europe contributed approximately 27% of the global market share in 2024, led by Germany, France, and the UK. Government funding for rare disease management, strong specialist care access, and favorable reimbursement policies support sustained market growth. European countries prioritize early diagnosis and long-term patient monitoring through integrated healthcare systems. The region also benefits from robust clinical trial participation, particularly for emerging biologics and immunomodulators. Regulatory initiatives such as the European Medicines Agency’s orphan drug designations help accelerate novel therapy availability. The presence of established biopharma companies further strengthens Europe’s competitive position in the treatment of cutaneous fibrosis.
Asia Pacific
Asia Pacific accounted for over 20% of the global Cutaneous Fibrosis Treatment market in 2024 and is poised for the fastest growth through 2032. Rising prevalence of autoimmune skin diseases, expanding access to specialist care, and increasing healthcare expenditure drive regional momentum. Countries like Japan, China, South Korea, and India are witnessing growing adoption of immunosuppressants and corticosteroids. Japan leads in biologics usage, supported by strong healthcare funding. Meanwhile, China and India benefit from large patient pools and rapid urbanization. Pharmaceutical investments, domestic production of generics, and rising clinical awareness contribute to sustained demand across diverse healthcare settings.
Latin America
Latin America captured nearly 8% of the global market share in 2024, with Brazil and Mexico leading in treatment adoption. Access to cutaneous fibrosis therapies is improving due to public health investments and expanding dermatology services in urban regions. Oral and topical therapies remain dominant due to affordability and accessibility, while biologics adoption is limited by cost and reimbursement challenges. International drugmakers are gradually expanding presence through partnerships with local distributors. Awareness campaigns and diagnostic improvements are expected to support gradual market expansion. However, fragmented healthcare systems and limited access in rural areas present ongoing constraints.
Middle East & Africa
The Middle East & Africa region represented around 7% of the Cutaneous Fibrosis Treatment market in 2024. Growth remains moderate due to limited specialist care and low awareness in many parts of Sub-Saharan Africa. However, the GCC countries especially the UAE and Saudi Arabia are investing heavily in specialty hospitals and rare disease centers. High-income urban populations in these markets are driving demand for parenteral and biologic therapies. Public-private partnerships and government-backed healthcare reforms are improving access to immunosuppressive treatments. Efforts to expand telemedicine and mobile health clinics may help address rural care gaps in the coming years.
Cutaneous Fibrosis Treatment Market Segmentations:
By Drug:
- Immunosuppressants
- Corticosteroids
- Monoclonal Antibody
- Others
By Route of Administration:
- Parenteral
- Oral
- Topical
By Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Cutaneous Fibrosis Treatment Market Competitive Landscape
The competitive landscape of the Cutaneous Fibrosis Treatment market is characterized by the presence of global pharmaceutical leaders and emerging biotech firms actively focused on immunomodulators and biologic therapies. Companies such as Novartis AG, Pfizer, Sanofi, AbbVie, and Amgen dominate with extensive portfolios targeting autoimmune and fibrotic disorders. F. Hoffmann-La Roche (Genentech) and Bristol-Myers Squibb continue to invest in monoclonal antibodies and pipeline assets targeting fibrosis-related cytokines. Johnson & Johnson, Merck & Co., and GlaxoSmithKline strengthen their position through strategic R&D alliances and regulatory approvals in rare disease spaces. Niche players like LEO Pharma, Actelion Pharmaceuticals, and Horizon Therapeutics focus on specialized treatment formulations and skin-specific fibrosis therapies. Competitive intensity remains high as firms race to secure orphan drug designations, expand clinical trials, and gain faster market entry. Strong emphasis on biologics, favorable reimbursement, and expanding access to specialty care are expected to shape market dynamics over the coming years.
Key Player Analysis
- Teva Pharmaceuticals
- Amgen
- Sanofi
- Pfizer
- Johnson & Johnson Services
- Actelion Pharmaceuticals
- LEO Pharma
- GlaxoSmithKline
- Hoffmann-La Roche (Genentech, Inc.)
- AbbVie
- Horizon Therapeutics USA, Inc.
- Jubilant Cadista
- Bristol-Myers Squibb Company
- Boehringer Ingelheim International GmbH
- Bayer
- Merck & Co.
- Novartis AG
Recent Developments
- In June 2024, Researchers at the University of Texas at El Paso developed a new therapeutic approach using nanoparticles to target and rehabilitate cells responsible for fibrosis. This method aims to modify cells to prevent excess collagen production, showing promising results in treating skin and lung fibrosis.
- In March 2024, Mirador Therapeutics, Inc. secured over USD 400.0 million to drive the development of precision medicines for immune-related disorders, including immune-mediated inflammatory and fibrotic diseases, representing a remarkable and uncommon early-stage fundraising milestone.
- In October 2023, Kyverna Therapeutics announced that the FDA has granted clearance for the investigative use of KYV-101 in the treatment of scleroderma.
Report Coverage
The research report offers an in-depth analysis based on Drug, Route of Administration, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Biologic therapies will gain wider adoption due to targeted action and long-term disease control.
- Monoclonal antibodies will expand in usage with new approvals for skin-specific fibrotic indications.
- Early diagnosis tools and biomarker-based screening will support faster treatment initiation.
- Clinical trials for novel antifibrotic agents will increase across rare and chronic skin fibrosis types.
- Oral immunosuppressants will remain dominant for long-term therapy due to patient convenience.
- Hospital pharmacies will continue leading distribution, supported by rising parenteral therapy use.
- Digital tools and teledermatology will enhance patient monitoring and improve access in underserved areas.
- North America will maintain dominance, while Asia Pacific will grow fastest due to improving healthcare access.
- Pricing pressure on biologics will increase demand for biosimilars and cost-effective options.
- Key players will invest in rare disease segments, focusing on expanded labels and orphan drug status.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Autoimmune and Fibrotic Skin Disorders
The increasing incidence of conditions such as systemic sclerosis and chronic graft-versus-host disease is expanding the patient pool for cutaneous fibrosis treatments, driving demand for both established and novel therapies.
Advancements in Biologic Therapies and Monoclonal Antibodies
The development and approval of targeted biologics and monoclonal antibodies, which offer improved efficacy and disease control, are expanding treatment options and encouraging adoption, especially for patients unresponsive to traditional therapies.
Improved Healthcare Access and Reimbursement
Enhanced insurance coverage and reimbursement policies in developed and emerging markets are making high-cost therapies, including biologics, more accessible, thereby supporting market growth and broader patient reach.
Expansion of Clinical Trials and Research in Novel Pathways
A surge in clinical research targeting new fibrotic pathways and the introduction of innovative drug candidates are increasing the pipeline of potential treatments, attracting investment and accelerating market expansion.
Integration of Digital Health and Remote Monitoring
The adoption of teledermatology, digital monitoring tools, and mobile health platforms is improving early diagnosis, patient adherence, and long-term management, particularly in underserved and rural regions, thus supporting market penetration.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Cutaneous Fibrosis Treatment market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cutaneous Fibrosis Treatment market projected to grow between 2024 and 2032?
Which Cutaneous Fibrosis Treatment market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cutaneous Fibrosis Treatment market?
Who are the leading companies in the Cutaneous Fibrosis Treatment market?
Which region commanded the largest share of the Cutaneous Fibrosis Treatment market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug
- 1.2.1 Immunosuppressants
- 1.2.2 Corticosteroids
- 1.2.3 Monoclonal Antibody
- 1.2.4 Others
- 1.3 By Route of Administration
- 1.3.1 Parenteral
- 1.3.2 Oral
- 1.3.3 Topical
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 701 million → 2032: USD 1,201.96 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cutaneous Fibrosis Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cutaneous Fibrosis Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cutaneous Fibrosis Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cutaneous Fibrosis Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cutaneous Fibrosis Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cutaneous Fibrosis Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cutaneous Fibrosis Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cutaneous Fibrosis Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 701 million → 2032: USD 1,201.96 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cutaneous Fibrosis Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Immunosuppressants
- 12.3.7.2 Corticosteroids
- 12.3.7.3 Monoclonal Antibody
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Parenteral
- 12.4.7.2 Oral
- 12.4.7.3 Topical
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cutaneous Fibrosis Treatment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cutaneous Fibrosis Treatment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cutaneous Fibrosis Treatment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Novartis AG
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Pfizer
- 17.4 Sanofi
- 17.5 F. Hoffmann-La Roche (Genentech)
- 17.6 AbbVie
- 17.7 Amgen
- 17.8 Bristol-Myers Squibb
- 17.9 Johnson & Johnson Services
- 17.10 GlaxoSmithKline
- 17.11 Merck & Co.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

