
Market Overview
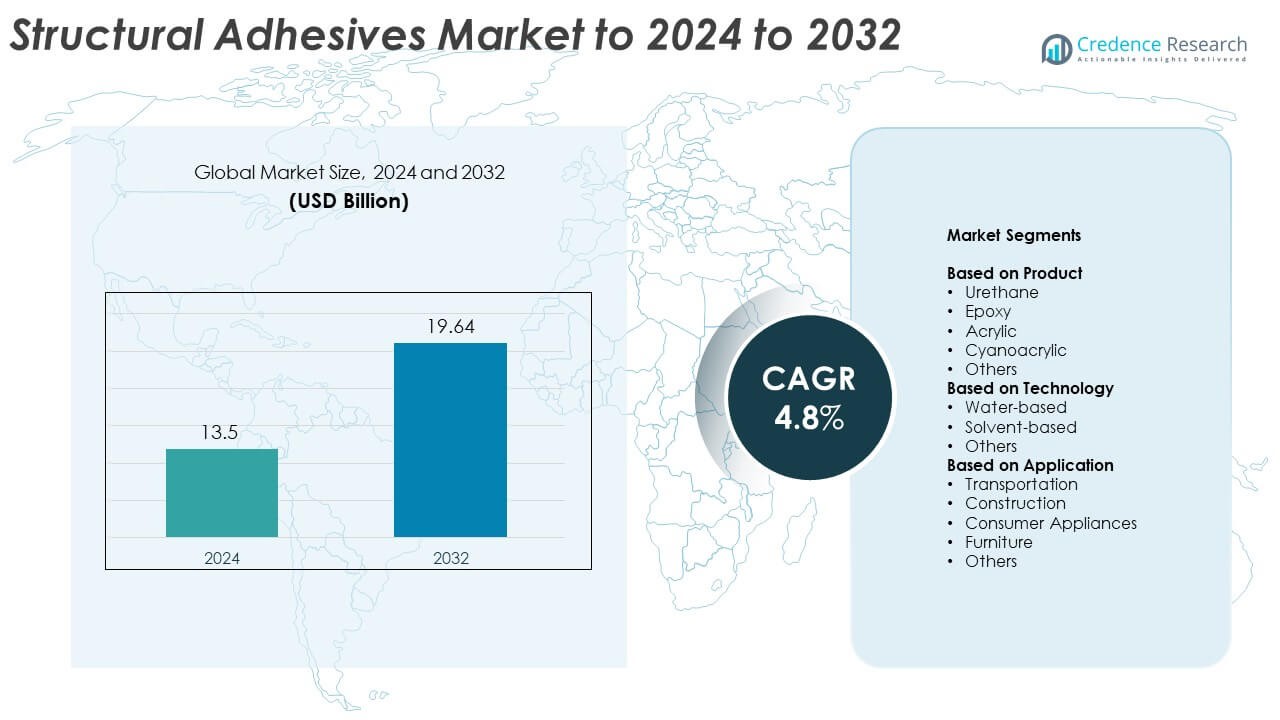
Structural Adhesives Market size was valued at USD 13.5 Billion in 2024 and is anticipated to reach USD 19.64 Billion by 2032, at a CAGR of 4.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Structural Adhesives Market Size 2024 | USD 13.5 Billion |
| Structural Adhesives Market, CAGR | 4.8% |
| Structural Adhesives Market Size 2032 | USD 19.64 Billion |
The structural adhesives market includes major players such as Arkema S.A., Scott Bader Co., HB Fuller Company, 3M, Ashland Global Specialty Chemicals Inc., Franklin International, Inc., Lord Corporation, Dow, Henkel AG & Co. KGaA, and Avery Dennison Corporation. These companies strengthen the market through innovation in high-performance bonding, sustainable formulations, and advanced curing technologies. North America leads the global market with about 32% share due to strong automotive, aerospace, and construction demand. Europe follows with nearly 28% share, supported by stringent environmental standards and advanced engineering industries, while Asia Pacific shows rapid expansion driven by manufacturing growth.
Market Insights
- The structural adhesives market reached USD 13.5 Billion in 2024 and is projected to hit USD 19.64 Billion by 2032, expanding at a CAGR of 4.8% during the forecast period.
- Rising demand for lightweight materials in automotive, aerospace, and transportation drives strong adoption, with the urethane segment leading the product category at about 36% share in 2024.
- Water-based technology continues to gain traction as a key trend due to tightening environmental regulations and rising preference for low-VOC, sustainable adhesive solutions across industries.
- The market remains moderately consolidated, with leading companies focusing on hybrid chemistries, faster curing systems, and automation-ready formulations to enhance performance in high-volume manufacturing.
- North America leads with around 32% share, followed by Europe at nearly 28%, while Asia Pacific accounts for about 30% and shows the fastest growth due to expanding automotive, electronics, and construction activities.
Market Segmentation Analysis:
By Product
Urethane leads the product segment with about 36% share in 2024 due to strong bonding flexibility, high impact resistance, and broad compatibility with metals, plastics, and composites. The urethane category grows as manufacturers in automotive and construction prefer durable adhesives that withstand vibration and thermal stress. Epoxy follows due to superior structural strength, while acrylic and cyanoacrylic gain steady use in fast-curing applications. Other product types serve niche needs where chemical resistance and specific material bonding are required.
- For instance, Arkema’s Bostik plant in Columbus, Ohio, has a total annual production capacity of up to 100 million pounds of specialty adhesives, which are used to produce products for food packaging (laminating flexible films) and wood bonding (engineered wood products, flooring, windows, and doors) customers.
By Technology
Water-based structural adhesives dominate this segment with nearly 42% share in 2024 because industries are shifting to low-VOC, environmentally safer formulations. Growth accelerates as regulators promote eco-friendly bonding solutions across transportation, furniture, and construction. Solvent-based adhesives remain relevant in heavy-duty and high-temperature applications, but adoption slows due to stricter emission rules. Other technologies, including reactive systems and hybrid chemistries, expand as manufacturers seek stronger adhesion with reduced curing time.
- For instance, Henkel’s Adhesive Technologies Innovation Center in Düsseldorf spans about 47,000 square meters. The site hosts more than 650 experts developing new water-based and low-emission adhesive systems.
By Application
Transportation holds the dominant position with about 38% share in 2024 due to rising use of lightweight materials in automotive, aerospace, rail, and marine sectors. Structural adhesives replace welding and mechanical fasteners as OEMs seek higher fatigue resistance and better design flexibility. Construction follows with increasing demand for high-strength bonding in panels, facades, and infrastructure components. Consumer appliances, furniture, and other applications grow steadily as manufacturers aim for quieter operation, improved aesthetics, and reduced assembly time.
Key Growth Drivers
Rising Demand for Lightweight Materials
The shift toward lightweight components in automotive, aerospace, and transportation sectors drives strong adoption of structural adhesives. Manufacturers replace mechanical fasteners to reduce vehicle weight, enhance fuel efficiency, and improve crash performance. Adhesives support bonding of composites, aluminum, and engineered plastics, enabling advanced design flexibility. This transition accelerates as OEMs align with global emission targets and efficiency mandates. The trend strengthens multi-material assembly needs, making lightweight construction the leading growth driver in the structural adhesives market.
- For instance, the BMW i3 features a LifeDrive architecture, where the CFRP (carbon-fiber–reinforced plastic) "Life module" (the passenger cell) sits on an aluminum "Drive module" (chassis, battery, and powertrain). The passenger compartment structure is comprised of around 150 CFRP parts.
Expansion in Construction and Infrastructure Projects
Global infrastructure investment boosts demand for high-strength bonding solutions across residential, commercial, and industrial projects. Structural adhesives support durable connections in facades, panels, flooring, and modular structures. Rising urbanization and large-scale smart city development further accelerate usage. Builders prefer adhesive bonding over welding due to faster installation, reduced labor cost, and enhanced design freedom. This consistent need for reliable and long-lasting adhesion makes construction activity a major driver in the structural adhesives market.
- For instance, as of the end of 2023, the Mapei Group operated in 57 countries, with 96 subsidiaries and 93 production plants Mapei 2023 Consolidated Financial Statements.
Growth of Consumer Appliances and Electronics Manufacturing
Rapid expansion of appliance and electronics production strengthens adhesive consumption, particularly in compact and lightweight device assembly. Adhesives support vibration damping, thermal stability, and aesthetic surface bonding, which improve product durability and design quality. Manufacturers rely on advanced formulations to bond plastics, glass, and metal components without visible joints. Increasing consumer demand for efficient and stylish home appliances keeps structural adhesives essential in assembly lines, making this segment a significant growth driver.
Key Trends and Opportunities
Adoption of Sustainable and Low-VOC Formulations
A major trend shaping the market is the rapid move toward eco-friendly, low-VOC, and water-based adhesive technologies. Manufacturers innovate to meet strict environmental regulations and rising customer preference for safer materials. Investments in bio-based and hybrid chemistries offer new opportunities for durable yet sustainable bonding. This shift encourages adoption in automotive, furniture, and construction applications, where sustainability standards continue to tighten. The transition to greener solutions creates long-term growth potential for high-performance adhesive formulations.
- For instance, Avery Dennison’s 2023 CDP Climate filing describes science-based targets for its adhesive businesses. Targets cut Scope 1 and 2 emissions from 2015 levels and pursue net-zero by 2050.
Expansion of Automation and Advanced Manufacturing
Increasing automation across automotive, electronics, and appliance sectors creates strong opportunities for structural adhesives tailored for robotic application. Consistent dispensing, fast curing, and high strength make adhesives ideal for automated assembly lines. Companies seek formulations compatible with precision manufacturing to improve cycle time and reliability. This trend grows as industries adopt Industry 4.0 technologies. The shift enables greater production efficiency and expands adhesive use in next-generation manufacturing environments.
- For instance, FANUC announced in 2023 that its cumulative industrial robot shipments reached 1 million units.
Key Challenges
Fluctuating Raw Material Prices
Volatility in petrochemical-based raw materials affects structural adhesive production costs and profit margins. Manufacturers face supply instability for key ingredients such as polyols, isocyanates, and epoxy resins. Global disruptions, geopolitical tensions, and energy price swings intensify this challenge. Price fluctuations make long-term planning difficult for adhesive producers and end-users. Companies often seek alternative formulations or diversify sourcing to reduce dependency, but cost pressure remains a major constraint in the structural adhesives market.
Performance Limitations in Extreme Conditions
Structural adhesives face challenges when exposed to extreme temperatures, high humidity, or harsh chemicals, which may weaken bond strength. Applications in aerospace, automotive under-the-hood systems, and heavy industrial environments demand exceptional durability. Some adhesive types still struggle to meet these rigorous standards, leading manufacturers to rely on mechanical fastening or hybrid bonding in critical zones. Continued R&D is required to overcome these performance gaps and expand adoption in high-stress applications.
Regional Analysis
North America North America holds about 32% share of the structural adhesives market in 2024 due to strong demand from automotive, construction, aerospace, and appliance manufacturing. The United States dominates regional consumption as OEMs adopt advanced bonding solutions for lightweight vehicles and high-performance industrial products. Growth continues with rising investments in infrastructure renovation and energy-efficient building materials. Canada adds steady demand through construction upgrades and machinery production. Expanding use of composites and the shift toward low-VOC formulations further enhance adoption across major industries.
Europe
Europe accounts for nearly 28% share, supported by strong automotive production, thriving aerospace operations, and advanced engineering industries. Germany, France, Italy, and the United Kingdom remain key contributors as manufacturers shift to lightweight materials and adopt high-strength bonding technologies. Stringent environmental regulations accelerate demand for water-based and low-VOC adhesives across construction and transportation segments. The region’s renewable energy expansion, including wind turbine components, further boosts usage. Ongoing industrial modernization and sustainability goals keep Europe a major market.
Asia Pacific
Asia Pacific leads growth momentum with around 30% share in 2024, driven by rapid industrialization and large-scale manufacturing across China, India, Japan, and South Korea. The region benefits from expanding automotive production, electronics assembly, and infrastructure development. China remains the largest consumer as factories adopt structural adhesives to improve efficiency and reduce assembly costs. Rising disposable income and growing appliance demand also support uptake. Government initiatives promoting energy-efficient buildings and electric vehicle production strengthen regional expansion.
Latin America
Latin America holds close to 6% share, driven by steady growth in construction, automotive assembly, and consumer goods production. Brazil and Mexico remain the primary markets as manufacturers adopt adhesives in vehicle components, household appliances, and industrial equipment. Increasing investments in infrastructure, residential housing, and commercial facilities support regional consumption. Adoption grows as industries shift from mechanical fasteners to high-strength adhesive bonding for cost efficiency and improved product durability. Economic recovery and manufacturing expansion help maintain stable demand.
Middle East and Africa
Middle East and Africa capture about 4% share in 2024, supported by rising construction projects, infrastructure expansion, and growing automotive and industrial activities. The United Arab Emirates and Saudi Arabia lead adoption with large-scale commercial developments and rising demand for durable bonding solutions in building materials. South Africa contributes through automotive assembly and consumer appliance production. Although the market is smaller compared with other regions, increasing industrial diversification and investment in manufacturing strengthen long-term opportunities.
Market Segmentations:
By Product
- Urethane
- Epoxy
- Acrylic
- Cyanoacrylic
- Others
By Technology
- Water-based
- Solvent-based
- Others
By Application
- Transportation
- Construction
- Consumer Appliances
- Furniture
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the structural adhesives market features key players such as Arkema S.A., Scott Bader Co., HB Fuller Company, 3M, Ashland Global Specialty Chemicals Inc., Franklin International, Inc., Lord Corporation, Dow, Henkel AG & Co. KGaA, and Avery Dennison Corporation. The market remains moderately consolidated, with companies focusing on product innovation, sustainable formulations, and advanced bonding technologies to meet evolving industrial needs. Many manufacturers invest in low-VOC and water-based solutions as environmental regulations tighten worldwide. Strategic partnerships with automotive, aerospace, construction, and appliance manufacturers support long-term growth. Firms also expand their portfolios through R&D in hybrid chemistries that improve curing efficiency and bond strength. Capacity expansion in high-demand regions and investments in automated adhesive dispensing systems further enhance competitiveness. As industries shift toward lightweight materials and multi-substrate bonding, companies strengthen their technical support and application expertise to maintain market position.
Key Player Analysis
- Arkema S.A.
- Scott Bader Co.
- HB Fuller Company
- 3M
- Ashland Global Specialty Chemicals Inc.
- Franklin International, Inc.
- Lord Corporation
- Dow
- Henkel AG & Co. KGaA
- Avery Dennison Corporation
Recent Developments
- In 2025, Dow announced the launch of an advanced structural epoxy adhesive designed for high-temperature and high-load applications
- In 2023, Bostik, a worldwide adhesive expert, introduced its new Thermal Conductive Adhesives (TCA) range at the India Battery Show. Bostik and Polytec PT collaborated to create a new TCA series that addresses the thermal management challenges of the latest Cell-to-Pack (CTP) battery designs.
- In 2023, Scott Bader launched two advanced sandable structural adhesives, Crestabond M1-60HV/2 and M1-90HV/2, designed to meet demanding bonding needs in various assembly operations
Report Coverage
The research report offers an in-depth analysis based on Product, Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow as industries shift toward lightweight materials in automotive and aerospace.
- Water-based and low-VOC adhesives will gain faster adoption due to stricter regulations.
- Demand from electric vehicle manufacturing will rise with increased use of multi-material structures.
- Automation in assembly lines will boost the need for adhesives compatible with robotic application.
- Construction activity will expand usage in facades, panels, and modular building systems.
- Advancements in hybrid chemistries will improve strength, flexibility, and curing performance.
- Appliance and electronics production will drive higher consumption for compact device assembly.
- Improved bonding solutions for extreme temperatures will open new industrial applications.
- Sustainability goals will encourage adoption of bio-based adhesive formulations.
- Global manufacturing expansion will create strong demand across emerging economies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Lightweight Materials in Transportation
Automotive, aerospace, and rail industries are increasingly adopting lightweight materials to improve fuel efficiency and meet emission targets. Structural adhesives enable the bonding of composites, aluminum, and engineered plastics, replacing mechanical fasteners and supporting advanced design flexibility.
Expansion in Construction and Infrastructure Projects
Global investments in residential, commercial, and industrial infrastructure are driving demand for high-strength bonding solutions. Structural adhesives offer faster installation, reduced labor costs, and durable connections in panels, facades, and modular structures, making them essential in modern construction.
Adoption of Water-Based and Low-VOC Adhesives
Stricter environmental regulations and growing preference for sustainable solutions are accelerating the shift to water-based and low-VOC adhesive technologies. These formulations reduce emissions and health risks, supporting their adoption across transportation, construction, and consumer goods manufacturing.
Growth in Consumer Appliances and Electronics Manufacturing
The rapid expansion of appliance and electronics production increases the need for advanced adhesives that provide vibration damping, thermal stability, and aesthetic bonding. Structural adhesives enable compact, lightweight device assembly and improved product durability, fueling market growth.
Advancements in Automation and Hybrid Chemistries
The rise of automated manufacturing and Industry 4.0 technologies is boosting demand for adhesives compatible with robotic application and fast curing. Innovations in hybrid chemistries further enhance bond strength and flexibility, supporting high-volume, precision assembly lines.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Structural Adhesives Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Structural Adhesives Market projected to grow between 2025 and 2032?
Which Structural Adhesives Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Structural Adhesives Market?
Who are the leading companies in the Structural Adhesives Market?
Which region commanded the largest share of the Structural Adhesives Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Urethane
- 1.2.2 Epoxy
- 1.2.3 Acrylic
- 1.2.4 Cyanoacrylic
- 1.2.5 Others
- 1.3 By Technology
- 1.3.1 Water-based
- 1.3.2 Solvent-based
- 1.3.3 Others
- 1.4 By Application
- 1.4.1 Transportation
- 1.4.2 Construction
- 1.4.3 Consumer Appliances
- 1.4.4 Furniture
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 13.5 Billion → 2032: USD 19.64 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Structural Adhesives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Structural Adhesives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Structural Adhesives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Structural Adhesives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Structural Adhesives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Structural Adhesives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Structural Adhesives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Structural Adhesives Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 13.5 Billion → 2032: USD 19.64 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Structural Adhesives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Urethane
- 12.3.7.2 Epoxy
- 12.3.7.3 Acrylic
- 12.3.7.4 Cyanoacrylic
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Water-based
- 12.4.7.2 Solvent-based
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Transportation
- 12.5.7.2 Construction
- 12.5.7.3 Consumer Appliances
- 12.5.7.4 Furniture
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Structural Adhesives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Structural Adhesives Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Structural Adhesives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Structural Adhesives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arkema S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Scott Bader Co.
- 18.4 HB Fuller Company
- 18.5 3M
- 18.6 Ashland Global Specialty Chemicals Inc.
- 18.7 Franklin International, Inc.
- 18.8 Lord Corporation
- 18.9 Dow
- 18.10 Henkel AG & Co. KGaA
- 18.11 Avery Dennison Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

