
Market overview
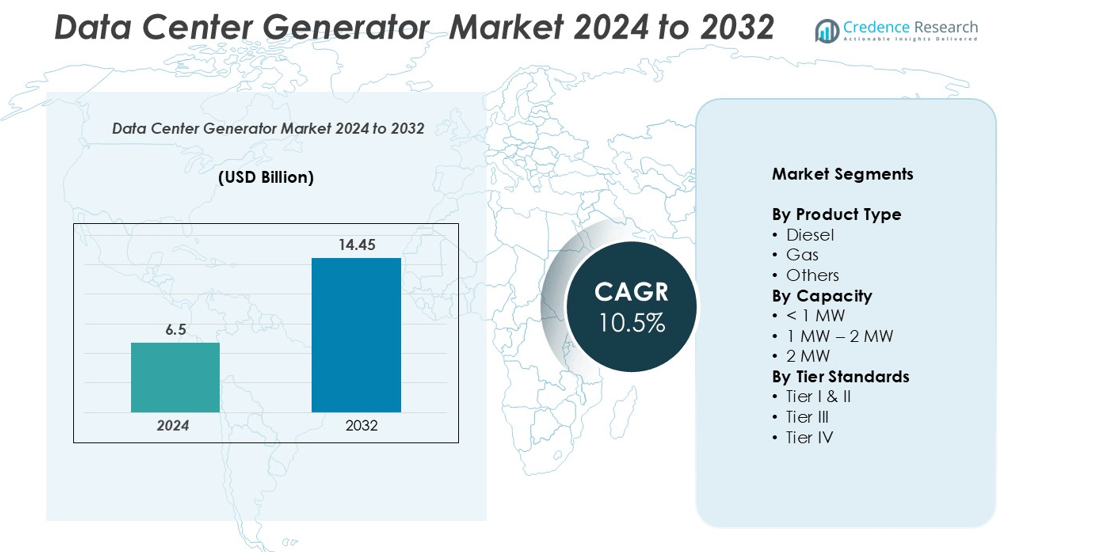
The data center generator market size was valued at USD 6.5 billion in 2024 and is anticipated to reach USD 14.45 billion by 2032, at a CAGR of 10.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Data Center Generator Market Size 2024 | USD 6.5 billion |
| Data Center Generator Market, CAGR | 10.5% |
| Data Center Generator Market Size 2032 | USD 14.45 billion |
The global data center generator market is led by major players such as Caterpillar, Cummins Inc., KOHLER, Generac Power Systems, Inc., and Rolls-Royce plc, which collectively account for a significant share of the market due to their strong technological capabilities and extensive product portfolios. Other notable participants include Atlas Copco, HIMOINSA, MITSUBISHI MOTORS CORPORATION, Piller (Langley Holdings plc), and Eurodiesel Services, focusing on energy-efficient and low-emission generator solutions. North America emerged as the leading regional market in 2024, holding over 35% of the global share, driven by the high concentration of hyperscale data centers and advanced backup power infrastructure.
Market Insights
- The global data center generator market was valued at USD 6.5 billion in 2024 and is projected to reach USD 14.45 billion by 2032, growing at a CAGR of 10.5% during the forecast period.
- Growing data center construction, increasing demand for uninterrupted power supply, and rising investments in hyperscale and edge facilities are driving market growth globally.
- Key trends include the adoption of low-emission gas generators, integration of smart monitoring systems, and a shift toward sustainable and hybrid energy solutions to meet carbon-neutral goals.
- The market is moderately consolidated, with Caterpillar, Cummins Inc., KOHLER, and Rolls-Royce plc dominating, while new entrants focus on regional expansion and advanced product innovation.
- North America leads with over 35% market share, followed by Asia-Pacific (30%) and Europe (25%); by segment, diesel generators and >2 MW capacity units hold the largest shares due to reliability and high power demand.
Market Segmentation Analysis:
By Product Type:
The data center generator market by product type is segmented into diesel, gas, and others. The diesel generator segment dominated the market in 2024, accounting for the largest revenue share of over 65%, owing to its high reliability, quick start capability, and suitability for large-scale data centers requiring uninterrupted power backup. Diesel generators are preferred for their robust performance during grid outages and lower upfront costs. However, the gas generator segment is expected to witness significant growth, driven by the rising focus on sustainability and stricter emission regulations promoting cleaner energy alternatives.
- For instance, Caterpillar's large diesel engines and generator sets, with a power output generally ranging from 1,000 to over 6,000 horsepower, are manufactured at their facility in Lafayette, Indiana. The main manufacturing building is approximately 1.3 million square feet within a larger campus of about 1.6 million square feet, and the site currently employs around 1,900 people with a recent expansion expected to add more jobs.
By Capacity:
Based on capacity, the market is categorized into <1 MW, 1 MW–2 MW, and >2 MW. The >2 MW segment held the dominant market share exceeding 45% in 2024, as hyperscale and large enterprise data centers demand high-capacity generators to ensure seamless operations. Increasing data traffic, cloud expansion, and growing adoption of AI-driven workloads are propelling demand for high-capacity power systems. Meanwhile, the 1 MW–2 MW category is projected to expand steadily due to the rising number of medium-sized data centers and colocation facilities prioritizing energy efficiency and operational reliability.
- For instance, Generac's new product lineup includes five generators ranging from 2.25 MW to 3.25 MW, available in both diesel and natural gas configurations, tailored for hyperscale, colocation, enterprise, and edge environments.
By Tier Standards:
In terms of tier standards, the market is divided into Tier I & II, Tier III, and Tier IV. The Tier III segment led the market with a share of more than 50% in 2024, supported by the growing construction of Tier III data centers offering high availability and redundant power systems. These facilities balance cost and uptime requirements, making them the preferred choice for enterprises and colocation providers. The Tier IV segment is expected to grow rapidly as hyperscale operators invest in fault-tolerant infrastructure with 99.995% uptime to support mission-critical applications and advanced digital services.
Key Growth Drivers
Rising Data Center Construction Worldwide
The rapid expansion of data centers globally is a major driver of the data center generator market. Increasing digital transformation, cloud computing adoption, and the surge in data consumption from AI, IoT, and edge computing applications have intensified the demand for reliable backup power systems. Hyperscale data centers, in particular, require high-capacity generators to ensure seamless operations during grid failures. Moreover, governments and enterprises are heavily investing in IT infrastructure to enhance data security and storage capabilities. This rise in construction activities across North America, Europe, and Asia-Pacific continues to fuel generator demand, ensuring operational continuity and reducing downtime risks.
- For instance, in 2025, Big Tech companies-primarily Amazon-led a significant data center construction boom in Virginia, filing permits for 54 new facilities in the state so far this year (as of reports published mid-year), an amount which would raise Amazon's global data center count by nearly 16% annually.
Growing Need for Uninterrupted Power Supply
Data centers require consistent and uninterrupted power to prevent data loss, operational disruptions, and hardware damage. Power outages, even for a few minutes, can result in significant financial losses and reputational damage for operators. Generators play a critical role in maintaining uptime by providing reliable backup during grid instability or natural disasters. The increasing dependency of businesses on cloud-based operations, online services, and digital communication drives the adoption of robust power backup systems. This necessity for continuous power availability, especially in colocation and hyperscale facilities, is propelling steady growth in the data center generator market.
- For instance, in 2024, AVK, in partnership with the Power Systems division of Rolls-Royce (under the mtubrand), sold and delivered over 500 generators powered by HVO to the data center sector, providing nearly 1.3 gigawatts of standby power capacity.
Increasing Investments in Hyperscale and Edge Data Centers
The proliferation of hyperscale and edge data centers is creating strong demand for efficient and scalable power solutions. Hyperscale facilities require multiple high-capacity generators to support extensive IT loads, while edge data centers need compact and efficient units for decentralized operations. The growing integration of AI, 5G, and IoT technologies accelerates the need for low-latency data processing, which in turn boosts regional data center deployment. These developments are increasing investments in advanced generator technologies that offer high fuel efficiency, reduced emissions, and improved load management, driving significant growth across developed and emerging markets.
Key Trends & Opportunities
Shift Toward Sustainable and Low-Emission Generators
The global emphasis on sustainability is driving a notable shift toward low-emission and eco-friendly data center generators. Traditional diesel generators are being gradually replaced or supplemented by natural gas, bi-fuel, and hybrid systems that reduce carbon footprints. Market players are investing in technologies that improve fuel efficiency, enable renewable energy integration, and comply with stringent environmental standards. This transition aligns with the sustainability goals of major cloud providers and colocation operators aiming for carbon neutrality. Consequently, the adoption of cleaner power solutions presents a lucrative opportunity for manufacturers developing next-generation green generator technologies.
- For instance, Rolls-Royce's mtu Series 4000 generator sets, each with a maximum output of 2,640 kVA, were installed in the European Commission's Jean Monnet 2 building in Luxembourg to provide emergency backup power.
Integration of Digital Monitoring and Smart Control Systems
The growing adoption of digital monitoring and smart control systems is transforming generator management in data centers. Advanced technologies, including IoT-enabled sensors, predictive maintenance software, and AI-based analytics, allow real-time tracking of generator performance, fuel consumption, and maintenance needs. These solutions enhance operational efficiency, reduce downtime, and lower maintenance costs. The increasing demand for automation and remote management, particularly in hyperscale and multi-site data centers, presents new opportunities for generator manufacturers to offer value-added digital solutions and service-based business models, improving reliability and customer satisfaction.
- For instance, Cummins' PowerCommand Cloud™ system enables remote monitoring of generator sets, transfer switches, and auxiliary power system components, providing real-time information and critical notifications to operators
Key Challenges
Environmental Concerns and Emission Regulations
Stringent environmental regulations related to emissions and noise pollution pose a significant challenge for the data center generator market. Diesel generators, which dominate the sector, emit carbon dioxide, nitrogen oxides, and particulate matter, leading to compliance issues in regions with strict environmental laws. Regulatory bodies are enforcing limits on backup generator usage and mandating cleaner technologies. Manufacturers must invest heavily in R&D to develop eco-friendly alternatives, such as gas-based or hybrid generators, which can increase operational costs. Balancing performance with sustainability remains a critical challenge for industry participants.
High Initial Investment and Maintenance Costs
The high capital investment required for installing and maintaining data center generators is another major challenge. Large-scale data centers often need multiple high-capacity units to ensure redundancy, significantly raising upfront costs. In addition, ongoing maintenance, fuel expenses, and compliance testing add to the total cost of ownership. For small and medium-sized enterprises, these expenses can be a financial burden. Moreover, the need for skilled technicians and continuous monitoring further elevates operational costs. Addressing these cost-related challenges through modular designs, fuel-efficient technologies, and service-based models is essential for sustained market growth.
Regional Analysis
North America:
North America dominated the data center generator market in 2024, accounting for over 35% of the global share, driven by the high concentration of hyperscale and colocation data centers in the United States. Major cloud service providers, such as Amazon Web Services, Microsoft, and Google, are expanding their facilities to meet growing digital demands. The region’s frequent power disruptions and stringent uptime requirements further increase the adoption of advanced backup power systems. Additionally, strong investments in green data centers and renewable-powered backup solutions are enhancing market growth across the U.S. and Canada.
Europe:
Europe held a market share of around 25% in 2024, supported by the rapid expansion of data center infrastructure in countries such as Germany, the U.K., and the Netherlands. The region’s growing focus on sustainability and strict environmental regulations are accelerating the shift toward low-emission and gas-powered generators. The rising adoption of cloud computing, digital transformation initiatives, and edge data centers further strengthen demand. Moreover, the integration of smart monitoring systems and hybrid energy models is gaining traction, aligning with Europe’s push for carbon-neutral data center operations by 2030.
Asia-Pacific:
The Asia-Pacific region captured 30% of the market share in 2024 and is expected to witness the fastest growth during the forecast period. Rapid digitalization, expanding IT infrastructure, and government-led data localization policies are driving large-scale data center developments in China, India, Japan, and Singapore. The rising demand for hyperscale facilities and the increasing presence of global cloud providers are boosting generator installations. Additionally, frequent power outages in developing economies emphasize the need for reliable backup power, while manufacturers are investing in localized production to meet the region’s growing requirements.
Latin America:
Latin America accounted for 6% of the global market share in 2024, with Brazil and Mexico leading regional growth. The increasing adoption of cloud computing, digital banking, and e-commerce is driving the establishment of new data centers. However, inconsistent grid reliability and infrastructure challenges have heightened reliance on backup generators. Global players are partnering with regional operators to expand capacity and deploy energy-efficient generator systems. Furthermore, favorable government policies promoting IT infrastructure investments are expected to strengthen the market outlook in the coming years.
Middle East & Africa:
The Middle East & Africa region represented 4% of the market share in 2024, fueled by rapid digital transformation and data center investments in the UAE, Saudi Arabia, and South Africa. The growing deployment of hyperscale and colocation facilities to support cloud and AI-driven services is increasing the demand for reliable power backup systems. Frequent power instability in certain areas further supports generator adoption. Additionally, ongoing smart city projects and expanding telecom infrastructure are creating new opportunities for generator manufacturers focused on high-performance and fuel-efficient solutions.
Market Segmentations:
By Product Type
- Diesel
- Gas
- Others
By Capacity
- < 1 MW
- 1 MW – 2 MW
- 2 MW
By Tier Standards
- Tier I & II
- Tier III
- Tier IV
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Afric
Competitive Landscape
The data center generator market is highly competitive, with several global and regional players focusing on technological innovation, product efficiency, and strategic partnerships to strengthen their market presence. Key companies such as Caterpillar, Cummins Inc., KOHLER, Generac Power Systems, and Rolls-Royce plc dominate the market, offering a wide range of high-performance diesel and gas generators tailored for hyperscale and enterprise data centers. These players emphasize advanced control systems, reduced emissions, and improved fuel efficiency to meet evolving regulatory and sustainability requirements. Emerging companies like HIMOINSA, Atlas Copco, and Eurodiesel Services are expanding through localized manufacturing and service support. Strategic initiatives, including collaborations with data center developers, R&D investments in hybrid systems, and the integration of digital monitoring technologies, are driving competitive differentiation. The market is expected to witness intensified competition as players focus on eco-friendly and modular generator solutions to align with global carbon-neutral targets.
Key Player Analysis
- Atlas Copco
- Caterpillar
- Cummins, Inc.
- Eurodiesel Services
- Generac Power Systems, Inc.
- HIMOINSA
- KOHLER
- MITSUBISHI MOTORS CORPORATION
- Piller (Langley Holdings plc)
- Rolls Royce plc
Recent Developments
- In January 2023, EdgeCloudLink launched off-grid, hydrogen-powered modular data centers using 3D printing, featuring 1MW units, liquid cooling, and diesel-free sustainable operations in Mountain View.
- In May 2023, Kohler Power Systems released a web-based Power Solutions Center, providing generator sizing, BIM files, drawings, and performance data directly via KohlerPower.com.
- In April 2025, Neysa Networks and NTT Data signed an agreement with the Telangana government to develop an AI data center cluster facility in Hyderabad, India, with a capacity of 400 MW
Report Coverage
The research report offers an in-depth analysis based on Product Type, Capacity, Tier Standards and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The data center generator market will continue to grow steadily, driven by the rising global demand for reliable backup power.
- Expansion of hyperscale and edge data centers will create strong opportunities for high-capacity generator installations.
- Manufacturers will increasingly adopt sustainable technologies, focusing on low-emission and hybrid generator systems.
- Integration of smart monitoring and predictive maintenance will enhance generator efficiency and uptime.
- Gas and bi-fuel generators will gain traction as operators shift toward cleaner energy sources.
- Modular and scalable generator designs will become more popular to meet flexible power needs.
- Regional data localization policies will boost data center construction in emerging economies.
- Collaboration between generator manufacturers and data center developers will increase to ensure optimized power solutions.
- Technological advancements will reduce fuel consumption and improve overall lifecycle performance.
- The market will see growing competition as key players invest in innovation and regional expansion
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Data center generator market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Data center generator market projected to grow between 2025 and 2032?
Which Data center generator market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Data center generator market?
Who are the leading companies in the Data center generator market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6.5 billion → 2032: USD 14.45 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Data Center Generator Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Data Center Generator Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Data Center Generator Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Data Center Generator Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Data Center Generator Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Data Center Generator Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Data Center Generator Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Data Center Generator Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6.5 billion → 2032: USD 14.45 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Data Center Generator Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Data Center Generator Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Data Center Generator Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Data Center Generator Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

