
Market Overview
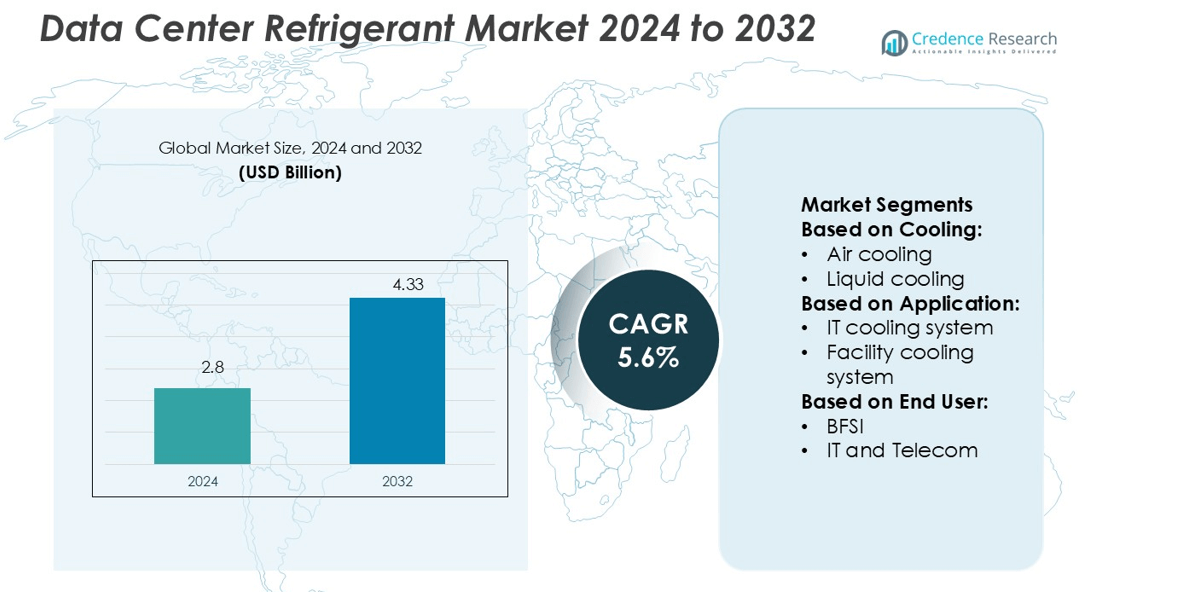
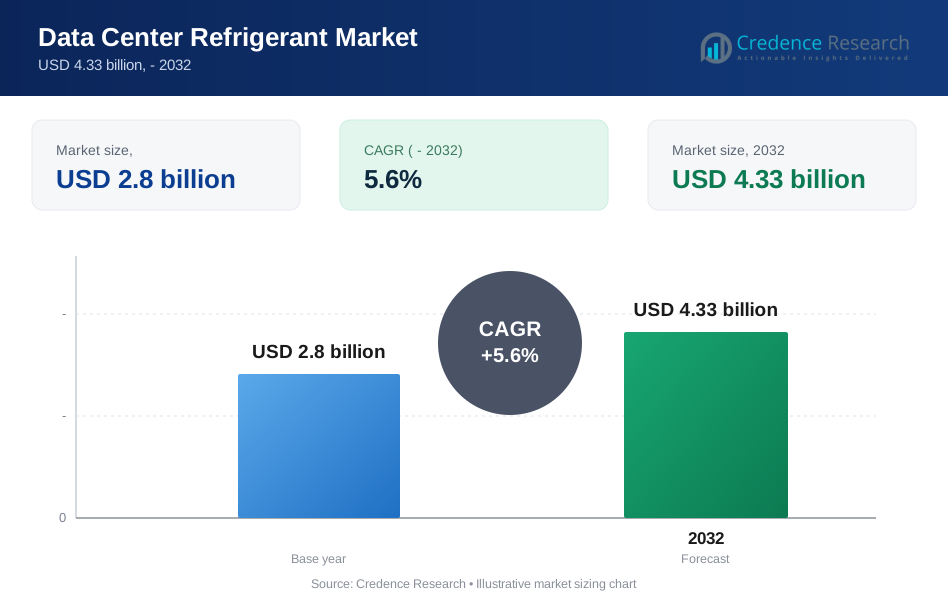
Data Center Refrigerant Market size was valued USD 2.8 billion in 2024 and is anticipated to reach USD 4.33 billion by 2032, at a CAGR of 5.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Data Center Refrigerant Market Size 2024 | USD 2.8 billion |
| Data Center Refrigerant Market, CAGR | 5.68% |
| Data Center Refrigerant Market Size 2032 | USD 4.33 billion |
The Data Center Refrigerant Market is driven by major companies such as Daikin Industries, Orbia, Honeywell International, Asetek, The Chemours Company, Arkema, 3M, Dow, Climalife, and M&I Materials. These players are focusing on sustainable, low-GWP refrigerant solutions to address tightening environmental regulations and rising demand for energy-efficient cooling. Strategic partnerships, product innovation, and global expansion strengthen their competitive positioning. North America leads the market with a 34.6% share, supported by strong hyperscale data center investments, early adoption of green technologies, and regulatory alignment. This leadership, combined with growing technological capabilities, positions the region as a core hub for refrigerant innovation and deployment.
Market Insights
- The Data Center Refrigerant Market was valued at USD 2.8 billion in 2024 and is expected to reach USD 4.33 billion by 2032, growing at a CAGR of 5.6%.
- Rising demand for low-GWP and energy-efficient refrigerants is driving growth, supported by regulatory pressure and expanding hyperscale and edge data center deployments.
- Market players focus on innovation, strategic partnerships, and global expansion to strengthen their competitive edge in sustainable cooling solutions.
- High retrofit costs and complex regulatory requirements remain key restraints, slowing the transition from traditional refrigerants in existing facilities.
- North America leads with a 34.6% share, followed by Europe and Asia Pacific, while air cooling dominates with 46.8% of the market share.
Market Segmentation Analysis:
By Cooling
Air cooling dominates the Data Center Refrigerant Market with a 46.8% share in 2025. Air-cooled systems remain popular due to lower upfront costs, easier installation, and lower maintenance compared to liquid systems. Liquid cooling is growing rapidly as high-density racks and AI workloads increase heat loads. Free cooling is gaining adoption in regions with favorable climates to reduce energy consumption and operational costs. Rising energy efficiency regulations and the push for greener data centers are driving the adoption of advanced cooling technologies, improving PUE and lowering emissions.
- For instance, Daikin supplied 71 EWFH-TZ D air-cooled free cooling chillers, 330 fan array units, and 8 control systems at Norway’s OSL-Hamar data center, yielding an average PUE of 1.20.
By Application
IT cooling systems account for 57.2% of the Data Center Refrigerant Market share in 2025. These systems ensure stable rack temperatures and efficient operation of IT infrastructure. The demand for high-capacity servers and storage units is pushing operators to upgrade thermal management. Facility cooling systems follow closely, supporting HVAC operations, power systems, and ambient environmental control. Increased automation and integration with DCIM platforms enhance cooling performance and reduce energy costs. Data centers with high compute density rely heavily on advanced IT cooling systems for optimal uptime.
- For instance, Orbia's NovoLINC thermal interface materials address cooling bottlenecks for high-density AI racks, reducing junction temperatures by 5–10 °C for GPUs under heavy workloads and achieving an estimated 32% increase in cooling efficiency for liquid-cooled servers.
By End User
The IT and Telecom segment leads the Data Center Refrigerant Market with a 33.5% share in 2025. Rapid expansion of cloud computing, 5G infrastructure, and edge data centers drives demand. BFSI and Government & Defense segments are growing steadily as institutions upgrade secure, high-performance facilities. Healthcare and manufacturing sectors are investing in advanced cooling to support digital transformation. Energy and retail sectors are adopting efficient refrigerant solutions to reduce operational costs. The growing need for high uptime, efficient heat management, and regulatory compliance accelerates refrigerant adoption across industries.
Key Growth Drivers
Rising Demand for Energy-Efficient Data Centers
The growing focus on energy efficiency is a major driver in the Data Center Refrigerant Market. Operators are replacing conventional refrigerants with low-GWP alternatives to meet regulatory standards and reduce power use. High-density computing environments require efficient cooling solutions to maintain optimal performance. Advanced refrigerants help reduce energy consumption and improve overall Power Usage Effectiveness (PUE). The shift toward sustainable infrastructure also attracts green investments. This strong emphasis on operational efficiency continues to push demand for innovative refrigerant technologies across hyperscale, edge, and enterprise data centers.
Expansion of Hyperscale and Edge Data Centers
Rapid growth in hyperscale and edge facilities significantly boosts refrigerant demand. Hyperscale operators deploy high-capacity cooling systems to manage intense heat loads from cloud computing and AI-driven applications. Edge data centers require compact, energy-efficient solutions to maintain performance at remote sites. Refrigerants play a crucial role in supporting stable thermal environments for these advanced infrastructures. The increasing volume of data traffic and low-latency application needs further accelerate deployment. This expansion of distributed computing infrastructure drives the adoption of efficient refrigerant-based cooling systems worldwide.
- For instance, Asetek reported shipping 171,000 sealed-loop liquid cooling units in Q1 2025, supporting compact cooling in dense server racks even in edge environments, while 11 new liquid cooling product models began shipping that quarter.
Stringent Environmental Regulations and Compliance
Global regulatory pressure on high-GWP refrigerants is shaping market growth. Many countries are phasing down HFC use and promoting eco-friendly refrigerants. Data center operators are adopting low-GWP alternatives to comply with international frameworks like the Kigali Amendment. This transition reduces environmental impact and aligns operations with sustainability targets. The shift encourages R&D investments in next-generation refrigerants and retrofitting of legacy systems. Regulatory mandates are turning sustainability from a compliance requirement into a strategic driver, pushing the market toward wider adoption of clean refrigerant technologies.
Key Trends & Opportunities
Adoption of Low-GWP and Natural Refrigerants
The market is witnessing a strong trend toward low-GWP and natural refrigerants like CO₂ and ammonia. These options help operators meet net-zero targets while maintaining efficient thermal management. Natural refrigerants offer long-term cost benefits by lowering regulatory risks and energy expenses. Vendors are innovating to make these solutions safer and more adaptable for data centers. Their rising acceptance creates strong opportunities for suppliers of advanced, environmentally friendly cooling technologies. This shift also aligns with corporate ESG goals and global decarbonization strategies.
- For instance, Chemours launched Opteon™ 2P50, a two-phase immersion cooling dielectric fluid with a GWP of 10 and a design PUE approaching 1, which in field trials has shown up to 90 % cooling energy reduction and up to 40 % total energy savings, and cuts water use nearly to zero.
Integration of AI and Smart Cooling Systems
The growing use of AI and intelligent monitoring is reshaping data center cooling strategies. Smart systems optimize refrigerant use based on real-time thermal loads, reducing energy waste. These systems improve operational reliability and extend equipment life. AI-enabled platforms also allow predictive maintenance, lowering downtime risks and costs. This integration creates strong opportunities for refrigerant manufacturers to align products with smart control technologies. The increasing adoption of such advanced systems is expected to accelerate efficiency gains and support the long-term market outlook.
- For instance, Arkema's Foranext® 1233zd fluid supports direct-to-chip two-phase cooling to handle the extreme heat from modern microprocessors in data centers, improving overall thermal performance, efficiency, and sustainability.
Rise of Modular and Prefabricated Data Centers
The expansion of modular data centers is creating new opportunities for refrigerant applications. Prefabricated units demand compact, efficient, and scalable cooling solutions. These facilities support rapid deployment and high energy efficiency, making refrigerant systems a key component. Manufacturers offering tailored solutions for modular infrastructure gain a competitive edge. The growing use of modular architectures across telecom, cloud, and edge deployments is expected to fuel steady refrigerant demand, especially in regions with rapid digital infrastructure expansion.
Key Challenges
High Retrofit and Transition Costs
Transitioning from traditional HFCs to low-GWP refrigerants involves significant retrofit investments. Many existing facilities require new equipment or system upgrades to handle alternative refrigerants safely. This cost factor delays large-scale adoption among mid-size operators. Additional expenses related to training, installation, and compliance checks further increase the financial burden. These costs pose a challenge for operators aiming to balance regulatory compliance with profitability, slowing down the overall replacement rate of legacy systems in the market.
Complex Regulatory and Safety Standards
Compliance with evolving environmental regulations remains a key challenge for operators. Different regions enforce varied refrigerant use guidelines, creating complexity for multinational data center operators. Natural refrigerants often involve stricter safety measures, including handling, storage, and monitoring protocols. Meeting these standards requires specialized equipment and skilled personnel. This regulatory and operational complexity increases compliance costs and lengthens project timelines. Navigating these diverse standards effectively is a major hurdle for rapid market expansion and uniform adoption of sustainable refrigerant solutions.
Regional Analysis
North America
North America leads the Data Center Refrigerant Market with a 34.6% share in 2025. The region’s dominance is driven by large hyperscale deployments, advanced digital infrastructure, and strong regulatory focus on energy efficiency. The U.S. hosts major cloud service providers that invest heavily in low-GWP refrigerant solutions to comply with evolving environmental standards. Growing adoption of edge facilities further boosts demand for efficient thermal management systems. Strategic investments in sustainable cooling technologies and early regulatory alignment position North America as a key hub for refrigerant innovation and large-scale adoption across data centers.
Europe
Europe holds a 27.4% share of the Data Center Refrigerant Market in 2025. Strict environmental policies, such as the EU F-Gas Regulation, are accelerating the transition toward low-GWP and natural refrigerants. Countries like Germany, the Netherlands, and Sweden are leading in green data center adoption. Operators are integrating energy-efficient cooling systems to reduce emissions and meet carbon neutrality targets. High investment in renewable-powered facilities supports this transition. The strong emphasis on sustainability and innovation positions Europe as a leading market for eco-friendly refrigerant technologies and next-generation cooling solutions.
Asia Pacific
Asia Pacific accounts for 24.1% of the Data Center Refrigerant Market in 2025. Rapid expansion of cloud services, 5G infrastructure, and edge data centers fuels strong demand for efficient refrigerants. Countries like China, India, Japan, and Singapore are investing heavily in hyperscale facilities to support rising data traffic. The growing presence of global hyperscale operators in the region accelerates advanced cooling adoption. Regulatory bodies are gradually implementing stricter efficiency norms, driving a shift toward low-GWP refrigerants. Asia Pacific’s fast-growing digital economy makes it a critical growth engine for future refrigerant demand.
Latin America
Latin America represents 7.1% of the Data Center Refrigerant Market in 2025. Brazil and Mexico lead regional demand with investments in new colocation and edge facilities. Growing cloud adoption and digital transformation across industries are driving the installation of energy-efficient cooling systems. Operators are adopting low-GWP refrigerants to align with international environmental standards. While regulatory frameworks are less strict compared to Europe, increased foreign investment in sustainable infrastructure is accelerating modernization. Latin America’s improving connectivity and expanding data center footprint support steady market growth for advanced refrigerant technologies.
Middle East & Africa
The Middle East & Africa region holds a 6.8% share in the Data Center Refrigerant Market in 2025. Countries like the UAE, Saudi Arabia, and South Africa are investing in data center infrastructure to support cloud growth and digitalization. High ambient temperatures in many locations increase the need for efficient refrigerant-based cooling solutions. Government-led smart city initiatives and green building programs encourage the use of sustainable refrigerants. Although the market is still developing, rapid infrastructure expansion and regulatory alignment with global standards create strong future growth opportunities in this region.
Market Segmentations:
By Cooling:
- Air cooling
- Liquid cooling
By Application:
- IT cooling system
- Facility cooling system
By End User:
- BFSI
- IT and Telecom
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Data Center Refrigerant Market features key players including Daikin Industries, Orbia, Honeywell International, Asetek, The Chemours Company, Arkema, 3M, Dow, Climalife, and M&I Materials. The Data Center Refrigerant Market is defined by rapid innovation, regulatory alignment, and increasing sustainability commitments. Companies are focusing on developing low-GWP and high-performance refrigerants to meet strict environmental standards. Strategic partnerships with data center operators, equipment manufacturers, and technology providers are strengthening product adoption. R&D investments aim to enhance thermal efficiency, energy savings, and operational safety. Many suppliers are also expanding service capabilities to support retrofitting of existing infrastructure. Intense competition, coupled with rising demand for eco-friendly solutions, is driving continuous technological advancements and shaping a dynamic, innovation-focused market environment.
Key Player Analysis
- Daikin Industries
- Orbia
- Honeywell International
- Asetek
- The Chemours Company
- Arkema
- 3M
- Dow
- Climalife
- M&I Materials
Recent Developments
- In May 2025, Samsung Electronics announced acquisition of Flak Group to expand HVAC offering in data center Samsung entered a $1.5 billion agreement to acquire Flak Group, a Germany based HVAC leader. The move strengthens Samsung position in climate.
- In February 2025, Vertiv rolled out a complete services suite for liquid cooling, including its Liebert XDU1350 system for CDU (cooling distribution units). The services target hyperscale and AI-focused data centers transitioning to liquid-based thermal management.
- In December 2024, Schneider Electric introduced new AI-ready data center solutions to meet the energy, and sustainability demands of AI systems. In collaboration with NVIDIA, Schneider Electric launched a reference design for liquid-cooled AI clusters supporting up to 132 kW per rack.
- In January 2024, Modine announced its acquisition of the intellectual property and distinct assets of TMG Core. TMG Core specializes in single- and two-phase liquid immersion cooling technology tailored for data centers with demanding high-density computing needs
Report Coverage
The research report offers an in-depth analysis based on Cooling, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see rising adoption of low-GWP and natural refrigerants to meet green standards.
- Hyperscale and edge data center growth will increase demand for advanced cooling solutions.
- Energy efficiency regulations will push operators to replace legacy refrigerants.
- Integration of AI-driven cooling systems will optimize refrigerant use and lower costs.
- Retrofitting of existing facilities will create strong opportunities for refrigerant suppliers.
- Modular and prefabricated data centers will boost demand for compact refrigerant systems.
- Regional regulatory alignment will accelerate the transition to sustainable refrigerants.
- Technological innovation will improve system performance and reduce environmental impact.
- Partnerships between refrigerant makers and operators will strengthen market penetration.
- Rising investments in green data centers will shape long-term refrigerant strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Data Center Refrigerant Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Data Center Refrigerant Market projected to grow between 2025 and 2032?
Which Data Center Refrigerant Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Data Center Refrigerant Market?
Who are the leading companies in the Data Center Refrigerant Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.8 billion → 2032: USD 4.33 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Data Center Refrigerant Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Data Center Refrigerant Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Data Center Refrigerant Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Data Center Refrigerant Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Data Center Refrigerant Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Data Center Refrigerant Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Data Center Refrigerant Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Data Center Refrigerant Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.8 billion → 2032: USD 4.33 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Data Center Refrigerant Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Data Center Refrigerant Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Data Center Refrigerant Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Data Center Refrigerant Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

