
Diesel Generator Market Overview:
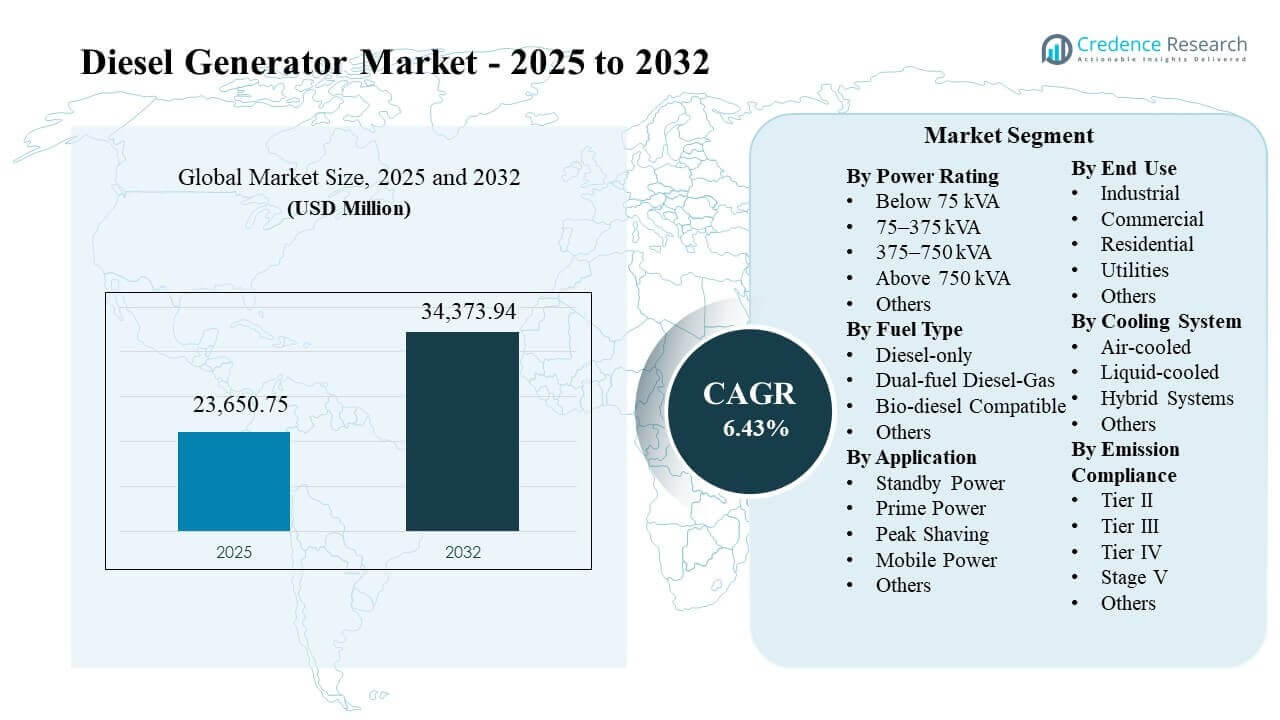
The global Diesel Generator Market size was estimated at USD 23,650.75 million in 2025 and is expected to reach USD 34,373.94 million by 2032, growing at a CAGR of 6.43% from 2025 to 2032. Demand is being propelled by reliability requirements across mission-critical operations where downtime risk drives investment in dependable backup power, especially for industrial sites, healthcare facilities, commercial buildings and telecom infrastructure. Asia Pacific remains a major consumption and installation hub as grid expansion, construction activity and critical-infrastructure buildouts increase the need for dependable standby and prime power coverage in both urban and remote settings.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Diesel Generator Market Size 2025 | USD 23,650.75 million |
| Diesel Generator Market , CAGR | 6.43% |
| Diesel Generator Market Size 2032 | USD 34,373.94 million |
Key Market Trends & Insights
- The market is projected to expand from USD 23,650.75 million in 2025 to USD 34,373.94 million by 2032.
- Growth is expected at a CAGR of 6.43% over 2025–2032, supported by resilient power planning across critical loads.
- Below 75 kVA accounted for the largest share of 41.8% in 2025, reflecting strong demand for small-site backup installations.
- Standby Power led applications with a 64.9% share in 2025, driven by uptime requirements for essential services.
- Asia Pacific held 32.1% of revenue in 2025, supported by infrastructure expansion and dense commercial and industrial activity.
Segment Analysis
Buyer behavior in the Diesel Generator Market is shaped by reliability targets, site criticality, operating hours and service accessibility. Small and mid-sized buyers prioritize rapid deployment, compact footprints and ease of maintenance, which supports strong adoption of lower kVA ranges for commercial buildings, small industrial sites and residential backup. Larger buyers emphasize redundancy planning, synchronization capability and lifecycle service support, which raises demand for engineered systems used in critical infrastructure.
Application selection is closely tied to grid stability and the cost of downtime. Standby systems remain a default risk-management tool for hospitals, data centers, telecom towers and factories that cannot tolerate outages. Prime power demand rises where grids are weak or where sites are remote and require continuous generation. Peak shaving and mobile power deployments grow where project-based loads and temporary infrastructure require flexible power coverage.
By Power Rating Insights
Below 75 kVA accounted for the largest share of 41.8% in 2025. Compact gensets fit widespread backup needs in small commercial sites, telecom loads and residential settings where installation space and capex constraints are decisive. Serviceability and parts availability also favor standardized low-kVA platforms. Buyers often prioritize quick-start performance and stable load acceptance, which supports repeat demand for dependable entry and mid-tier configurations.
By Fuel Type Insights
Diesel-only configurations remain a common selection where fuel logistics, long-duration runtime requirements and proven maintenance practices support predictable operation. Dual-fuel Diesel-Gas options gain attention in locations with gas availability and where operators seek lower operating costs or reduced emissions profiles within site constraints. Bio-diesel compatible options are increasingly evaluated where sustainability targets influence procurement and where compatible fuel supply chains exist. Fuel type decisions are also shaped by permitting, duty cycles and total cost of ownership.
By Application Insights
Standby Power accounted for the largest share of 64.9% in 2025. Backup readiness is reinforced by increasing sensitivity to outages across commercial operations and critical services. Facilities prioritize fast response, reliability under variable loads and integration with transfer switches and control systems. Standby systems also benefit from structured maintenance schedules and fleet standardization programs that reduce operational risk across multi-site operators.
By End Use Insights
Industrial demand remains structurally strong because factories, process industries and remote operations place a premium on uptime, rugged equipment and service coverage. Commercial buyers adopt gensets to protect revenue continuity in offices, retail, hospitality and healthcare where outages disrupt operations and safety systems. Residential adoption rises in markets with recurring outages and where households invest in backup resilience. Utilities and infrastructure operators deploy gensets for emergency response, maintenance windows and localized resilience needs.
By Cooling System Insights
Cooling system selection reflects power class, ambient conditions, runtime expectations and enclosure design. Air-cooled systems tend to align with smaller kVA installations where simplicity and lower upfront cost guide decisions. Liquid-cooled systems are typically preferred for higher loads and longer duty cycles because thermal stability supports consistent performance. Hybrid approaches that combine engine systems with controls and storage are evaluated where noise, fuel efficiency and emissions performance influence deployment decisions.
By Emission Compliance Insights
Emissions compliance requirements increasingly shape product selection and upgrade cycles, especially in regions with tighter standards and permitting scrutiny. Higher-compliance engines and aftertreatment packages can raise upfront costs but reduce regulatory risk for large buyers and fleet operators. Procurement teams also weigh compliance against duty cycle, maintenance complexity and local service capability. Compliance planning is often linked to broader sustainability reporting and operational governance in critical industries.
Diesel Generator Market Drivers
Grid Reliability and Uptime Requirements
Grid disturbances and planned maintenance outages continue to elevate demand for dependable backup power across essential services and commercial operations. Diesel generator systems remain a trusted solution where fast start, high load acceptance and predictable runtime are prioritized. Critical facilities often require redundancy planning and proven performance under emergency conditions. Reliability expectations also support investment in controls, switchgear and service agreements that sustain readiness and reduce operational risk.
Expansion of Critical Infrastructure and Construction Activity
Industrial expansion, construction projects and critical infrastructure buildouts increase the need for temporary and permanent power coverage. Remote worksites and project-based loads often require mobile and prime power solutions that can be deployed quickly and serviced reliably. Growth in logistics facilities, healthcare sites and commercial real estate also raises standby installations as part of resilience planning. Equipment standardization across multi-site operators further supports repeat purchases and fleet upgrades.
- For instance, Aggreko provides modular generator systems such as its 1,250 kVA units that can be deployed within hours and operate continuously for over 8,000 hours annually in remote construction and mining environments, supporting large-scale infrastructure projects.
Data Center, Telecom and Digital Economy Resilience
Digital services depend on uninterrupted power, driving adoption of generator-backed resilience strategies across data centers and telecom infrastructure. Operators prioritize systems that integrate with UPS architectures, synchronize across multiple units and support continuous testing regimes. Service network strength, parts availability and remote monitoring capabilities influence purchasing decisions for these uptime-focused buyers. Reliability-driven procurement also accelerates replacement of aging equipment to reduce failure probability during grid events.
Product Modernization and Service Ecosystems
OEMs compete by improving power density, footprint efficiency, monitoring capabilities and service responsiveness. Buyers increasingly evaluate lifecycle support, preventive maintenance tooling and technician coverage when selecting generator platforms. More capable control systems enable better load management and easier integration with site energy strategies. These improvements expand addressable applications and strengthen customer retention, particularly in regulated or mission-critical environments where performance assurance matters.
- For instance, Rolls-Royce Power Systems’ mtu Series 4000 generators feature advanced digital control systems with real-time monitoring and predictive maintenance capabilities, reducing unplanned downtime by up to 30% and supporting power outputs ranging from 1,000 kVA to over 3,000 kVA in critical applications.
Diesel Generator Market Challenges
Supply chain volatility, component availability constraints and logistics disruptions can delay deliveries and elevate equipment costs, which complicates project timelines for commercial and industrial buyers. Compliance-driven configurations can increase complexity in procurement and maintenance, especially when aftertreatment requirements vary by jurisdiction. Fuel price variability also affects operating economics for prime power users, pushing buyers to scrutinize total cost of ownership and service plans.
- For instance, Cummins Inc. reported in its 2023 annual disclosures that supply chain disruptions extended lead times for generator components such as alternators and control systems by up to 20–30%, while its Tier 4 Final compliant diesel generators require aftertreatment systems that reduce nitrogen oxide (NOx) emissions by up to 90% and particulate matter by 98%, increasing system complexity and maintenance requirements.
Regulatory tightening and permitting requirements can constrain deployments in regions with strict emissions policies and noise limitations. Competitive alternatives such as gas generators, microgrids and storage-based solutions increase pressure on diesel systems in selected use cases. Site operators also face challenges integrating generators with modern electrical architectures, including coordination with UPS systems, controls and safety protocols. Skilled service labor availability can influence uptime performance and buyer satisfaction.
Diesel Generator Market Trends and Opportunities
Hybridization and smarter controls are gaining traction as buyers seek better fuel efficiency, improved load management and stronger compliance readiness. Remote monitoring, predictive maintenance and digital service platforms are increasingly used to improve availability and reduce unplanned downtime. Buyers are also prioritizing solutions that simplify commissioning and standardize maintenance across multi-site operations. These trends create opportunities for OEMs that combine equipment performance with service-led differentiation.
Infrastructure investment in emerging markets continues to expand demand for standby and prime power solutions across commercial and industrial end uses. Growth in healthcare expansion, logistics networks and telecom densification strengthens the need for resilient on-site power. Opportunities also arise from replacement demand as aging fleets are upgraded for compliance and reliability. Channel strength and aftermarket support can unlock recurring revenue through parts, service contracts and performance optimization.
- For instance, Caterpillar’s healthcare references show the scale of critical backup power demand: Hamilton Health Sciences installed 13 Cat G3516H natural gas generator sets across a seven-hospital network, St. Luke’s Hospital operated for two days on a 4.5 MW standby plant consisting of three Cat 3512 diesel generator sets, and OSF St. Francis uses three Cat C32 generator sets that start within 10 seconds to support a 10-building campus during outages.
Regional Insights
North America
North America represented 18.6% of Diesel Generator Market revenue in 2025, supported by resilience planning across commercial facilities, healthcare and critical infrastructure. Procurement emphasizes compliance alignment, service coverage and availability of parts and technicians. Demand is also shaped by severe weather exposure and continuity planning across essential services. Growth opportunities remain strongest in mission-critical deployments where uptime standards drive redundant system architectures.
Europe
Europe accounted for 10.9% of revenue in 2025, with purchasing decisions influenced by emissions standards, permitting requirements and noise constraints in dense urban environments. Buyers increasingly evaluate compliant systems and operational practices that reduce regulatory risk. Commercial and industrial installations remain important, particularly where backup coverage supports safety and continuity needs. Service networks and compliance-ready product portfolios are key differentiators across competitive bids.
Asia Pacific
Asia Pacific held the leading regional share at 32.1% in 2025, driven by infrastructure development, expanding commercial real estate and industrial capacity growth. Demand spans standby systems for urban commercial buildings and prime power coverage in remote or weak-grid areas. Buyers prioritize cost-effective ownership, reliable service access and scalable product ranges across power classes. Regional growth is also supported by construction activity and expansion of digital infrastructure requiring resilient power planning.
Latin America
Latin America represented 9.7% of revenue in 2025, supported by backup power needs in commercial buildings, industrial sites and telecom infrastructure. Grid stability variability in selected markets encourages standby adoption for operational continuity. Procurement can be influenced by financing constraints and the availability of service networks, which elevates the importance of distributor strength. Opportunity remains in fleet replacement and modernization where reliability and maintenance practices are prioritized.
Middle East & Africa
Middle East & Africa accounted for 28.7% of revenue in 2025, reflecting strong reliance on backup and prime power solutions across infrastructure, oil and gas operations and large commercial developments. Remote operations and high-temperature environments elevate demand for robust configurations and dependable service coverage. Large projects often require engineered systems, redundancy planning and strong commissioning support. Growth is reinforced by infrastructure programs and continuity requirements for essential services.
Competitive Landscape
Competition in the Diesel Generator Market is defined by portfolio breadth across kVA classes, compliance-ready engine platforms and the depth of service and distribution ecosystems. OEMs differentiate through reliability performance, faster commissioning support, control-system capability and lifecycle service plans that reduce downtime risk. Large buyers increasingly standardize fleets to simplify maintenance and improve readiness. Channel reach and aftermarket capability remain decisive for winning multi-site accounts and mission-critical deployments.
Caterpillar competes through broad power portfolios and solutions engineered for high-uptime environments where performance assurance is central to procurement. Caterpillar’s positioning emphasizes durable equipment design, service network depth and integration support for complex electrical systems. Critical infrastructure buyers value consistent load acceptance and the ability to scale redundancy with synchronized units. Aftermarket parts availability and service responsiveness strengthen Caterpillar’s retention in fleets where lifecycle performance is a primary purchasing criterion.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Caterpillar
- Cummins
- Generac
- Kohler
- Mitsubishi Heavy Industries
- Wärtsilä
- Rolls-Royce Power Systems
- Atlas Copco
- FG Wilson
- Kirloskar Oil Engines
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In March 2026, Generac Holdings Inc. introduced its new SD1250 and SD1500 diesel generators, expanding its high-capacity industrial product lineup with more fuel-efficient, lower-emission 46‑liter Perkins 5012 engine-based units designed for mission-critical applications.
- In August 2025, Generac launched a new diesel generator product line tailored for the Indian market, aligning the range with residential, commercial and industrial uninterrupted power needs while simultaneously expanding its manufacturing facility in India under its new legal identity, Generac Captiva Private Limited.
- In March 2025, Caterpillar Inc. acquired a majority stake in a leading renewable hybrid power solutions provider to broaden its clean energy and hybrid diesel generator portfolio and strengthen its position in low-emission power systems.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 23,650.75 million |
| Revenue forecast in 2032 | USD 34,373.94 million |
| Growth rate (CAGR) | 6.43% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | Power Rating; Fuel Type; Application; End Use; Cooling System; Emission Compliance |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Caterpillar; Cummins; Generac; Kohler; Mitsubishi Heavy Industries; Wärtsilä; Rolls-Royce Power Systems; Atlas Copco; FG Wilson; Kirloskar Oil Engines |
| No.of Pages | 328 |
Segmentation
By Power Rating
- Below 75 kVA
- 75–375 kVA
- 375–750 kVA
- Above 750 kVA
- Others
By Fuel Type
- Diesel-only
- Dual-fuel Diesel-Gas
- Bio-diesel Compatible
- Others
By Application
- Standby Power
- Prime Power
- Peak Shaving
- Mobile Power
- Others
By End Use
- Industrial
- Commercial
- Residential
- Utilities
- Others
By Cooling System
- Air-cooled
- Liquid-cooled
- Hybrid Systems
- Others
By Emission Compliance
- Tier II
- Tier III
- Tier IV
- Stage V
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Grid Reliability and Uptime Requirements
Frequent grid disturbances and planned maintenance outages are driving investments in diesel generators as dependable backup power sources, especially for critical facilities like hospitals, data centers, and telecom infrastructure where downtime is unacceptable.
Expansion of Critical Infrastructure and Construction Activity
Ongoing industrial expansion, infrastructure buildouts, and construction projects are increasing the need for both temporary and permanent power solutions, with diesel generators providing rapid deployment and reliable service in remote or project-based environments.
Data Center, Telecom, and Digital Economy Resilience
The growth of digital services and data centers requires uninterrupted power, leading operators to adopt diesel generators for resilience strategies, integration with UPS systems, and continuous testing to ensure uptime.
Product Modernization and Service Ecosystems
OEMs are enhancing generator offerings with improved power density, digital monitoring, and lifecycle service support, making diesel generators more attractive for buyers seeking reliability, easier maintenance, and integration with modern site energy strategies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Diesel Generator Market?
What is the CAGR for the Diesel Generator Market during 2025–2032?
Which segment holds the largest share in the Diesel Generator Market?
What factors are driving growth in the Diesel Generator Market?
Who are the leading companies in the Diesel Generator Market?
Which region leads the Diesel Generator Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Industrial
- 1.2.2 Commercial
- 1.2.3 Residential
- 1.2.4 Utilities
- 1.3 By Fuel Type
- 1.3.1 Diesel-only
- 1.3.2 Dual-fuel Diesel-Gas
- 1.3.3 Bio-diesel Compatible
- 1.4 By Application
- 1.4.1 Standby Power
- 1.4.2 Prime Power
- 1.4.3 Peak Shaving
- 1.4.4 Mobile Power
- 1.5 By Power Rating
- 1.5.1 Below 75 kVA
- 1.5.2 75–375 kVA
- 1.5.3 375–750 kVA
- 1.5.4 Above 750 kVA
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 23,650.75 million → 2032: USD 34,373.94 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Diesel Generators Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Diesel Generators Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Diesel Generators Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Diesel Generators Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Diesel Generators Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Diesel Generators Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Diesel Generators Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Diesel Generators Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 23,650.75 million → 2032: USD 34,373.94 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Diesel Generators Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Industrial
- 12.3.7.2 Commercial
- 12.3.7.3 Residential
- 12.3.7.4 Utilities
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Fuel Type - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Diesel-only
- 12.4.7.2 Dual-fuel Diesel-Gas
- 12.4.7.3 Bio-diesel Compatible
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Standby Power
- 12.5.7.2 Prime Power
- 12.5.7.3 Peak Shaving
- 12.5.7.4 Mobile Power
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Power Rating - Market Size and Forecast, 2025-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2025-2032
- 12.6.4 Volume Forecast, 2025-2032
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Below 75 kVA
- 12.6.7.2 75–375 kVA
- 12.6.7.3 375–750 kVA
- 12.6.7.4 Above 750 kVA
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Diesel Generators End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Diesel Generators Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Diesel Generators Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Diesel Generators Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Caterpillar
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cummins
- 18.4 Generac
- 18.5 Kohler
- 18.6 Mitsubishi Heavy Industries
- 18.7 Wärtsilä
- 18.8 Rolls-Royce Power Systems
- 18.9 Atlas Copco
- 18.10 FG Wilson
- 18.11 Kirloskar Oil Engines
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

