
Market Overview
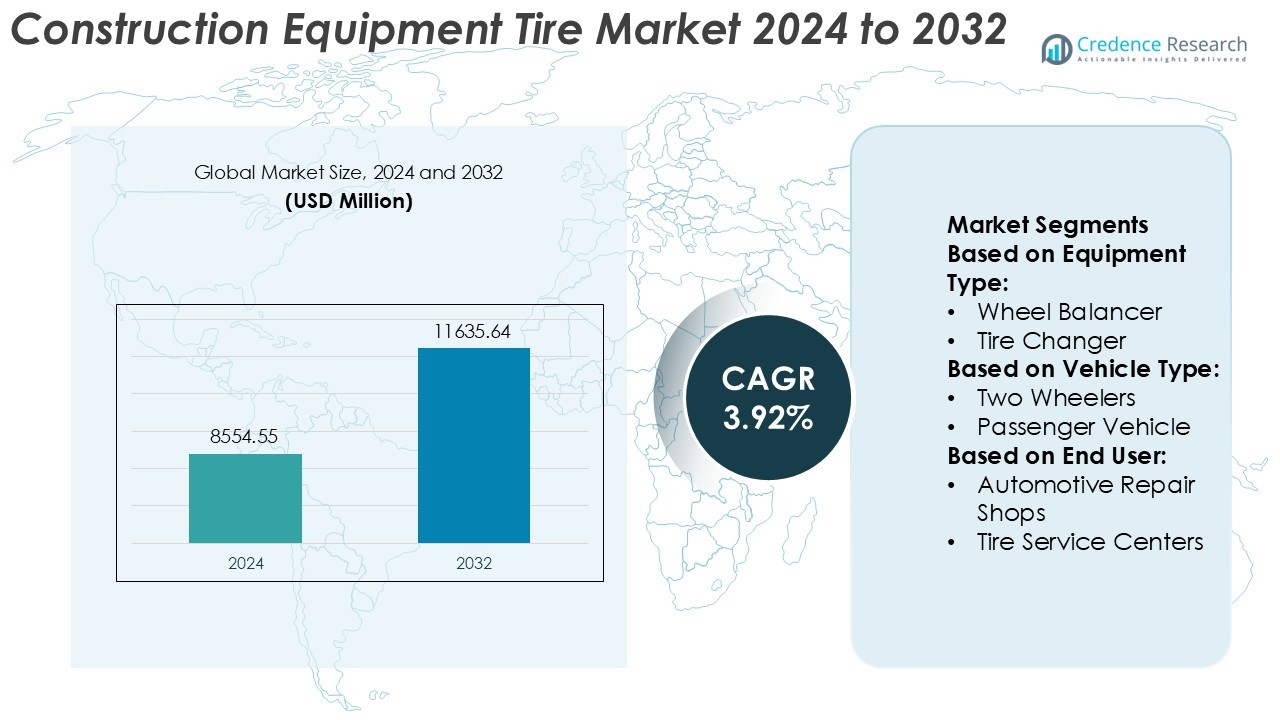
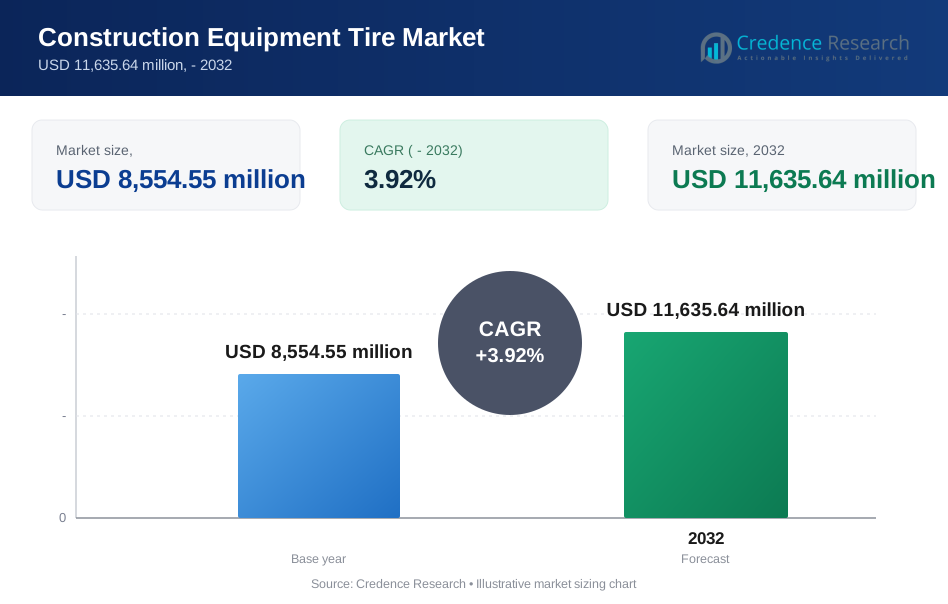
Construction Equipment Tire Market size was valued USD 8554.55 million in 2024 and is anticipated to reach USD 11635.64 million by 2032, at a CAGR of 3.92% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Construction Equipment Tire Market Size 2024 | USD 8554.55 Million |
| Construction Equipment Tire Market, CAGR | 3.92% |
| Construction Equipment Tire Market Size 2032 | USD 11635.64 Million |
The Construction Equipment Tire Market is shaped by strong competition from global and regional manufacturers offering tires for loaders, excavators, dump trucks, and graders. The market includes premium brands focusing on advanced tread compounds, puncture resistance, and longer operating life, while cost-focused suppliers compete through affordable bias and radial options for developing countries. Asia Pacific remains the leading region, holding 35% market share, driven by large infrastructure programs, rapid urbanization, and expanding mining and quarrying activities. High construction equipment utilization in China, India, and Southeast Asia sustains steady replacement demand. Growing adoption of radial tires, increasing rental equipment fleets, and investments in tire pressure monitoring technology further strengthen the region’s leadership.
Market Insights
- The Construction Equipment Tire Market was valued USD 8,554.55 million in 2024 and is set to reach USD 11,635.64 million by 2032 at a 3.92% CAGR, supported by steady demand from construction and mining fleets.
- Infrastructure development, mechanized construction, and higher equipment utilization drive demand, while the shift toward radial tires increases market revenue due to longer life, better stability, and lower rolling resistance.
- Smart technologies such as tire pressure monitoring and predictive maintenance gain traction, and replacement sales remain strong as rental fleets account for a large share of equipment usage.
- Competition stays intense as premium brands focus on durability and advanced tread compounds, while low-cost manufacturers gain share with budget-friendly bias and radial tires.
- Asia Pacific leads the market with 35% share due to rapid construction activity in China, India, and Southeast Asia, and radial tires hold the largest segment share as contractors prefer longer service life and reduced downtime.
 Market Segmentation Analysis:
By Equipment Type
Wheel balancers hold the leading share in the construction equipment tire market with 31% share. Fleet operators and service centers prefer wheel balancers because they reduce vibration, improve tire life, and protect suspension components. Heavy construction vehicles need precise balancing due to uneven terrain and long operating hours. Tire changers and inflators follow, supported by rising maintenance needs in infrastructure projects. Wheel alignment systems and lifting equipment grow at a steady pace due to safety regulations and the need to minimize downtime.
- For instance, JK Tyre’s global research and technology centre at Mysore utilised its testing rigs to validate tyre-changer compatibility across 10 size-categories in 2023, ensuring service-tool readiness for commercial and OTR tyres.
By Vehicle Type
Commercial vehicles dominate this segment with 46% share. Construction fleets rely on heavy-duty trucks, LCVs, and HCVs for material transport, which increases tire wear and service frequency. Rising logistics activity and large construction investments also push tire maintenance demand. SUVs, luxury cars, and mid-size vehicles contribute steady growth due to increased urban construction activity, but their service requirement remains lower compared to large commercial fleets. Coaches and buses add a smaller share, driven by infrastructure-linked public transport growth.
- For instance, Cheng Shin Rubber Ind. Co., Ltd. (CST) introduced the “CST Cortex” radial tyre featuring a 60 TPI sidewall carcass design, achieving a weight reduction of 0.72 kg per unit and a rolling-resistance drop of “more than 10 %”.
By End User
Automotive repair shops lead the market with 38% share, driven by high daily service volume and wide availability in urban and rural areas. These workshops handle routine tire changes, balancing, and inflating for both personal and commercial vehicles. Tire service centers follow, supported by dedicated equipment and specialized technicians. Motorcycle repair shops add steady demand due to two-wheeler dominated regions. Automotive OEM dealerships capture a smaller share, mostly serving premium and new-vehicle owners who prefer brand-certified service facilities.
Key Growth Drivers
Rising Construction and Infrastructure Spending
Global infrastructure programs, housing development, and public transportation projects boost demand for construction equipment tires. Heavy machinery like loaders, excavators, and graders require durable tires that can withstand harsh operating environments. Government investments in roads, bridges, smart cities, and industrial facilities continue to expand fleet sizes. Manufacturers are also supplying tires optimized for fuel efficiency and traction to support productivity at construction sites. Growth in commercial real estate and mining activity further supports tire replacement needs, creating sustained market demand across developing and developed nations.
- For instance, Continental AG’s EM-Master range for wheel loaders and articulated dump trucks uses a steel-cord reinforced carcass capable of handling loads up to 15,000 kg per tire, as documented in Continental’s OTR product specifications.
Rapid Urbanization and Industrial Expansion
Urban population growth drives real estate development, public utilities expansion, and road construction. Industrial growth increases the use of earthmoving and material-handling machinery, directly influencing tire consumption. Manufacturers are developing high-load capacity tires for rough terrains, tunnels, and high-dust environments. Urban redevelopment projects, warehouse automation, and logistics infrastructure also contribute to equipment utilization rates. Rising demand from rental fleets accelerates frequent tire replacement cycles. As cities expand and industries adopt mechanized construction, the need for efficient equipment tires continues to strengthen market revenues.
- For instance, Guizhou Tyre Co., Ltd. produces its "Advance" OTR series at the Zhazuo plant in Guiyang, which is undergoing expansion through an "intelligent manufacturing" project designed to eventually reach an annual output capacity of 380,000 OTR tires and includes specialized steel-cord radial lines for mining equipment.
Technological Advancements in Tire Engineering
Enhanced tread designs, puncture-resistant compounds, and self-sealing technologies improve durability and reduce downtime. Tire companies are investing in real-time pressure monitoring and smart tire sensors to prevent equipment failures. Low-heat-generation rubber compounds help extend tire life during long operating hours. Manufacturers are designing tires that support higher ground stability and lower fuel consumption for heavy-duty vehicles. These innovations reduce operating costs for contractors and fleet operators. The growing adoption of radial tires over bias-ply designs further increases market potential by offering better load distribution and longer service life.
Key Trends & Opportunities
Growing Demand for Sustainable and Retreadable Tires
Construction companies are switching to eco-friendly tire materials and retreadable designs to cut waste and reduce costs. Retreading extends tire life and lowers expenses for rental fleets and contractors working on large infrastructure projects. Tire makers are introducing recyclable rubber compounds and bio-based materials to reduce carbon footprints. Green construction certifications and sustainability initiatives encourage contractors to adopt products with lower environmental impact. These trends create opportunities for suppliers offering fuel-efficient, low-rolling-resistance tires built for long-term use in heavy-duty environments.
- For instance, Camso’s retread program for construction tires supports tread reuse up to 3 times on its solid skid-steer lines, and the company documents that retreading can reduce raw-material consumption by up to 63 kg per tire compared to a full replacement.
Rapid Adoption of Smart and Connected Tire Solutions
Digital tire management systems help track wear, pressure, and temperature in real time. Connected sensors alert operators before failures occur, reducing accidents and machine downtime. Contractors with large fleets gain cost savings through automated alerts, predictive maintenance, and optimized tire usage. Smart tires also support fleet analytics, improving performance and safety on job sites. As construction becomes more digitized, demand for smart tire technologies continues to rise among OEMs, rental companies, and heavy-duty machinery owners.
- For instance, Kenda reports that its automated inspection line performs uniformity and X-ray checks on every single OTR tire, which is a key feature of Industry 4.0 automation designed to ensure 100% quality control and the line scans carcass thickness to a precision of 0.01 millimeters.
Expansion of Rental Construction Machinery Fleets
Short-term construction projects and cost-optimization practices increase reliance on rental machines. Rental fleets replace tires more frequently due to heavy utilization across varied terrains. Tire makers are developing rugged models that meet rental fleet durability and low-maintenance requirements. This trend unlocks growth for mid-priced and premium tire segments used in loaders, cranes, backhoes, and excavators. Regional equipment rental penetration in developing markets presents new opportunities for tire suppliers to expand distribution networks and service partnerships.
Key Challenges
Volatility in Raw Material Prices
Rubber, carbon black, and specialty polymers face fluctuating prices due to supply constraints, energy costs, and geopolitical instability. Rising input costs pressure manufacturers and distributors, pushing them to adjust product pricing. Smaller suppliers face margin challenges when large contractors demand cost-competitive tires. Currency fluctuations further raise import expenses in developing markets. These conditions complicate long-term production planning and impact profitability across the supply chain, especially for companies without integrated raw-material sourcing.
Intense Competition from Low-Cost Tire Manufacturers
Low-cost producers offer budget-friendly tires that attract small construction contractors and rental companies. This competition pressures premium brands to reduce pricing or expand mid-range offerings. Cheaper tires often have shorter service life, increasing replacement cycles, but some buyers prioritize upfront cost over durability. Global manufacturers must differentiate through performance, safety certifications, and advanced technologies. As price competition increases across Asia and Latin America, brand loyalty becomes harder to maintain without strong service and distribution support.
Regional Analysis
North America
North America holds a significant share of the Construction Equipment Tire Market due to strong demand for machinery used in road building, commercial infrastructure, and mining operations. The United States accounts for the highest spending on heavy equipment fleets, driven by federal and state infrastructure programs. High mechanization levels and strict safety standards encourage the use of premium, puncture-resistant tires. The region captures around 28% market share, supported by a large rental equipment ecosystem and advanced tire management technologies. Replacement tire sales remain steady as fleets operate in high-wear conditions across construction and quarry sites.
Europe
Europe secures approximately 25% market share, supported by public investment in transportation, energy networks, and industrial facilities. Germany, France, and the U.K. lead demand for high-durability tires used in compact construction machinery and material-handling equipment. The region emphasizes low-emission and sustainable tire materials due to strict environmental regulations. Manufacturers focus on retreaded products and radial tire adoption to reduce operating costs. Ongoing housing upgrades, tunnel development, and refurbishment of aging infrastructure sustain replacement cycles. The presence of major tire producers and high safety certification standards supports continued product innovation across European construction fleets.
Asia Pacific
Asia Pacific commands the largest share of the Construction Equipment Tire Market, holding close to 35%. China, India, Japan, and Southeast Asia show strong demand due to rapid urbanization, industrialization, and large government-funded infrastructure programs. Growth in mining, real estate, and transport corridors increases the need for heavy-duty and earthmoving tires. Local manufacturing capacity enables competitive pricing and wider product range availability. Rising adoption of mechanized construction techniques and expanding rental equipment fleets further strengthen consumption. Frequent replacement of tires in rough terrain and hot climates sustains long-term demand across the region.
Latin America
Latin America accounts for around 7% market share, driven by construction activities in Brazil, Mexico, Chile, and Colombia. Mining operations in Chile and Peru further boost the need for off-road and loader tires. Infrastructure expansion, including highways, airports, and commercial facilities, supports steady equipment usage. However, market growth fluctuates with economic cycles and public spending. Local distributors and global tire brands compete through price-focused offerings. Demand for durable and cost-efficient radial tires is rising as contractors seek to reduce downtime in rugged conditions. Replacement sales contribute a significant portion of revenue.
Middle East & Africa
The Middle East & Africa region captures approximately 5% market share, supported by construction of smart cities, energy infrastructure, and mega commercial projects. The Gulf countries deploy large fleets of cranes, loaders, and haul trucks for road building and real-estate expansion. Mining activities in South Africa, Botswana, and Ghana also drive off-the-road tire demand. Hot climates and abrasive terrains cause faster tire wear, pushing frequent replacement cycles. Increasing investments in logistics, seaports, and industrial zones support tire consumption. However, reliance on imported products and price sensitivity influence buyer preferences across several emerging markets.
Market Segmentations:
By Equipment Type:
- Wheel Balancer
- Tire Changer
By Vehicle Type:
- Two Wheelers
- Passenger Vehicle
By End User:
- Automotive Repair Shops
- Tire Service Centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Construction Equipment Tire Market features strong competition among JK Tyre & Industries Ltd., CST (Cheng Shin Tire), Continental AG, Guizhou Tyre Co., Ltd., Camso, Kenda Rubber Industrial Co., Ltd., Alliance Tire Group (ATG), Bridgestone Corporation, Carlstar, Hankook Tire, and Balkrishna Industries Limited (BKT). The Construction Equipment Tire Market is characterized by strong rivalry among global and regional manufacturers offering tires for heavy-duty machinery such as loaders, excavators, and dump trucks. Leading companies focus on advanced tread patterns, heat-resistant compounds, and high-load radial tires to enhance durability and reduce operating costs in harsh environments. Many players expand their aftermarket reach with dealer partnerships and service networks to support faster replacement cycles. Innovation in tire pressure monitoring, self-sealing technology, and retreadable designs helps differentiate premium brands from low-cost competitors. Sustainability initiatives, including recyclable rubber compounds and reduced rolling resistance, further influence purchasing decisions across major construction and mining fleets.
Key Player Analysis
- JK Tyre & Industries Ltd.
- CST (Cheng Shin Tire)
- Continental AG
- Guizhou Tyre Co., Ltd.
- Camso
- Kenda Rubber Industrial Co., Ltd.
- Alliance Tire Group (ATG)
- Bridgestone Corporation
- Carlstar
- Hankook Tire
- Balkrishna Industries Limited (BKT)
Recent Developments
- In March 2025, Continental widened its TeleMaster lineup with new pneumatic and solid non-marking tire solutions. Engineered together with JLG, the new TeleMaster V.ply provides a pneumatic option specifically designed for use in telehandlers in the United States with improved stability and comfort through V.ply technology and optimized tread design.
- In February 2024, MAXAM Tire, a global leader in specialty tire manufacturing, improved farmers' and growers' productivity by introducing the VF sizes to the AGILXTRA I-3 implement product series.
- In January 2024, The Goodyear Tire & Rubber Company introduced the GP-3E tire line to its Goodyear Off-the-Road (OTR) portfolio. The GP-3E line offers a range of sizing options and features and specially formulated tread compounds designed for extended wear and advanced abrasion resistance in various underfoot conditions.
- In October 2023, Trident launched a skid steer tire, showcasing a patented non-directional traction tread pattern. This groundbreaking design ensures outstanding performance while providing added benefits including reduced wear and lowered inventory expenses.
Report Coverage
The research report offers an in-depth analysis based on Equipment Type, Vehicle Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise as countries continue to invest in road, rail, and smart city projects.
- Adoption of radial tires will increase due to better load stability and longer service life.
- Sustainable and retreadable tires will gain preference to reduce operating costs and carbon impact.
- Smart tires with pressure and temperature monitoring will see wider use in rental and large fleets.
- Growth in mining and quarrying activities will boost heavy-duty and off-the-road tire consumption.
- Expanding rental equipment fleets will drive frequent replacement demand across developing regions.
- Manufacturers will introduce advanced tread designs for better traction on uneven and abrasive terrains.
- Digital fleet management and predictive maintenance systems will support tire performance monitoring.
- Price competition will intensify as low-cost Asian suppliers expand global distribution.
- OEM partnerships and product customization will increase to meet regional construction requirements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Construction Equipment Tire Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Construction Equipment Tire Market projected to grow between 2025 and 2032?
Which Construction Equipment Tire Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Construction Equipment Tire Market?
Who are the leading companies in the Construction Equipment Tire Market?
Which region commanded the largest share of the Construction Equipment Tire Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,554.55 million → 2032: USD 11,635.64 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Construction Equipment Tire Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Construction Equipment Tire Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Construction Equipment Tire Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Construction Equipment Tire Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Construction Equipment Tire Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Construction Equipment Tire Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Construction Equipment Tire Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Construction Equipment Tire Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,554.55 million → 2032: USD 11,635.64 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Construction Equipment Tire Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Construction Equipment Tire Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Construction Equipment Tire Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Construction Equipment Tire Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

