
Market Overview
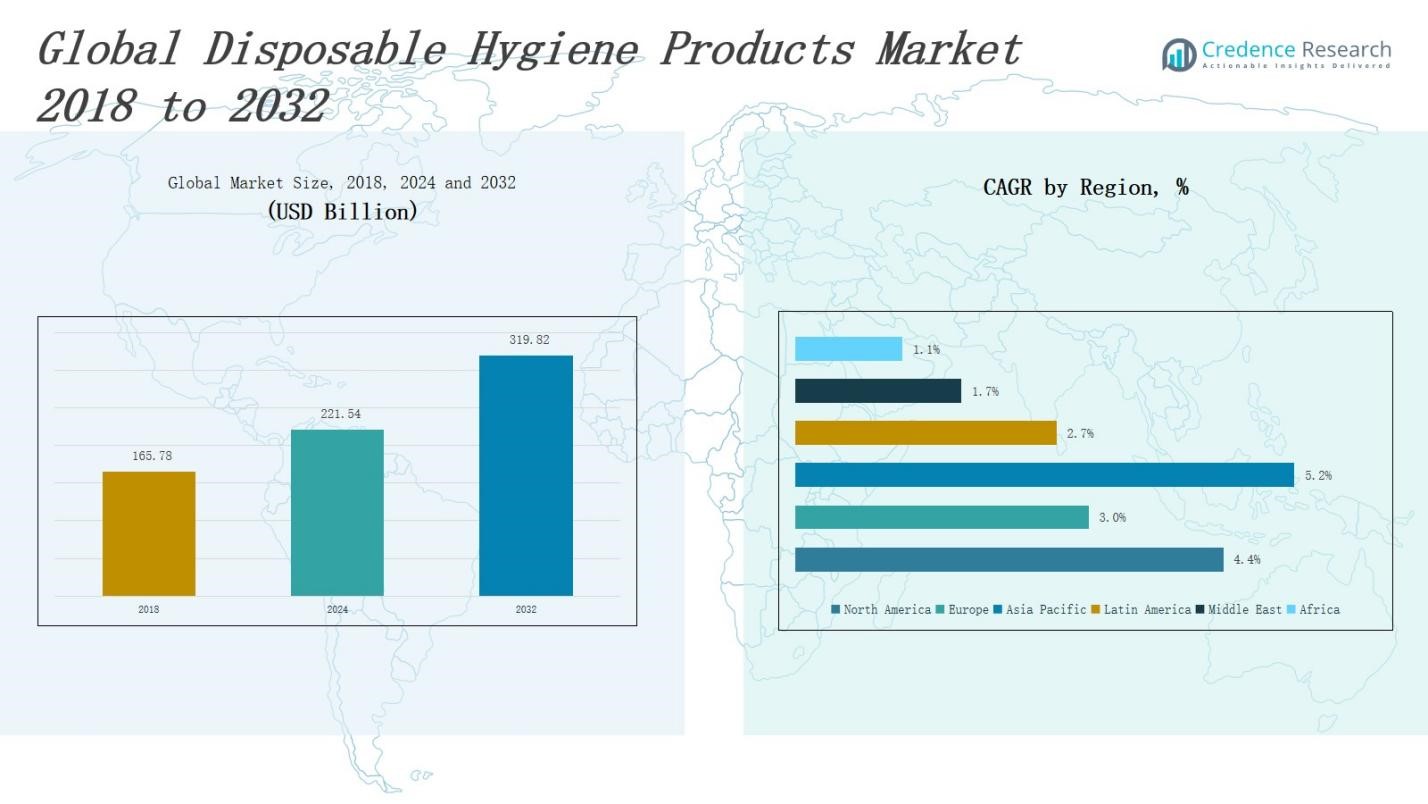
The Disposable Hygiene Products Market size was valued at USD 165.78 million in 2018 to USD 221.54 million in 2024 and is anticipated to reach USD 319.82 million by 2032, at a CAGR of 4.37% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Disposable Hygiene Products Market Size 2024 | USD 221.54 Million |
| Disposable Hygiene Products Market, CAGR | 4.37% |
| Disposable Hygiene Products Market Size 2032 | USD 319.82 Million |
The Disposable Hygiene Products Market is driven by rising awareness of personal hygiene, increasing urbanization, and growing demand for convenient, single-use solutions across baby care, feminine hygiene, and adult incontinence segments. Expanding healthcare access and a growing elderly population further support adoption. Manufacturers focus on innovations in absorbent core technologies, skin-friendly materials, and biodegradable alternatives to align with sustainability goals. E-commerce growth, along with influencer-led awareness campaigns, enhances product visibility and consumer engagement. Premiumization trends and preference for ultra-thin, odor-controlling, and organic variants continue to shape purchasing behavior in both developed and emerging markets.
The Disposable Hygiene Products Market spans North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa, with Asia Pacific leading in size and growth. North America and Europe hold significant shares due to high awareness and established retail infrastructure, while Latin America, the Middle East, and Africa offer emerging opportunities. Key players include Procter & Gamble, Kimberly-Clark, Unicharm, Essity, Ontex, Domtar, Kao, First Quality, and TZMO. These companies compete through innovation, sustainability efforts, and strategic expansion across diverse regional markets to capture evolving consumer demand.
Market Insights
- The Disposable Hygiene Products Market was valued at USD 165.78 million in 2018 and is expected to reach USD 319.82 million by 2032, growing at a CAGR of 4.37%.
- Rising hygiene awareness, urbanization, and demand for convenient, single-use products across infant, feminine, and elderly care drive consistent market growth.
- Sustainability trends encourage the use of biodegradable materials, recyclable packaging, and chemical-free alternatives in product innovation.
- Environmental concerns and waste generation challenge manufacturers to balance performance with eco-friendly design and regulatory compliance.
- North America and Europe maintain strong market shares due to premium product demand, advanced retail infrastructure, and high healthcare spending.
- Asia Pacific leads the market in size and growth, supported by rising incomes, population density, and expanding retail and e-commerce reach.
- Key players such as Procter & Gamble, Kimberly-Clark, Unicharm, Essity, and Domtar compete on product quality, sustainability, and regional expansion strategies.
Market Drivers
Rising Awareness of Hygiene and Health Among Consumers
The Disposable Hygiene Products Market is driven by heightened consumer awareness of personal cleanliness and health protection. It benefits from public health campaigns, education initiatives, and increased media coverage on hygiene practices. Consumers are prioritizing products that prevent infections, offer convenience, and promote well-being. It addresses rising demand for sanitary pads, diapers, and wipes across all age groups. The market also reflects greater emphasis on safe and effective solutions for daily hygiene needs.
- For instance, Kimberly-Clark enhanced its Huggies diapers with skin-sensitive materials and leak protection, directly addressing parental concerns for infant health and hygiene.
Expanding Urbanization and Changing Lifestyles
Urban migration and evolving lifestyles continue to boost the Disposable Hygiene Products Market. It caters to busy, time-constrained consumers who prefer convenient and easy-to-use products. Rapid urbanization contributes to better access to retail outlets and modern trade channels, encouraging frequent purchases. Working women and nuclear families favor disposable hygiene over reusable alternatives. Increasing affordability in developing economies also supports broader adoption. These changes align with the market’s growth trajectory in emerging urban centers.
- For instance, Procter & Gamble’s Always brand introduced ultra-thin sanitary pads with breathable fabrics targeting working women in cities, responding to their needs for comfort and convenience.
Growing Demand from Infant, Feminine, and Geriatric Care Segments
The Disposable Hygiene Products Market benefits from demographic trends such as rising birth rates in developing countries and a growing elderly population in developed regions. It supports diverse needs through baby diapers, feminine care, and adult incontinence products. Aging populations drive demand for discreet and comfortable solutions for bladder control. Women’s health awareness fuels demand for advanced menstrual hygiene products. Consumer preference for specialized, skin-friendly materials reinforces market expansion across age-specific segments.
Innovation in Materials and Sustainable Product Development
Continuous innovation in product design and materials strengthens the Disposable Hygiene Products Market. It focuses on high-absorbency cores, breathable fabrics, and biodegradable alternatives to meet both performance and environmental expectations. Sustainability pressures push companies to reduce plastic content and adopt recyclable packaging. Consumers seek chemical-free, hypoallergenic products, encouraging R&D investments. Brands introduce plant-based and organic variants to target health-conscious buyers. Product innovation remains a key driver of competitive advantage and customer loyalty.
Market Trends
Shift Toward Sustainable and Biodegradable Products
Consumers increasingly demand eco-friendly hygiene solutions, pushing manufacturers to innovate with biodegradable and compostable materials. The Disposable Hygiene Products Market reflects this trend through plant-based fibers, reduced plastic content, and recyclable packaging formats. Brands invest in sustainable sourcing and transparent supply chains to meet regulatory and consumer expectations. It enables companies to align with corporate ESG goals. Governments worldwide encourage green alternatives, reinforcing momentum. Eco-conscious choices are reshaping product lines and influencing purchasing decisions across regions.
- For instance, Native offers a plastic-free deodorant in a fully compostable paper-based tube with a vegan formula, merging eco-friendly packaging and mainstream appeal.
Rising Popularity of Organic and Skin-Friendly Variants
The Disposable Hygiene Products Market shows strong traction for products free from synthetic fragrances, dyes, and harmful chemicals. It caters to growing demand for hypoallergenic, dermatologically tested, and natural formulations. Consumers prioritize comfort, skin safety, and health assurance, particularly in baby care and feminine hygiene segments. Brands highlight certifications and ingredient transparency on packaging. The rise in allergic sensitivities and lifestyle-related skin concerns fuels interest in organic alternatives. This trend drives premiumization and brand differentiation in competitive markets.
- For instance, Lola offers feminine hygiene products made with 100% organic cotton, without synthetic materials, emphasizing ingredient transparency and certifications.
Expansion of E-commerce and Direct-to-Consumer Channels
E-commerce plays a pivotal role in transforming access to hygiene products, offering convenience and subscription-based models. The Disposable Hygiene Products Market benefits from direct-to-consumer strategies that promote brand loyalty and personalized customer experiences. Digital platforms support product education, reviews, and targeted promotions. It enables new brands to scale quickly without traditional retail infrastructure. Online visibility boosts awareness in rural and underserved areas. Increasing mobile penetration and digital literacy further strengthen the role of online sales in market expansion.
Integration of Advanced Absorbent and Odor-Control Technologies
Product innovation centers on performance enhancements such as high-absorbency cores, leak-proof barriers, and odor-control layers. The Disposable Hygiene Products Market embraces advanced materials that improve comfort, discretion, and wearability. It addresses user concerns around nighttime protection, travel use, and extended wear. Patented technologies help brands stand out and command premium pricing. Investments in R&D and testing facilities drive competitive advantage. Consumers reward functionality and reliability, making technological upgrades a defining trend across product categories.
Market Challenges Analysis
Environmental Concerns and Waste Management Issues
The Disposable Hygiene Products Market faces scrutiny over its environmental impact due to the large volume of non-biodegradable waste it generates. It relies heavily on plastics and superabsorbent polymers that contribute to landfill buildup and pollution. Waste management systems in many regions lack the infrastructure to handle this load responsibly. Rising public concern and environmental regulations put pressure on manufacturers to redesign products. Balancing performance with eco-friendliness remains a technical and economic challenge. Companies must address sustainability without compromising product effectiveness.
Fluctuating Raw Material Costs and Supply Chain Disruptions
Volatility in raw material prices poses a significant challenge for the Disposable Hygiene Products Market. It depends on stable supplies of cellulose, synthetic fibers, and packaging materials, which are subject to market swings and geopolitical instability. Supply chain disruptions from global events, trade restrictions, or transportation delays can impact production timelines and profitability. Price-sensitive consumers in emerging markets may switch to lower-cost alternatives. Maintaining consistent quality while controlling costs requires agile sourcing and operational efficiency.
Market Opportunities
Untapped Growth Potential in Emerging Economies
Expanding access to hygiene products in developing regions presents strong growth opportunities for the Disposable Hygiene Products Market. It benefits from rising income levels, urbanization, and improving awareness of health and sanitation. Government initiatives and NGO campaigns support distribution and education, especially in rural areas. Increasing retail penetration and mobile connectivity enable product availability through both traditional and digital channels. Localized product development based on cultural preferences strengthens brand acceptance. These factors create long-term potential for volume growth and market entry.
Rising Demand for Customized and Gender-Inclusive Products
Consumers increasingly seek personalized hygiene solutions tailored to specific needs, lifestyles, and demographics. The Disposable Hygiene Products Market can capitalize on this by offering gender-inclusive, age-specific, and activity-focused products. It supports innovation in discreet packaging, ergonomic design, and product sizing. Trends in unisex hygiene products and inclusive marketing appeal to younger, socially conscious consumers. Brands can leverage data analytics to develop targeted offerings and strengthen customer relationships. Customization enables differentiation and opens premium pricing opportunities.
Market Segmentation Analysis:
By Product Type
The Disposable Hygiene Products Market includes key categories such as baby diapers, feminine hygiene products, adult incontinence products, wet wipes, and disposable underpads. Baby diapers lead in terms of volume, driven by high birth rates in developing nations and product innovations. Feminine hygiene products show steady growth with rising awareness and increased disposable income among women. Adult incontinence products gain traction due to aging populations in developed regions. Wet wipes and under pads expand rapidly in both personal and institutional use cases.
- For instance, Ontex’s Dreamshield 360º baby pants, which incorporate triple leakage barriers and patented SeconDRY technology, gaining strong retail demand in Europe for superior night protection and comfort.
By Material
Material selection plays a vital role in product performance and sustainability in the Disposable Hygiene Products Market. Nonwoven fabrics and superabsorbent polymers dominate due to their high absorbency and comfort. Cotton usage grows in premium and organic segments, appealing to health-conscious consumers. Plastic resins remain prevalent in mainstream products but face scrutiny for environmental impact. Biodegradable materials present growth potential in response to rising demand for eco-friendly alternatives across product lines.
- For instance, BioSAP has developed biodegradable superabsorbent polymers (AHPs) that are biocompatible and degrade more easily than conventional synthetic polymers, addressing environmental concerns while maintaining high absorbency.
By End User
The Disposable Hygiene Products Market serves a wide range of users including infants, women, men, elderly populations, and healthcare institutions. Infants and women represent the largest user base due to consistent demand for baby care and menstrual hygiene products. The elderly population contributes significantly to the adult incontinence segment, especially in aging societies. Healthcare institutions use underpads and wipes in patient care, creating bulk demand. Growing male awareness of personal hygiene also supports market expansion.
Segments:
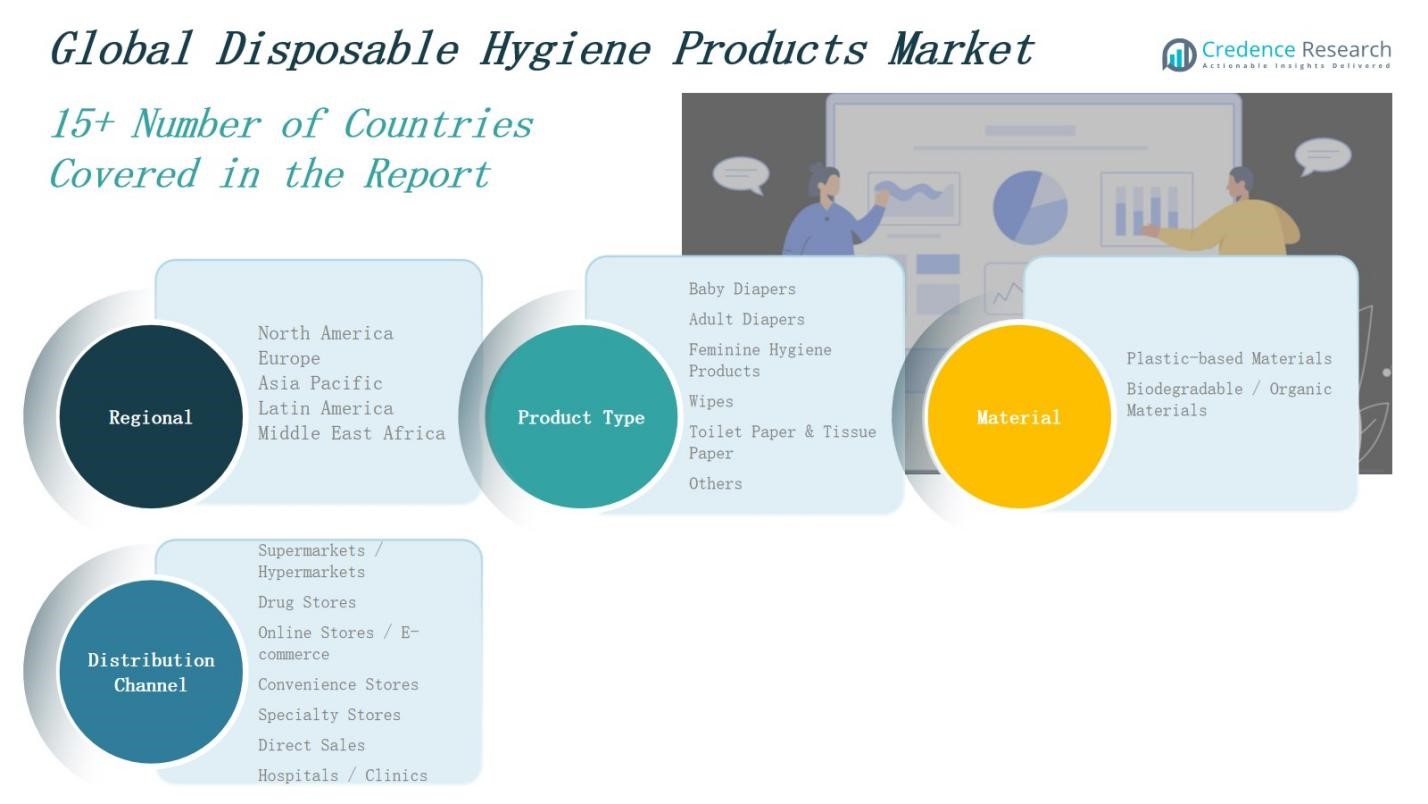
Based on Product Type:
- Baby Diaper
- Feminine Hygiene Products (Sanitary Pads, Panty Liners, Tampons)
- Adult Incontinence Products (Pads, Diapers, Liners)
- Wet Wipes
- Disposable Underpads
Based on Material:
- Cotton
- Superabsorbent Polymers
- Nonwoven Fabrics
- Plastic Resins
- Biodegradable Materials
Based on End User:
- Infants
- Women
- Men
- Elderly Population
- Healthcare Institutions
Based on Distribution Channel:
- Supermarkets/Hypermarkets
- Pharmacies & Drug Stores
- Convenience Store
- Online Retail/E-commerce
- Specialty Stores
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Disposable Hygiene Products Market size was valued at USD 52.09 billion in 2018 to USD 68.61 billion in 2024 and is anticipated to reach USD 99.43 billion by 2032, at a CAGR of 4.4% during the forecast period. North America holds the second-largest market share globally due to high awareness of hygiene, strong purchasing power, and widespread product availability. It benefits from a well-established retail network and high adoption of adult incontinence and feminine hygiene products. Consumers demand premium, eco-friendly solutions, prompting innovation in sustainable materials and packaging. The U.S. leads the regional market, supported by healthcare institutions and aging population. Product personalization and online distribution further support market expansion.
Europe
The Europe Disposable Hygiene Products Market size was valued at USD 28.88 billion in 2018 to USD 36.33 billion in 2024 and is anticipated to reach USD 47.33 billion by 2032, at a CAGR of 3.0% during the forecast period. Europe maintains a significant market share with strict regulations on product safety and environmental sustainability. It shows steady growth due to widespread use of biodegradable and organic hygiene products. Germany, France, and the U.K. contribute majorly to sales. Consumer preference leans toward chemical-free, skin-friendly materials. Strong retail infrastructure and healthcare expenditure drive the demand across adult and infant care categories.
Asia Pacific
The Asia Pacific Disposable Hygiene Products Market size was valued at USD 70.99 billion in 2018 to USD 98.45 billion in 2024 and is anticipated to reach USD 150.96 billion by 2032, at a CAGR of 5.2% during the forecast period. Asia Pacific leads the global market in volume and growth rate, driven by large population, rising incomes, and urbanization. It sees increasing demand for baby diapers, feminine care, and wet wipes, especially in China, India, and Southeast Asia. Growing awareness, improved retail access, and government health initiatives fuel adoption. Domestic and international brands invest in localization and pricing strategies. Online platforms play a key role in expanding rural market reach.
Latin America
The Latin America Disposable Hygiene Products Market size was valued at USD 7.48 billion in 2018 to USD 9.87 billion in 2024 and is anticipated to reach USD 12.53 billion by 2032, at a CAGR of 2.7% during the forecast period. Latin America shows moderate growth supported by increasing hygiene awareness and improving distribution networks. Brazil and Mexico dominate the market with rising consumption of sanitary pads, diapers, and wipes. Affordability influences purchasing decisions, encouraging demand for economy products. Government programs promote hygiene education, especially in rural areas. Local manufacturing capabilities and private label brands support price competitiveness and accessibility.
Middle East
The Middle East Disposable Hygiene Products Market size was valued at USD 4.00 billion in 2018 to USD 4.81 billion in 2024 and is anticipated to reach USD 5.67 billion by 2032, at a CAGR of 1.7% during the forecast period. The Middle East market grows slowly but steadily, driven by demand for premium hygiene products in urban areas. It benefits from strong presence of international brands in countries like UAE and Saudi Arabia. High-income consumers prefer ultra-thin, organic, and fragrance-free variants. Product adoption in baby care and feminine hygiene segments remains consistent. E-commerce expansion supports access in less-developed parts of the region.
Africa
The Africa Disposable Hygiene Products Market size was valued at USD 2.34 billion in 2018 to USD 3.48 billion in 2024 and is anticipated to reach USD 3.91 billion by 2032, at a CAGR of 1.1% during the forecast period. Africa holds the smallest share but offers long-term potential as income levels and awareness rise. The market faces challenges in affordability, distribution, and cultural taboos, particularly in rural areas. South Africa, Nigeria, and Kenya are key markets showing gradual growth. NGOs and global health organizations promote education and access to basic hygiene products. Local production initiatives help address supply gaps and lower costs.
Key Player Analysis
- Edgewell Personal Care
- Kao Corporation
- TZMO SA
- Unicharm Corporation
- Daio Paper Corporation
- Domtar Corporation
- The Honest Company, Inc.
- Hengan International Group Company Limited
- First Quality Enterprises, Inc.
- Kimberly-Clark Corporation
- Abena A/S
- Essity AB
- Johnson & Johnson
- Ontex Group NV
- Procter & Gamble Co.
Competitive Analysis
The Disposable Hygiene Products Market features intense competition driven by global brands and regional manufacturers. It includes key players such as Procter & Gamble, Kimberly-Clark, Unicharm, and Essity, which dominate through strong brand portfolios, advanced R&D, and widespread distribution. Companies focus on innovation in absorbent technologies, skin-friendly materials, and sustainable packaging to differentiate offerings. Private labels and regional firms compete on pricing and localized preferences. E-commerce expansion enables smaller brands to scale quickly and reach underserved areas. Strategic mergers, acquisitions, and product launches support market positioning. Players invest in marketing campaigns and consumer education to build loyalty and expand customer base. Multinational corporations are enhancing their presence in high-growth regions through joint ventures and distribution partnerships. Continuous investment in automation and manufacturing efficiency helps improve margins. Competitive dynamics are also influenced by changing consumer expectations, regulatory requirements, and the growing importance of environmentally responsible product lines across all market tiers.
Recent Developments
- In June 2025, TSG Consumer, a San Francisco-based investment firm, entered a strategic partnership with Dude Wipes, a growing brand in disposable hygiene wipes.
- In September 2024, DOMS Industries finalized the acquisition of a 51.77% stake in Uniclan Healthcare, marking their entry into the baby hygiene products market, according to multiple news sources.
- In May 2023, Niine Sanitary Napkins (India) launched India’s first biodegradable sanitary pads made from PLA (polylactic acid), certified by CIPET, decomposing over 90% within 175 days.
- On October 12, 2024, Good Glamm Group acquired Sirona Hygiene in a ₹450 crore deal, expanding its presence in the feminine hygiene segment in India.
Market Concentration & Characteristics
The Disposable Hygiene Products Market exhibits moderate to high market concentration, with a few dominant multinational companies controlling a significant share. It includes established players like Procter & Gamble, Kimberly-Clark, Unicharm, and Essity, which lead through extensive global distribution, strong brand equity, and continuous product innovation. The market also features regional manufacturers and private labels that offer competitive pricing and localized products. It shows strong brand loyalty in mature markets and growing price sensitivity in emerging regions. Innovation, regulatory compliance, and sustainability shape competitive dynamics. The Disposable Hygiene Products Market relies on advancements in materials, absorption technology, and eco-friendly packaging to address evolving consumer preferences. E-commerce and direct-to-consumer strategies influence distribution models, allowing smaller players to enter niche segments. The market is driven by demographics, lifestyle shifts, and rising health awareness. Its long-term growth depends on affordability, access in underserved areas, and the ability of brands to balance performance with environmental responsibility.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, End-User, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for biodegradable and compostable hygiene products will grow due to rising environmental concerns.
- Innovation in superabsorbent and breathable materials will improve comfort and product performance.
- Online retail channels will expand market access, especially in rural and semi-urban areas.
- Customized hygiene solutions will gain popularity among age-specific and gender-inclusive consumer segments.
- Private label brands will strengthen presence by offering affordable alternatives in developing markets.
- Healthcare facilities will increase procurement of adult incontinence and sanitary products.
- Companies will invest more in local manufacturing to reduce costs and improve supply chain resilience.
- Emerging markets in Africa, Latin America, and Southeast Asia will drive future volume growth.
- Marketing campaigns will focus on hygiene education and destigmatizing personal care topics.
- Regulatory pressure will push manufacturers to adopt safer ingredients and sustainable packaging formats.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Awareness of Hygiene and Health
Increased public health campaigns, education, and media coverage have heightened consumer focus on personal cleanliness and infection prevention, boosting demand for disposable hygiene products across all age groups.
Expanding Urbanization and Changing Lifestyles
Urban migration and busier lifestyles drive preference for convenient, single-use hygiene solutions, with better access to modern retail and e-commerce channels supporting frequent purchases, especially among working women and nuclear families.
Innovation in Materials and Sustainable Product Development
Continuous advancements in absorbent core technologies, skin-friendly materials, and biodegradable alternatives address both performance and environmental concerns, attracting health-conscious and eco-aware consumers.
Demographic Shifts in Infant, Feminine, and Elderly Care
Rising birth rates in developing countries and aging populations in developed regions fuel demand for baby diapers, feminine hygiene, and adult incontinence products, expanding the market’s user base.
Growth of E-commerce and Direct-to-Consumer Channels
The expansion of online retail and subscription models increases product accessibility, especially in rural and underserved areas, while enabling brands to educate consumers and build loyalty through digital engagement.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Disposable Hygiene Products Market?
What factors are driving the growth of the Disposable Hygiene Products Market?
What are the key segments within the Disposable Hygiene Products Market?
What are some challenges faced by the Disposable Hygiene Products Market?
Who are the major players in the Disposable Hygiene Products Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Infants
- 1.2.2 Women
- 1.2.3 Men
- 1.2.4 Elderly Population
- 1.2.5 Healthcare Institutions
- 1.3 By Material
- 1.3.1 Cotton
- 1.3.2 Superabsorbent Polymers
- 1.3.3 Nonwoven Fabrics
- 1.3.4 Plastic Resins
- 1.3.5 Biodegradable Materials
- 1.4 By Product Type
- 1.4.1 Baby Diaper
- 1.4.2 Feminine Hygiene Products (Sanitary Pads, Panty Liners, Tampons)
- 1.4.3 Adult Incontinence Products (Pads, Diapers, Liners)
- 1.4.4 Wet Wipes
- 1.4.5 Disposable Underpads
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 221.54 million → 2032: USD 319.82 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Disposable Hygiene Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Disposable Hygiene Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Disposable Hygiene Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Disposable Hygiene Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Disposable Hygiene Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Disposable Hygiene Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Disposable Hygiene Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Disposable Hygiene Products Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 221.54 million → 2032: USD 319.82 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Disposable Hygiene Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Infants
- 12.3.7.2 Women
- 12.3.7.3 Men
- 12.3.7.4 Elderly Population
- 12.3.7.5 Healthcare Institutions
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cotton
- 12.4.7.2 Superabsorbent Polymers
- 12.4.7.3 Nonwoven Fabrics
- 12.4.7.4 Plastic Resins
- 12.4.7.5 Biodegradable Materials
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Baby Diaper
- 12.5.7.2 Feminine Hygiene Products (Sanitary Pads, Panty Liners, Tampons)
- 12.5.7.3 Adult Incontinence Products (Pads, Diapers, Liners)
- 12.5.7.4 Wet Wipes
- 12.5.7.5 Disposable Underpads
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Disposable Hygiene Products End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Disposable Hygiene Products Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Disposable Hygiene Products Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Disposable Hygiene Products Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Procter & Gamble Co.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kimberly-Clark Corporation
- 18.4 Unicharm Corporation
- 18.5 Essity AB
- 18.6 Domtar Corporation
- 18.7 Kao Corporation
- 18.8 Ontex Group NV
- 18.9 First Quality Enterprises, Inc.
- 18.10 TZMO SA
- 18.11 Edgewell Personal Care
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

