
Market Overview
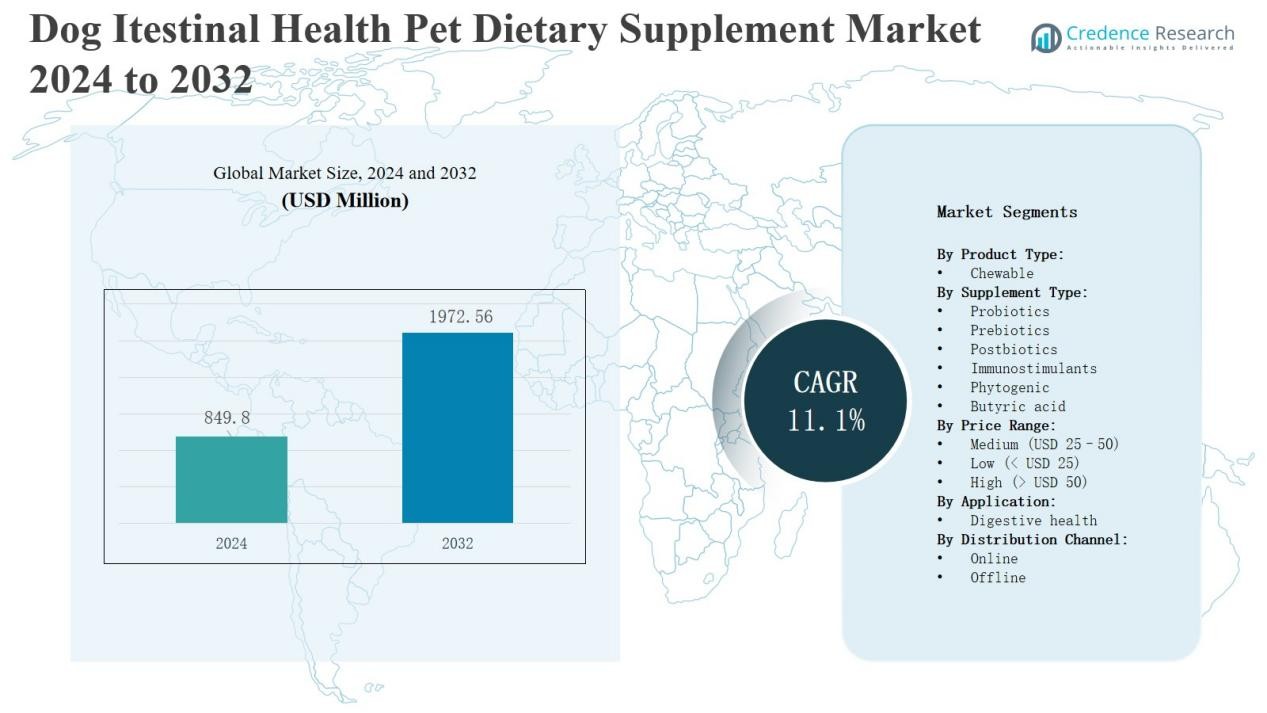
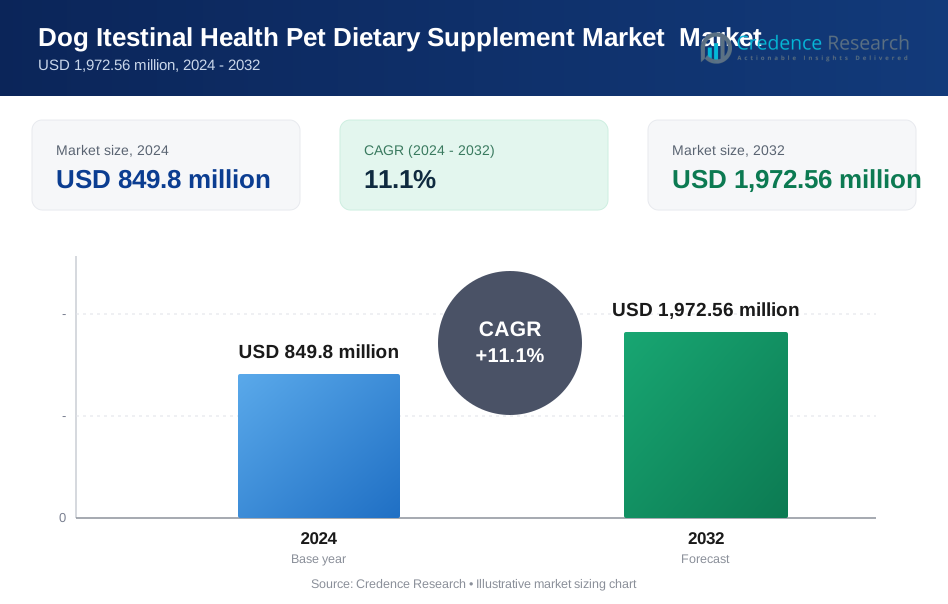
Dog Intestinal Health Pet Dietary Supplement Market size was valued at USD 849.8 million in 2024 and is anticipated to reach USD 1,972.56 million by 2032, at a CAGR of 11.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dog Intestinal Health Pet Dietary Supplement Market Size 2024 | USD 849.8 Million |
| Dog Intestinal Health Pet Dietary Supplement Market, CAGR | 11.1% |
| Dog Intestinal Health Pet Dietary Supplement Market Size 2032 | USD 1,972.56 Million |
The dog intestinal health pet dietary supplement market is driven by strong competition among key players such as Mars Petcare Inc., Hill’s Pet Nutrition, Inc., Boehringer Ingelheim Vetmedica, Inc., Elanco, Nestlé, BASF SE, K9 Natural Ltd., Ark Naturals Inc., Dr. Harvey’s LLC, and Nutritional Veterinary Care, Inc. These companies focus on research-based formulations featuring probiotics, prebiotics, and natural ingredients to enhance canine digestive health and immunity. Strategic initiatives, including product innovation, veterinary collaborations, and digital marketing, strengthen their global reach and brand visibility. North America leads the market with a 38% share in 2024, supported by high pet ownership, strong veterinary infrastructure, and growing awareness of microbiome-based nutrition among dog owners.
Market Insights
- The Dog Intestinal Health Pet Dietary Supplement Market was valued at USD 849.8 million in 2024 and is projected to reach USD 1,972.56 million by 2032, growing at a CAGR of 11.1%.
- The chewable segment held the largest share of 72% in 2024, supported by ease of use, flavor appeal, and high absorption that improve compliance among dogs.
- The probiotics segment led the market with a 41% share in 2024, driven by rising awareness of gut microbiome health and increased veterinary recommendations.
- The medium price range category (USD 25–50) accounted for 54% of total sales in 2024, appealing to consumers seeking affordable yet high-quality supplement options.
- North America dominated with a 38% share in 2024, benefiting from strong pet ownership, advanced veterinary infrastructure, and growing awareness of canine digestive wellness.
Market Segment Insights
By Product Type
The chewable segment dominates the dog intestinal health pet dietary supplement market, holding a 72% share in 2024. Its dominance is due to high palatability, ease of administration, and better absorption. Pet owners prefer chewable forms for their convenience and flavor variety, which enhances compliance among dogs. Manufacturers focus on soft-chew formulations enriched with probiotics and vitamins to support gut health, improving digestive balance and overall pet wellness.
- For instance, Purina launched its Pro Plan Veterinary Supplements Calming Care Chews, featuring a proprietary strain of Bifidobacterium longum BL999 aimed at improving gut microbiome stability and digestive comfort in dogs.
By Supplement Type
The probiotics segment leads the market with a 41% share, driven by growing awareness of gut microbiome health in dogs. Probiotic supplements aid digestion, enhance immunity, and reduce gastrointestinal issues like bloating and diarrhea. Increasing recommendations by veterinarians and rising premium pet care spending strengthen demand. Innovations in multi-strain formulations and long shelf-life products further boost the segment’s growth across online and offline retail platforms.
- For instance, Zesty Paws launched its Probiotic Bites Advanced formula, featuring six probiotic strains designed to support gut function and nutrient absorption.
By Price Range
The medium price range segment (USD 25–50) accounts for 54% of the market share in 2024. This range offers a balance between product quality and affordability, appealing to most pet owners. Products in this range often feature scientifically tested ingredients and trusted brands. Expanding e-commerce channels and the preference for premium yet cost-effective supplements drive steady sales growth in this category across North America and Europe.
Key Growth Drivers
Rising Awareness of Canine Gut Health
Growing awareness of the link between gut health and overall well-being drives market demand. Pet owners increasingly recognize digestive balance as essential for nutrient absorption, immune strength, and mood regulation. Social media, veterinary campaigns, and premium pet food brands promote probiotic and prebiotic benefits. This rising awareness encourages regular supplement use, fueling consistent sales growth for chewable and powder-based products designed to improve intestinal microbiota and digestive comfort in dogs.
- For instance, Nestlé Purina introduced its Pro Plan Veterinary Supplements FortiFlora SA Synbiotic Action in the U.S., formulated with probiotics and prebiotics to support canine digestive and immune health.
Expanding Pet Humanization and Premiumization Trends
The ongoing humanization of pets encourages owners to treat dogs like family members, increasing spending on preventive healthcare. Owners are prioritizing specialized nutritional supplements for gut health similar to human wellness routines. Premiumization trends further boost demand for scientifically backed formulations containing natural and organic ingredients. This behavioral shift fosters strong market growth, especially in developed markets such as North America and Western Europe, where disposable incomes and pet care awareness remain high.
- For instance, Chewy has embraced pet humanization by referring to pet owners as "parents," implementing personalized customer engagements like sending painted pet portraits and condolence cards, which underscore the emotional connection driving premium pet product sales.
Veterinary Endorsements and E-Commerce Expansion
Veterinary professionals play a crucial role in recommending intestinal health supplements. Their endorsement enhances consumer trust and product credibility. Simultaneously, the rise of e-commerce platforms offers wider product access and personalized subscription models. Online retail allows brands to target specific digestive concerns through digital marketing and data analytics. The combined impact of expert recommendations and digital convenience strengthens market expansion and encourages frequent repurchases among pet owners worldwide.
Key Trends & Opportunities
Innovation in Microbiome-Based Formulations
Manufacturers are investing in microbiome research to develop advanced formulations combining probiotics, prebiotics, and postbiotics. These blends offer comprehensive digestive support by restoring gut flora balance and improving immunity. Brands are introducing strain-specific products targeting different digestive issues, such as diarrhea or food intolerance. This innovation presents significant opportunities for differentiation, especially as consumers seek clinically proven, science-based supplements tailored to canine digestive health and long-term wellness.
- For instance, Probiotics International Limited introduced a prebiotic formula designed to selectively nourish beneficial gut bacteria, enhancing microbial diversity and digestive wellness in dogs.
Growing Demand for Natural and Functional Ingredients
Pet owners increasingly prefer supplements made from clean-label and plant-based ingredients. Phytogenic additives, butyric acid, and herbal extracts are gaining traction for their anti-inflammatory and gut-protective effects. The shift toward natural formulations aligns with sustainability goals and transparency expectations. Brands focusing on organic sourcing and minimal additives are well-positioned to attract health-conscious consumers seeking safer, eco-friendly intestinal health supplements for their pets.
- For instance, Vitalus offers VitaGOS, a patented natural prebiotic derived from dairy that supports gut health while maintaining palatability across various product formulations.
Key Challenges
High Product Cost and Limited Affordability
Premium dog intestinal health supplements often carry high production costs due to specialized ingredients and quality assurance standards. This makes them less accessible to cost-sensitive consumers, particularly in developing regions. The price gap between low-cost and high-end supplements restricts wider adoption. Manufacturers must balance affordability and efficacy to expand their customer base while maintaining profitability in competitive markets.
Lack of Standardization and Quality Regulation
The absence of uniform global standards for pet dietary supplements poses quality and efficacy challenges. Variations in ingredient labeling, dosage accuracy, and microbial safety reduce consumer confidence. Some unregulated products make unverified claims, leading to skepticism among pet owners. Strengthening industry guidelines and ensuring veterinary validation are essential to build trust and maintain consistent market growth in the intestinal health supplement segment.
Limited Veterinary Awareness in Emerging Markets
In developing countries, many veterinarians lack training or awareness of advanced canine nutritional therapies. This limits professional recommendations and reduces market penetration. Without veterinary guidance, pet owners often rely on unverified online information or generic supplements, which may not address specific gut issues. Expanding educational programs and collaborations with veterinary associations are key to overcoming this awareness gap and driving product adoption.
Regional Analysis
North America
North America dominates the dog intestinal health pet dietary supplement market with a 38% share in 2024. The region’s growth is supported by high pet ownership, premiumization trends, and strong veterinary infrastructure. Consumers are well-informed about digestive wellness, driving demand for probiotic and prebiotic supplements. The United States leads due to a mature pet healthcare industry and presence of leading brands focusing on functional formulations. Expanding online retail networks further enhance accessibility. It continues to benefit from rising awareness of microbiome health in companion animals.
Europe
Europe holds a 27% share of the market, driven by widespread adoption of premium pet care products and regulatory emphasis on animal nutrition quality. Countries such as Germany, France, and the United Kingdom promote probiotic supplements for digestive and immune support. Growing humanization of pets and sustainable ingredient sourcing drive market expansion. It also benefits from innovation in postbiotic and phytogenic formulations. Rising consumer preference for clean-label supplements ensures strong regional performance and steady long-term demand.
Asia Pacific
Asia Pacific accounts for 22% of the market share, supported by rapid pet population growth and urbanization. Countries such as China, Japan, and India show increasing adoption of gut health supplements due to rising disposable incomes and improved veterinary awareness. Domestic brands are expanding product portfolios, offering affordable and natural formulations to attract middle-income consumers. It benefits from the growing e-commerce ecosystem and online education on pet wellness. Rising pet expenditure trends indicate strong future market potential across the region.
Latin America
Latin America captures a 7% share, with Brazil and Mexico leading market growth. Rising pet adoption and increasing attention to preventive healthcare drive supplement consumption. Veterinary recommendations and social media influence are encouraging awareness of digestive health products. It is witnessing a gradual transition toward premium and functional formulations. Expanding retail distribution and entry of international brands further enhance market visibility and accessibility in key urban areas.
Middle East & Africa
The Middle East & Africa region holds a 6% share, supported by rising pet ownership and growing awareness of digestive health. Countries such as the United Arab Emirates and South Africa are emerging as key growth markets. The market is still developing, with limited product availability and price-sensitive consumers. International manufacturers are introducing targeted probiotic and prebiotic products through online platforms. It shows gradual improvement driven by expanding veterinary services and growing interest in pet nutrition.
Market Segmentations:
By Product Type:
- Chewable
By Supplement Type:
- Probiotics
- Prebiotics
- Postbiotics
- Immunostimulants
- Phytogenic
- Butyric acid
By Price Range:
- Medium (USD 25–50)
- Low (< USD 25)
- High (> USD 50)
By Application:
- Digestive health
By Distribution Channel:
- Online
- Offline
By Region:
- North America
-
- USA
- Canada
- Mexico
- Latin America
-
- Brazil
- Chile
- Rest of Latin America
- Western Europe
-
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- Eastern Europe
-
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- East Asia
-
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- Middle East & Africa
-
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Competitive Landscape
The competitive landscape of the dog intestinal health pet dietary supplement market is characterized by strong product innovation, brand differentiation, and expanding distribution channels. Leading companies such as Mars Petcare Inc., Hill’s Pet Nutrition, Inc., Boehringer Ingelheim Vetmedica, Inc., Elanco, and Nestlé focus on research-driven formulations to enhance digestive health and immunity. These players invest in probiotics, prebiotics, and natural ingredient blends to meet rising consumer demand for scientifically validated products. Emerging brands like Ark Naturals Inc., K9 Natural Ltd., and Dr. Harvey’s LLC emphasize clean-label and holistic nutrition approaches, appealing to health-conscious pet owners. BASF SE supports industry growth by supplying essential raw materials and functional additives. Strategic partnerships with veterinary clinics and e-commerce expansion strengthen brand reach and customer engagement. It remains a highly competitive market driven by continuous innovation, premiumization, and the growing focus on gut microbiome wellness in companion animals.
Key Players
- K9 Natural Ltd.
- BASF SE
- Nutritional Veterinary Care, Inc.
- Ark Naturals Inc
- Boehringer Ingelheim Vetmedica, Inc.
- Hill’s Pet Nutrition, Inc.
- Harvey’s LLC
- Mars Petcare Inc.
- Elanco
- Nestle
Recent Developments
- In August 2025, Native Pet launched Gutwell™, a new gut-microbiome supplement line designed to improve canine digestive balance.
- In January 2025, Pooch & Mutt acquired BIOME9, a gut-health testing and supplement company, expanding its presence in the functional pet nutrition sector.
- In April 2025, Grizzly Pet Products introduced a liquid gut health supplement formulated with EpiCor® postbiotic to enhance immunity and digestive wellness in dogs.
- In July 2024, Vetnique Labs acquired Lintbells, a supplement manufacturer known for its digestive and wellness products for pets.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Supplement Type, Price Range, Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow with rising awareness of gut health among pet owners.
- Demand for natural and probiotic-based supplements will continue to expand.
- Companies will focus on developing breed-specific and age-specific formulations.
- Online retail channels will play a key role in future sales growth.
- Veterinary recommendations will increasingly influence consumer purchase choices.
- Partnerships between supplement brands and pet clinics will strengthen market presence.
- Research on prebiotics and postbiotics will drive new product innovations.
- Premium product lines emphasizing organic ingredients will gain popularity.
- Expansion in emerging markets will provide new revenue opportunities for manufacturers.
- Technological integration in packaging and dosage tracking will enhance product reliability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the dog intestinal health pet dietary supplement market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the dog intestinal health pet dietary supplement market projected to grow between 2025 and 2032?
Which dog intestinal health pet dietary supplement market segment held the largest share in 2024?
What are the primary factors fueling the growth of the dog intestinal health pet dietary supplement market?
Who are the leading companies in the dog intestinal health pet dietary supplement market?
Which region commanded the largest share of the dog intestinal health pet dietary supplement market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Dog Itestinal Health Pet Dietary Supplement Market Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Dog Itestinal Health Pet Dietary Supplement Market Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 849.8 million → 2032: USD 1,972.56 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Dog Itestinal Health Pet Dietary Supplement Market Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Dog Itestinal Health Pet Dietary Supplement Market Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Dog Itestinal Health Pet Dietary Supplement Market Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Dog Itestinal Health Pet Dietary Supplement Market Market Drivers
- 3.3 Dog Itestinal Health Pet Dietary Supplement Market Market Restraints & Challenges
- 3.4 Dog Itestinal Health Pet Dietary Supplement Market Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Dog Itestinal Health Pet Dietary Supplement Market Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Dog Itestinal Health Pet Dietary Supplement Market Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Dog Itestinal Health Pet Dietary Supplement Market category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Dog Itestinal Health Pet Dietary Supplement Market Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Dog Itestinal Health Pet Dietary Supplement Market Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Dog Itestinal Health Pet Dietary Supplement Market market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Dog Itestinal Health Pet Dietary Supplement Market Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Dog Itestinal Health Pet Dietary Supplement Market Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Dog Itestinal Health Pet Dietary Supplement Market Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Dog Itestinal Health Pet Dietary Supplement Market (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Dog Itestinal Health Pet Dietary Supplement Market Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Dog Itestinal Health Pet Dietary Supplement Market Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Dog Itestinal Health Pet Dietary Supplement Market Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Dog Itestinal Health Pet Dietary Supplement Market Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Dog Itestinal Health Pet Dietary Supplement Market Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Dog Itestinal Health Pet Dietary Supplement Market Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Dog Itestinal Health Pet Dietary Supplement Market Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Dog Itestinal Health Pet Dietary Supplement Market Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Dog Itestinal Health Pet Dietary Supplement Market Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
