
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Drone Camera Market Size 2024 | USD 15,490.71 million |
| Drone Camera Market, CAGR | 30.90% |
| Drone Camera Market Size 2032 | USD 133,532.93 million |
Market Overview:
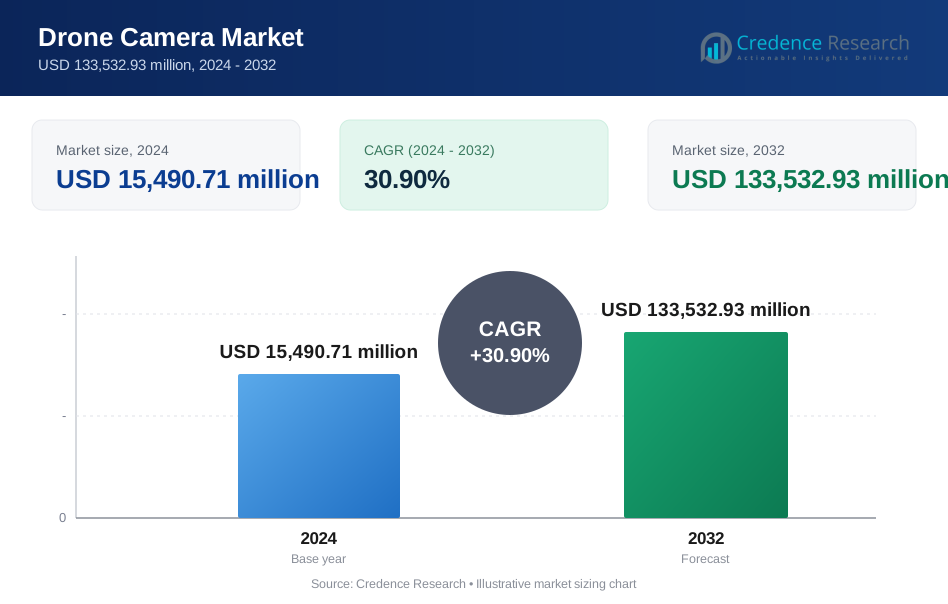
The global Drone Camera Market is set to experience explosive growth, with its market size projected to expand from USD 15,490.71 million in 2024 to USD 133,532.93 million by 2032, reflecting an impressive compound annual growth rate (CAGR) of 30.90% over the forecast period.
This rapid expansion is driven by the increasing adoption of drone cameras across various industries, including agriculture, construction, media, and defence. The versatility of drone cameras, offering high-resolution imaging and video capabilities, is revolutionizing sectors that rely on aerial data and imagery. Additionally, the growing use of drones in commercial applications, such as logistics and inspection services, further contributes to the market's dynamic growth.
Several key factors are driving the growth of the Drone Camera Market. The advancements in drone technology, particularly in terms of enhanced camera resolution, stability, and range, are making drones more effective and accessible for a wide range of professional applications. For instance, in agriculture, drone cameras are increasingly used for crop monitoring and precision farming, allowing farmers to optimize yields and reduce costs. In the construction and real estate sectors, drones provide detailed aerial views that facilitate project management and property inspections. Moreover, the rising demand for drones in the media and entertainment industry, driven by the need for innovative content creation, is also a significant driver of market growth. Furthermore, regulatory developments and government support for the commercial use of drones are enabling broader adoption across industries.
Regionally, North America is expected to dominate the Drone Camera Market, accounting for the largest market share due to its early adoption of drone technology and the presence of key players in the region. The United States, in particular, leads the market, driven by strong demand from the defence, agriculture, and media sectors. Europe follows closely, with countries like the United Kingdom, Germany, and France contributing significantly to market growth through their advanced industrial and commercial drone applications. The Asia-Pacific region is anticipated to witness the fastest growth, propelled by the increasing use of drones in agriculture, logistics, and infrastructure development in countries such as China, Japan, and India. The Rest of the World, including Latin America and the Middle East, is also expected to see substantial growth as drone technology becomes more accessible and integrated into various industries globally.
Market Drivers:
Technological Advancements in Drone Capabilities:
The rapid advancement of drone technology is a primary driver of the Drone Camera Market. Innovations in camera resolution, image stabilization, and flight control systems have significantly enhanced the functionality and appeal of drone cameras. For instance, leading companies are now offering drones equipped with 4K and even 8K cameras, providing ultra-high-definition video and imagery that were previously only possible with manned aircraft. Additionally, improvements in battery life and range allow drones to cover larger areas and operate for extended periods, making them more versatile for various professional applications.
Increasing Adoption in Agriculture and Precision Farming:
Drone cameras are becoming indispensable tools in the agriculture industry, particularly for precision farming. The ability to capture detailed aerial imagery allows farmers to monitor crop health, assess soil conditions, and manage irrigation more effectively. For instance, drones equipped with multispectral and thermal cameras can identify issues such as pest infestations or water stress before they become critical, enabling timely interventions. This adoption of drone technology in agriculture is driven by the need to optimize yields, reduce input costs, and increase overall efficiency in food production.
Expanding Applications in Construction and Real Estate:
The construction and real estate sectors are increasingly utilizing drone cameras for a variety of purposes, including site surveying, project monitoring, and property inspections. For example, drones provide detailed aerial views that can be used to create accurate 3D models of construction sites, track progress over time, and identify potential issues early in the building process. In real estate, drones offer prospective buyers’ unique perspectives of properties, enhancing marketing efforts and providing valuable insights that traditional photography cannot match. This growing reliance on drones in these sectors is a significant driver of market growth.
Government Support and Regulatory Developments:
Government support and evolving regulations are also critical factors driving the Drone Camera Market. Many countries are developing frameworks to regulate the commercial use of drones, making it easier for businesses to integrate this technology into their operations. For instance, the Federal Aviation Administration (FAA) in the United States has implemented rules that allow for the broader use of drones in commercial activities, such as inspections, deliveries, and surveillance. These regulatory advancements, coupled with government initiatives to promote the use of drones in public services like emergency response and infrastructure monitoring, are encouraging wider adoption across industries.
Market Trends:
Integration of Artificial Intelligence and Machine Learning:
A significant trend in the Drone Camera Market is the integration of artificial intelligence (AI) and machine learning (ML) technologies. These advancements are transforming how drone cameras are used, allowing for more sophisticated data analysis and autonomous operations. For instance, AI-enabled drones can automatically identify and track objects, making them invaluable for applications such as wildlife monitoring, traffic management, and security surveillance. The ability to process and analyze large volumes of data in real-time enhances the efficiency and effectiveness of drone operations, setting a new standard for drone capabilities.
Growing Use in Emergency Response and Public Safety:
Drone cameras are increasingly being deployed in emergency response and public safety operations, a trend that underscores their value in critical situations. For example, drones equipped with thermal imaging cameras are used by firefighters to locate individuals in smoke-filled buildings or during wildfires, providing crucial information that can save lives. Law enforcement agencies also utilize drones for crowd monitoring, search and rescue missions, and crime scene analysis. The ability to quickly deploy drones and obtain real-time aerial views is transforming emergency response strategies and public safety efforts.
Expansion of Drone Deliveries and Logistics:
The use of drones in logistics and delivery services is expanding rapidly, driven by the need for faster, more efficient delivery solutions. Companies like Amazon and UPS are actively testing and implementing drone delivery systems that can transport packages directly to consumers, especially in hard-to-reach areas. For instance, drones equipped with cameras ensure accurate navigation and safe delivery, even in complex urban environments. This trend is particularly strong in sectors like e-commerce, where the demand for rapid and reliable delivery options is critical.
Enhanced Regulatory Frameworks and Industry Standards:
The development of enhanced regulatory frameworks and industry standards is another key trend shaping the Drone Camera Market. Governments worldwide are working to establish clear guidelines for drone operations, addressing issues such as airspace management, privacy, and safety. For example, the European Union's regulations on unmanned aerial vehicles (UAVs) set a precedent for standardized drone usage across member states, promoting safer and more coordinated operations. These regulatory developments are helping to build trust in drone technology, encouraging wider adoption across various sectors while ensuring compliance with safety and legal requirements.
Market Challenges Analysis:
Growing privacy and security concerns:
The Drone Camera Market faces several key restraints and challenges that could impact its growth trajectory. One of the primary challenges is the growing privacy and security concerns associated with drone usage. The ability of drones to capture high-resolution images and videos raises significant privacy issues, leading to regulatory scrutiny and potential restrictions on their use. Additionally, unauthorized drone flights in restricted areas or sensitive locations can pose security risks, further complicating the regulatory landscape.
Complexity involved in maintaining and repairing drones:
Another significant challenge is the complexity involved in maintaining and repairing drones. Drone cameras can easily lose their signal with remote control, especially when flying in crowded areas or at a distance. This can lead to operational inefficiencies and increased maintenance costs. Moreover, the lack of standardized maintenance protocols and the need for specialized skills to repair drone cameras can hinder market growth.
High initial costs:
High initial costs of drone acquisition and maintenance also act as a restraint. While the prices of drones have decreased over time, the cost of high-quality drone cameras remains substantial. This can limit the adoption of drone cameras, particularly among small and medium-sized enterprises (SMEs) and individual consumers. Additionally, the ongoing costs associated with software updates, battery replacements, and other maintenance activities can add to the financial burden.
Shortage of skilled drone pilots:
Lastly, the shortage of skilled drone pilots presents a challenge. Operating drones effectively requires specific training and expertise, and the lack of qualified personnel can limit the growth of certain applications. This shortage can also lead to operational inefficiencies and increased risks of accidents or mishaps.
Market Segmentation Analysis:
By Type, the market is divided into HD Cameras, Ultra HD Cameras, Thermal Cameras, and Multispectral Cameras. HD Cameras dominate the market due to their affordability and sufficient quality for most applications. Ultra HD Cameras are gaining traction for their superior image quality, making them ideal for professional photography and videography. Thermal and Multispectral Cameras are increasingly used in specialized applications such as agriculture, surveillance, and environmental monitoring.
By Technology, the market is segmented into embedded cameras, infrared cameras, and thermal cameras. Embedded cameras are widely used due to their integration with various drone models, offering versatility and ease of use. Infrared cameras are essential for applications requiring night vision and low-light performance, such as security and surveillance. Thermal cameras are crucial for detecting heat signatures, making them valuable in search and rescue operations, firefighting, and industrial inspections.
By End User, the market is categorized into commercial, military, and homeland security. The commercial segment is the largest, driven by the increasing use of drone cameras in industries such as real estate, agriculture, and media and entertainment. The military segment also holds a significant share, with drone cameras being used for surveillance, reconnaissance, and tactical operations. Homeland security applications include border patrol, disaster response, and public safety.
Segmentation:
By Type
- HD Cameras
- Ultra HD Cameras
- Thermal Cameras
- Multispectral Cameras
By Application
- Aerial Photography and Videography
- Surveillance and Security
- Mapping and Surveying
- Agriculture
- Inspection and Monitoring
By Resolution
- 12 MP
- 12-20 MP
- 20-32 MP
- 32 MP
By End-use industry
- Media and Entertainment
- Agriculture
- Military and Defence
- Commercial
- Construction and Real Estate
- Others (e.g., Mining, Insurance)
- North America
- U.S
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the Drone Camera Market, accounting for approximately 35% of the global market. The region's dominance is driven by early adoption of drone technology across various industries, including agriculture, media, construction, and defence. The United States is the primary contributor to this market, with robust demand fuelled by advancements in drone technology, supportive government regulations, and significant investments in research and development. The Federal Aviation Administration (FAA) has played a crucial role in shaping the regulatory landscape, allowing for the integration of drones into commercial and public sectors. The use of drone cameras for military and surveillance purposes also adds to North America's substantial market share.
Europe
Europe follows closely, capturing around 30% of the global market share. The region’s growth is underpinned by strong adoption in industries such as agriculture, construction, and environmental monitoring. Countries like the United Kingdom, Germany, and France lead the European market, driven by technological innovation and a supportive regulatory environment. The European Union's regulations on unmanned aerial vehicles (UAVs) have provided a standardized framework that promotes the safe and coordinated use of drones across member states. Additionally, Europe's focus on sustainability and precision agriculture has led to increased utilization of drone cameras in monitoring crop health, optimizing resource use, and reducing environmental impact.
Asia-Pacific
Asia-Pacific is expected to witness the fastest growth in the Drone Camera Market, with its market share projected to reach around 25% by the end of the forecast period. This growth is driven by the region's rapid industrialization, expanding agricultural sector, and increasing infrastructure development. China and Japan are the key contributors to the market, with China being a global leader in drone manufacturing and deployment. The Chinese government's push for technological innovation, coupled with the widespread use of drones in agriculture, logistics, and public safety, propels the market forward. India also presents significant growth potential, driven by government initiatives to promote drone usage in various sectors, including agriculture, infrastructure inspection, and disaster management.
Latin America, the Middle East Africa
Latin America, the Middle East Africa, accounts for the remaining 10% of the global market share. These regions are gradually adopting drone technology, with growing applications in agriculture, mining, and oil and gas industries. In Latin America, Brazil and Mexico are leading the charge, driven by the need for innovative agricultural solutions and infrastructure monitoring. The Middle East is increasingly utilizing drone cameras for surveillance and infrastructure projects, while Africa is beginning to explore the potential of drones in agriculture and wildlife conservation.
Key Player Analysis:
- DJI Innovations
- Parrot SA
- GoPro, Inc.
- Yuneec International
- Autel Robotics
- AeroVironment, Inc.
- FLIR Systems, Inc.
- Kespry
- L3Harris Technologies
- Intel Corporation
Competitive Analysis:
The Drone Camera Market is highly competitive, with several key players striving for dominance through continuous innovation and technological advancements. DJI Innovations leads the market with a significant share, owing to its wide range of high-quality drones and strong global presence. Other prominent players like Parrot SA, Yuneec International, and GoPro, Inc. compete by offering specialized drones with advanced camera features tailored to different industries, including media, agriculture, and surveillance. Companies such as FLIR Systems and AeroVironment, Inc. focus on niche markets, providing drones with thermal imaging and defence capabilities, which are crucial for specific professional applications. The market is also characterized by the entry of tech giants like Intel Corporation, which leverage their expertise in processing and sensor technology to offer high-performance drone solutions. The intense competition is driving rapid innovation, with companies continually enhancing camera resolution, battery life, and AI capabilities to capture more market share.
Recent Developments:
- DJI Innovations (2024): In 2024, DJI introduced the Matrice 350 RTK, a new industrial drone featuring an upgraded RTK positioning system for enhanced precision and stability. This drone is designed for professional use in surveying, agriculture, and inspection, offering high-resolution cameras and improved flight performance, making it a top choice for complex aerial operations.
- Parrot SA (2023): In 2023, Parrot launched the ANAFI Ai, the world’s first 4G-connected drone. This innovative drone enables users to control it remotely over vast distances without the limitations of traditional radio frequency ranges. The ANAFI Ai features a 48MP camera with 4K HDR video capabilities, making it ideal for professional applications in mapping, inspection, and surveillance.
- Autel Robotics (2022): Autel Robotics released the EVO Lite+ drone in 2022, which comes equipped with a 1-inch CMOS sensor capable of capturing 50MP stills and 6K video. The EVO Lite+ also includes advanced features like obstacle avoidance and AI-powered subject tracking, catering to both professional photographers and industrial users who require high-quality aerial imagery.
Market Concentration & Characteristics:
The Drone Camera Market is moderately concentrated, with a few key players such as DJI Innovations, Parrot SA, and Autel Robotics holding significant market shares. These companies dominate the market through their advanced technology, extensive product portfolios, and strong global distribution networks. The market is characterized by rapid technological innovation, with a focus on improving camera resolution, flight stability, and autonomous capabilities. The competitive landscape is dynamic, driven by continuous product development and the integration of artificial intelligence (AI) and machine learning (ML) technologies. Additionally, there is a growing emphasis on specialized applications, such as thermal imaging and industrial inspections, which are catered to by companies like FLIR Systems and AeroVironment. As regulatory frameworks evolve and the adoption of drone technology expands across various industries, the market is expected to see increased competition and further innovation, particularly in high-growth regions such as Asia-Pacific and North America.
Report Coverage:
The research report offers an in-depth analysis based on type, application, resolution, and end-use industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for high-resolution drone cameras will continue to rise, driven by advancements in camera technology and image processing capabilities.
- Increased adoption of drone cameras in industries such as agriculture, real estate, and construction will drive market growth.
- The integration of AI and machine learning in drone cameras will enhance their functionality and efficiency.
- The development of lightweight and compact drone cameras will improve drone performance and battery life.
- Growing investments in drone technology start-ups will lead to innovative camera solutions and expanded market opportunities.
- Enhanced regulatory frameworks will facilitate the safe and widespread use of drone cameras in various applications.
- The use of drone cameras for surveillance and security purposes will become more prevalent, particularly in defence and law enforcement.
- The expansion of e-commerce platforms will boost the sales of drone cameras through online channels.
- Increased consumer interest in aerial photography and videography will drive demand for high-quality drone cameras.
- Collaboration between drone manufacturers and technology providers will result in advanced camera features and improved user experiences.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Drone Capabilities
Rapid improvements in camera resolution, image stabilization, and flight control systems are making drone cameras more effective and accessible for a wide range of professional and industrial applications, fueling market growth.
Increasing Adoption in Agriculture and Precision Farming
Drone cameras enable farmers to monitor crop health, assess soil conditions, and manage resources more efficiently, driving adoption in agriculture and supporting the expansion of precision farming practices.
Expanding Applications in Construction and Real Estate
The use of drone cameras for site surveying, project monitoring, and property inspections is streamlining operations and providing unique perspectives, leading to increased demand in construction and real estate sectors.
Government Support and Regulatory Developments
Supportive regulatory frameworks and government initiatives are making it easier for businesses to integrate drones into commercial operations, encouraging broader adoption across industries such as logistics, public safety, and infrastructure monitoring.
Integration of Artificial Intelligence and Machine Learning
The incorporation of AI and ML technologies into drone cameras is enabling advanced data analysis, autonomous operations, and real-time object tracking, significantly enhancing the value proposition and expanding potential use cases.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Drone Camera Market?
What factors are driving the growth of the Drone Camera Market?
What are some challenges faced by the Drone Camera Market?
Who are the major players in the Drone Camera Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 HD Cameras
- 1.2.2 Ultra HD Cameras
- 1.2.3 Thermal Cameras
- 1.2.4 Multispectral Cameras
- 1.3 By Resolution
- 1.3.1 12 MP
- 1.3.2 12-20 MP
- 1.3.3 20-32 MP
- 1.3.4 32 MP
- 1.4 By Application
- 1.4.1 Aerial Photography and Videography
- 1.4.2 Surveillance and Security
- 1.4.3 Mapping and Surveying
- 1.4.4 Agriculture
- 1.4.5 Inspection and Monitoring
- 1.5 By End-use industry
- 1.5.1 Media and Entertainment
- 1.5.2 Agriculture
- 1.5.3 Military and Defence
- 1.5.4 Commercial
- 1.5.5 Construction and Real Estate
- 1.5.6 Others (e.g., Mining, Insurance)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15,490.71 million → 2032: USD 133,532.93 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Drone Camera Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Drone Camera Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Drone Camera Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Drone Camera Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Drone Camera Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Drone Camera Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Drone Camera Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Drone Camera Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15,490.71 million → 2032: USD 133,532.93 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Drone Camera Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 HD Cameras
- 12.3.7.2 Ultra HD Cameras
- 12.3.7.3 Thermal Cameras
- 12.3.7.4 Multispectral Cameras
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Resolution - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 12 MP
- 12.4.7.2 12-20 MP
- 12.4.7.3 20-32 MP
- 12.4.7.4 32 MP
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Aerial Photography and Videography
- 12.5.7.2 Surveillance and Security
- 12.5.7.3 Mapping and Surveying
- 12.5.7.4 Agriculture
- 12.5.7.5 Inspection and Monitoring
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-use industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Media and Entertainment
- 12.6.7.2 Agriculture
- 12.6.7.3 Military and Defence
- 12.6.7.4 Commercial
- 12.6.7.5 Construction and Real Estate
- 12.6.7.6 Others (e.g., Mining, Insurance)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Drone Camera End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Drone Camera Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Drone Camera Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Drone Camera Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DJI Innovations
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Parrot SA
- 18.4 GoPro, Inc.
- 18.5 Yuneec International
- 18.6 Autel Robotics
- 18.7 AeroVironment, Inc.
- 18.8 FLIR Systems, Inc.
- 18.9 Kespry
- 18.10 L3Harris Technologies
- 18.11 Intel Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

