
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| DSP Motor Controllers Market Size 2024 | USD 1,711.22 million |
| DSP Motor Controllers Market , CAGR | 4.64% |
| DSP Motor Controllers Market Size 2032 | USD 2,460.65 million |
Market Overview
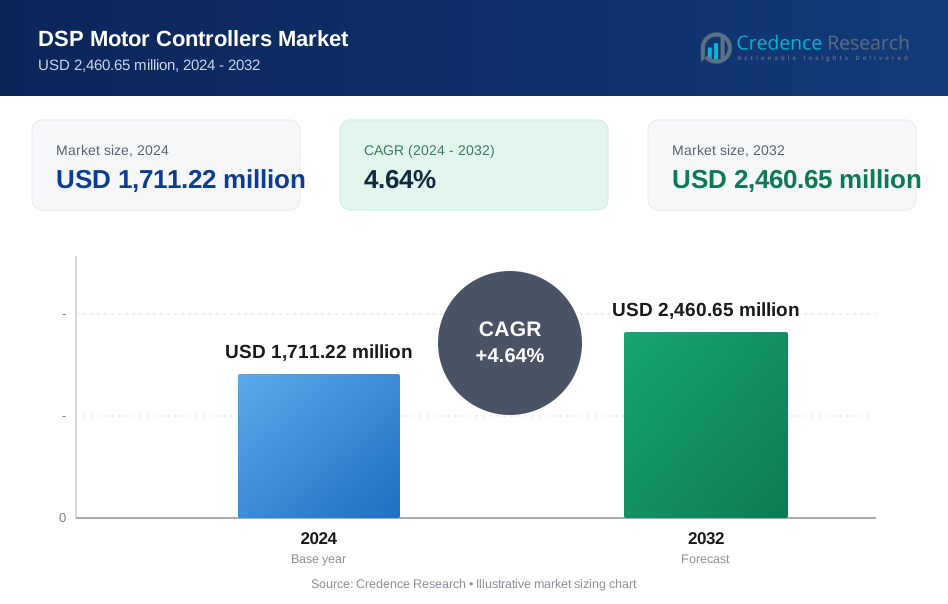
The Global DSP Motor Controllers Market is projected to grow from USD 1,711.22 million in 2024 to an estimated USD 2,460.65 million by 2032, registering a compound annual growth rate (CAGR) of 4.64% from 2025 to 2032.
Key drivers propelling the DSP Motor Controllers Market include the growing emphasis on energy conservation and the need for precise motor speed and torque control. DSP motor controllers offer enhanced processing capabilities, enabling real-time adjustments and improved system reliability. Market trends indicate a shift toward integrating advanced features such as IoT connectivity and machine learning algorithms to optimize motor performance. Additionally, technological advancements in semiconductor devices and increasing automation in manufacturing sectors support the market’s steady growth.
Geographically, the Asia-Pacific region dominates the DSP Motor Controllers Market due to rapid industrialization, expanding automotive production, and increased investments in automation technologies. North America and Europe hold significant shares, driven by advanced manufacturing infrastructure and strong R&D activities. Key players operating in this market include Texas Instruments, Infineon Technologies, STMicroelectronics, NXP Semiconductors, and Analog Devices. These companies focus on product innovation, strategic partnerships, and expanding their global presence to capture growing demand.

Market Insights
- The Global DSP Motor Controllers Market is projected to grow steadily, driven by increasing adoption in automotive, industrial automation, and consumer electronics sectors.
- Rising demand for energy-efficient and precise motor control solutions propels market growth, supported by advancements in digital signal processing technology.
- Technological innovations, including IoT integration and machine learning algorithms, enhance motor performance and system reliability.
- High development costs and technical complexity pose challenges, limiting market entry for smaller players and slowing adoption in cost-sensitive applications.
- Asia-Pacific dominates the market due to rapid industrialization, expanding automotive production, and growing investments in automation technologies.
- North America and Europe maintain significant shares, backed by strong manufacturing infrastructure, regulatory support, and intensive R\&D activities.
- Competitive dynamics involve major players focusing on product innovation, strategic partnerships, and expanding global presence to capture increasing demand.
Market Drivers
Energy Efficiency and Precise Motor Control
The Global DSP Motor Controllers Market benefits from increasing demand for energy-efficient motor systems across industries. DSP motor controllers provide precise control over motor speed and torque, reducing energy consumption while maintaining optimal performance. It enables real-time adjustments to varying load conditions, enhancing overall system efficiency. Companies and end-users prioritize sustainability and compliance with energy regulations, which drives adoption. These controllers also support variable frequency drives that contribute to significant energy savings. The rising need for lower operational costs further encourages the use of DSP-based motor control solutions.
- For instance, industrial automation applications accounted for over 40% of DSP motor controller deployments, driven by the need for energy-efficient solutions in manufacturing.
Advancements in Semiconductor Technology
Technological progress in semiconductor devices fuels the market expansion. Improved processing power and integration capabilities of DSP chips allow complex motor control algorithms to execute with higher accuracy and speed. The miniaturization of components supports compact and lightweight designs suitable for diverse applications. It also enables enhanced reliability and longer lifespan of motor control systems. Manufacturers continuously innovate to deliver controllers with better thermal management and reduced power losses. These advancements meet the growing demands of high-performance applications in automotive and industrial sectors.
- For instance, semiconductor advancements have enabled the development of motor driver ICs with enhanced efficiency, supporting the growing adoption of electric vehicles and industrial automation.
Automation and Industry 4.0 Adoption
Increasing automation in manufacturing and industrial processes significantly drives demand for DSP motor controllers. These controllers support smart factories by providing precise, programmable motor control that integrates with IoT and Industry 4.0 frameworks. It enables predictive maintenance, remote monitoring, and improved process control. The market growth aligns with rising investments in automation technologies to enhance productivity and reduce downtime. Industrial sectors adopt these controllers to improve operational flexibility and system scalability.
Growing Automotive Applications
The automotive sector represents a key growth area for DSP motor controllers. It leverages these controllers for electric vehicles (EVs), hybrid electric vehicles (HEVs), and advanced driver-assistance systems (ADAS). The increasing production of EVs creates demand for efficient motor control to maximize battery life and vehicle performance. It supports functions such as regenerative braking and torque vectoring, improving drivability and safety. The shift toward electrification and stricter emission regulations propel market growth in this segment.
Market Trends
Integration of IoT and Connectivity Features Enhances Motor Controller Capabilities
The Global DSP Motor Controllers Market increasingly adopts Internet of Things (IoT) integration to enable smarter motor control solutions. It allows real-time data collection and communication between motor controllers and other system components, facilitating predictive maintenance and performance optimization. Manufacturers develop controllers with enhanced connectivity options such as wireless communication protocols. This trend supports remote monitoring and diagnostics, reducing downtime and operational costs. The integration of IoT also enables adaptive motor control based on changing environmental and operational conditions. It aligns with the growing demand for automation and digital transformation in industries.
- For instance, IoT-enabled DSP controllers in industrial automation have led to a 41% reduction in unplanned downtimes in chemical plants using predictive maintenance systems.
Shift Toward Compact and Energy-Efficient Designs to Meet Industry Requirements
Market players focus on producing compact DSP motor controllers that offer high efficiency without compromising performance. It supports applications where space constraints and energy savings are critical, such as consumer electronics and electric vehicles. These controllers feature optimized power management and low thermal dissipation to enhance durability and reliability. The trend reflects the demand for lightweight systems that deliver precise control with minimal energy loss. Advances in semiconductor fabrication technologies contribute to this miniaturization while maintaining computational power. This development broadens the adoption of DSP controllers across various sectors.
- For instance, advancements in DSP-based motor controllers have enabled up to 95% energy conversion efficiency, significantly improving performance in robotics and automotive applications.
Adoption of Machine Learning and AI to Improve Motor Performance and Reliability
The use of machine learning (ML) and artificial intelligence (AI) algorithms in DSP motor controllers marks a significant market trend. It enables adaptive control strategies that learn from operational data to optimize motor efficiency and reduce faults. The controllers analyze patterns and predict maintenance needs, preventing unexpected failures. This trend enhances overall system intelligence and extends equipment lifespan. Integration of AI-driven motor control supports the growing complexity of modern industrial and automotive applications. Manufacturers increasingly invest in R\&D to embed intelligent features into their DSP controllers.
Growing Demand for Multi-Function Controllers to Support Diverse Applications
Market demand shifts toward multifunctional DSP motor controllers that can handle various motor types and control modes within a single device. It simplifies system design and reduces the need for multiple specialized controllers, lowering overall costs. These versatile controllers support applications ranging from industrial automation to renewable energy systems. The trend reflects customer preference for flexible and scalable solutions that accommodate evolving operational requirements. It encourages manufacturers to develop programmable and customizable DSP motor controllers. This approach increases market competitiveness and adoption across diverse end-use sectors.
Market Challenges
Key Technical Complexity and High Development Costs Limit Market Growth
The Global DSP Motor Controllers Market faces challenges due to the technical complexity involved in designing and implementing advanced DSP-based control systems. It requires skilled engineers and significant investment in research and development to develop reliable and efficient controllers. The intricate programming and integration with other industrial systems increase the time and cost of product development. These factors create barriers for new entrants and small manufacturers, limiting market expansion. High initial costs also deter some end-users, especially in cost-sensitive applications. Overcoming these challenges requires continuous innovation and efficient development processes to balance performance and affordability.
- For instance, the global DSP motor controllers market had over 4,500 registered manufacturers in 2024, with approximately 1,200 firms specializing in industrial automation applications.
Compatibility Issues and Industry Standardization Challenges Restrain Adoption
The lack of uniform industry standards for DSP motor controllers creates compatibility challenges across different applications and devices. It complicates integration with existing systems and limits interoperability between controllers from various manufacturers. This fragmentation slows adoption, particularly in industries requiring seamless integration and scalability. It forces companies to invest additional resources in customization and testing. The market growth depends on developing standardized protocols and ensuring compatibility to encourage wider deployment. Efforts toward harmonizing standards and fostering collaboration among key players remain crucial to addressing this challenge effectively.

Market Opportunities
Expanding Applications in Electric Vehicles and Renewable Energy Sectors Drive Growth Prospects
The Global DSP Motor Controllers Market presents significant opportunities in the rapidly growing electric vehicle (EV) and renewable energy sectors. It plays a critical role in enhancing the efficiency and reliability of motor systems used in EV drivetrains and renewable energy equipment such as wind turbines and solar tracking systems. Increasing investments in clean energy infrastructure and stringent emission regulations encourage the adoption of advanced motor controllers. The rising demand for high-performance, energy-efficient solutions in these sectors offers vast growth potential. Companies that focus on developing specialized DSP motor controllers tailored to EV and renewable energy applications can capitali on this expanding market.
Emerging Technologies and Digital Transformation Open New Market Frontiers
The integration of emerging technologies like artificial intelligence, machine learning, and IoT within DSP motor controllers creates new avenues for market growth. It enables smarter, predictive, and adaptive motor control solutions that enhance operational efficiency and reduce downtime. The growing trend of Industry 4.0 adoption in manufacturing and automation sectors fuels demand for intelligent motor controllers. Furthermore, digital transformation in consumer electronics and industrial equipment drives the need for advanced DSP motor control systems. Market players investing in R\&D to innovate and embed these technologies can unlock significant opportunities and strengthen their competitive position.
Market Segmentation Analysis
By Controller Type
The Global DSP Motor Controllers Market segments into fixed point and floating point controllers based on controller type. Fixed point controllers dominate due to their cost-effectiveness and suitability for applications requiring moderate processing power. They provide efficient motor control in consumer electronics and basic industrial automation. Floating point controllers gain traction in high-performance applications where precise calculations and complex algorithms are necessary. It supports advanced motor control functions in sectors such as automotive and aerospace. The choice between fixed and floating point controllers depends on the balance between performance requirements and cost considerations.
By Motor Type
The market segments by motor type include brushed DC motors, brushless DC motors, AC induction motors, and others. Brushless DC motors hold a significant market share due to their higher efficiency, lower maintenance, and longer lifespan compared to brushed motors. DSP motor controllers effectively manage brushless DC motors, optimizing speed and torque control. AC induction motors maintain substantial demand in industrial applications for their robustness and cost efficiency. Controllers designed for AC motors focus on energy savings and reliability in heavy-duty operations. The ‘others’ segment covers specialized motors such as synchronous and stepper motors, where DSP controllers offer precise control tailored to unique operational needs. These segments reflect the diverse applications and requirements that drive the market’s growth.
Segments
Based on Controller Type
- Fixed Point
- Floating Point
Based on Motor Type
- Brushed DC Motors
- Brushless DC Motors
- 9AC Induction Motors
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America DSP Motor Controllers Market
North America DSP Motor Controllers Market holds a significant share of approximately 24.5% in 2024, valued at USD 419.81 million and projected to reach USD 606.13 million by 2032, registering a CAGR of 4.7%. It benefits from advanced industrial infrastructure, extensive R\&D investments, and a strong presence of key market players. The region’s automotive and industrial automation sectors drive demand for high-performance DSP motor controllers. Growing adoption of electric vehicles and smart manufacturing further supports market expansion. The United States and Canada lead the regional market, focusing on innovation and technological integration.
Europe DSP Motor Controllers Market
Europe DSP Motor Controllers Market accounted for around 20.4% share in 2024, standing at USD 349.26 million and expected to reach USD 461.62 million by 2032 with a CAGR of 3.6%. It reflects steady growth fueled by stringent energy efficiency regulations and increasing automation in manufacturing. Germany, France, and the UK contribute significantly, driven by automotive electrification and renewable energy initiatives. The market focuses on developing energy-efficient and compact motor control solutions. Continuous investments in smart factory technologies promote adoption of advanced DSP motor controllers across industries.
Asia-Pacific DSP Motor Controllers Market
Asia-Pacific DSP Motor Controllers Market dominates with a 34.9% share in 2024, valued at USD 597.76 million and forecasted to grow to USD 919.92 million by 2032 at a CAGR of 5.6%. Rapid industrialization, expanding automotive manufacturing, and growing electronics sectors drive demand. China, Japan, India, and South Korea serve as key contributors, supported by government initiatives promoting automation and clean energy. The market benefits from increased investments in electric vehicles and smart manufacturing facilities. Growing middle-class populations and rising disposable incomes further boost market penetration.
Latin America’s DSP Motor Controllers Market
Latin America’s DSP Motor Controllers Market held approximately 7.8% share in 2024, valued at USD 134.37 million and projected to reach USD 194.61 million by 2032, growing at a CAGR of 4.8%. The region experiences growth through expanding industrial automation and infrastructure development. Brazil and Mexico lead demand, driven by automotive and manufacturing sectors adopting energy-efficient motor controllers. Investment in renewable energy projects and modernization of industries present growth opportunities.
Middle East DSP Motor Controllers Market
Middle East DSP Motor Controllers Market accounted for about 4.8% share in 2024, standing at USD 82.77 million and expected to reach USD 111.01 million by 2032, registering a CAGR of 3.8%. It benefits from increasing industrial projects and energy sector investments. The UAE and Saudi Arabia focus on smart manufacturing and automation to improve operational efficiency. The demand for energy-efficient motor control systems supports market growth in the region.
Africa’s DSP Motor Controllers Market
Africa’s DSP Motor Controllers Market held roughly 7.4% share in 2024, with a market value of USD 127.25 million, projected to grow to USD 167.36 million by 2032 at a CAGR of 3.4%. It experiences steady growth driven by expanding manufacturing sectors and infrastructure development. South Africa leads the regional market, adopting advanced motor control technologies to enhance industrial productivity. Growing investments in energy and transportation infrastructure promote DSP motor controller adoption.
Key players
- Toshiba Corp.
- Broadcom Corp.
- Renesas Electronics Corp.
- Analog Devices Inc.
- ST Microelectronics N.V.
- Freescale Semiconductor Ltd.
- LSI Corp.
- Ceva Inc.
- Texas Instruments Inc.
- Altera Corp.
- NXP Semiconductors N.V.
- Marvell Technology Group Ltd.
- Qualcomm Inc.
- Samsung Electronics Co. Ltd.
Competitive Analysis
The Global DSP Motor Controllers Market is highly competitive, characterized by the presence of established semiconductor and electronics companies with strong technological capabilities. Key players such as Texas Instruments, Toshiba Corp., and Analog Devices leverage extensive R\&D investments to innovate and offer advanced motor control solutions tailored to diverse applications. It faces intense competition driven by the need for energy-efficient, compact, and high-performance controllers. Companies focus on strategic collaborations, product portfolio expansion, and geographic market penetration to strengthen their position. Innovation in integrating IoT, AI, and machine learning features differentiates leading players. The market's competitive landscape demands continuous improvement in controller precision, reliability, and cost-effectiveness to meet evolving industrial and automotive requirements.
Recent Developments
- In January 2025, Toshiba introduced seven new 32-bit microcontrollers featuring Arm® Cortex®-M4 cores, expanding its motor control MCU lineup. These devices are designed for field-oriented control (FOC) of up to two AC motors, brushless DC (BLDC) motors, and various inverter control applications.
- In March 2025, Broadcom announced the Sian3 and Sian2M chips, additions to its PAM-4 DSP PHY product portfolio. These chips, built on 3-nanometer process technology, offer significant power reductions and are optimized for 800G and 1.6T optical modules, catering to the demands of AI and machine learning data centers.
- In April 2025, Marvell announced the sale of its automotive Ethernet business to Infineon for \$2.5 billion in cash, indicating a strategic shift that may impact its focus on DSP motor controller technologies.
Market Concentration and Characteristics
The Global DSP Motor Controllers Market exhibits a moderately concentrated competitive environment dominated by several key players with strong technological expertise and extensive product portfolios. It features a mix of large multinational corporations and specialized firms competing on innovation, product quality, and customization capabilities. Market leaders invest heavily in research and development to maintain their competitive edge by introducing advanced features such as IoT integration and AI-driven motor control. The market’s characteristics include a growing demand for energy-efficient, compact, and high-precision controllers across automotive, industrial, and consumer electronics sectors. Customer requirements for reliability, scalability, and cost-effectiveness influence vendor strategies. It encourages continuous innovation and strategic partnerships to expand market reach and address diverse application needs worldwide.
Report Coverage
The research report offers an in-depth analysis based on Controller Type, Motor Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global DSP Motor Controllers Market will experience steady growth driven by rising demand in automotive electrification and industrial automation sectors. Increasing focus on energy efficiency will sustain market expansion.
- Advancements in semiconductor technology will enable more compact, powerful, and cost-effective DSP motor controllers, broadening their application across various industries. Enhanced processing capabilities will support complex motor control algorithms.
- Integration of artificial intelligence and machine learning within DSP controllers will improve adaptive motor performance, predictive maintenance, and fault detection, enhancing system reliability and reducing downtime.
- The adoption of IoT-enabled motor controllers will grow, enabling real-time monitoring and remote diagnostics, facilitating smarter industrial operations and improved operational efficiency.
- Growth in electric vehicle production worldwide will significantly boost demand for high-performance DSP motor controllers to optimize battery usage and vehicle drivability.
- Expanding renewable energy infrastructure, including wind and solar power systems, will increase the need for precise and reliable motor control solutions that DSP controllers provide.
- Emerging markets in Asia-Pacific, Latin America, and Africa will offer substantial growth opportunities due to rapid industrialization and increased investments in automation technologies.
- Demand for multifunctional and programmable DSP motor controllers will rise, allowing greater flexibility and adaptability across diverse motor types and applications.
- Strategic collaborations and partnerships among key players will accelerate innovation and market penetration, helping companies meet evolving customer requirements globally.
- Regulatory emphasis on environmental sustainability and energy conservation will drive continuous development of DSP motor controllers with improved energy-saving features and reduced carbon footprints.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Energy Efficiency and Precise Motor Control
DSP motor controllers enable precise speed and torque control, reducing energy consumption and supporting compliance with increasingly stringent energy regulations. This is especially critical in industrial automation and automotive sectors where operational cost savings and sustainability are prioritized.
Advancements in Semiconductor Technology
Continuous improvements in DSP chip processing power, miniaturization, and integration capabilities allow for more complex motor control algorithms and compact controller designs. These advancements enable higher performance, reliability, and broader application in demanding environments such as electric vehicles and smart factories.
Automation and Industry 4.0 Adoption
The shift toward smart manufacturing and Industry 4.0 drives demand for DSP motor controllers that can integrate with IoT systems, enable predictive maintenance, and support flexible, programmable motor control. This trend is particularly strong in Asia-Pacific and North America, where industrial automation investments are high.
Growing Automotive Electrification
The rapid increase in electric and hybrid vehicle production requires advanced DSP motor controllers for efficient drivetrain management, regenerative braking, and torque vectoring. Stricter emission regulations and the global push for vehicle electrification are accelerating adoption in this sector.
Integration of IoT and Machine Learning
Manufacturers are embedding IoT connectivity and machine learning algorithms into DSP motor controllers, enabling real-time monitoring, adaptive control, and predictive maintenance. This enhances system reliability, reduces downtime, and aligns with the digital transformation of industrial and automotive applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global DSP Motor Controllers Market in 2023, and what are the forecasts for 2032?
What factors drive the growth of the DSP Motor Controllers Market?
Which regions dominate the DSP Motor Controllers Market?
Who are the key players in the Global DSP Motor Controllers Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Motor Type
- 1.2.1 Brushed DC Motors
- 1.2.2 Brushless DC Motors
- 1.2.3 AC Induction Motors
- 1.2.4 Others
- 1.3 By Application
- 1.3.1 Industrial Automation
- 1.3.2 Automotive
- 1.3.3 Consumer Electronics
- 1.3.4 Renewable Energy
- 1.3.5 Others
- 1.4 By Controller Type
- 1.4.1 Fixed Point
- 1.4.2 Floating Point
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,711.22 million → 2032: USD 2,460.65 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global DSP Motor Controllers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global DSP Motor Controllers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global DSP Motor Controllers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global DSP Motor Controllers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global DSP Motor Controllers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global DSP Motor Controllers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global DSP Motor Controllers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global DSP Motor Controllers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,711.22 million → 2032: USD 2,460.65 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global DSP Motor Controllers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Motor Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Brushed DC Motors
- 12.3.7.2 Brushless DC Motors
- 12.3.7.3 AC Induction Motors
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Industrial Automation
- 12.4.7.2 Automotive
- 12.4.7.3 Consumer Electronics
- 12.4.7.4 Renewable Energy
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Controller Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fixed Point
- 12.5.7.2 Floating Point
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global DSP Motor Controllers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global DSP Motor Controllers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global DSP Motor Controllers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global DSP Motor Controllers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Texas Instruments Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Infineon Technologies AG
- 18.4 STMicroelectronics N.V.
- 18.5 NXP Semiconductors N.V.
- 18.6 Analog Devices Inc.
- 18.7 Toshiba Corp.
- 18.8 Broadcom Corp.
- 18.9 Renesas Electronics Corp.
- 18.10 Marvell Technology Group Ltd.
- 18.11 Samsung Electronics Co. Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

