
Market Overview
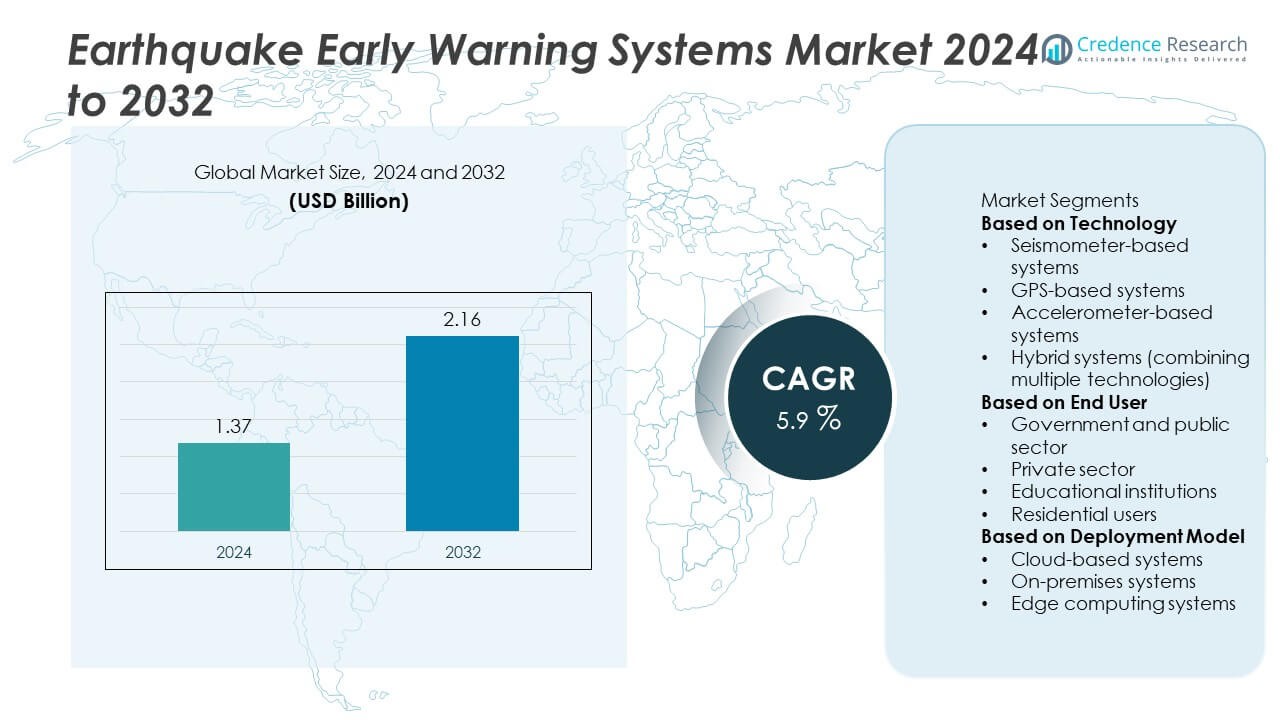
The Earthquake Early Warning Systems market was valued at USD 1.37 billion in 2024 and is projected to reach USD 2.16 billion by 2032, growing at a CAGR of 5.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Earthquake Early Warning Systems market Size 2024 | USD 1.37 Billion |
| Earthquake Early Warning Systems market, CAGR | 5.9% |
| Earthquake Early Warning Systems market Size 2032 | USD 2.16 Billion |
The earthquake early warning systems market is led by key players such as Kinemetrics, SeismicAI, Early Warning Labs, SeisComP3, Optimum Seismic, Seismic Warning Systems, Seismic Warning Group, Nanometrics Inc., SkyAlert, and GeoSIG Ltd. These companies dominate the market through technological innovation in multi-sensor networks, AI-driven seismic data processing, and cloud-based alert delivery. They focus on improving detection precision and reducing alert latency across public and private sectors. North America led the market with a 37% share in 2024, supported by large-scale government initiatives like ShakeAlert. Asia-Pacific followed with a 29% share, driven by Japan and China’s advanced nationwide warning infrastructure and growing investments in seismic safety modernization.
Market Insights
- The earthquake early warning systems market was valued at USD 1.37 billion in 2024 and is projected to reach USD 2.16 billion by 2032, growing at a CAGR of 5.9%.
- Growth is driven by rising seismic vulnerability, government safety mandates, and investments in public alert infrastructure across high-risk regions.
- Integration of AI, IoT, and multi-sensor hybrid systems is a major trend improving detection accuracy and reducing response time.
- The market is moderately competitive, with key players like Kinemetrics, SeismicAI, and Early Warning Labs focusing on cloud-based analytics and real-time data integration.
- North America held a 37% market share in 2024, followed by Asia-Pacific with 29%, while seismometer-based systems led by technology with a 43% share due to their precision in large-scale seismic monitoring.
Market Segmentation Analysis:
By Technology
The seismometer-based systems segment dominated the earthquake early warning systems market with a 43% share in 2024. This dominance is attributed to their proven reliability in detecting primary seismic waves and issuing alerts within seconds. These systems are widely used in national and regional warning networks due to their high precision and low false-alarm rate. Hybrid systems are gaining traction as they integrate GPS and accelerometer data for enhanced detection accuracy. The increasing focus on real-time, multi-sensor integration supports hybrid adoption in densely populated and high-risk seismic zones.
- For instance, the U.S. ShakeAlert network uses a network of over 2,000 seismic sensors, which include equipment from partners like Kinemetrics, to detect seismic activity. The system is designed to provide alerts within a few seconds of an earthquake's start, with the precise warning time depending on the recipient's distance from the epicenter.
By End User
The government and public sector segment held a 56% share of the earthquake early warning systems market in 2024. Governments lead adoption through large-scale infrastructure projects and national seismic monitoring initiatives. These systems are deployed to protect public safety, critical infrastructure, and transportation networks. Public agencies in Japan, the U.S., and Mexico have implemented extensive alert networks connected to schools, hospitals, and industries. The private sector is also expanding adoption to safeguard industrial facilities, while educational institutions integrate systems for campus safety and evacuation management.
- For instance, SeismicAI powers a nationwide Earthquake Early Warning system in a Balkan country in partnership with a local hardware manufacturer, delivering fast alerts to civilians and critical infrastructure. The company uses its AI-based platform and advanced algorithms to analyze data from sensors to provide high-precision regional alerts.
By Deployment Model
The cloud-based systems segment accounted for a 48% share of the earthquake early warning systems market in 2024. Cloud deployment enables faster data processing, centralized monitoring, and easy scalability for regional and national networks. It supports seamless integration with communication platforms and mobile alerting applications. The shift toward cloud computing enhances system reliability and accessibility for emergency agencies and public networks. Edge computing systems are emerging for remote and high-risk regions requiring low-latency alerts, while on-premises models remain preferred for secure government and defense installations.
Key Growth Drivers
Rising Seismic Vulnerability and Urban Development
Increasing urbanization in earthquake-prone regions is driving the demand for advanced early warning systems. Governments and city planners are investing in seismic monitoring infrastructure to protect critical assets, transportation networks, and populations. These systems provide crucial seconds of warning before seismic waves arrive, reducing casualties and infrastructure damage. Growing awareness of disaster resilience and risk mitigation has led to large-scale national implementations in countries like Japan, the U.S., and Chile, positioning earthquake early warning systems as essential components of urban safety planning.
- For instance, Japan's Earthquake Early Warning (EEW) system, operated by the Japan Meteorological Agency (JMA) alongside other national and local government networks, utilizes an expansive network of seismometers across the country.
Government Initiatives and Funding Programs
Public sector investments and funding initiatives are major drivers of the earthquake early warning systems market. Governments across North America, Asia-Pacific, and Europe are launching national seismic alert networks to strengthen disaster preparedness. Programs like Japan’s JMA warning system and the U.S. ShakeAlert have inspired similar frameworks globally. Financial support for sensor installation, software upgrades, and communication infrastructure enhances deployment reach. These initiatives aim to ensure rapid public notifications and protect critical infrastructure such as railways, utilities, and hospitals.
- For instance, the U.S. Geological Survey expanded its ShakeAlert network through Early Warning Labs, which deployed more than 1,200 MEMS-based seismic sensors across California and Oregon. The network transmits real-time alerts through integrated cell broadcast and API-based systems, achieving signal transmission speeds under 2.5 seconds to emergency management agencies and public notification platforms.
Advancements in Sensor and Data Processing Technology
Technological advancements in seismic sensors, GPS monitoring, and cloud-based analytics are transforming earthquake early warning capabilities. Modern systems leverage high-speed data transmission, AI-based analytics, and edge computing for real-time ground motion assessment. Improved accuracy and lower latency in signal processing enable faster alerts to emergency services, industries, and citizens. Integration with IoT and mobile applications expands accessibility, allowing broader dissemination of warnings. These innovations enhance system efficiency and promote large-scale adoption across both government and private sectors.
Key Trends & Opportunities
Integration of AI and Machine Learning for Predictive Analysis
The integration of AI and machine learning is revolutionizing earthquake detection and early warning precision. AI algorithms analyze vast datasets from seismometers and GPS sensors to identify seismic patterns and minimize false alarms. Predictive models enhance the system’s ability to distinguish real events from noise, improving reliability. This trend offers opportunities for developing adaptive systems capable of self-learning from past tremors. The growing collaboration between research institutions and technology providers accelerates innovation in predictive analytics and real-time event forecasting.
- For instance, Nanometrics offers the Pegasus seismic data acquisition system, which processes waveform data. Nanometrics introduced an advanced AI-powered event detection engine that integrates with its systems, providing faster processing and enhanced accuracy for identifying seismic events in near real-time.
Expansion of Public Alert Networks and Mobile Connectivity
Global expansion of mobile and public alert networks presents significant opportunities for the earthquake early warning systems market. Countries are integrating warnings into mobile platforms, TV networks, and IoT-based devices to maximize population coverage. Partnerships with telecom operators and emergency agencies enable instant, region-specific alerts. The adoption of multilingual, automated notification systems enhances accessibility in diverse communities. This growing emphasis on public communication infrastructure supports faster response coordination and broader system deployment in high-risk regions.
- For instance, SkyAlert expanded its EEW mobile platform to serve more than 7 million users across Mexico and select areas of California, Oregon, and Washington. The system delivers localized seismic alerts through AWS cloud servers, broadcasting messages in both English and Spanish to ensure effective real-time communication during seismic emergencies.
Key Challenges
High Implementation and Maintenance Costs
The high cost of deploying and maintaining large-scale seismic networks remains a major challenge. Installation of advanced sensors, cloud platforms, and communication infrastructure requires substantial investment. Developing regions face financial limitations that hinder widespread implementation. Regular calibration, data management, and system upgrades further increase operational expenses. To address this, governments and private organizations are exploring cost-sharing models, while manufacturers are focusing on modular, low-maintenance solutions to improve affordability and expand coverage.
Limited Infrastructure and Technical Expertise in Developing Regions
In many developing countries, limited technical expertise and insufficient communication infrastructure restrict the deployment of early warning systems. Inconsistent data connectivity and lack of trained personnel reduce system reliability and response effectiveness. These regions often depend on international aid or partnerships to establish seismic monitoring networks. Strengthening local capacity through training programs, technology transfers, and regional collaboration is essential to overcome these barriers and ensure sustainable, long-term adoption of earthquake early warning systems.
Regional Analysis
North America
North America held a 37% share of the earthquake early warning systems market in 2024. The region’s leadership is driven by advanced seismic infrastructure, robust government programs, and strong public safety policies. The U.S. leads with extensive deployment through the ShakeAlert system, which covers high-risk areas along the West Coast. Canada also invests in expanding seismic monitoring networks to strengthen early disaster response. Continuous technological innovation, integration with mobile alert systems, and partnerships between research institutions and emergency management agencies support market growth across the region.
Europe
Europe accounted for a 28% share of the earthquake early warning systems market in 2024. Countries such as Italy, Greece, and Turkey are major adopters due to frequent seismic activity across the Mediterranean zone. The European Union supports coordinated research initiatives and infrastructure funding to improve real-time earthquake detection. Integration of IoT and AI technologies enhances system precision and cross-border data sharing. Growing urban safety regulations and government-backed monitoring programs are boosting implementation in public transportation networks, utilities, and industrial zones, driving regional market expansion.
Asia-Pacific
Asia-Pacific captured a 29% share of the earthquake early warning systems market in 2024. The region’s growth is driven by high seismic vulnerability in Japan, China, Indonesia, and the Philippines. Japan remains the global leader, with a fully operational nationwide warning network operated by the Japan Meteorological Agency. China continues to expand regional alert systems under its national emergency management initiatives. Rising investments in disaster resilience, rapid urbanization, and government-led early alert programs support steady adoption. Technological collaborations between universities and tech firms further enhance innovation in real-time seismic monitoring.
Middle East & Africa
The Middle East & Africa region held a 3% share of the earthquake early warning systems market in 2024. Seismic hotspots in Iran, Turkey, and parts of North Africa are driving limited but growing adoption. Governments are focusing on integrating early warning systems within disaster management frameworks to reduce damage from frequent tremors. Infrastructure development projects and regional cooperation with international research agencies are improving access to seismic data. However, limited technical expertise and funding constraints continue to slow large-scale implementation across developing economies in the region.
Latin America
Latin America accounted for a 3% share of the earthquake early warning systems market in 2024. The region’s growth is fueled by seismic risk in countries such as Mexico, Chile, and Peru. Mexico’s national alert system, SASMEX, remains one of the most established networks globally, covering millions of residents. Governments are expanding similar initiatives to protect critical infrastructure and urban populations. Increasing awareness of disaster preparedness, combined with regional collaborations and international aid programs, supports technological upgrades and broader deployment across high-risk areas in Latin America.
Market Segmentations:
By Technology
- Seismometer-based systems
- GPS-based systems
- Accelerometer-based systems
- Hybrid systems (combining multiple technologies)
By End User
- Government and public sector
- Private sector
- Educational institutions
- Residential users
By Deployment Model
- Cloud-based systems
- On-premises systems
- Edge computing systems
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the earthquake early warning systems market includes key players such as Kinemetrics, SeismicAI, Early Warning Labs, SeisComP3, Optimum Seismic, Seismic Warning Systems, Seismic Warning Group, Nanometrics Inc., SkyAlert, and GeoSIG Ltd. These companies compete through advancements in real-time seismic monitoring, AI-based analytics, and rapid alerting technologies. Leading firms focus on integrating multi-sensor networks with cloud and edge computing to enhance detection accuracy and reduce latency. Strategic partnerships with governments, research institutions, and telecom operators are expanding their deployment reach and improving disaster resilience infrastructure. Product differentiation through automated response systems, mobile integration, and predictive algorithms strengthens competitiveness. Meanwhile, regional players emphasize cost-effective and modular systems for local implementation. Continuous innovation, strong after-service support, and data reliability remain key factors driving competition in this evolving and safety-critical market segment.
Key Player Analysis
- Kinemetrics
- SeismicAI
- Early Warning Labs
- SeisComP3
- Optimum Seismic
- Seismic Warning Systems
- Seismic Warning Group
- Nanometrics Inc.
- SkyAlert
- GeoSIG Ltd.
Recent Developments
- In May 2025, SeismicAI’s pilot system detected and issued a warning for a magnitude 6.0 event near Crete.
- In April 2025, Kinemetrics, Inc. announced delivery of its OASISPlus earthquake response platform tailored for smart-city infrastructure, supporting multiple M2M protocols and real-time alerting.
- In June 2024, Sanlien Technology Corp. launched a structural health monitoring and advanced earthquake early warning system. The system employed advanced technology to issue alerts seconds to tens of seconds before earthquakes occur. This early warning capability allows for vital evacuation time and facilitates proactive safety measures.
- In February 2024, Kinemetrics launched earthquake early warning alerts for its OasisPlus Earthquake Response Platform, powered by ShakeAlert. The system integrated real-time seismic data to provide timely alerts to users in the event of an earthquake.
Report Coverage
The research report offers an in-depth analysis based on Technology, End User, Deployment Model and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with increasing government investments in seismic safety programs.
- AI and machine learning will enhance real-time earthquake detection and prediction accuracy.
- Cloud and edge computing will improve data processing speed and alert distribution.
- Integration with public communication networks will ensure wider emergency coverage.
- Hybrid sensor systems will gain adoption for improved reliability and precision.
- Asia-Pacific will emerge as the fastest-growing region with strong government support.
- North America will maintain leadership with advanced seismic monitoring infrastructure.
- Private sector participation will increase through industrial safety initiatives.
- Partnerships between technology firms and research institutions will drive innovation.
- Development of low-cost, scalable systems will expand adoption in developing regions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Earthquake Early Warning Systems market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Earthquake Early Warning Systems market projected to grow between 2025 and 2032?
Which Earthquake Early Warning Systems market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Earthquake Early Warning Systems market?
Who are the leading companies in the Earthquake Early Warning Systems market?
Which region commanded the largest share of the Earthquake Early Warning Systems market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.37 billion → 2032: USD 2.16 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Earthquake Early Warning Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Earthquake Early Warning Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Earthquake Early Warning Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Earthquake Early Warning Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Earthquake Early Warning Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Earthquake Early Warning Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Earthquake Early Warning Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Earthquake Early Warning Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.37 billion → 2032: USD 2.16 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Earthquake Early Warning Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Earthquake Early Warning Systems Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Earthquake Early Warning Systems Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Earthquake Early Warning Systems Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
