
Market Overview:
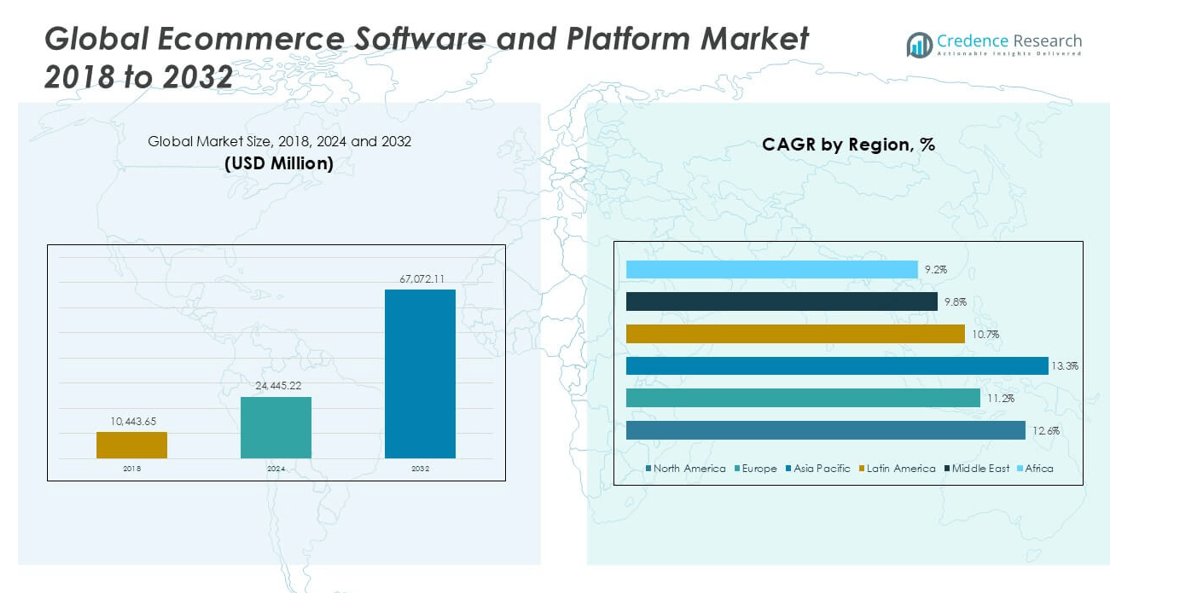
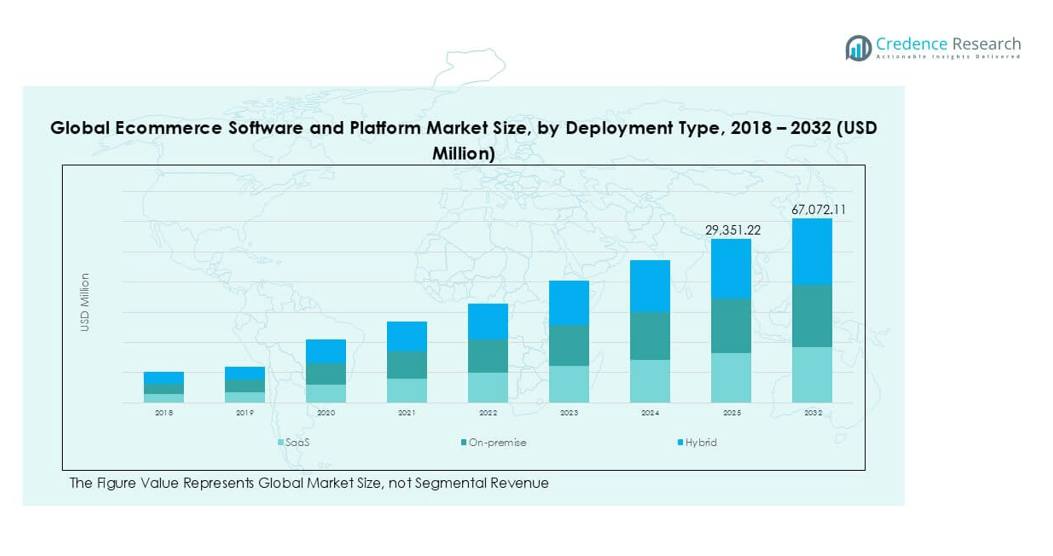
The Global Ecommerce Software and Platform market size was valued at USD 10,443.65 million in 2018, increasing to USD 24,445.22 million in 2024, and is anticipated to reach USD 67,072.11 million by 2032, growing at a CAGR of 12.53% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ecommerce Software and Platform Market Size 2024 | USD 24,445.22 million |
| Ecommerce Software and Platform Market, CAGR | 12.53% |
| Ecommerce Software and Platform Market Size 2032 | USD 67,072.11 million |
Key players in the global ecommerce software and platform market include Shopify, WooCommerce, BigCommerce, Magento, Squarespace, Wix eCommerce, and Salesforce Commerce Cloud. These companies lead through advanced SaaS platforms, seamless integrations, and strong cloud-based infrastructure supporting omnichannel operations. Shopify remains a front-runner with extensive merchant adoption and innovative AI-driven tools, while Salesforce Commerce Cloud excels in enterprise-grade solutions. WooCommerce and Wix dominate the SME segment with flexibility and cost efficiency. Regionally, Asia Pacific leads the market with a 48% share in 2024, followed by North America at 26%, driven by strong digitalization, expanding online retail, and robust payment ecosystems.
Market Insights
- The global ecommerce software and platform market was valued at USD 10,443.65 million in 2018 and reached USD 24,445.22 million in 2024. It is projected to attain USD 67,072.11 million by 2032, registering a CAGR of 12.53%.
- Growth is driven by digital transformation, mobile commerce expansion, and rising SME participation in online retail. Cloud-based deployments and integrated payment systems are boosting scalability and efficiency.
- AI integration, omnichannel retailing, and personalized shopping experiences are key trends shaping platform innovation. Increasing automation and predictive analytics enhance customer engagement and retention.
- The market is competitive, with key players such as Shopify, WooCommerce, BigCommerce, Magento, Wix, and Salesforce Commerce Cloud investing in SaaS upgrades and global reach.
- Regionally, Asia Pacific dominates with 48% share, followed by North America at 26% and Europe at 17%. SaaS remains the leading deployment model with over 61% market share in 2024.
Market Segmentation Analysis:
By Deployment Type
The SaaS segment dominated the global ecommerce software and platform market in 2024 with over 61% share. Its leadership is driven by easy scalability, low upfront costs, and rapid integration with third-party applications. Cloud-based models allow businesses to deploy updates automatically and access analytics in real time. Vendors like Shopify and BigCommerce leverage SaaS infrastructure to support millions of active stores with minimal downtime. The growing preference for subscription-based models among SMEs and large enterprises continues to strengthen the dominance of SaaS deployment.
- For instance, Shopify operates over 2.3 million active online stores across 175 countries through its SaaS infrastructure. The company maintains an uptime of 99.99%,processing more than 10,000 orders per minute during peak sales periods.
By Business Model
The B2C segment held the leading 54% market share in 2024, supported by the expanding global online retail ecosystem. The model benefits from rapid smartphone adoption, digital payment integration, and personalized shopping experiences. Platforms such as Adobe Commerce and Wix provide AI-powered tools for targeted marketing and omnichannel management, enhancing user engagement. Rising consumer demand for direct-to-consumer shopping and same-day delivery is pushing brands to optimize B2C ecommerce operations. This trend continues to drive investment in flexible, high-performance ecommerce platforms globally.
- For instance, as of 2025, Adobe Commerce provides AI-powered product recommendations, with some users reporting an increase in average order value of up to 25%. While the platform has powered hundreds of thousands of stores, recent data indicates the active store count is now lower and varies depending on the reporting source.
By End-use
The electronics segment led the market with a 29% revenue share in 2024, reflecting strong digitalization and product availability through ecommerce channels. Online platforms enable detailed product comparisons, competitive pricing, and quick logistics fulfillment, which attract a large customer base. Major brands like Dell and Samsung have expanded proprietary online storefronts to boost direct sales. Growth in smart devices, home appliances, and consumer electronics continues to fuel online demand. The increasing role of AR-based visualization and real-time customer support further enhances electronic ecommerce adoption.
Key Growth Drivers
Rapid Digitalization and Internet Penetration
Rising global internet access and smartphone adoption are driving ecommerce platform expansion. Businesses are leveraging digital transformation to reach wider audiences through online storefronts, apps, and marketplaces. Affordable data plans and improved broadband infrastructure in emerging economies support new entrants and small sellers. Companies like Shopify and WooCommerce provide low-cost, scalable solutions that enable rapid online setup. Additionally, payment gateways such as PayPal and Stripe have simplified digital transactions, increasing consumer confidence in online purchases. This rapid digital adoption continues to fuel platform usage across retail, manufacturing, and service sectors.
- For instance, Shopify recorded approximately 875 million unique buyers across its network in 2024, representing one in six internet users globally.
Growing Preference for Omnichannel Retail
The increasing integration of online and offline retail channels is a major driver for ecommerce software adoption. Retailers are implementing omnichannel platforms to synchronize sales, inventory, and customer engagement across physical stores, websites, and mobile apps. Tools from companies like Adobe Commerce and Salesforce Commerce Cloud allow real-time customer tracking and personalized recommendations. Consumers now expect seamless shopping experiences, from browsing on mobile devices to completing in-store pickups. This behavioral shift is compelling retailers to upgrade existing systems and adopt unified ecommerce software that supports cross-channel operations efficiently.
- For instance, Adobe Commerce (formerly Magento) features a comprehensive Inventory Management module that allows for unified, multi-source inventory control. This functionality is designed for merchants with multiple warehouses, stores, or pickup locations and provides real-time stock updates across all sales channels.
Rise of SMEs and D2C Brands
The surge in small and medium enterprises (SMEs) and direct-to-consumer (D2C) brands is accelerating market growth. Easy access to SaaS-based ecommerce platforms enables startups to launch global operations with minimal infrastructure. Platforms like Wix and BigCommerce offer customizable templates, marketing automation, and payment integration, empowering independent sellers. D2C brands leverage data analytics to enhance customer relationships and reduce reliance on intermediaries. This transformation has opened vast opportunities for platform vendors catering to niche markets. As SME participation expands, demand for affordable, AI-driven, and scalable ecommerce solutions continues to rise globally.
Key Trends and Opportunities
Integration of Artificial Intelligence and Analytics
AI and predictive analytics are transforming ecommerce operations by enhancing personalization and efficiency. Platforms now use AI-driven engines to recommend products, optimize pricing, and automate marketing campaigns. Amazon and Alibaba have integrated machine learning algorithms that analyze billions of data points daily to refine customer experiences. AI chatbots are improving response times and reducing support costs for retailers. The growing need for data-driven decision-making presents opportunities for vendors offering intelligent analytics dashboards. As businesses adopt automation and AI-integrated solutions, ecommerce platforms gain a strong competitive edge through efficiency and customer insight.
- For instance, Amazon employs over 1.5 billion product data points per day through its recommendation engine.
Expansion into Emerging Economies
Ecommerce platforms are experiencing strong growth in developing regions such as Asia-Pacific, Latin America, and Africa. Expanding digital infrastructure, fintech adoption, and rising consumer spending are driving demand. Localized platforms like Jumia and Flipkart have tailored payment options, logistics support, and language integration to reach new audiences. Governments promoting digital inclusion and cross-border trade provide added momentum. Vendors focusing on regional customization, multilingual interfaces, and mobile-first platforms can capture significant market share. This expansion into underpenetrated markets offers long-term opportunities for ecommerce software providers worldwide.
Key Challenges
Cybersecurity and Data Privacy Concerns
The increasing volume of online transactions raises significant cybersecurity risks. Data breaches, phishing attacks, and payment fraud threaten both consumers and businesses. Ecommerce platforms handle vast amounts of personal data, requiring robust encryption and compliance with regulations such as GDPR and CCPA. Despite advanced security tools, many small retailers lack resources to implement full-scale protection. Cyber incidents not only cause financial loss but also damage brand trust. Strengthening multi-factor authentication, encryption, and data governance frameworks remains essential to ensure secure ecommerce operations globally.
High Competition and Market Saturation
The ecommerce software market faces intense competition, with numerous global and regional players offering similar features. Giants like Shopify, Magento, and WooCommerce dominate large segments, leaving limited space for new entrants. Price wars and constant innovation pressure smaller vendors to differentiate through niche offerings or specialized services. Additionally, frequent updates and integration requirements increase operational costs for both vendors and users. As market maturity rises, sustained growth will depend on advanced technologies, unique customer experiences, and targeted industry solutions to maintain competitive advantage.
Regional Analysis
North America
North America held a significant 26% share of the global ecommerce software and platform market in 2024, with revenue rising from USD 2,780.46 million in 2018 to USD 6,397.30 million. The market is projected to reach USD 17,633.22 million by 2032, growing at a CAGR of 12.6%. Growth is fueled by high internet penetration, advanced logistics infrastructure, and rapid adoption of cloud-based ecommerce solutions. Leading vendors such as Shopify and Salesforce Commerce Cloud continue to expand enterprise-level integrations and omnichannel capabilities, supporting sustained digital retail transformation across the region.
Europe
Europe accounted for 17% of the global market in 2024, increasing from USD 1,904.35 million in 2018 to USD 4,207.45 million, and projected to reach USD 10,471.14 million by 2032, at a CAGR of 11.2%. The region benefits from strong regulatory frameworks, digital trust, and cross-border ecommerce growth within the EU. Companies like SAP and PrestaShop enhance localization and payment integration features, improving user engagement. Expanding digital marketplaces and government-backed digital transformation programs continue to strengthen Europe’s ecommerce ecosystem.
Asia Pacific
Asia Pacific dominated the market with a 48% share in 2024, growing from USD 4,879.63 million in 2018 to USD 11,816.08 million and expected to reach USD 34,274.49 million by 2032, at a CAGR of 13.3%. The region’s growth is driven by large consumer bases, rising smartphone usage, and widespread digital payment adoption. Major players such as Alibaba and Shopify are expanding presence across India, China, and Southeast Asia. Government-led initiatives promoting online trade and SME digitalization further support ecommerce platform expansion in Asia Pacific.
Latin America
Latin America captured an 8% market share in 2024, expanding from USD 460.81 million in 2018 to USD 1,064.24 million, and is forecast to reach USD 2,560.53 million by 2032, at a CAGR of 10.7%. Regional growth is supported by improving digital payment infrastructure and increasing online retail participation. Platforms like VTEX and Nuvemshop are enhancing cross-border selling tools and omnichannel integration. The rise of social commerce and growing internet access in Brazil and Mexico continue to drive ecommerce platform adoption across Latin America.
Middle East
The Middle East represented nearly 5% of the global market in 2024, up from USD 263.53 million in 2018 to USD 558.02 million, and is expected to reach USD 1,262.80 million by 2032, registering a CAGR of 9.8%. Market expansion is supported by rapid urbanization, digital wallet growth, and retail modernization. Companies such as Salla and Zid are enabling local retailers to digitize operations efficiently. The increasing popularity of cross-border ecommerce and government-led digital economy initiatives further strengthen market potential.
Africa
Africa accounted for 4% of the market in 2024, rising from USD 154.87 million in 2018 to USD 402.13 million, and projected to reach USD 869.93 million by 2032, at a CAGR of 9.2%. Growing internet penetration, mobile commerce, and fintech innovation are key drivers. Local players like Jumia are expanding digital marketplaces and last-mile delivery networks to enhance accessibility. Despite infrastructure challenges, the rising adoption of mobile-based ecommerce platforms presents strong long-term opportunities for regional growth.
Market Segmentations:
By Deployment Type
- SaaS
- On-premise
- Hybrid
By Business Model
- B2B
- B2C
- Marketplace
- Others
By End-use
- Apparel
- Electronics
- Travel & Tourism
- Home & Furnishing
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The global ecommerce software and platform market is highly competitive, featuring a mix of established players and emerging innovators. Leading companies such as Shopify, WooCommerce, BigCommerce, Magento, and Salesforce Commerce Cloud dominate the landscape by offering scalable and customizable platforms that cater to businesses of all sizes. These firms focus on enhancing user experience, integrating AI-driven analytics, and supporting omnichannel retail operations. Smaller players like Wix eCommerce and Squarespace are gaining traction among SMEs through affordable, user-friendly solutions with integrated marketing tools. Strategic partnerships, acquisitions, and feature enhancements are central to maintaining market position. Vendors are also emphasizing security, mobile optimization, and cloud deployment to meet evolving customer expectations. The competition remains intense, with differentiation driven by innovation, integration capabilities, and value-added services such as automation, analytics, and seamless third-party connectivity across global digital ecosystems.
Key Player Analysis
- Shopify
- WooCommerce
- BigCommerce
- Magento
- Squarespace
- Wix eCommerce
- Salesforce Commerce Cloud
Recent Developments
- In May 2025, Square launched the Square Handheld, a sleek, pocket-sized POS device designed for restaurants and retailers. Weighing just 11 ounces with IP54 durability, it features a 6.2" Gorilla Glass touchscreen, barcode scanner, 16 MP camera, and full payment capabilities.
- In May 2025, Wix introduced Wixel, a standalone AI-powered visual design platform, democratizing professional-grade design for all users. Integrated with intuitive tools and OpenAI’s image-generation model, Wixel enables effortless background removal, context switching, and style customization within minutes.
- In April 2025, eBay strengthened its global strategic partnership with Klarna, introducing flexible payment methods, including Pay in 4, financing options, and reselling tools to US shoppers. This expansion enhances eBay’s checkout experience by improving affordability across categories such as electronics, fashion, and collectibles. The integration empowers structured payments and circular commerce, reflecting a growing commitment to seamless, customer-centric commerce enabled by Buy Now Pay Later innovation and sustainable shopping practices.
- In April 2025, BigCommerce announced an expanded commercial partnership with Noibu, integrating their eCommerce intelligence directly into BigCommerce’s platform. This collaboration enables one-click activation of Noibu’s enterprise-grade error detection and prioritization tools without separate contracts. The integration accelerates time-to-value, enhances proactive revenue protection by resolving technical and performance issues early, and fosters joint merchant success across growth stages.
Report Coverage
The research report offers an in-depth analysis based on Deployment Type, Business Model, End-use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- AI-driven personalization will enhance customer experience and optimize sales performance.
- Cloud-based SaaS platforms will remain the dominant deployment choice among businesses.
- Omnichannel retail integration will strengthen links between online and offline sales channels.
- Mobile commerce adoption will rise as smartphone-based shopping becomes mainstream.
- SMEs will continue driving market growth through low-cost and scalable ecommerce platforms.
- Cross-border ecommerce expansion will increase demand for localized and multilingual platforms.
- Data analytics and automation tools will improve marketing precision and operational efficiency.
- Security and compliance technologies will advance to address growing data privacy concerns.
- Emerging markets in Asia Pacific and Latin America will witness strong ecommerce adoption.
- Strategic partnerships and platform consolidation will shape the future competitive landscape.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Digitalization and Internet Penetration
Expanding internet access and smartphone adoption globally are enabling more businesses and consumers to participate in ecommerce, driving demand for scalable and accessible ecommerce software platforms. Affordable data plans and improved broadband infrastructure, especially in emerging markets, are accelerating online retail adoption.
Growing Preference for Omnichannel Retail
Retailers are increasingly integrating online and offline channels to provide seamless customer experiences, which requires advanced ecommerce platforms capable of synchronizing sales, inventory, and engagement across multiple touchpoints. This trend is pushing businesses to invest in unified, omnichannel-ready software solutions.
Rise of SMEs and D2C Brands
The proliferation of small and medium enterprises and direct-to-consumer brands is fueling market growth, as these businesses seek affordable, easy-to-deploy SaaS ecommerce platforms to quickly establish and scale their online presence. Customizable templates, integrated marketing, and payment solutions are particularly attractive to this segment.
Integration of Artificial Intelligence and Analytics
AI-driven personalization, predictive analytics, and automation are transforming ecommerce operations by enhancing customer engagement, optimizing marketing, and improving operational efficiency. Platforms that offer intelligent analytics and automation tools are gaining a competitive edge as businesses seek data-driven insights.
Expansion into Emerging Economies
Strong growth in regions like Asia Pacific, Latin America, and Africa is being driven by expanding digital infrastructure, fintech adoption, and rising consumer spending. Localized platforms and government initiatives supporting digital inclusion are opening new opportunities for ecommerce software providers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Ecommerce Software and Platform market?
At what Compound Annual Growth Rate is the Global Ecommerce Software and Platform market projected to grow between 2025 and 2032?
What factors are driving the growth of the Ecommerce Software and Platform market?
What are some challenges faced by the Ecommerce Software and Platform market?
Who are the major players in the Ecommerce Software and Platform market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-use
- 1.2.1 Apparel
- 1.2.2 Electronics
- 1.2.3 Travel & Tourism
- 1.2.4 Home & Furnishing
- 1.2.5 Others
- 1.3 By Business Model
- 1.3.1 B2B
- 1.3.2 B2C
- 1.3.3 Marketplace
- 1.3.4 Others
- 1.4 By Deployment Type
- 1.4.1 SaaS
- 1.4.2 On-premise
- 1.4.3 Hybrid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 24,445.22 million → 2032: USD 67,072.11 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ecommerce Software and Platform Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ecommerce Software and Platform Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Ecommerce Software and Platform Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Ecommerce Software and Platform Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ecommerce Software and Platform Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ecommerce Software and Platform Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ecommerce Software and Platform Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ecommerce Software and Platform Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 24,445.22 million → 2032: USD 67,072.11 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ecommerce Software and Platform Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Apparel
- 12.3.6.2 Electronics
- 12.3.6.3 Travel & Tourism
- 12.3.6.4 Home & Furnishing
- 12.3.6.5 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Business Model - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 B2B
- 12.4.6.2 B2C
- 12.4.6.3 Marketplace
- 12.4.6.4 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 SaaS
- 12.5.6.2 On-premise
- 12.5.6.3 Hybrid
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ecommerce Software and Platform End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ecommerce Software and Platform Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ecommerce Software and Platform Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ecommerce Software and Platform Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Shopify
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 WooCommerce
- 18.4 BigCommerce
- 18.5 Magento
- 18.6 Squarespace
- 18.7 Wix eCommerce
- 18.8 Salesforce Commerce Cloud
- 18.9 Adobe Commerce
- 18.10 SAP
- 18.11 VTEX
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

