
Market Overview
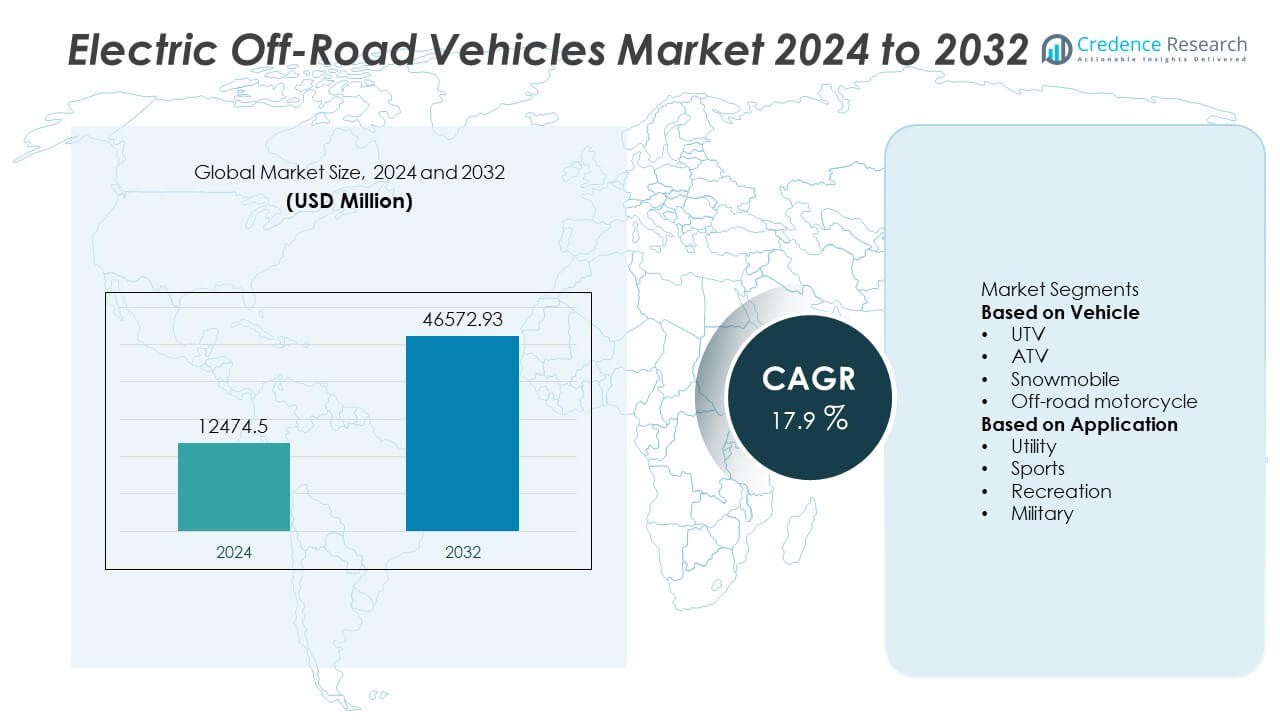
The Electric Off-Road Vehicles Market was valued at USD 12,474.5 million in 2024 and is projected to reach USD 46,572.93 million by 2032, growing at a CAGR of 17.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Off-Road Vehicles Market Size 2024 | USD 12,474.5 Million |
| Electric Off-Road Vehicles Market, CAGR | 17.9% |
| Electric Off-Road Vehicles Market Size 2032 | USD 46,572.93 Million |
The electric off-road vehicles market is led by prominent players including TACITA, Polaris, Zero Motorcycles, Deere, KTM, Hisun, Alke, Daymak, Intimidator, and American Landmaster. These companies dominate through innovation in electric drivetrains, extended-range batteries, and all-terrain performance capabilities. North America emerged as the leading region in 2024, holding a 36% share of the global market, driven by high recreational vehicle ownership and strong adoption in farming and utility sectors. Europe followed with a 29% share, supported by sustainability regulations and e-mobility incentives. Asia-Pacific captured 27%, fueled by expanding electric mobility manufacturing and increasing demand for eco-friendly off-road solutions.
Market Insights
- The electric off-road vehicles market was valued at USD 12,474.5 million in 2024 and is projected to reach USD 46,572.93 million by 2032, growing at a CAGR of 17.9% during the forecast period.
- Rising adoption of electric UTVs and ATVs, which together account for 70% of total demand, is driving market growth supported by environmental regulations and the shift toward zero-emission recreational vehicles.
- Increasing integration of digital dashboards, lithium-ion battery systems, and fast-charging technology is transforming product design and improving performance efficiency.
- Key players such as Polaris, TACITA, Zero Motorcycles, Deere, and Hisun are expanding through product diversification, hybrid innovations, and electric powertrain advancements to strengthen global presence.
- North America leads with 36% share, followed by Europe with 29% and Asia-Pacific with 27%, while the utility segment dominates applications with 40% share, driven by demand from agriculture, construction, and adventure tourism sectors.
Market Segmentation Analysis:
By Vehicle
The UTV segment dominated the electric off-road vehicles market in 2024, accounting for over 45% of the total share. UTVs are widely adopted in agriculture, construction, and outdoor adventure activities due to their superior towing capacity, stability, and ability to carry multiple passengers. Electric UTVs offer quiet operation, reduced maintenance, and zero tailpipe emissions, making them suitable for both recreational and utility use. Advancements in lithium-ion batteries and drivetrain efficiency have enhanced vehicle range and performance, further strengthening UTV adoption in both commercial and recreational segments.
- For instance, the Polaris RANGER XP Kinetic UTV Ultimate trim is powered by a 29.8 kWh lithium-ion battery pack, delivering 110 horsepower and 190 Nm of torque. It achieves a towing capacity of 1,134 kg and a range of up to 129 km per charge.
By Application
The utility segment led the market in 2024, capturing around 40% of the total share, driven by rising demand across farming, forestry, and industrial operations. Electric off-road vehicles are increasingly used for hauling, transportation, and inspection tasks where noise reduction and low emissions are critical. The sports segment followed with a 30% share, benefiting from growing interest in adventure tourism and competitive racing. Increasing adoption in government and military operations, supported by durable all-terrain designs, continues to expand the role of electric off-road vehicles in specialized utility applications.
- For instance, Deere's Gator TE electric utility vehicle operates with a 48V system powered by an eight-battery configuration, provides a payload capacity of 408 kg and a top speed of up to 20.92 km/h (13 mph). Some sources suggest the vehicle can run for approximately 7 to 8 hours per charge, making it suitable for quiet, emission-free operation in environments where internal combustion engines are restricted.
Key Growth Drivers
Rising Demand for Eco-Friendly Recreational Vehicles
Growing environmental awareness and tightening emission standards are driving the demand for electric off-road vehicles. Consumers are increasingly shifting toward zero-emission UTVs, ATVs, and motorcycles for recreational and adventure activities. These vehicles offer quieter operation, lower maintenance, and high torque output compared to gasoline-powered models. Government incentives for electric mobility and outdoor recreation growth further support adoption. As sustainability becomes a key purchasing factor, electric off-road vehicles are emerging as a preferred choice for eco-conscious enthusiasts and professionals.
- For instance, TACITA's 2024 T-Race Enduro electric motorcycle is equipped with a 9 kWh lithium-ion battery and a 34 kW motor. The bike supports a real-world range of approximately 100-118 km and offers a charging time ranging from 1.5 to 5 hours, depending on the charger used. It is one of several zero-emission off-road motorcycles in its class.
Advancements in Battery Technology and Range Capabilities
Rapid improvements in lithium-ion and solid-state batteries are boosting the performance of electric off-road vehicles. Enhanced energy density, faster charging, and longer lifespans enable extended riding time and improved reliability across tough terrains. Manufacturers are integrating modular battery packs and regenerative braking to optimize energy efficiency. These innovations reduce charging downtime and make electric off-road vehicles suitable for longer recreational or utility use. As technology costs decline, battery advancements are expected to remain a central driver of market growth.
- For instance, The Hisun Motors Sector E1 electric UTV features a 48V Discover Dry Cell battery system. The model is capable of a range of more than 68 kilometers and a top speed of 40 km/h. It includes a regenerative braking system and a 1.2 kW onboard charger that enables recharging within 6 to 10 hours.
Government Incentives and Infrastructure Development
Global governments are supporting electric mobility adoption through subsidies, tax rebates, and charging infrastructure expansion. Policies promoting clean energy transport and emission-free recreational areas are accelerating market penetration. Many regions now permit electric vehicles in protected zones where conventional engines are restricted. Additionally, investments in off-grid and portable charging stations enhance operational flexibility. This growing regulatory and infrastructural support is encouraging both individual consumers and fleet operators to transition toward electric off-road solutions.
Key Trends & Opportunities
Integration of Smart and Connected Technologies
Digital integration is transforming the electric off-road vehicle market. Features like GPS navigation, Bluetooth connectivity, and performance monitoring enhance user experience and vehicle management. IoT-enabled systems allow real-time data tracking, remote diagnostics, and safety alerts for riders. Manufacturers are incorporating AI-driven controls for terrain adaptation and torque management. These innovations improve efficiency and attract tech-savvy consumers. The integration of smart systems offers strong opportunities for premiumization and differentiation in a competitive landscape.
- For instance, Zero Motorcycles integrates its proprietary Cypher III+ operating system in the DSR/X electric adventure bike, enabling smartphone connectivity, route planning, and over-the-air firmware updates. The system manages a 17.3 kWh lithium-ion battery and provides adaptive traction control that adjusts torque delivery based on road conditions, with telemetry capable of processing over 100 real-time performance parameters for enhanced off-road stability and control.
Expansion of Adventure Tourism and Recreational Activities
The growing popularity of outdoor adventure tourism and recreational sports is fueling electric off-road vehicle sales. Consumers seek sustainable options for activities such as trail riding, desert exploration, and snow adventures. Electric variants provide silent operation and minimal environmental disruption, aligning with eco-tourism goals. Rental and tour companies are increasingly adopting electric fleets to meet demand for sustainable travel. This trend presents significant growth potential for manufacturers focusing on performance-oriented and eco-friendly designs.
- For instance, the Daymak Beast 2 AWD off-road scooter is available with dual 1,000 W hub motors. The scooter offers a range of approximately 60 km per charge with the optional 60V 40Ah lithium battery. This model's rugged suspension and all-terrain tires enable travel across dirt trails and hilly terrains. It is marketed as a low-impact vehicle for outdoor exploration.
Key Challenges
High Initial Costs and Limited Model Availability
Electric off-road vehicles remain expensive compared to traditional models due to costly batteries and advanced electronic systems. Limited mass production and low-scale supply chains also contribute to higher prices. In many regions, the variety of available models remains restricted, reducing consumer accessibility. These factors deter adoption among budget-conscious buyers and small commercial operators. However, manufacturers are working to mitigate costs through localized production, modular design, and flexible financing solutions.
Insufficient Charging Infrastructure and Range Constraints
The lack of robust charging infrastructure remains a major barrier to widespread adoption. Off-road trails, farms, and recreational parks often lack convenient charging access, limiting usability for long-duration activities. Although portable and solar-powered charging systems are emerging, availability remains low. Range limitations also pose challenges for professional and adventure users requiring extended runtime. Expanding fast-charging networks and improving battery efficiency are critical to overcoming these operational constraints and achieving broader market adoption.
Regional Analysis
North America
North America dominated the electric off-road vehicles market in 2024, holding a 36% share of the global market. The region’s leadership is driven by high adoption in recreational sports, agriculture, and military operations. The United States leads demand due to strong consumer interest in sustainable adventure vehicles and supportive government incentives for electric mobility. Expanding charging infrastructure and product innovation from major manufacturers further strengthen market growth. The presence of established brands and rising off-road tourism continues to make North America a key hub for electric ATV, UTV, and off-road motorcycle development.
Europe
Europe accounted for a 28% share of the electric off-road vehicles market in 2024, supported by stringent emission norms and sustainability-focused policies. Countries such as Germany, France, and the United Kingdom are promoting electrified mobility across recreational and utility applications. The region’s emphasis on eco-friendly adventure tourism and green transport incentives drives demand for electric UTVs and ATVs. Manufacturers are investing in advanced battery systems and lightweight materials to enhance vehicle performance. With strong regulatory support and growing outdoor recreation culture, Europe remains a significant market for electric off-road innovations.
Asia-Pacific
Asia-Pacific captured a 29% share of the global electric off-road vehicles market in 2024, emerging as one of the fastest-growing regions. China, Japan, and India dominate production and adoption, supported by large-scale manufacturing capabilities and favorable government incentives. Expanding rural electrification, infrastructure development, and low-cost battery availability fuel regional demand. Increasing participation in off-road sports and utility applications, particularly in agriculture and construction, further strengthens growth. Rapid technological innovation and the presence of domestic brands offering affordable electric UTVs and motorcycles position Asia-Pacific as a powerhouse for future expansion.
Latin America
Latin America held a 4% share of the electric off-road vehicles market in 2024, driven by growing adoption across agricultural and recreational sectors. Brazil and Mexico lead the region’s market with increasing investments in sustainable mobility and outdoor tourism. Consumers are shifting toward eco-friendly off-road solutions to reduce fuel dependency and maintenance costs. Although high vehicle prices and limited charging networks pose challenges, the rise of rental services and government interest in electrification support gradual growth. Manufacturers targeting cost-effective, durable electric vehicles are expected to gain traction in this evolving market.
Middle East & Africa
The Middle East and Africa accounted for a 3% share of the global electric off-road vehicles market in 2024, supported by expanding infrastructure and increasing interest in recreational mobility. The United Arab Emirates and Saudi Arabia lead regional demand due to strong investment in electric mobility and outdoor adventure activities. Electric UTVs and ATVs are gaining popularity in desert tourism and agricultural operations. However, limited charging access and high import costs restrict faster adoption. Ongoing government efforts toward clean energy transition and tourism development are expected to create new growth opportunities across the region.
Market Segmentations:
By Vehicle
- UTV
- ATV
- Snowmobile
- Off-road motorcycle
By Application
- Utility
- Sports
- Recreation
- Military
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the electric off-road vehicles market includes key players such as TACITA, Hisun, Polaris, Alke, Deere, Intimidator, KTM, Zero Motorcycles, American Landmaster, and Daymak. These companies compete through innovations in powertrain technology, battery performance, and vehicle design to enhance range, durability, and off-road capabilities. Leading manufacturers focus on expanding their product lines with high-torque motors, regenerative braking systems, and advanced suspension technologies suited for rugged terrains. Strategic partnerships and investments in lightweight materials are improving vehicle efficiency and performance. Companies are also leveraging digital connectivity and remote diagnostics to enhance user experience. As environmental regulations tighten and demand for eco-friendly recreation rises, manufacturers are prioritizing cost efficiency, modular battery systems, and global distribution networks to gain a competitive edge. Continuous R&D in fast-charging solutions and hybrid-electric variants is further shaping the evolution of the electric off-road vehicle market.
Key Player Analysis
- TACITA
- Hisun
- Polaris
- Alke
- Deere
- Intimidator
- KTM
- Zero Motorcycles
- American Landmaster
- Daymak
Recent Developments
- In 2025, KTM released the 2025 FREERIDE E, a nearly all-new electric off-road motorcycle with 11 kW nominal output, 18.5 kW peak power, more than 37 Nm torque, and a top speed of ~95 km/h.
- In 2025, Polaris began shipping its updated 2025 ATV models, signaling production ramp for its powersports line.
- In August 2024, Polaris expanded its 2025 off-road vehicle lineup with new trims and vehicle variants, including the return of trail-oriented models like the RANGER XP 1000 NorthStar Trail Boss.
- In 2024, Polaris also upgraded its RZR XP line for 2025 with enhancements like a standard 4,500 lb winch on the Ultimate trim and refreshed graphics across the model range.
Report Coverage
The research report offers an in-depth analysis based on Vehicle, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The electric off-road vehicles market will expand rapidly with growing demand for sustainable recreation.
- Manufacturers will focus on enhancing battery life, torque, and terrain adaptability.
- Integration of smart connectivity and GPS-based tracking will improve vehicle performance.
- Government incentives will continue to support electric vehicle adoption in utility and defense sectors.
- Lightweight materials and modular battery systems will drive product innovation.
- Hybrid and fully electric off-road models will gain traction in agriculture and mining applications.
- North America will remain the largest regional market due to strong consumer spending and outdoor activities.
- Asia-Pacific will experience the fastest growth with expanding manufacturing and e-mobility initiatives.
- Partnerships between OEMs and battery technology firms will improve charging efficiency and range.
- Advancements in autonomous and AI-assisted driving systems will shape the next generation of electric off-road vehicles.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Electric Off-Road Vehicles market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electric Off-Road Vehicles market projected to grow between 2025 and 2032?
Which Electric Off-Road Vehicles market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electric Off-Road Vehicles market?
Who are the leading companies in the Electric Off-Road Vehicles market?
Which region commanded the largest share of the Electric Off-Road Vehicles market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,474.5 million → 2032: USD 46,572.93 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Off-Road Vehicles Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Off-Road Vehicles Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Off-Road Vehicles Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Off-Road Vehicles Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Off-Road Vehicles Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Off-Road Vehicles Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Off-Road Vehicles Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Off-Road Vehicles Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,474.5 million → 2032: USD 46,572.93 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Off-Road Vehicles Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Off-Road Vehicles Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Electric Off-Road Vehicles Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Electric Off-Road Vehicles Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

