
Market Overview
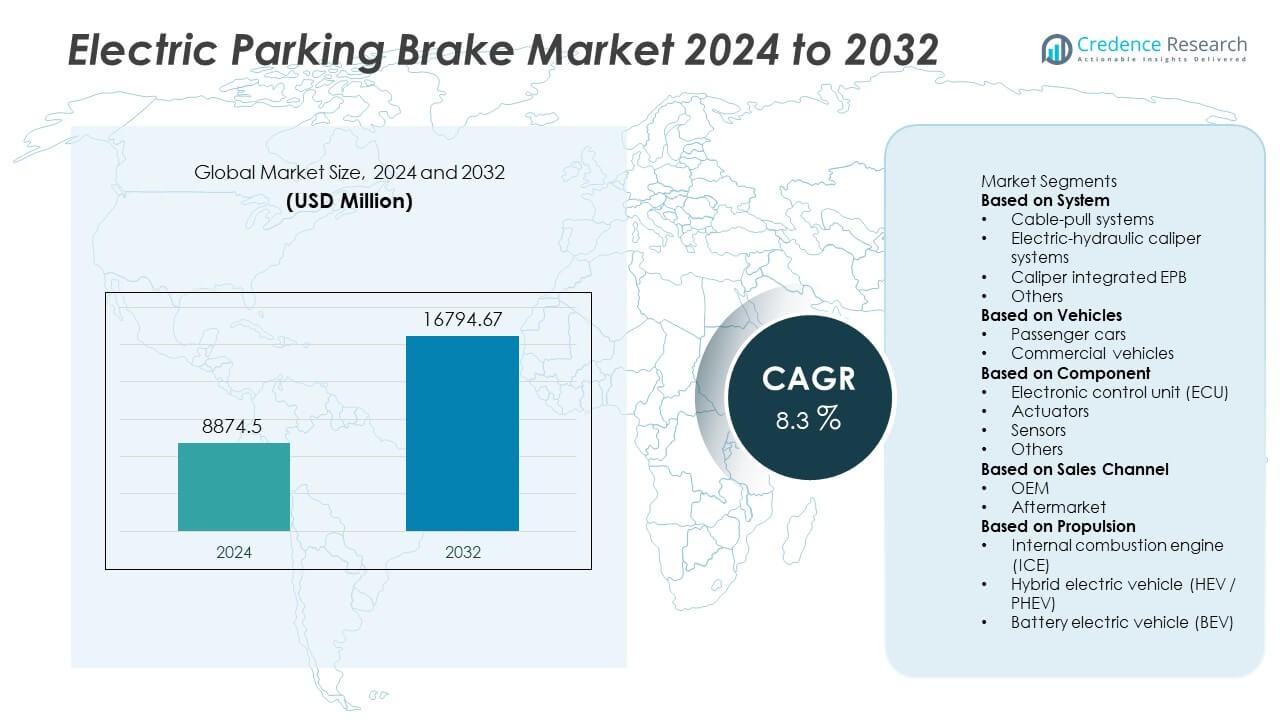
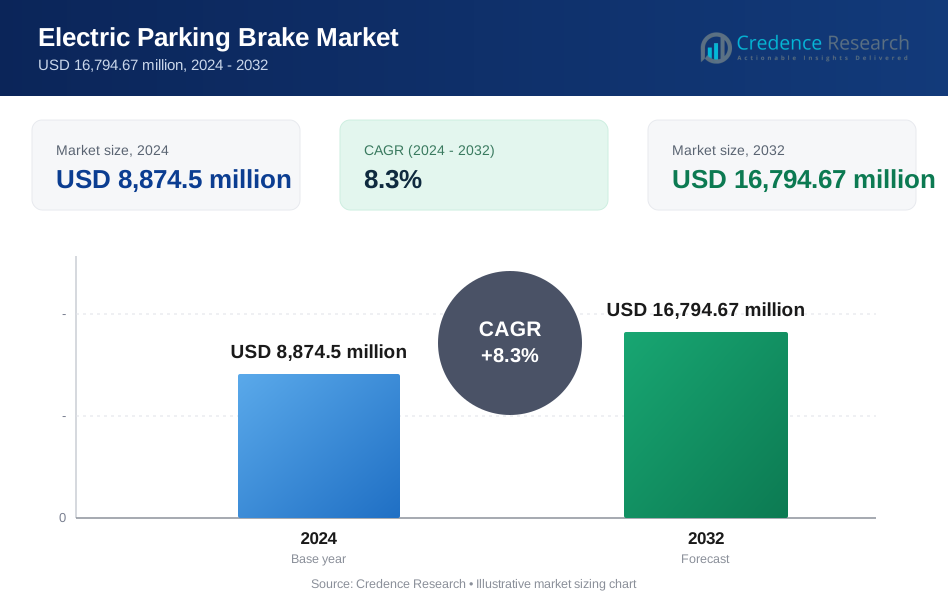
The Electric Parking Brake (EPB) market was valued at USD 8,874.5 million in 2024 and is projected to reach USD 16,794.67 million by 2032, registering a CAGR of 8.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Parking Brake Market Size 2024 | USD 8,874.5 Million |
| Electric Parking Brake Market, CAGR | 8.3% |
| Electric Parking Brake Market Size 2032 | USD 16,794.67 Million |
The Electric Parking Brake market is led by major companies including ZF Friedrichshafen, Continental, Robert Bosch, Hitachi Astemo, Aisin Seiki, Hyundai Mobis, Knorr-Bremse, Mando, Brembo, and Akebono Brake Industry. These players dominate through advanced braking technologies, integration with electronic stability systems, and strategic OEM partnerships. Europe emerged as the leading region, capturing 32% of the global market share in 2024, driven by strong automotive manufacturing and strict safety regulations. Asia-Pacific followed with 30%, supported by high vehicle production and EV adoption, while North America accounted for 28%, emphasizing advanced driver-assistance system integration.
Market Insights
- The Electric Parking Brake market was valued at USD 8,874.5 million in 2024 and is projected to reach USD 16,794.67 million by 2032, growing at a CAGR of 8.3%.
- Growth is driven by rising vehicle electrification, integration of ADAS features, and increasing demand for automated safety systems across passenger cars and commercial vehicles.
- The market is witnessing a trend toward lightweight, integrated, and software-driven EPB systems designed for electric and hybrid platforms, enhancing energy efficiency and braking control.
- Leading companies such as ZF Friedrichshafen, Continental, Robert Bosch, and Hitachi Astemo focus on partnerships, R&D, and regional manufacturing expansion to maintain competitive strength.
- Europe led the market with 32% share in 2024, followed by Asia-Pacific at 30% and North America at 28%, while the caliper integrated EPB segment dominated by system type with over 45% share.
Market Segmentation Analysis:
By System
The caliper integrated EPB segment dominated the Electric Parking Brake market in 2024, accounting for over 45% of the total share. Its leadership is driven by compact design, lower maintenance, and direct integration with the rear brake caliper, improving efficiency and space utilization. Automakers prefer this system for mid- and high-end vehicles due to easy assembly and reduced cable use. The shift toward lightweight designs and fully electronic braking systems in EVs and premium sedans continues to strengthen this segment’s adoption over cable-pull and electric-hydraulic systems.
- For instance, Continental AG's MK C2 is an electro-hydraulic brake-by-wire system that integrates the master cylinder, brake booster, and control systems (ABS and ESC) into a single, lightweight module. It supports 100% regenerative braking and features a compact electronic control unit.
By Vehicle
The passenger car segment held the largest share of around 70% in 2024, reflecting strong integration of EPB systems in luxury and mid-range vehicles. Rising adoption of ADAS and autonomous features has accelerated the use of electronic braking over manual systems. Growing EV production, especially across Europe and Asia-Pacific, further supports passenger car dominance. Consumers’ demand for safety, convenience, and advanced control systems continues to boost EPB installation in compact and premium car models globally.
- For instance, the integrated braking system in the BMW iX series combines functions like brake actuation, force assistance, and brake control into a single module. It uses an electric actuator to trigger the required brake pressure dynamically, providing excellent and precise deceleration performance.
By Component
The electronic control unit (ECU) segment led the market with over 40% share in 2024, driven by its essential role in controlling actuation, diagnostics, and integration with vehicle stability systems. ECUs ensure precise engagement and disengagement, enhancing driver safety and system reliability. Automakers increasingly adopt intelligent ECUs compatible with regenerative braking and automated functions in EVs and hybrids. Continuous innovation in microcontrollers and software-based calibration supports the growing reliance on ECU-driven braking control across global automotive platforms.
Key Growth Drivers
Rising Adoption of Advanced Safety and Driver Assistance Systems
The increasing integration of advanced driver-assistance systems is fueling growth in the Electric Parking Brake market. EPB technology enhances vehicle safety with automatic engagement, hill-start assist, and emergency braking support. Automakers are focusing on improving driving comfort and meeting stricter safety standards by replacing manual braking systems with electronic ones. As vehicles move toward greater automation, electronic braking solutions are becoming essential for safe and reliable performance.
- For instance, Robert Bosch GmbH’s iBooster system is an electromechanical brake booster that uses an electric motor and gear unit to amplify the driver's braking input and convert it into hydraulic pressure within the master cylinder. In conjunction with the Electronic Stability Program (ESP) and ADAS sensors, it enables functions like autonomous emergency braking and adaptive cruise control.
Expansion of Electric and Hybrid Vehicle Production
The global shift toward electric and hybrid mobility is accelerating the adoption of Electric Parking Brakes. These vehicles demand compact, electronically controlled braking systems that reduce mechanical complexity and improve energy efficiency. Automakers are integrating EPBs to support regenerative braking and enhance vehicle control. The growing availability of electric models across segments is strengthening the role of EPB systems in next-generation mobility platforms.
- For instance, Hitachi Astemo’s advanced EPB module for electric and hybrid vehicles integrates a 48V motor actuator with regenerative energy capture. The company develops these technologies to maximize eco-friendliness and improve driving performance.
Regulatory Push for Enhanced Vehicle Safety Standards
Tightening vehicle safety regulations across regions are driving the replacement of traditional braking mechanisms with electronic systems. Government policies emphasizing driver assistance, automatic braking, and stability control encourage manufacturers to adopt EPB technologies. Automakers are responding to global safety initiatives by integrating EPBs into both premium and mass-market models. This regulatory shift reinforces the technology’s importance in achieving higher safety compliance and reliability.
Key Trends and Opportunities
Integration with Autonomous and Connected Vehicle Platforms
The integration of Electric Parking Brakes with connected and autonomous vehicle systems is emerging as a key trend. EPB units can communicate with other control modules for automated operation, remote diagnostics, and predictive maintenance. These capabilities enhance both safety and convenience in modern mobility applications. As connected technologies advance, EPB systems are expected to play a central role in supporting vehicle automation.
- For instance, ZF Friedrichshafen’s Integrated Brake Control (IBC) system combines the functions of the electronic stability control, brake booster, and brake assist into a single, vacuum-independent electro-hydraulic unit.
Lightweight and Modular EPB Designs for Efficiency
Manufacturers are emphasizing lightweight and modular EPB systems to improve efficiency and simplify integration. Compact actuators, low-voltage electronics, and durable materials are enabling better energy use and design flexibility. This shift benefits electric and hybrid vehicles, where space and weight savings are critical. The trend also creates opportunities for suppliers to develop high-performance, customizable solutions for diverse vehicle architectures.
- For instance, HL Mando develops integrated electronic parking brake (EPB) systems, such as its Motor-on-Caliper (MoC) products, designed for modern vehicle platforms and offering a streamlined design with reduced size and weight compared to conventional braking systems.
Key Challenges
High Implementation and Maintenance Costs
Widespread adoption of Electric Parking Brakes faces cost-related hurdles, especially in price-sensitive markets. Advanced components such as sensors and control units increase production expenses compared to manual systems. Servicing electronic systems also requires specialized diagnostic tools and trained technicians, adding to ownership costs. These financial barriers continue to limit EPB penetration in entry-level vehicle categories.
Reliability Concerns in Harsh Environmental Conditions
Electric Parking Brakes face performance challenges under extreme temperature, humidity, or dust exposure. Electronic circuits and actuators may experience degradation, leading to reduced system reliability. Manufacturers are enhancing component protection through better sealing, corrosion-resistant materials, and adaptive control software. Despite ongoing improvements, ensuring long-term durability in demanding environments remains a critical concern for automakers and suppliers.
Regional Analysis
North America
North America held a market share of 28% in the Electric Parking Brake market in 2024. Growth is supported by strong demand for premium vehicles equipped with advanced safety systems. The United States leads the region due to high adoption of ADAS and increased electric vehicle production. Major automakers such as General Motors and Ford are integrating EPB systems into new hybrid and electric models. Canada’s growing focus on road safety standards and consumer preference for convenience-based features also contribute to regional market expansion.
Europe
Europe accounted for 32% of the global Electric Parking Brake market in 2024, making it the leading regional segment. The region’s dominance is driven by strict vehicle safety regulations and widespread electrification initiatives. Germany, France, and the United Kingdom are key contributors, with luxury and electric vehicle manufacturers such as BMW, Volkswagen, and Renault actively adopting EPB technology. High consumer demand for comfort and performance features further supports the use of electronic braking systems in both passenger and light commercial vehicles across Europe.
Asia-Pacific
Asia-Pacific captured 30% of the Electric Parking Brake market in 2024, fueled by rapid vehicle production and growing EV adoption. China, Japan, and South Korea lead the region, supported by strong domestic manufacturing and government incentives for electrification. Expanding middle-class income and consumer preference for technologically advanced vehicles drive EPB installation across passenger and premium car segments. Local suppliers are also strengthening their partnerships with global OEMs to produce cost-efficient EPB components, improving regional supply chain capacity and competitiveness.
Latin America
Latin America represented 6% of the Electric Parking Brake market in 2024. Brazil and Mexico dominate regional adoption due to rising production of compact and mid-range vehicles equipped with electronic systems. Increasing investments from global automakers and growing demand for safety-enhanced cars support gradual EPB penetration. However, high production costs and limited aftermarket infrastructure slow widespread implementation. Government-led automotive modernization programs are expected to encourage future growth, especially as vehicle electrification expands in the region’s key economies.
Middle East and Africa
The Middle East and Africa held a market share of 4% in the Electric Parking Brake market in 2024. The region’s growth is supported by increasing sales of luxury and imported vehicles that feature EPB systems. The United Arab Emirates and Saudi Arabia drive market expansion through premium car imports and rising consumer demand for advanced safety technologies. In Africa, countries such as South Africa are seeing early adoption due to improving automotive manufacturing capabilities. Gradual infrastructure development and economic growth are expected to support future EPB market penetration.
Market Segmentations:
By System
- Cable-pull systems
- Electric-hydraulic caliper systems
- Caliper integrated EPB
- Others
By Vehicles
- Passenger cars
- Commercial vehicles
By Component
- Electronic control unit (ECU)
- Actuators
- Sensors
- Others
By Sales Channel
- OEM
- Aftermarket
By Propulsion
- Internal combustion engine (ICE)
- Hybrid electric vehicle (HEV / PHEV)
- Battery electric vehicle (BEV)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Electric Parking Brake market includes key players such as ZF Friedrichshafen, Mando, Continental, Hitachi Astemo, Aisin Seiki, Knorr-Bremse, Robert Bosch, Brembo, Hyundai Mobis, and Akebono Brake Industry. These companies focus on technological innovation, integration of intelligent control systems, and partnerships with major automakers to strengthen their market presence. Leading manufacturers are expanding their portfolios with compact, energy-efficient, and software-driven EPB systems suited for electric and autonomous vehicles. Continuous R&D investments support advancements in actuator design, sensors, and ECUs for improved performance and safety compliance. Strategic mergers, collaborations, and supply agreements with global OEMs remain central to market positioning. Regional production expansions, particularly in Asia-Pacific and Europe, enable faster delivery and cost optimization, ensuring competitiveness across diverse vehicle platforms.
Key Player Analysis
- ZF Friedrichshafen
- Mando
- Continental
- Hitachi Astemo
- Aisin Seiki
- Knorr-Bremse
- Robert Bosch
- Brembo
- Hyundai Mobis
- Akebono Brake Industry
Recent Developments
- In September 2025, Robert Bosch presented brake-by-wire solutions at IAA Mobility, advancing software-defined braking.
- In January 2025, ZF Friedrichshafen secured major brake-by-wire business for light vehicles, underscoring its EPB/BBW roadmap.
- In September 2024, Knorr-Bremse showcased next-gen brake control platforms at IAA Transportation, supporting electrification and automation.
- In November 2023, Mando (HL Mando) highlighted its parking-automation and electrified brake focus around CES recognition for “Parkie.”
Report Coverage
The research report offers an in-depth analysis based on System, Vehicles, Component, Sales Channel, Propulsion and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Electric Parking Brake market will continue expanding with the global shift toward vehicle electrification.
- Integration of EPB systems in autonomous and connected vehicles will increase significantly.
- Manufacturers will invest more in compact and modular EPB designs to reduce weight and improve efficiency.
- Software-driven braking control and diagnostic features will become standard in next-generation vehicles.
- Partnerships between EPB suppliers and EV manufacturers will strengthen global supply chains.
- Demand for intelligent ECUs and sensor-based control units will rise in premium and mid-segment vehicles.
- Regulatory policies promoting road safety and automation will accelerate EPB adoption across regions.
- Cost reduction through localized production and digital manufacturing will improve market competitiveness.
- Replacement of traditional mechanical handbrakes will continue across passenger and commercial vehicle segments.
- Asia-Pacific will emerge as the fastest-growing region, supported by rising EV production and strong OEM expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Electric Parking Brake market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electric Parking Brake market projected to grow between 2025 and 2032?
Which Electric Parking Brake market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electric Parking Brake market?
Who are the leading companies in the Electric Parking Brake market?
Which region commanded the largest share of the Electric Parking Brake market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Electric Parking Brake Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Electric Parking Brake Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,874.5 million → 2032: USD 16,794.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Electric Parking Brake Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Electric Parking Brake Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Electric Parking Brake Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Electric Parking Brake Market Drivers
- 3.3 Electric Parking Brake Market Restraints & Challenges
- 3.4 Electric Parking Brake Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Electric Parking Brake Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Electric Parking Brake Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Electric Parking Brake category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Electric Parking Brake Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Electric Parking Brake Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Electric Parking Brake market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Electric Parking Brake Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Electric Parking Brake Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Electric Parking Brake Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Electric Parking Brake (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Electric Parking Brake Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Electric Parking Brake Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Electric Parking Brake Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Electric Parking Brake Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Electric Parking Brake Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Electric Parking Brake Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Electric Parking Brake Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Electric Parking Brake Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Electric Parking Brake Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
