
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Vehicle Adhesives Market Size 2024 | USD 986.2 million |
| Electric Vehicle Adhesives Market, CAGR | 26.50% |
| Electric Vehicle Adhesives Market Size 2032 | USD 6,466.8 million |
Market Overview:
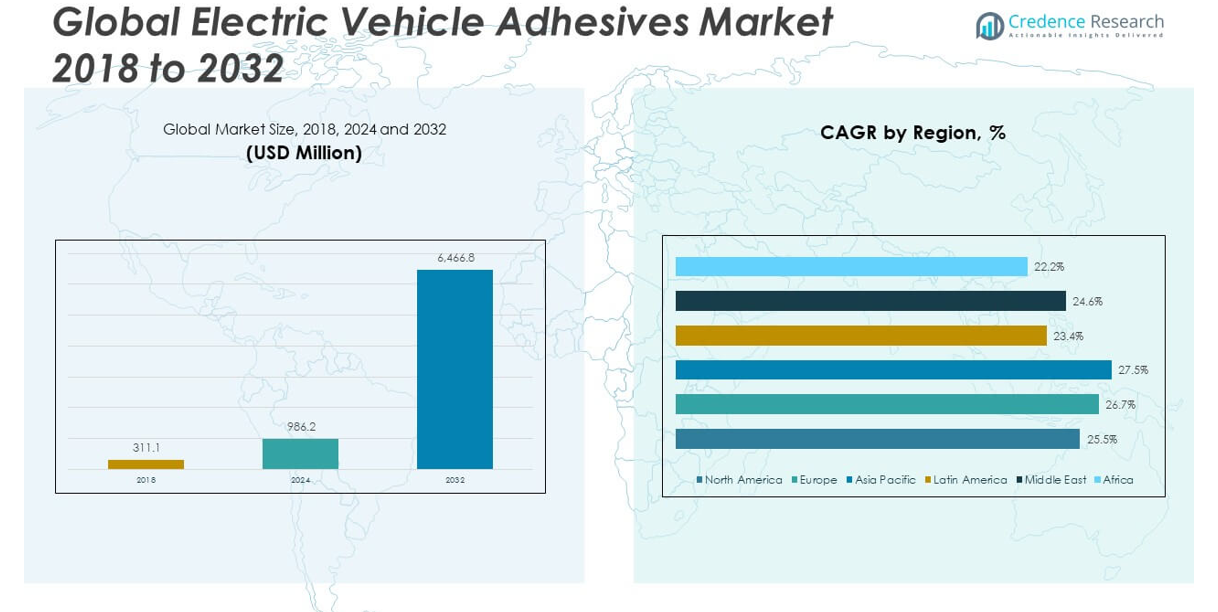
The Electric Vehicle Adhesives Market size was valued at USD 311.1 million in 2018 to USD 986.2 million in 2024 and is anticipated to reach USD 6,466.8 million by 2032, at a CAGR of 26.50% during the forecast period.
Several key factors are driving the growth of the electric vehicle adhesives market. The global shift towards sustainable and eco-friendly transportation solutions has led to a surge in electric vehicle production. Adhesives are essential in EV manufacturing for applications such as battery pack assembly, powertrain systems, and structural bonding. Their ability to bond diverse materials like metals, plastics, and composites is vital for enhancing the performance, safety, and efficiency of EVs. Additionally, advancements in battery technology and the need for lightweight materials to improve energy efficiency are further propelling the demand for specialized adhesives. The growing focus on reducing vehicle weight for improved battery efficiency and extended range has accelerated the use of lightweight adhesive materials in EV manufacturing, boosting market growth.
Regionally, the Asia-Pacific region dominates the electric vehicle adhesives market, accounting for a significant share due to the rapid growth of electric vehicle production in countries like China, Japan, and South Korea. China, in particular, has become a global leader in electric vehicle manufacturing, driving the demand for adhesives in battery systems, powertrain assembly, and vehicle body parts. The presence of major automotive manufacturers in these countries and strong government support for EV adoption contribute to the region's market leadership. Additionally, the increasing investments in EV infrastructure, such as charging stations and battery production facilities, are fueling the demand for adhesives in the region. Europe and North America are also witnessing substantial growth in the EV adhesives market, driven by stringent environmental regulations and increasing consumer demand for electric vehicles. Governments in these regions are implementing stricter emission regulations, which further push the adoption of electric vehicles and, consequently, increase the demand for specialized adhesives in EV production.
Market Insights:
- The Electric Vehicle Adhesives Market is growing rapidly, from USD 311.1 million in 2018 to an anticipated USD 6,466.8 million by 2032, driven by the increasing demand for electric vehicles (EVs) and their components.
- Government policies and regulations promoting eco-friendly transportation, such as stricter emission standards, are fueling the adoption of electric vehicles and consequently increasing the demand for specialized adhesives.
- Technological advancements in adhesives for lightweight materials are a key growth factor, as they help improve energy efficiency and vehicle performance by reducing weight in electric vehicles.
- Adhesives used in battery assembly, powertrain integration, and structural bonding are essential in enhancing the safety, performance, and efficiency of EVs, particularly in high-demand areas like battery management.
- The need for higher-performing and safer battery systems is pushing the demand for advanced adhesives, which help secure battery cells and enhance thermal management for longer EV ranges.
- The market faces challenges in developing high-performance adhesives capable of withstanding high temperatures, extreme pressures, and constant vibrations in EV manufacturing.
- Regional dominance in the electric vehicle adhesives market is observed in Asia-Pacific, where countries like China, Japan, and South Korea drive significant demand, supported by substantial investments in EV production and infrastructure.
Market Drivers:
Growing Demand for Electric Vehicles and Environmental Regulations
The rising demand for electric vehicles (EVs) is one of the most significant drivers of the electric vehicle adhesives market. The global shift towards sustainable and eco-friendly transportation solutions has increased the production of EVs across the automotive industry. Government policies and regulations in various regions have been designed to accelerate the adoption of electric vehicles, including stricter emission standards and incentives for EV buyers. These regulations have fostered a favorable environment for manufacturers to invest in EV production, driving the need for advanced adhesives. In EV manufacturing, adhesives are essential in applications such as battery assembly, powertrain integration, and structural bonding, contributing to enhanced performance and safety.
Technological Advancements in Adhesives for Lightweight Materials
Advancements in adhesive technology have also played a critical role in the growth of the electric vehicle adhesives market. Modern adhesives enable the bonding of lightweight materials, which is crucial for improving energy efficiency and performance in electric vehicles. The automotive industry increasingly uses composites and lightweight materials to reduce vehicle weight and improve battery efficiency. Adhesives provide a strong, durable bond between different materials such as metals, plastics, and composites, which are used extensively in EVs. By replacing traditional mechanical fasteners with adhesives, manufacturers can improve aerodynamics, reduce weight, and increase the overall energy efficiency of electric vehicles.
- For example, DuPont’s BETAFORCE™ Elastic Structural Adhesive, a 2024 R&D 100 award winner, bonds aluminum-laminated film substrates without primers, offers up to 30% renewable content, and cures at room temperature eliminating the need for high-temperature ovens and reducing energy consumption during manufacturing.
Growing Need for Battery Efficiency and Enhanced Performance
The shift towards higher efficiency batteries and improved performance in electric vehicles has spurred the need for specialized adhesives. Adhesives are essential in creating secure battery packs and ensuring proper thermal management in EVs. These adhesives play a role in securing battery cells, which are critical for maintaining the safety and longevity of electric vehicle batteries. As the demand for longer-range EVs increases, manufacturers are turning to adhesives to enhance the performance and durability of batteries, enabling faster charging times and higher energy retention. The need for higher-performing and safer batteries continues to drive the demand for advanced adhesives.
Strategic Focus on Cost Efficiency and Increased Manufacturing Capacity
Another key driver of the electric vehicle adhesives market is the automotive industry's focus on reducing production costs while increasing manufacturing capacity. Manufacturers are increasingly turning to adhesives as a cost-effective solution for joining materials without the need for mechanical fasteners, which can be expensive and time-consuming to install. Adhesives also streamline the manufacturing process, allowing for greater precision in assembly. As demand for electric vehicles increases, automotive manufacturers are scaling up their production and incorporating adhesives into their processes to enhance efficiency and reduce costs. This growing trend in the automotive sector supports the growth of the electric vehicle adhesives market.
- For example, Henkel’s new range of sustainable adhesives for EV battery packs and Sika’s strategic partnerships with major EV manufacturers are directly aimed at scaling up production while maintaining high technical standards.
Market Trends:
Increased Focus on Sustainable and Eco-friendly Adhesives
One of the prominent trends in the electric vehicle adhesives market is the growing demand for eco-friendly and sustainable adhesive solutions. Environmental concerns surrounding traditional adhesive materials have led to a shift toward greener alternatives that are both biodegradable and recyclable. Manufacturers in the automotive sector are increasingly focused on reducing the carbon footprint of their vehicles, and this includes the adhesives used in the production process. The use of bio-based adhesives that meet stringent environmental standards is gaining traction. These eco-friendly adhesives align with the overall sustainability goals of electric vehicle manufacturers and are expected to play a significant role in the market's growth.
Development of High-performance Adhesives for Battery Integration
The electric vehicle adhesives market is witnessing significant advancements in adhesive technologies specifically designed for battery integration. As electric vehicles rely heavily on efficient battery systems, the need for adhesives that provide both structural integrity and effective thermal management has become crucial. Adhesives are used to bond battery cells, manage thermal expansion, and enhance the overall safety and performance of EV batteries. Manufacturers are investing in the development of specialized adhesives that can withstand the high temperatures and stresses associated with EV battery packs. These innovations contribute to longer battery life, better energy retention, and safer battery operation, directly impacting the performance of electric vehicles.
- For instance, H.B. Fuller’s EV THERM 441 is a modified acrylic adhesive with a UL94 V0 flame retardancy rating and a controlled adhesive gap of 0.25 mm (0.01 in), engineered for excellent thermal conductivity and mechanical strength across metals, thermoplastics, and thermosets.
Shift Toward Lightweight Materials and Structural Bonding Applications
Another major trend is the increasing use of lightweight materials in the automotive industry, which is driving the demand for structural adhesives in electric vehicle manufacturing. Lightweighting is critical for improving the efficiency of electric vehicles by reducing overall vehicle weight and enhancing battery range. Adhesives offer a reliable solution for bonding materials such as aluminum, carbon fiber, and plastics, which are increasingly used in the production of electric vehicle components. As automakers strive for greater fuel efficiency and extended driving range, the role of structural adhesives in EV assembly becomes more prominent. This trend toward lightweighting is expected to continue, further boosting the demand for specialized adhesives.
Integration of Smart Adhesives in EV Production
The integration of smart adhesives into electric vehicle production is an emerging trend gaining momentum. Smart adhesives, which have the ability to change properties in response to external stimuli such as temperature or pressure, are becoming more prevalent in EV manufacturing. These adhesives provide enhanced performance by adapting to changing conditions in real-time. For example, certain smart adhesives can improve battery safety by providing additional bonding strength when the temperature rises, thus reducing the risk of thermal runaway. The increasing use of smart adhesives in EV production is expected to drive growth in the electric vehicle adhesives market, offering manufacturers enhanced reliability and performance.
- For example, triboelectric sensors embedded in adhesives can maintain stable performance after 2,000 cycles at 200°C, providing robust pressure and temperature sensing capabilities well beyond human perception ranges (25–200°C)
Market Challenges Analysis:
Challenges in Developing High-Performance Adhesives for EV Applications
A significant challenge in the electric vehicle adhesives market is the need for high-performance adhesives that meet the demanding requirements of electric vehicle production. Adhesives used in EV manufacturing must withstand high temperatures, extreme pressures, and constant vibrations while maintaining bond strength and reliability over time. The integration of adhesives into battery systems, powertrains, and structural components adds complexity, as these adhesives must ensure both durability and safety. Developing adhesives that can handle these challenging conditions without compromising performance or longevity remains a critical hurdle for manufacturers. Overcoming this challenge requires continuous innovation and extensive testing to meet the unique demands of the electric vehicle sector.
Cost Pressures and Raw Material Availability
Cost pressures and the availability of raw materials represent another challenge in the electric vehicle adhesives market. The demand for adhesives that are both high-performing and cost-effective places strain on manufacturers, particularly in a competitive and cost-sensitive market like electric vehicles. The sourcing of raw materials for adhesive production, such as resins and curing agents, can be subject to market fluctuations, impacting pricing and availability. This unpredictability in raw material costs can affect the pricing structure for adhesives used in electric vehicles. Additionally, manufacturers face the challenge of balancing the need for high-quality materials with cost-efficiency, as automakers increasingly prioritize affordability in EV production. These factors contribute to the complexities that adhesive suppliers face in scaling production while maintaining competitive pricing.
Market Opportunities:
Expansion of Electric Vehicle Production and Adhesive Demand
The rapid expansion of electric vehicle (EV) production presents significant opportunities in the electric vehicle adhesives market. As automakers scale up their efforts to meet increasing consumer demand for electric vehicles, the need for specialized adhesives is expected to rise. Adhesives are essential in improving vehicle performance, reducing weight, and enhancing battery efficiency, all of which are crucial for the success of EVs. The growing number of EV manufacturers entering the market further increases the demand for adhesives tailored to EV production, offering opportunities for suppliers to innovate and expand their offerings. This growth trajectory presents substantial revenue potential for adhesive manufacturers targeting the automotive industry.
Advancements in Sustainable and High-Performance Adhesive Solutions
There is a notable opportunity in developing sustainable and high-performance adhesive solutions for the electric vehicle market. With an increasing focus on reducing the environmental impact of manufacturing processes, the demand for eco-friendly adhesives is growing. Manufacturers are eager to incorporate greener alternatives that align with sustainability goals. At the same time, innovations in adhesives that offer enhanced thermal, structural, and electrical properties create opportunities for differentiation in the market. By developing solutions that meet the stringent performance and environmental standards of the EV industry, suppliers can position themselves as key players in a rapidly growing and evolving market.
Market Segmentation Analysis:
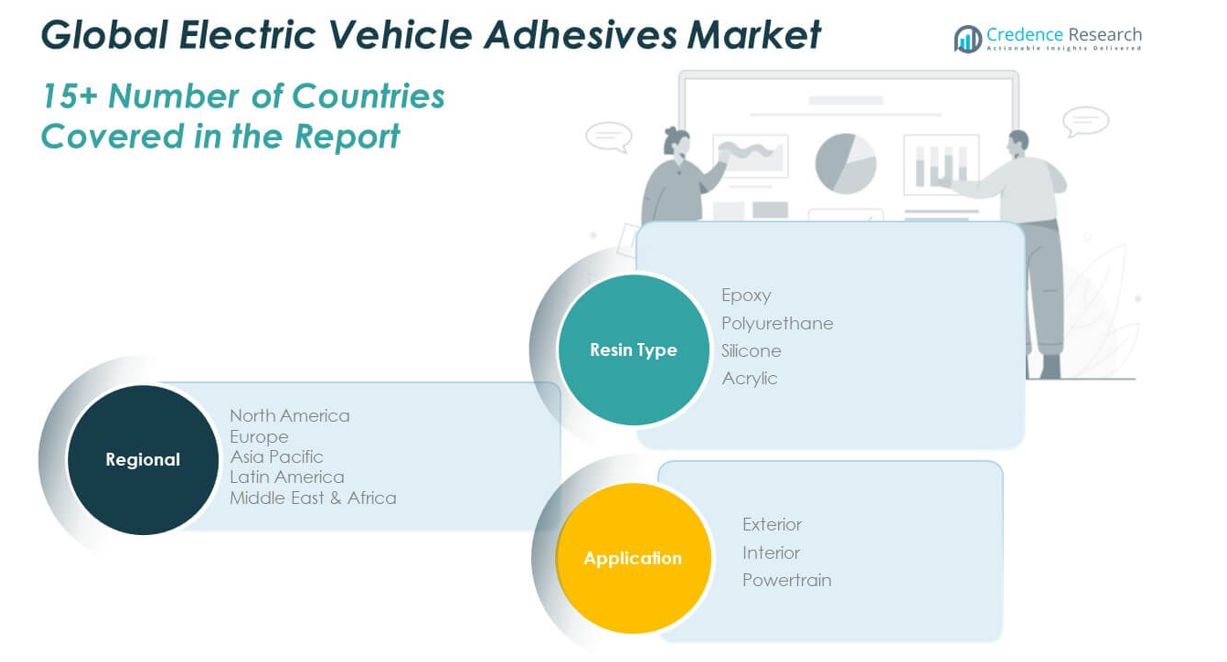
The electric vehicle adhesives market is segmented by resin type and application, with each segment contributing to the market's growth.
By Resin Type, the market is divided into Epoxy, Polyurethane, Silicone, and Acrylic adhesives. Epoxy adhesives are widely used due to their superior bonding strength and thermal stability, making them ideal for battery assembly and powertrain applications. Polyurethane adhesives are known for their flexibility and resistance to moisture, making them suitable for exterior applications and sealing components. Silicone adhesives are highly valued for their temperature resistance, which is crucial in high-temperature areas like powertrain systems. Acrylic adhesives are increasingly used for their fast curing properties and versatility in bonding a wide range of materials.
- For instance, 3M™ Polyurethane Adhesive 540 delivers high flexibility (elongation 400%) and excellent moisture resistance, making it suitable for exterior bonding and sealing in automotive applications, and meets automotive weathering standards.
By Application, the market is categorized into Exterior, Interior, and Powertrain applications. Exterior adhesives are used primarily for bonding body parts, windows, and trim, focusing on durability and weather resistance. Interior adhesives are applied in areas such as cabin fixtures, dashboards, and seating, where comfort and strength are essential. Powertrain adhesives are critical for ensuring the integrity of EV power systems, including battery packs and electric motors, requiring high-performance adhesives to maintain safety and efficiency in demanding conditions.
- For example, SikaPower®-4725 is used for bonding body parts, windows, and trim, providing weather resistance, durability, and UV resistance.
Segmentation:
By Resin Type:
- Epoxy
- Polyurethane
- Silicone
- Acrylic
By Application:
- Exterior
- Interior
- Powertrain
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Electric Vehicle Adhesives Market
The North America Electric Vehicle Adhesives Market size was valued at USD 50.7 million in 2018, USD 182.4 million in 2024, and is anticipated to reach USD 1,286.9 million by 2032, at a CAGR of 25.5% during the forecast period. North America holds a significant market share, driven by the rapid growth in electric vehicle adoption, particularly in the United States and Canada. Government policies promoting clean energy and EV incentives further boost the demand for EVs, creating a favorable environment for adhesive suppliers. The region’s advanced automotive industry, coupled with the increasing demand for lightweight vehicles and efficient battery systems, contributes to market growth. Additionally, North America benefits from the presence of major automotive manufacturers and adhesive suppliers, fostering innovation and competition within the market. The shift toward electric vehicle production in the region further strengthens its position in the global electric vehicle adhesives market.
Europe Electric Vehicle Adhesives Market
The Europe Electric Vehicle Adhesives Market size was valued at USD 56.0 million in 2018, USD 246.6 million in 2024, and is anticipated to reach USD 1,771.9 million by 2032, at a CAGR of 26.7% during the forecast period. Europe represents one of the fastest-growing regions in the electric vehicle adhesives market due to the region's strong commitment to sustainability and environmental regulations. The European Union's stringent emissions standards and its aggressive targets for electric vehicle adoption drive the demand for EV adhesives. Major automotive manufacturers in countries like Germany, France, and the UK are heavily investing in EV production, increasing the need for specialized adhesives. The shift towards electrification of public transportation and commercial fleets further supports market expansion in Europe, ensuring long-term growth in this region.
Asia Pacific Electric Vehicle Adhesives Market
The Asia Pacific Electric Vehicle Adhesives Market size was valued at USD 168.0 million in 2018, USD 448.7 million in 2024, and is anticipated to reach USD 2,547.9 million by 2032, at a CAGR of 27.5% during the forecast period. Asia Pacific dominates the global electric vehicle adhesives market, holding the largest market share due to the rapid growth in electric vehicle manufacturing in China, Japan, and South Korea. China is the world’s largest producer and consumer of electric vehicles, contributing significantly to the regional market share. The region's strong automotive industry, combined with government initiatives to promote clean energy vehicles, further accelerates the adoption of adhesives in EV manufacturing. As electric vehicle adoption continues to rise, the demand for adhesives in battery packs, structural bonding, and lightweight materials will continue to expand across the region.
Latin America Electric Vehicle Adhesives Market
The Latin America Electric Vehicle Adhesives Market size was valued at USD 14.0 million in 2018, USD 33.5 million in 2024, and is anticipated to reach USD 206.9 million by 2032, at a CAGR of 23.4% during the forecast period. The market in Latin America is experiencing growth as electric vehicle adoption gradually gains momentum, particularly in countries like Brazil and Mexico. Government incentives and international trade agreements are encouraging the production and sale of electric vehicles in the region. The increasing focus on reducing carbon emissions and transitioning to renewable energy sources has driven local demand for EVs, consequently boosting the demand for adhesives. The automotive sector's growth and investment in EV infrastructure are key drivers for the region’s expanding electric vehicle adhesives market.
Middle East Electric Vehicle Adhesives Market
The Middle East Electric Vehicle Adhesives Market size was valued at USD 18.4 million in 2018, USD 57.2 million in 2024, and is anticipated to reach USD 413.9 million by 2032, at a CAGR of 24.6% during the forecast period. The Middle East is witnessing significant growth in the electric vehicle adhesives market as governments in countries such as the UAE and Saudi Arabia are focusing on reducing carbon footprints and diversifying their energy sources. Growing investments in electric mobility infrastructure and the adoption of EVs in public transportation systems are expected to drive market demand. The region’s large-scale adoption of renewable energy further supports the transition to electric vehicles, increasing the need for specialized adhesives in EV manufacturing.
Africa Electric Vehicle Adhesives Market
The Africa Electric Vehicle Adhesives Market size was valued at USD 4.0 million in 2018, USD 17.8 million in 2024, and is anticipated to reach USD 239.3 million by 2032, at a CAGR of 22.2% during the forecast period. The electric vehicle adhesives market in Africa is at an early stage but is poised for growth as the automotive industry in the region begins to shift towards electric mobility. Several African nations are implementing policies that promote electric vehicle adoption and aim to reduce environmental pollution. The rising demand for EVs in countries like South Africa and Kenya, coupled with the growing interest in energy-efficient solutions, contributes to the growth of the electric vehicle adhesives market. Increasing investments in the EV infrastructure and battery production in the region also create opportunities for adhesive manufacturers to expand their presence in the African market.
Key Player Analysis:
- Henkel AG & Co. KGaA
- 3M Company
- Sika AG
- B. Fuller
- Dow Inc.
- Bostik (Arkema Group)
- Wacker Chemie AG
- Ashland Inc.
- LORD Corporation (Parker Hannifin)
- Permabond LLC
- SinoHarvest (USA)
- Huntsman Corporation
- Arkema S.A.
- Evonik Industries AG
Competitive Analysis:
The electric vehicle adhesives market is highly competitive, with several key players leading the industry. Companies such as Henkel AG & Co., 3M, and H.B. Fuller dominate the market, offering a wide range of high-performance adhesives designed for various EV applications, including battery assembly, structural bonding, and lightweight materials integration. These players focus on innovation, developing advanced adhesive solutions that meet the evolving needs of electric vehicle manufacturers. Strategic collaborations and partnerships between automotive OEMs and adhesive suppliers help strengthen market positions. For instance, many adhesive manufacturers collaborate with EV producers to design customized solutions that enhance performance, safety, and efficiency. Market players also emphasize sustainability, developing eco-friendly adhesives to meet regulatory demands and consumer preferences. As demand for electric vehicles grows, competition intensifies, with companies expanding their product portfolios to address new applications and capture a larger market share in this rapidly growing sector.
Recent Developments:
- In April 2025, Henkel officially launched a suite of advanced solutions for electric vehicle batteries, including AI-generated virtual adhesives, mica-replacement safety coatings, structural adhesive debonding, and cutting-edge electrode coatings.
- In May 2025, 3M entered a distribution partnership with Ellsworth Adhesives to meet the growing demand for its Scotch-Weld One-Part Epoxy Adhesives 6101 and 6102, which are used in electronics and automotive manufacturing, including EV battery assemblies. These new adhesives offer high impact resistance, improved throughput, and are designed for efficient, automated production lines.
- In May 2024, H.B. Fuller acquired ND Industries Inc., a leading provider of specialty adhesives and fastener locking solutions for the automotive and electronics sectors. This acquisition expands H.B. Fuller’s product portfolio and service offering in high-growth, high-margin segments, including EV adhesives.
Market Concentration & Characteristics:
The electric vehicle adhesives market is moderately concentrated, with a few key players commanding significant market share. Leading companies such as Henkel AG & Co., 3M, and H.B. Fuller dominate the landscape by offering a range of high-performance adhesive solutions tailored to electric vehicle manufacturing. These players invest heavily in research and development to create innovative products that cater to the growing demand for lightweight, durable, and sustainable adhesives. The market is characterized by intense competition, with manufacturers focused on meeting the evolving needs of electric vehicle producers, particularly in battery assembly, structural bonding, and energy efficiency. Companies are also placing emphasis on sustainability by developing eco-friendly adhesive solutions to comply with stringent environmental regulations. The market’s concentration is expected to remain stable, with major players expanding their product portfolios and forming strategic partnerships to strengthen their competitive edge.
Report Coverage:
The research report offers an in-depth analysis based on resin type and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The electric vehicle adhesives market is expected to grow at a robust pace, driven by increasing EV adoption globally.
- The shift towards lightweight materials will continue to boost demand for specialized adhesives in vehicle manufacturing.
- Innovations in adhesive technology will play a key role in improving battery performance, safety, and efficiency.
- The demand for eco-friendly adhesives will rise, aligning with stricter environmental regulations and sustainability goals.
- Rising investments in EV infrastructure will contribute to higher adhesive consumption for automotive applications.
- The growing electric vehicle production in Asia-Pacific, especially China, will dominate market growth.
- Strategic partnerships between adhesive suppliers and automakers will intensify to create tailored adhesive solutions.
- Expansion of EV manufacturing in emerging markets will present new opportunities for adhesive providers.
- The increasing need for advanced adhesives in autonomous electric vehicle production will foster market growth.
- As the market matures, competition will intensify, encouraging further innovation and product diversification.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surge in Electric Vehicle Production
The rapid global shift toward sustainable transportation is driving a significant increase in electric vehicle manufacturing, which directly boosts demand for adhesives used in battery assembly, powertrain systems, and structural bonding.
Technological Advancements in Lightweight Adhesives
Innovations in adhesive technology enable the bonding of lightweight materials such as composites and plastics, helping automakers reduce vehicle weight, improve energy efficiency, and extend EV range, thereby increasing the need for advanced adhesives.
Stringent Environmental Regulations
Government policies and stricter emission standards in major markets are accelerating the adoption of electric vehicles, which in turn raises the demand for specialized adhesives that meet both performance and environmental requirements.
Growth in Battery Efficiency and Safety Requirements
As EV manufacturers focus on developing higher-performing and safer battery systems, the need for adhesives that provide secure bonding, thermal management, and vibration resistance in battery packs is rising, fueling market growth.
Expansion of EV Infrastructure and Manufacturing Capacity
Increasing investments in EV infrastructure, such as charging stations and battery production facilities, along with the scaling up of automotive manufacturing, are driving higher consumption of adhesives in the sector.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Electric Vehicle Adhesives Market?
What factors are driving the growth of the Electric Vehicle Adhesives Market?
What are some challenges faced by the Electric Vehicle Adhesives Market?
Who are the major players in the Electric Vehicle Adhesives Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Resin Type
- 1.2.1 Epoxy
- 1.2.2 Polyurethane
- 1.2.3 Silicone
- 1.2.4 Acrylic
- 1.3 By Application
- 1.3.1 Exterior
- 1.3.2 Interior
- 1.3.3 Powertrain
- 1.4 By Vehicle Type
- 1.4.1 Battery Electric Vehicles (BEV)
- 1.4.2 Plug-in Hybrid Electric Vehicles (PHEV)
- 1.4.3 Hybrid Electric Vehicles (HEV)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 311.1 million → 2024: USD 986.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2024
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2024
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Vehicle Adhesives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Vehicle Adhesives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2024
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2024
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Vehicle Adhesives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2024
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Vehicle Adhesives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Vehicle Adhesives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Vehicle Adhesives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Vehicle Adhesives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Vehicle Adhesives Market Outlook, 2018-2024
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 311.1 million → 2024: USD 986.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2024
- 11.2.1 Revenue Forecast to 2024
- 11.2.2 Volume Forecast to 2024
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Vehicle Adhesives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Resin Type - Market Size and Forecast, 2018-2024
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2024
- 12.3.4 Volume Forecast, 2018-2024
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Epoxy
- 12.3.7.2 Polyurethane
- 12.3.7.3 Silicone
- 12.3.7.4 Acrylic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2024
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2024
- 12.4.4 Volume Forecast, 2018-2024
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Exterior
- 12.4.7.2 Interior
- 12.4.7.3 Powertrain
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2018-2024
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2024
- 12.5.4 Volume Forecast, 2018-2024
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Battery Electric Vehicles (BEV)
- 12.5.7.2 Plug-in Hybrid Electric Vehicles (PHEV)
- 12.5.7.3 Hybrid Electric Vehicles (HEV)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Vehicle Adhesives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electric Vehicle Adhesives Geographic Market Outlook, 2018-2024
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2024
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electric Vehicle Adhesives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2024
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electric Vehicle Adhesives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2024
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Henkel AG & Co. KGaA
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 3M Company
- 18.4 Sika AG
- 18.5 H.B. Fuller
- 18.6 Dow Inc.
- 18.7 Bostik (Arkema Group)
- 18.8 Wacker Chemie AG
- 18.9 Ashland Inc.
- 18.10 LORD Corporation (Parker Hannifin)
- 18.11 Permabond LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

