
Market Overview:
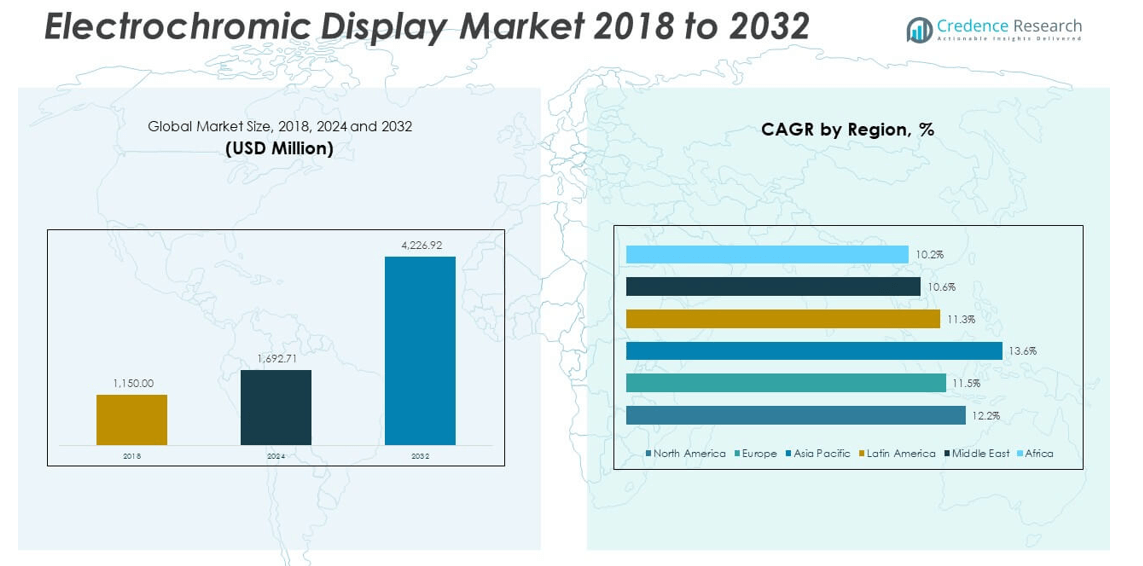
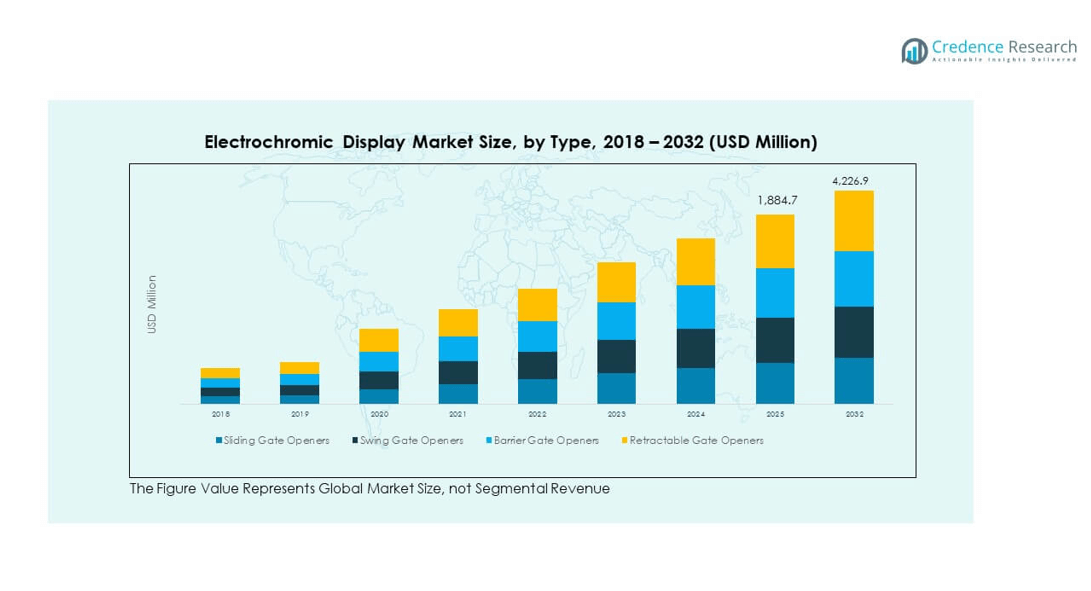
The Global Electrochromic Display Market size was valued at USD 1,150.00 million in 2018, reaching USD 1,692.71 million in 2024, and is anticipated to attain USD 4,226.92 million by 2032, at a CAGR of 12.23% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electrochromic Display Market Size 2024 | USD 1,692.71 million |
| Electrochromic Display Market , CAGR | 12.23% |
| Electrochromic Display Market Size 2032 | USD 4,226.92 million |
Growth in this market is driven by rising adoption of energy-efficient and smart display technologies across industries. Automotive manufacturers integrate electrochromic displays into rear-view mirrors, sunroofs, and infotainment systems to improve safety and comfort. Consumer electronics increasingly use electrochromic features for e-readers, wearables, and portable devices due to low power consumption. Expanding use in advertising, defense, and medical devices further strengthens demand, with innovations in electrochemical, electrowetting, and OLED-based technologies fueling momentum.
Geographically, North America and Europe lead the market due to strong automotive and architectural integration. Asia Pacific emerges as the fastest-growing region, supported by rising consumer electronics adoption in China, Japan, and South Korea. Latin America and the Middle East show gradual adoption, primarily in construction and automotive applications. Africa remains a nascent market but holds future potential through urbanization and growing interest in energy-efficient infrastructure.
Market Insights:
- The Global Electrochromic Display Market size was USD 1,150.0 million in 2018, reached USD 1,692.7 million in 2024, and is projected to attain USD 4,226.9 million by 2032, registering a CAGR of 12.23% during the forecast period.
- North America (31.9%), Europe (27.9%), and Asia Pacific (26.5%) accounted for the top three shares in 2024, driven by strong adoption in automotive, smart infrastructure, and consumer electronics.
- Asia Pacific, with 26.5% share in 2024, is the fastest-growing region, fueled by rapid industrialization, strong consumer electronics demand, and large-scale smart city investments.
- Transparent electrochromic displays dominated the market with an estimated 41% share in 2024, owing to their widespread use in automotive and smart window applications.
- Reflective and transflective displays collectively captured around 37% share in 2024, supported by adoption in low-power devices, signage, and outdoor applications.
Market Drivers:
Rising Adoption of Energy-Efficient Technologies in Automotive and Construction:
Automotive manufacturers integrate electrochromic displays into mirrors, dashboards, and sunroofs to improve efficiency and comfort. Construction firms adopt smart windows with electrochromic features to reduce heating and cooling costs. Growing environmental regulations drive both sectors to favor sustainable technologies. The Global Electrochromic Display Market benefits from these investments in energy efficiency. Consumers seek solutions that combine functionality and environmental responsibility. Companies highlight sustainability as a key selling point in competitive markets. Partnerships between technology developers and OEMs expand product reach. Rising demand for energy-saving solutions ensures continued market momentum.
- For instance, Saint-Gobain’s SageGlass RealTone™, launched in February 2025, offers electrochromic glazing that significantly reduces glare and thermal load with natural neutral tinting, boosting sustainable building design. Growing environmental regulations drive both sectors to favor sustainable technologies.
Integration of Electrochromic Displays in Consumer Electronics and Wearables:
The proliferation of portable and connected devices fuels adoption of electrochromic displays. Manufacturers use them in e-readers, smartwatches, and mobile devices due to low energy needs. Compact form factors and flexibility enable designs that attract tech-savvy consumers. The Global Electrochromic Display Market experiences growth through high-volume electronics adoption. Brands emphasize longer battery life and sleek aesthetics to appeal to buyers. Wearables integrate displays that balance clarity and minimal power use. Product differentiation depends on performance, durability, and user experience. Continued miniaturization enhances demand across personal devices.
- For instance, the Texas-based Polytronix, Inc. manufactures switchable privacy glass (marketed as Polyvision) that uses a liquid crystal polymer film to change from opaque to clear when an electrical current is applied. This low-power technology is suitable for architectural applications like conference rooms and partitions.
Technological Advancements Expanding Product Capabilities Across Applications:
Continuous R&D improves electrochromic technologies through higher resolution and faster switching speeds. Innovations in OLED and electrowetting displays open new opportunities for vibrant visuals. The Global Electrochromic Display Market evolves as companies refine durability and scalability. Military and aerospace applications value rugged displays with low visibility signatures. Medical devices adopt compact and efficient formats for diagnostic tools. Investment in nanotechnology and thin-film coatings increases product reliability. Manufacturers focus on enhancing bio-compatibility for healthcare usage. The market gains strength from multi-sector adoption driven by advanced features.
Government Support and Regulatory Push for Sustainable Technologies:
Policies encouraging green building and energy-saving devices accelerate electrochromic adoption. Governments promote incentives for smart infrastructure projects with electrochromic windows. The Global Electrochromic Display Market gains momentum from public-private partnerships in technology integration. Standards for emissions reduction stimulate adoption across transportation and construction. Defense spending supports advanced display integration for secure communication. Consumer subsidies for energy-efficient solutions increase purchasing power. Vendors align strategies with policy frameworks to strengthen positioning. These policies form a stable foundation for long-term industry expansion.
Market Trends:
Expansion of Smart Infrastructure Projects with Integrated Electrochromic Displays:
Urban development increasingly incorporates smart windows and intelligent displays in commercial spaces. Architects integrate electrochromic solutions for energy efficiency and aesthetics. The Global Electrochromic Display Market benefits from large-scale adoption in public and private projects. Demand for sustainable cities creates steady opportunities. Real estate developers leverage electrochromic features as premium add-ons. Corporate buyers seek displays that reduce long-term costs. Integration with automated systems enhances operational control. The trend highlights the link between smart cities and electrochromic technology growth.
- For instance, ChromoGenics AB’s ConverLight dynamic glass product offers controllable solar heat gain and light transmission with visible light transmittance modulation, making it a preferred choice in smart building projects. The Global Electrochromic Display Market benefits from large-scale adoption in public and private projects. Demand for sustainable cities creates steady opportunities. Real estate developers leverage electrochromic features as premium add-ons.
Emergence of Flexible and Lightweight Display Formats in Multiple Industries:
Flexible displays enable new applications across consumer electronics, automotive, and aerospace. Manufacturers design lightweight electrochromic displays for mobility and efficiency. The Global Electrochromic Display Market advances through versatility and adaptability. Foldable and curved formats expand design possibilities. Aerospace and defense use these solutions to reduce weight while maintaining durability. Consumer electronics firms explore new product categories with innovative shapes. The shift promotes cross-industry collaboration in design. Growth is driven by user demand for practical and innovative devices.
- For instance, AGC Inc. developed a light control panoramic roof, featuring their WONDERLITE™ Dx technology, which has been adopted by manufacturers for vehicles like the Lexus RZ and Toyota Harrier. This light control glass instantly switches between opaque and transparent states to manage sunlight and improve cabin comfort, and its shade-less design contributes to weight reduction and enhanced headroom.
Integration of IoT and Connectivity Features with Electrochromic Displays:
Connected systems use electrochromic displays as interactive interfaces. Smart homes and vehicles benefit from displays linked to IoT platforms. The Global Electrochromic Display Market adapts by embedding sensors and connectivity. Displays serve not only as visual tools but also as interactive hubs. Real-time data visibility increases functional value across devices. Automotive systems integrate connected displays for safer driving experiences. Healthcare devices use connected features for remote monitoring. This trend ensures electrochromic displays align with digital ecosystems.
Growing Adoption of Electrochromic Displays in Branding and Retail Environments:
Retailers and advertisers adopt electrochromic displays for dynamic signage. These displays capture attention with flexible visuals and low energy use. The Global Electrochromic Display Market gains from the rise of experiential marketing. Brands deploy displays for real-time promotions and customer engagement. Shopping malls integrate electrochromic signage for interactive experiences. Energy efficiency aligns with sustainability goals in retail operations. Businesses view electrochromic displays as cost-effective branding tools. This trend strengthens commercial adoption in competitive markets.
Market Challenges Analysis:
High Production Costs and Limited Economies of Scale:
The cost of advanced materials and specialized manufacturing processes increases product prices. The Global Electrochromic Display Market faces adoption barriers due to affordability issues in emerging economies. Limited economies of scale prevent significant cost reduction in early stages. SMEs struggle to compete with established vendors with stronger resources. End users hesitate when alternatives offer lower upfront costs. Supply chain complexity raises risks of delays and shortages. Companies invest in R&D but need larger volumes for price reduction. Cost challenges limit rapid penetration across diverse applications.
Performance Limitations and Consumer Perception Hurdles:
Electrochromic displays face challenges related to switching speed and color uniformity. The Global Electrochromic Display Market contends with concerns over durability under extreme conditions. Consumers often compare them with conventional LCD and OLED displays. Lack of awareness about benefits restricts wider acceptance. Commercial buyers demand proof of reliability in high-use environments. Integration into complex systems raises technical compatibility issues. Vendors must invest in education campaigns to build trust. Market growth depends on overcoming performance and perception obstacles.
Market Opportunities:
Emerging Demand in Healthcare, Aerospace, and Defense Applications:
Electrochromic displays offer compact, power-efficient solutions ideal for critical applications. The Global Electrochromic Display Market expands as aerospace integrates lightweight formats and defense adopts stealth-friendly designs. Healthcare systems benefit from diagnostic and monitoring devices with efficient displays. Growth accelerates through specialized R&D collaborations. Companies gain from contracts in these strategic industries. Vendors diversify portfolios to target high-value end markets. The opportunity strengthens long-term positioning. Partnerships ensure tailored innovations meet sector needs.
Rising Focus on Sustainable Smart Cities and Green Buildings:
Urban projects increasingly prioritize energy-efficient display integration. The Global Electrochromic Display Market benefits from sustainable infrastructure initiatives worldwide. Architects and developers integrate smart windows to meet regulatory and consumer expectations. Governments fund projects that emphasize eco-friendly technologies. Vendors find opportunities in public sector contracts. Corporate buyers invest in premium sustainable spaces. Strong alignment with urban sustainability goals secures long-term relevance. The opportunity supports consistent growth in construction-linked applications.
Market Segmentation Analysis:
By Display Type
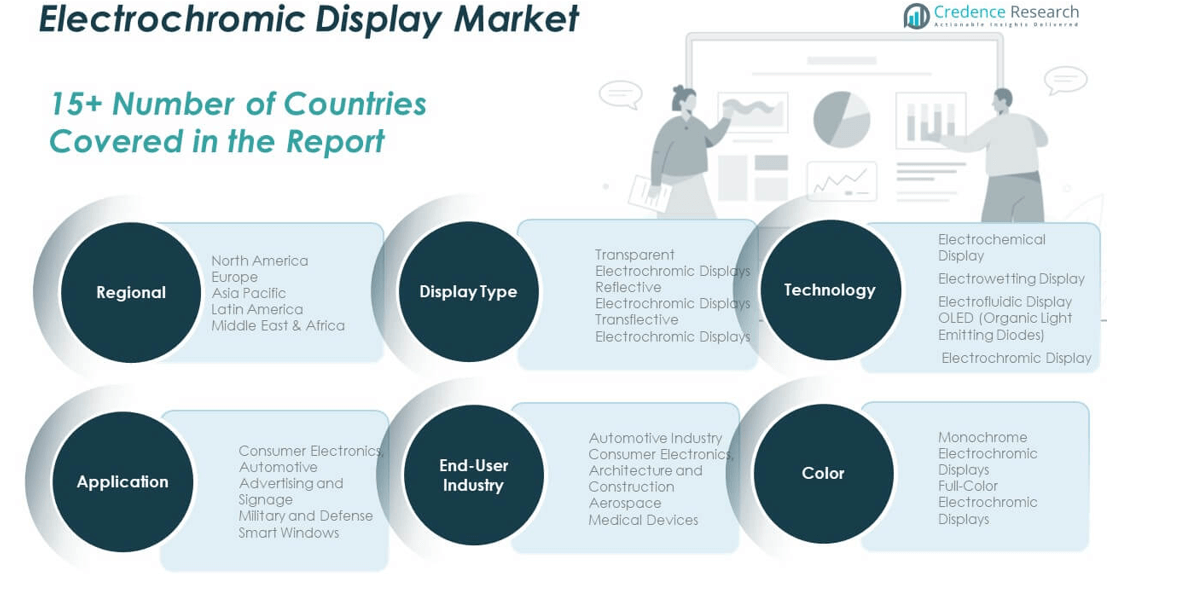
Transparent electrochromic displays lead adoption due to their role in smart windows and premium automotive applications. Reflective displays gain traction in low-power devices, while transflective formats balance outdoor visibility and energy efficiency.
- For instance, Gentex’s digital rearview mirrors utilize transparent electrochromic glass integrated with OLED displays for enhanced driver monitoring and glare reduction. Reflective displays gain traction in low-power devices, while transflective formats balance outdoor visibility and energy efficiency.
By Technology Source
Electrochemical displays dominate early adoption in consumer devices. Electrowetting and electrofluidic technologies expand opportunities in portable and flexible formats. OLED-based electrochromic displays secure strong interest in high-resolution and color-rich applications.
- For instance, companies like Gentex create hybrid digital rearview mirrors that integrate an OLED display with electrochromic (EC) auto-dimming technology. This allows the mirror to function both as a conventional auto-dimming mirror to reduce glare from headlights (using EC technology) and as a high-contrast, fast-responsive digital video display (using OLED technology) for an unobstructed rearward view.
By Color
Monochrome displays maintain share in cost-sensitive and industrial applications. Full-color electrochromic displays capture growth in advertising, automotive, and premium consumer electronics.
By Application
The Global Electrochromic Display Market shows strong penetration in consumer electronics and automotive. Advertising and signage utilize electrochromic properties for dynamic visual appeal. Military and defense prioritize durability and low-energy requirements, while smart windows expand across commercial buildings.
By End-User Industry
Automotive remains the dominant industry, integrating electrochromic displays in mirrors, sunroofs, and infotainment. Consumer electronics follow with wearable devices and e-readers. Architecture and construction leverage electrochromic windows for energy-efficient buildings. Aerospace integrates displays for cockpit and cabin functions, while medical devices adopt them for compact, power-efficient solutions.
Segmentation:
By Display Type
- Transparent Electrochromic Displays
- Reflective Electrochromic Displays
- Transflective Electrochromic Displays
By Technology Source
- Electrochemical Display
- Electrowetting Display
- Electrofluidic Display
- OLED (Organic Light Emitting Diodes) Electrochromic Display
By Color
- Monochrome Electrochromic Displays
- Full-Color Electrochromic Displays
By Application
- Consumer Electronics
- Automotive
- Advertising and Signage
- Military and Defense
- Smart Windows
By End-User Industry
- Automotive Industry
- Consumer Electronics
- Architecture and Construction
- Aerospace
- Medical Devices
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Electrochromic Display Market size was valued at USD 372.60 million in 2018, reaching USD 540.98 million in 2024, and is anticipated to attain USD 1,348.82 million by 2032, at a CAGR of 12.2% during the forecast period. North America accounts for 31.9% of the global market share in 2024. The Global Electrochromic Display Market in this region benefits from strong adoption across automotive and construction sectors. Automakers integrate electrochromic displays in premium models for safety and comfort. The region invests heavily in smart infrastructure, supporting demand for smart windows and energy-efficient displays. Consumer electronics adoption is driven by tech-savvy populations and high disposable income. Defense and aerospace sectors adopt electrochromic technologies for tactical displays and stealth applications. Government incentives for sustainable technologies enhance market penetration. The U.S. remains the leading contributor, supported by strong R&D and innovation ecosystems.
Europe
The Europe Electrochromic Display Market size was valued at USD 332.35 million in 2018, reaching USD 471.88 million in 2024, and is anticipated to attain USD 1,119.09 million by 2032, at a CAGR of 11.5% during the forecast period. Europe holds 27.9% of the global market share in 2024. The Global Electrochromic Display Market in Europe is shaped by strict sustainability regulations and advanced automotive industries. Smart building initiatives accelerate adoption of electrochromic windows across commercial and residential sectors. Germany and France lead in construction-driven applications, while the UK supports growth through consumer electronics and innovation. The luxury automotive segment drives significant demand for electrochromic sunroofs and mirrors. Companies invest in R&D partnerships with universities and research centers. EU directives on energy efficiency strengthen long-term adoption. The market maintains steady growth driven by innovation and environmental priorities.
Asia Pacific
The Asia Pacific Electrochromic Display Market size was valued at USD 292.10 million in 2018, reaching USD 448.31 million in 2024, and is anticipated to attain USD 1,231.31 million by 2032, at a CAGR of 13.6% during the forecast period. Asia Pacific commands 26.5% of the global market share in 2024. The Global Electrochromic Display Market in this region is fueled by rapid industrialization and growing consumer electronics adoption. China dominates production with investments in display technologies and large-scale manufacturing. Japan and South Korea lead innovation in flexible and high-resolution displays. India emerges as a key growth hub through construction projects and smart city initiatives. Regional growth is supported by rising disposable incomes and urbanization. Automotive manufacturers integrate electrochromic features in vehicles targeted at premium buyers. Local players expand aggressively into domestic and international markets. Asia Pacific remains the fastest-growing region due to high demand across applications.
Latin America
The Latin America Electrochromic Display Market size was valued at USD 81.65 million in 2018, reaching USD 119.15 million in 2024, and is anticipated to attain USD 278.43 million by 2032, at a CAGR of 11.3% during the forecast period. Latin America represents 7% of the global market share in 2024. The Global Electrochromic Display Market in this region benefits from rising construction and automotive adoption. Brazil leads regional demand with large-scale urban projects and growing middle-class purchasing power. Mexico contributes through automotive manufacturing and electronics assembly. Advertising and signage applications expand in retail and commercial spaces. Governments promote energy-efficient solutions in construction. Challenges include limited local manufacturing and reliance on imports. Companies explore partnerships to increase distribution networks. Steady economic recovery supports consistent market growth.
Middle East
The Middle East Electrochromic Display Market size was valued at USD 39.10 million in 2018, reaching USD 53.48 million in 2024, and is anticipated to attain USD 118.80 million by 2032, at a CAGR of 10.6% during the forecast period. The region accounts for 3.2% of the global market share in 2024. The Global Electrochromic Display Market here is driven by investment in smart infrastructure and high-end construction. GCC countries lead adoption through luxury real estate projects and advanced transportation initiatives. Governments integrate energy-efficient solutions in new urban developments. Automotive markets show rising interest in electrochromic features for premium vehicles. Israel contributes through R&D and technology innovation. Retail adoption of dynamic signage strengthens visibility in commercial hubs. Regional growth remains steady despite economic volatility. Investment in sustainability ensures long-term relevance of electrochromic technologies.
Africa
The Africa Electrochromic Display Market size was valued at USD 32.20 million in 2018, reaching USD 58.91 million in 2024, and is anticipated to attain USD 130.48 million by 2032, at a CAGR of 10.2% during the forecast period. Africa holds 3.5% of the global market share in 2024. The Global Electrochromic Display Market in Africa is at an early stage but shows promising opportunities. South Africa leads adoption through construction projects and automotive integration. Egypt invests in modernizing infrastructure and smart buildings. Limited local production slows rapid expansion, but imports bridge demand gaps. Urbanization and rising consumer awareness drive gradual adoption. Energy-efficient technologies align with government initiatives for sustainable development. Commercial real estate integrates electrochromic windows for cost savings. Future growth depends on stronger supply chains and increased investment.
Key Player Analysis:
- Gentex Corporation
- Saint-Gobain / SageGlass
- AGC Inc. (Asahi Glass)
- ChromoGenics AB
- EControl-Glas GmbH
- Kinestral Technologies (Halio)
- Ricoh
- Polytronix
- Kent Displays
- Pervasive Displays
Competitive Analysis:
The Global Electrochromic Display Market is moderately consolidated, with a mix of global corporations and specialized technology firms. Leading players such as Gentex Corporation, Saint-Gobain, AGC Inc., and ChromoGenics AB dominate through innovation, partnerships, and geographic expansion. It is characterized by strong investments in R&D, especially in automotive, construction, and consumer electronics applications. Companies focus on enhancing performance, reducing costs, and scaling production to improve competitiveness. Start-ups and niche firms contribute by advancing flexible displays and niche applications, often targeting defense, aerospace, and healthcare. Competitive intensity is defined by patents, strategic alliances, and the pace of technology commercialization. It continues to evolve through collaborations that expand market reach and product portfolios.
Recent Developments:
- In February 2025, Saint-Gobain’s subsidiary SageGlass launched RealTone™, a breakthrough electrochromic glazing solution designed to eliminate the typical bluish tint associated with electrochromic glass. RealTone™ offers architects and builders a more natural neutral aesthetic while maintaining glare control and thermal regulation. It is compatible with various coatings and bird-friendly solutions, enhancing design flexibility for architectural projects.
- In early 2025, Gentex Corporation unveiled its next-generation dimmable glass technology at CES 2025, featuring film-based electrochromic sunroofs and sun visors with integrated displays. These new products demonstrate lower current draw, memory functionality to retain light transmission states without power, and flexibility for large panoramic roofs. Gentex’s innovation also extends to digital rearview mirrors with OLED displays and enhanced driver monitoring systems, signifying a broad adoption in over 29 automaker brands and 124 vehicles globally as of January 2025.
Report Coverage:
The research report offers an in-depth analysis based on display type and technology source. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Stronger adoption of electrochromic displays in premium automotive applications.
- Growing role of smart buildings driving demand for electrochromic windows.
- Expanding use of flexible and lightweight displays in aerospace and defense.
- Rising integration of displays into consumer electronics and wearables.
- Increasing focus on energy-efficient technologies across developed markets.
- Strategic partnerships between display firms and construction companies.
- Rapid innovation in OLED and electrowetting technologies.
- Growth of Asia Pacific as the fastest-emerging regional hub.
- Heightened competition among global and niche technology players.
- Accelerated demand from healthcare and medical device applications.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Energy-Efficient Technologies in Automotive and Construction
Automotive manufacturers and construction firms are integrating electrochromic displays into vehicles and buildings to improve energy efficiency, reduce glare, and enhance occupant comfort. Environmental regulations and consumer demand for sustainable solutions are accelerating this trend.
Integration of Electrochromic Displays in Consumer Electronics and Wearables
The proliferation of portable and connected devices, such as e-readers, smartwatches, and mobile devices, is driving demand for electrochromic displays due to their low power consumption and flexible design capabilities, appealing to tech-savvy consumers.
Technological Advancements Expanding Product Capabilities
Continuous R&D in electrochromic, OLED, and electrowetting technologies is resulting in higher resolution, faster switching speeds, and improved durability, enabling new applications in automotive, aerospace, medical, and consumer electronics sectors.
Government Support and Regulatory Push for Sustainable Technologies
Policies and incentives promoting green building, smart infrastructure, and energy-efficient devices are encouraging the adoption of electrochromic displays, especially in public and commercial projects, further supported by emissions reduction standards and subsidies.
Expansion of Smart Infrastructure and Smart Cities
Large-scale urban development projects are increasingly incorporating electrochromic displays in smart windows and intelligent building systems, creating steady demand as cities and real estate developers prioritize sustainability and operational efficiency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Electrochromic Display Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Electrochromic Display Market projected to grow between 2025 and 2032?
Which Global Electrochromic Display Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Electrochromic Display Market?
Who are the leading companies in the Global Electrochromic Display Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Consumer Electronics
- 1.2.2 Automotive
- 1.2.3 Advertising and Signage
- 1.2.4 Military and Defense
- 1.2.5 Smart Windows
- 1.3 By Display Type
- 1.3.1 Transparent Electrochromic Displays
- 1.3.2 Reflective Electrochromic Displays
- 1.3.3 Transflective Electrochromic Displays
- 1.4 By End-User Industry
- 1.4.1 Automotive Industry
- 1.4.2 Consumer Electronics
- 1.4.3 Architecture and Construction
- 1.4.4 Aerospace
- 1.4.5 Medical Devices
- 1.5 By Technology Source
- 1.5.1 Electrochemical Display
- 1.5.2 Electrowetting Display
- 1.5.3 Electrofluidic Display
- 1.5.4 OLED (Organic Light Emitting Diodes) Electrochromic Display
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,692.71 million → 2032: USD 4,226.92 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electrochromic Display Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electrochromic Display Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electrochromic Display Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electrochromic Display Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electrochromic Display Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electrochromic Display Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electrochromic Display Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electrochromic Display Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,692.71 million → 2032: USD 4,226.92 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electrochromic Display Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumer Electronics
- 12.3.7.2 Automotive
- 12.3.7.3 Advertising and Signage
- 12.3.7.4 Military and Defense
- 12.3.7.5 Smart Windows
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Display Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Transparent Electrochromic Displays
- 12.4.7.2 Reflective Electrochromic Displays
- 12.4.7.3 Transflective Electrochromic Displays
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive Industry
- 12.5.7.2 Consumer Electronics
- 12.5.7.3 Architecture and Construction
- 12.5.7.4 Aerospace
- 12.5.7.5 Medical Devices
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Technology Source - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Electrochemical Display
- 12.6.7.2 Electrowetting Display
- 12.6.7.3 Electrofluidic Display
- 12.6.7.4 OLED (Organic Light Emitting Diodes) Electrochromic Display
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electrochromic Display End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electrochromic Display Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electrochromic Display Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electrochromic Display Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Gentex Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Saint-Gobain / SageGlass
- 18.4 AGC Inc. (Asahi Glass)
- 18.5 ChromoGenics AB
- 18.6 EControl-Glas GmbH
- 18.7 Kinestral Technologies (Halio)
- 18.8 Ricoh
- 18.9 Polytronix
- 18.10 Kent Displays
- 18.11 Pervasive Displays
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

