
Market Overview:
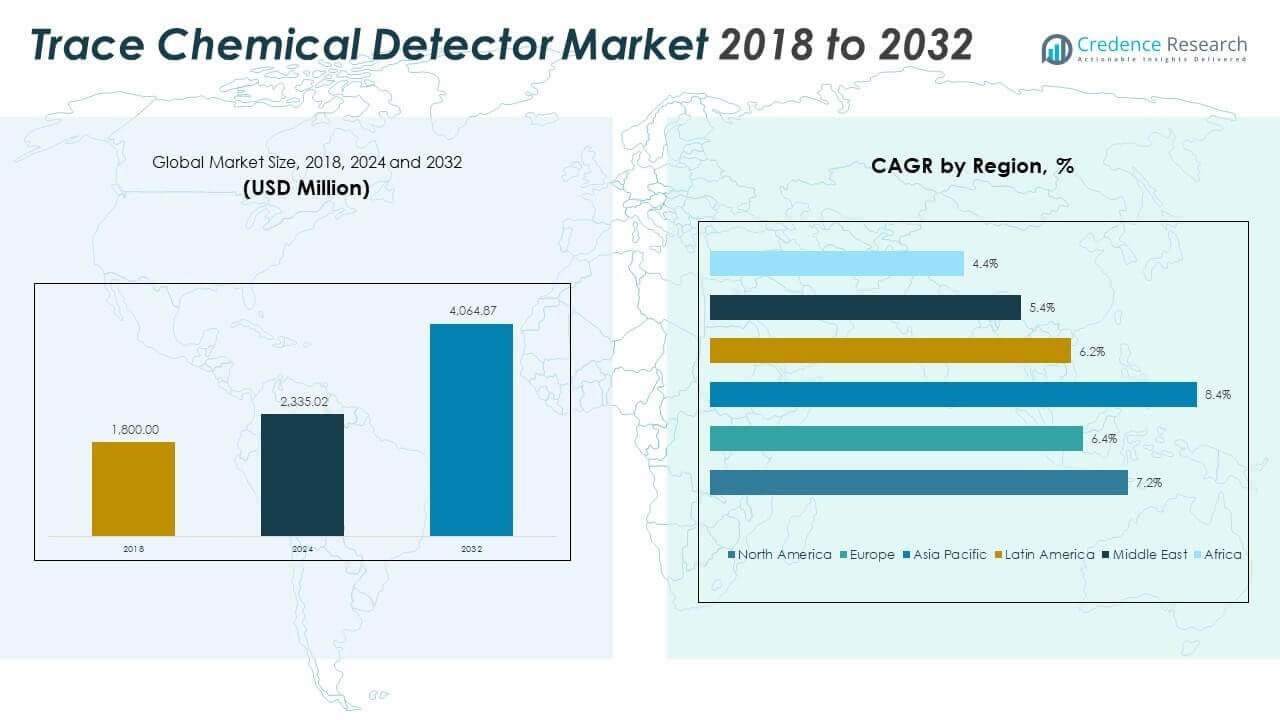
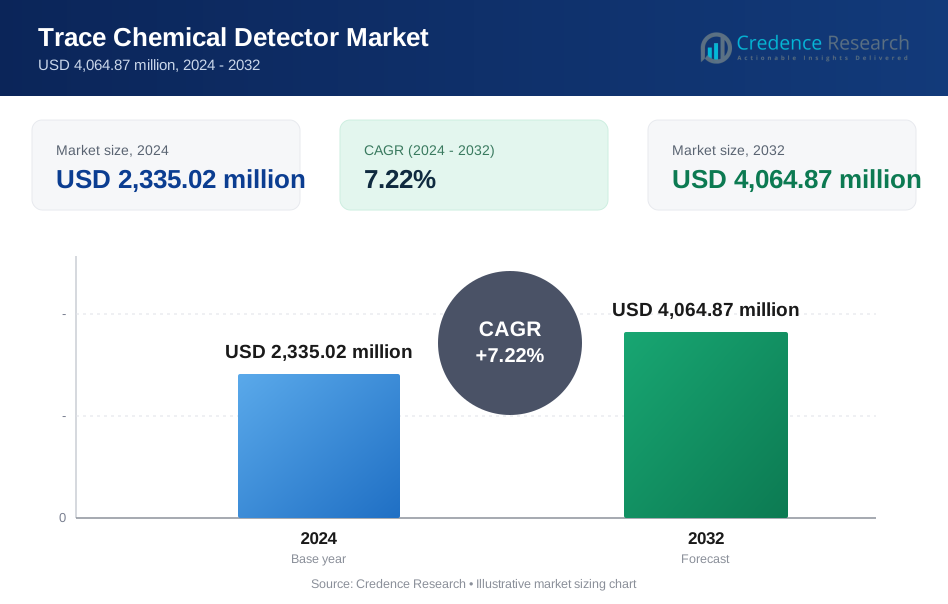
The Global Trace Chemical Detector Market size was valued at USD 1,800.00 million in 2018 to USD 2,335.02 million in 2024 and is anticipated to reach USD 4,064.87 million by 2032, at a CAGR of 7.22% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Trace Chemical Detector Market Size 2024 | USD 2,335.02 million |
| Trace Chemical Detector Market, CAGR | 7.22% |
| Trace Chemical Detector Market Size 2032 | USD 4,064.87 million |
Market growth is driven by rising security threats and strict safety regulations worldwide. Governments invest in advanced detection systems for public safety and border control. Airports and transport hubs deploy trace detectors to prevent chemical attacks. Industrial facilities use detectors to monitor hazardous leaks and worker exposure. Defense agencies adopt portable and fixed systems for field operations. Advances in sensor accuracy and faster response times improve adoption. Growing use in emergency response and forensic applications further supports demand across sectors.
North America leads the market due to strong homeland security spending and early technology adoption. The United States drives demand through defense, aviation, and infrastructure security programs. Europe follows with strict safety norms and wide use across transport and industrial sites. Asia Pacific emerges as a fast-growing region due to rising security needs and urban expansion. China, India, and Japan invest in public safety and industrial monitoring. Middle East adoption grows due to critical infrastructure protection needs.
Market Insights:
- The Global Trace Chemical Detector Market was valued at USD 1,800.00 million in 2018, reached USD 2,335.02 million in 2024, and is projected to hit USD 4,064.87 million by 2032, growing at a CAGR of 7.22% over the forecast period.
- North America led the market with about 36% share in 2024 due to strong defense spending, followed by Asia Pacific with nearly 28% from rapid security upgrades, and Europe with around 24% driven by strict safety regulations.
- Asia Pacific is the fastest-growing region, holding close to 28% share, supported by urbanization, expanding transport networks, and rising public security investments across China and India.
- By end user, Security & Defence accounted for the largest share at roughly 35% in 2024, reflecting sustained demand from border control, military, and homeland security applications.
- Chemical & Pharmaceutical and Oil & Gas together represented nearly 40% share, supported by compliance-driven monitoring, industrial safety needs, and expanding research activities.
Market Drivers:
Rising National Security And Counterterrorism Preparedness Requirements
Governments face persistent chemical threat risks across public spaces. Security agencies expand monitoring at airports and borders. Defense forces deploy detectors for battlefield readiness and troop safety. Law enforcement agencies rely on fast identification of trace substances. The Global Trace Chemical Detector Market benefits from these security mandates. Public event protection increases equipment demand worldwide. Emergency response teams require reliable field detection tools. Policy focus on preparedness sustains long-term procurement plans. Budget allocations support continuous technology upgrades.
- For instance, Smiths Detection reports its IONSCAN systems deliver trace detection within seconds and are deployed at more than 70% of major international airports worldwide.
Expansion Of Industrial Safety And Hazardous Material Monitoring Needs
Industrial plants handle toxic and reactive chemicals daily. Safety rules require early leak detection systems. Chemical, oil, and gas sectors adopt trace detection tools. Worker protection standards push strict exposure monitoring. Manufacturing sites deploy detectors to prevent accidents. Regulators enforce compliance through inspections and audits. Plant operators value early alerts to reduce downtime. Equipment reliability strengthens operational safety confidence.
- For instance, Honeywell notes that its industrial chemical detection systems support continuous monitoring with detection sensitivity at parts-per-billion levels for hazardous gases.
Strict Regulatory Compliance Across Environmental And Occupational Safety
Environmental agencies enforce chemical emission monitoring rules. Occupational safety bodies mandate exposure control measures. Compliance pressure drives adoption across facilities. Inspectors require precise trace detection tools. Penalties for violations raise risk awareness. Industries prioritize certified and approved detection systems. Regulatory audits increase equipment replacement cycles. Compliance focus sustains steady market demand.
Growing Demand From Emergency Response And Disaster Management Agencies
Hazard response teams manage chemical spills and attacks. Rapid identification supports faster containment actions. Portable detectors support field mobility needs. Fire departments integrate detection tools into standard kits. Training programs promote routine detector use. Public safety planning includes chemical risk scenarios. Urban density raises emergency readiness focus. Agency procurement supports consistent market growth.
Market Trends:
Shift Toward Portable And Handheld Detection System Designs
End users prefer lightweight and mobile detectors. Field operations require quick deployment capabilities. Compact designs support single-person operation. Battery efficiency improvements extend usage time. Agencies value portability during rapid response missions. Equipment makers focus on ergonomic product layouts. Transport ease supports adoption across sectors. Mobility demand shapes product development strategies.
- For instance, FLIR Systems states that its handheld chemical detectors weigh under 1.5 kg and provide response times below 60 seconds for field screening.
Integration Of Advanced Sensor Technologies And Digital Interfaces
Manufacturers adopt multi-sensor detection platforms. Digital displays improve result clarity and speed. Software integration enables data logging and reporting. Connectivity supports centralized monitoring systems. Sensor accuracy improves trace-level identification. Users expect faster response and fewer false alerts. Digital upgrades raise operational confidence. Technology convergence defines product roadmaps.
- For instance, Bruker highlights that its mass spectrometry-based trace detectors achieve sub-part-per-billion detection limits with automated digital data capture.
Rising Preference For Multi-Threat Detection Capabilities
Users seek detectors covering varied chemical classes. Single-device solutions reduce equipment complexity. Security teams value broad-spectrum detection ability. Industrial users prefer flexible monitoring tools. Product design focuses on expanded threat libraries. Calibration efficiency improves multi-threat performance. Procurement favors versatile detector platforms. Market offerings reflect this consolidation trend.
Increased Adoption Across Transportation And Logistics Infrastructure
Transport hubs face strict chemical screening rules. Cargo inspection requires fast trace detection. Ports and rail terminals deploy fixed systems. Aviation security integrates detectors into checkpoints. Logistics operators manage hazardous shipment risks. Infrastructure expansion supports detector installations. Screening efficiency becomes a key purchase factor. Transport growth supports sustained adoption.
Market Challenges Analysis:
High Equipment Costs And Maintenance Complexity Constraints
Advanced detectors require high initial investment. Budget limits affect smaller agencies and firms. Maintenance demands skilled technical support teams. Calibration procedures add operational burden. Replacement parts increase ownership costs. Training requirements extend deployment timelines. Procurement delays impact adoption rates. Cost sensitivity remains a key challenge.
Performance Limitations Under Harsh Environmental Conditions
Extreme temperatures affect sensor stability. Humidity impacts detection accuracy in some models. Dust exposure reduces system reliability. Field conditions challenge long-term device performance. Users report occasional false positives. Calibration drift affects consistent readings. Environmental robustness requires further improvement. Performance gaps slow wider deployment.
Market Opportunities:
Growth In Smart Infrastructure And Urban Security Projects
Smart city plans include advanced safety systems. Urban authorities invest in integrated detection networks. Public infrastructure upgrades support detector deployment. Data-driven security planning boosts demand. City surveillance systems adopt chemical detection layers. Urbanization increases risk management needs. Integrated platforms create new revenue channels. Smart projects expand long-term opportunities.
Rising Adoption In Emerging Economies And Civil Defense Programs
Developing regions strengthen civil defense systems. Governments invest in disaster preparedness capabilities. Industrial expansion raises chemical safety needs. Border security upgrades increase detector procurement. Training initiatives promote technology awareness. Local manufacturing partnerships reduce entry barriers. Regional programs support steady market expansion. Emerging economies present strong growth potential.
Market Segmentation Analysis:
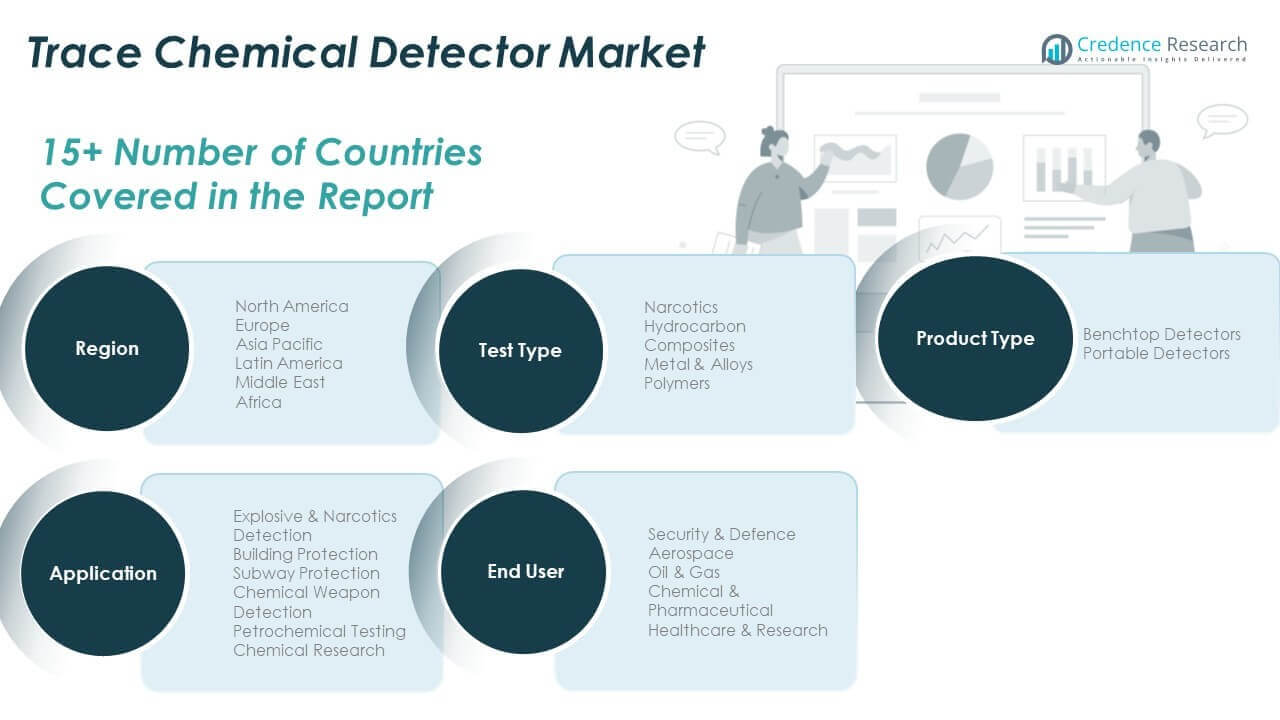
By Test Type
Narcotics detection supports border control and law enforcement operations. Hydrocarbon detection serves energy, transport, and industrial safety needs. Composites testing supports advanced materials verification in manufacturing. Metal and alloys analysis aids quality control and security screening. Polymers testing supports chemical safety and research accuracy. These test types reflect diverse threat profiles and material risks. Demand favors fast identification with high sensitivity. Portfolio breadth supports wider adoption across sectors.
- For instance, Thermo Fisher Scientific confirms its trace analyzers can identify narcotics residues at nanogram-level sensitivity across varied material surfaces.
By Application
Explosive and narcotics detection anchors security use cases. Building protection focuses on public safety and access control. Subway protection addresses dense transit risk profiles. Chemical weapon detection supports military and civil defense readiness. Petrochemical testing ensures process safety and compliance. Chemical research requires precise trace analysis for experiments. Use cases demand speed, accuracy, and reliability. Application diversity stabilizes demand cycles.
- For instance, NUCTECH reports deployment of its trace chemical detection systems across metro and rail networks in more than 30 countries for transit security screening.
By Product Type
Benchtop detectors support labs and fixed checkpoints. These systems offer high precision and repeatability. Portable detectors support field and rapid response missions. Mobility enables screening across varied locations. Users value rugged design and quick setup. Product choice aligns with operating context. The mix supports flexible deployments. Procurement favors proven performance.
By End-User
Security and defence lead adoption due to threat exposure. Aerospace uses detectors for cargo and facility screening. Oil and gas relies on leak and hazard detection. Chemical and pharmaceutical sectors require compliance monitoring. Healthcare and research depend on accurate trace analysis. Each end-user values reliability and speed. The Global Trace Chemical Detector Market benefits from this breadth. End-user needs guide feature priorities.
Segmentation:
- By Test Type
- Narcotics
- Hydrocarbon
- Composites
- Metal & Alloys
- Polymers
- By Application
- Explosive & Narcotics Detection
- Building Protection
- Subway Protection
- Chemical Weapon Detection
- Petrochemical Testing
- Chemical Research
- By Product Type
- Benchtop Detectors
- Portable Detectors
- By End-User
- Security & Defence
- Aerospace
- Oil & Gas
- Chemical & Pharmaceutical
- Healthcare & Research
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Regional Analysis: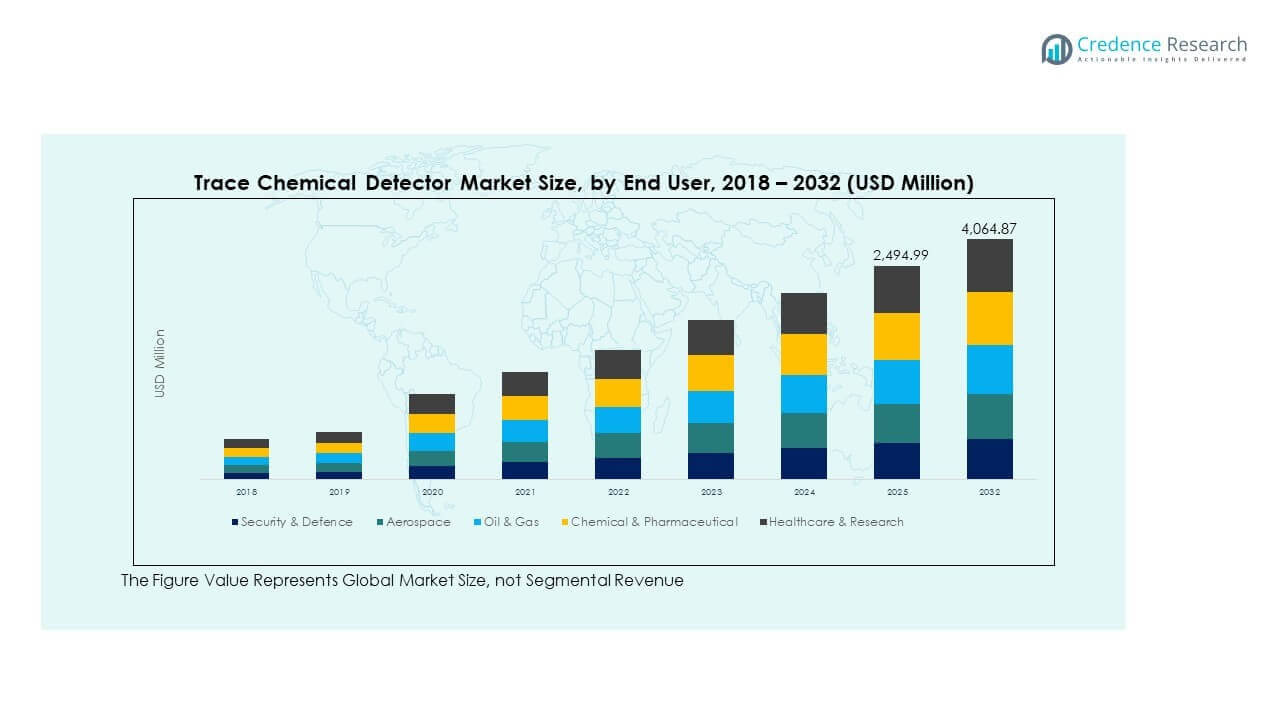
North America
The North America Global Trace Chemical Detector Market size was valued at USD 657.72 million in 2018 to USD 842.93 million in 2024 and is anticipated to reach USD 1,465.39 million by 2032, at a CAGR of 7.2 during the forecast period. North America holds about 36% market share in 2024. The United States drives demand through homeland security and defense programs. Airports deploy trace detectors for passenger and cargo screening. Industrial safety rules support adoption across energy and chemicals. Law enforcement agencies rely on rapid identification tools. Research institutions use advanced benchtop systems. Technology maturity supports early adoption. Stable budgets sustain replacement demand.
Europe
The Europe Global Trace Chemical Detector Market size was valued at USD 455.40 million in 2018 to USD 566.88 million in 2024 and is anticipated to reach USD 929.85 million by 2032, at a CAGR of 6.4 during the forecast period. Europe accounts for nearly 24% market share in 2024. Strong safety regulations support steady adoption. Transport hubs deploy detectors for public protection. Industrial compliance drives demand across manufacturing sites. Defense agencies maintain chemical threat readiness. Research laboratories support analytical system use. Focus on worker safety strengthens procurement. Market growth remains stable across countries.
Asia Pacific
The Asia Pacific Global Trace Chemical Detector Market size was valued at USD 489.60 million in 2018 to USD 660.45 million in 2024 and is anticipated to reach USD 1,257.27 million by 2032, at a CAGR of 8.4 during the forecast period. Asia Pacific holds about 28% market share in 2024. China and India lead through security upgrades. Urban transport expansion raises screening needs. Industrial growth increases chemical monitoring demand. Governments invest in public safety systems. Manufacturing hubs adopt portable detectors. Research spending supports advanced applications. Growth momentum remains strong.
Latin America
The Latin America Global Trace Chemical Detector Market size was valued at USD 113.40 million in 2018 to USD 145.68 million in 2024 and is anticipated to reach USD 235.23 million by 2032, at a CAGR of 6.2 during the forecast period. Latin America represents nearly 6% market share in 2024. Border security programs support detector use. Oil and gas activities drive industrial adoption. Airports increase screening investments. Public safety initiatives gain focus. Technology adoption remains selective. Budget limits affect large deployments. Growth stays moderate.
Middle East
The Middle East Global Trace Chemical Detector Market size was valued at USD 52.02 million in 2018 to USD 61.86 million in 2024 and is anticipated to reach USD 93.51 million by 2032, at a CAGR of 5.4 during the forecast period. The Middle East holds about 3% market share in 2024. Critical infrastructure protection drives demand. Defense and border security remain priorities. Oil and gas facilities adopt detection tools. Urban security projects support installations. Research use stays limited. Imports dominate supply chains. Growth remains gradual.
Africa
The Africa Global Trace Chemical Detector Market size was valued at USD 31.86 million in 2018 to USD 57.22 million in 2024 and is anticipated to reach USD 83.61 million by 2032, at a CAGR of 4.4 during the forecast period. Africa accounts for nearly 2% market share in 2024. Adoption focuses on security and mining sites. Border control upgrades support demand. Industrial safety awareness grows slowly. Budget limits restrict advanced systems. Training gaps affect usage rates. Government programs drive key purchases. Market expansion remains early stage.
Key Player Analysis:
- ABB
- Siemens
- Hitachi High-Tech Analytical Science
- Ametek (Ortec)
- Thermo Fisher Scientific
- Bruker
- FLIR Systems (Teledyne Technologies)
- Horiba
- JFE Techno-Research Corporation
- NSL Analytical Services
- Westminster International Ltd
- NUCTECH Company Limited
- Morphix Technologies
Competitive Analysis:
The Global Trace Chemical Detector Market shows moderate consolidation with strong technology focus. Leading players compete through sensor accuracy, response speed, and system reliability. Companies invest in portable and benchtop product lines to serve varied use cases. Security and defense contracts drive long-term revenue stability. Industrial and research applications support diversified demand. Firms emphasize certifications and regulatory compliance. Strategic partnerships strengthen regional reach. Product differentiation relies on detection range and false alarm control. Competitive intensity remains steady across regions.
Recent Developments:
- Thermo Fisher Scientific announced a transformative acquisition in October 2025, entering an $8.875 billion definitive agreement to acquire Clario Holdings, enabling enhanced clinical research capabilities and digital transformation. Clario's platform provides critical insights from patient data, improving decision-making and accelerating drug development innovation. The acquisition broadens Thermo Fisher's digital and data capabilities while strengthening AI integration for clinical research, data-driven insights, and operational efficiency. The transaction is expected to deliver approximately $175 million in adjusted operating income synergies by year five, with Clario becoming part of Thermo Fisher's laboratory products and biopharma services segment.
- In October 2025, SoftBank Group Corp. announced a definitive agreement to acquire ABB's robotics business for USD 5.375 billion, representing a significant strategic move to strengthen the Swedish conglomerate's position in AI-driven automation. The acquisition demonstrates ABB's strategic pivot toward separating specialized businesses while positioning robotics as a critical component of next-generation manufacturing. Expected to close in mid-to-late 2026, this transaction reflects broader industry consolidation around artificial intelligence and advanced robotics capabilities.
- Additionally, in December 2025, ABB strengthened its grid automation portfolio by signing an agreement to acquire Netcontrol, a provider of electrical grid automation solutions for power utilities and critical infrastructure operators. This acquisition, expected to close in Q1 2026, enhances ABB's distribution solutions offerings and expands its presence across Europe, Asia, and the Middle East. Simultaneously, ABB extended its 18-year partnership with Tata Consultancy Services to modernize its global hosting operations and implement AI-driven IT transformations, underscoring ABB's commitment to digital infrastructure advancement.
- in September 2025, Siemens signed a new Memorandum of Understanding with Merck KGaA, Darmstadt, Germany, to accelerate digital transformation in the life sciences industry. This collaboration marks the first joint deployment of technology acquired through Siemens' Dotmatics acquisition (completed July 2025) and focuses on delivering end-to-end digital workflows from drug discovery through manufacturing. The partnership integrates Merck's software-as-a-service products with Siemens' digital ecosystem, including Luma, the Dotmatics Scientific Intelligence Platform.
Report Coverage:
The research report offers an in-depth analysis based on test type, application, product type, and end-user segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Security modernization programs will sustain detector demand.
- Portable detector adoption will rise across field operations.
- Sensor accuracy improvements will strengthen user confidence.
- Multi-threat detection capability will gain preference.
- Public transport security will expand system deployments.
- Industrial safety compliance will support steady uptake.
- Emerging economies will increase procurement volumes.
- Research applications will adopt advanced benchtop systems.
- Partnerships will enhance regional distribution networks.
- Product innovation will remain a core growth lever.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising National Security and Counterterrorism Preparedness
Governments and security agencies are investing in advanced trace chemical detectors to address persistent chemical threat risks in public spaces, border control, and defense operations, driving sustained market demand.
Expansion of Industrial Safety and Hazardous Material Monitoring
Industrial sectors such as chemical, oil, and gas are increasingly adopting trace chemical detectors to comply with safety regulations, monitor hazardous leaks, and protect workers, fueling market growth.
Strict Regulatory Compliance for Environmental and Occupational Safety
Stringent environmental and occupational safety regulations require precise trace detection tools for emission monitoring and exposure control, prompting industries to invest in certified and approved detection systems.
Growth in Emergency Response and Disaster Management
Emergency response teams, fire departments, and disaster management agencies are integrating portable trace chemical detectors into their operations to enable rapid identification and containment of chemical hazards, supporting broader adoption.
Technological Advancements in Sensor Accuracy and Portability
Continuous improvements in sensor sensitivity, response times, and the development of portable, user-friendly devices are enhancing operational efficiency and expanding the use of trace chemical detectors across diverse applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Trace Chemical Detector Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Trace Chemical Detector Market projected to grow between 2025 and 2032?
Which Global Trace Chemical Detector Market market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Trace Chemical Detector Market?
Who are the leading companies in the Global Trace Chemical Detector Market?
Which region commanded the largest share of the Global Trace Chemical Detector Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Security & Defence
- 1.2.2 Aerospace
- 1.2.3 Oil & Gas
- 1.2.4 Chemical & Pharmaceutical
- 1.2.5 Healthcare & Research
- 1.3 By Test Type
- 1.3.1 Narcotics
- 1.3.2 Hydrocarbon
- 1.3.3 Composites
- 1.3.4 Metal & Alloys
- 1.3.5 Polymers
- 1.4 By Application
- 1.4.1 Explosive & Narcotics Detection
- 1.4.2 Building Protection
- 1.4.3 Subway Protection
- 1.4.4 Chemical Weapon Detection
- 1.4.5 Petrochemical Testing
- 1.4.6 Chemical Research
- 1.5 By Product Type
- 1.5.1 Benchtop Detectors
- 1.5.2 Portable Detectors
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,335.02 million → 2032: USD 4,064.87 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Trace Chemical Detector Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Trace Chemical Detector Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Trace Chemical Detector Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Trace Chemical Detector Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Trace Chemical Detector Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Trace Chemical Detector Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Trace Chemical Detector Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Trace Chemical Detector Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,335.02 million → 2032: USD 4,064.87 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Trace Chemical Detector Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Security & Defence
- 12.3.7.2 Aerospace
- 12.3.7.3 Oil & Gas
- 12.3.7.4 Chemical & Pharmaceutical
- 12.3.7.5 Healthcare & Research
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Test Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Narcotics
- 12.4.7.2 Hydrocarbon
- 12.4.7.3 Composites
- 12.4.7.4 Metal & Alloys
- 12.4.7.5 Polymers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Explosive & Narcotics Detection
- 12.5.7.2 Building Protection
- 12.5.7.3 Subway Protection
- 12.5.7.4 Chemical Weapon Detection
- 12.5.7.5 Petrochemical Testing
- 12.5.7.6 Chemical Research
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Benchtop Detectors
- 12.6.7.2 Portable Detectors
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Trace Chemical Detector End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Trace Chemical Detector Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Trace Chemical Detector Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Trace Chemical Detector Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Siemens
- 18.4 Hitachi High-Tech Analytical Science
- 18.5 Ametek (Ortec)
- 18.6 Thermo Fisher Scientific
- 18.7 Bruker
- 18.8 FLIR Systems (Teledyne Technologies)
- 18.9 Horiba
- 18.10 NUCTECH Company Limited
- 18.11 Morphix Technologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

