
Market Overview:
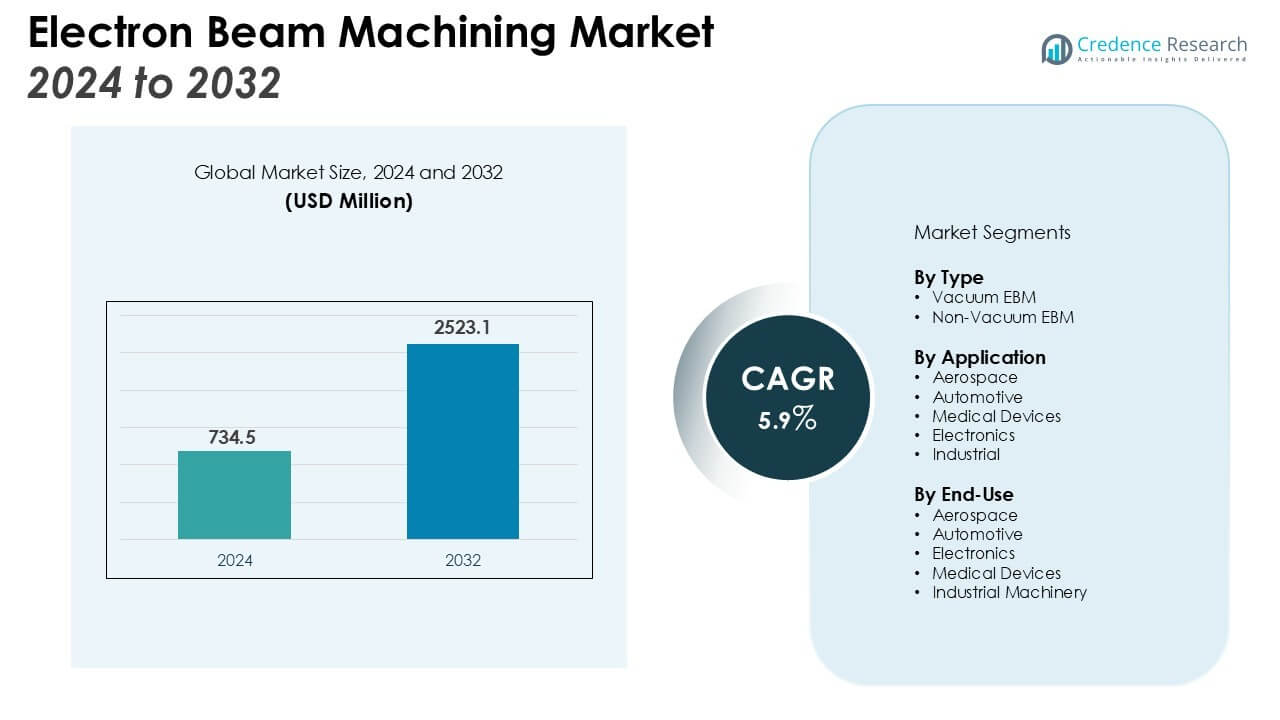
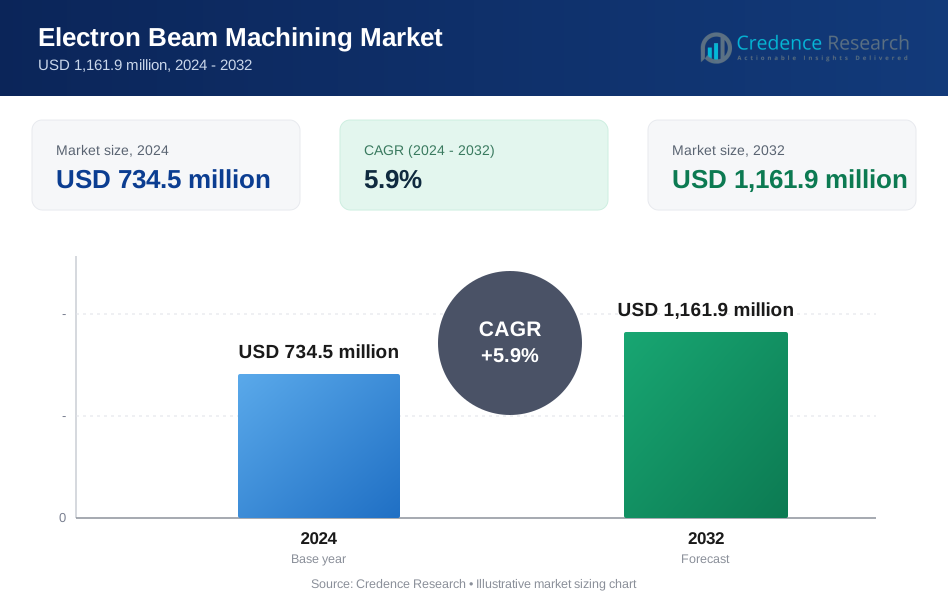
The Electron Beam Machining Market size was valued at USD 734.5 million in 2024 and is anticipated to reach USD 1161.9 million by 2032, at a CAGR of 5.9% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electron Beam Machining Market Size 2024 | USD 734.5 Million |
| Electron Beam Machining Market, CAGR | 5.9% |
| Electron Beam Machining Market Size 2032 | USD 1161.9 Million |
Key drivers for market growth include the increasing demand for precision engineering in industries such as aerospace, automotive, and medical devices. The rising complexity of manufacturing processes, alongside the push for cost-effective and efficient production methods, is fueling the adoption of EBM. Additionally, the growing trend of miniaturization in electronics and the need for fine-tuned components drive further demand for EBM technology. The technology’s ability to achieve highly accurate, intricate designs also adds to its appeal across diverse industries.
Regionally, North America and Europe dominate the EBM market, driven by the presence of key players, advanced manufacturing infrastructure, and high demand in aerospace and automotive sectors. However, the Asia-Pacific region is expected to experience the highest growth due to rapid industrialization, increasing investments in precision machining, and growing adoption in emerging economies such as China and India. These regions are expanding their manufacturing capabilities, further boosting the demand for advanced machining technologies like EBM. Additionally, ongoing technological advancements in EBM equipment are enhancing the efficiency and versatility of the technology, leading to wider market penetration.
Market Insights:
- The Electron Beam Machining Market size was valued at USD 734.5 million in 2024 and is anticipated to reach USD 1,161.9 million by 2032, at a CAGR of 5.9%.
- Increased demand for precision engineering in aerospace, automotive, and medical sectors drives EBM adoption for highly accurate and complex components.
- Technological advancements in electron beam generators and focusing systems are enhancing EBM’s performance, reducing costs, and expanding its applicability.
- The need for cost-effective production methods boosts EBM adoption by reducing material waste, tool wear, and setup time.
- The miniaturization of electronics fuels demand for high-precision components, with EBM offering accuracy for semiconductors, sensors, and microprocessors.
- North America holds 35% of the market share, driven by aerospace, automotive, and medical industries requiring precision components.
- Asia-Pacific holds 25% market share and is expected to see the highest growth due to industrialization and increasing adoption in emerging economies.
Market Drivers:
Rising Demand for Precision Engineering in Key Industries
The Electron Beam Machining (EBM) market is driven by the growing demand for precision engineering in sectors such as aerospace, automotive, and medical devices. These industries require highly accurate and intricate components, which EBM is well-suited to produce. Its ability to machine hard-to-process materials with minimal thermal distortion supports its increasing use in manufacturing components with tight tolerances and complex geometries. This demand for precision in critical applications is propelling the adoption of EBM technology.
- For instance, Electron Beam Engineering, Inc. uses EBM to weld Inconel 718 link assemblies for GE and Pratt & Whitney aircraft engines, a process that eliminates the 2 additional welding operations required by conventional TIG welding.
Technological Advancements Fueling Adoption
Ongoing advancements in EBM technology contribute significantly to market growth. Improvements in electron beam generators, focusing systems, and control software are enhancing the overall performance and precision of EBM systems. These innovations make the technology more efficient, reduce production costs, and expand its applicability across diverse sectors. Enhanced capabilities in high-power and high-speed operations are further driving the adoption of EBM for both prototyping and large-scale production runs.
Need for Cost-Effective and Efficient Production Methods
The pressure to reduce production costs while maintaining high quality is a major factor boosting the demand for EBM in manufacturing. The technology’s ability to machine materials with minimal waste and high precision aligns with the industry's focus on optimizing production processes. EBM helps companies achieve cost savings by reducing material loss, tool wear, and setup time, thereby increasing overall efficiency. These advantages make it a preferred choice for industries aiming to enhance their competitiveness.
Miniaturization of Electronic Components
The trend towards miniaturization in the electronics industry is driving the need for advanced machining technologies like EBM. As devices become smaller and more complex, the demand for high-precision components grows. EBM offers the ability to create fine, detailed features with extreme accuracy, which is essential for producing miniature parts used in electronics, such as semiconductors, sensors, and microprocessors. The technology’s ability to handle delicate and small-scale components supports its increased use in this rapidly evolving sector.
- For instance, a fabrication process for standing ceramic circuit boards demonstrated the technology's precision by creating circuits with a minimum line width of 7 micrometers (µm).
Market Trends:
Increasing Adoption in Aerospace and Automotive Sectors
The Electron Beam Machining (EBM) market is seeing significant growth in the aerospace and automotive industries due to the need for high-precision parts. In aerospace, it is used to create intricate components for engines, turbines, and airframes, where precision and material strength are paramount. The automotive sector is increasingly relying on EBM for manufacturing lightweight, high-strength parts used in electric vehicles (EVs) and advanced powertrains. Both sectors are embracing EBM for its ability to process tough materials like titanium and high-strength steel, essential for meeting the stringent performance and safety requirements of these industries. EBM technology’s efficiency in producing complex geometries further drives its adoption across these sectors, where accuracy and reliability are critical.
- For instance, aerospace leader Boeing utilizes advanced additive manufacturing technologies, including EBM, to create parts for its aircraft, the company has successfully produced over 20,000 flight-qualified components with these methods, showcasing the technology's reliability in demanding aerospace applications.
Rising Focus on Sustainability and Eco-Friendly Manufacturing
There is a growing trend in the Electron Beam Machining market towards sustainability and eco-friendly manufacturing practices. EBM’s ability to minimize material waste during production aligns with the increasing demand for environmentally responsible processes. The precision of the technology ensures that only the necessary material is used, contributing to resource efficiency. This trend is particularly relevant in industries like electronics, where the need for sustainable manufacturing is becoming more pronounced due to environmental regulations and consumer preferences for eco-friendly products. Furthermore, the reduction in tool wear and the longer lifespan of EBM systems contribute to its appeal as a more sustainable option compared to traditional machining technologies. This focus on sustainability is expected to drive the further adoption of EBM in diverse industries.
- For instance, GE Aviation demonstrates the sustainable impact of additive manufacturing by redesigning its LEAP engine fuel nozzles, this innovative approach consolidated 20 different components into a single printed part, substantially reducing material waste and simplifying the manufacturing process.
Market Challenges Analysis:
High Initial Investment and Maintenance Costs
One of the primary challenges facing the Electron Beam Machining (EBM) market is the high initial investment and maintenance costs associated with the technology. The sophisticated equipment required for EBM systems, including electron beam generators and vacuum chambers, comes with a significant price tag. This high upfront cost can be a barrier for small and medium-sized enterprises (SMEs) that are reluctant to invest in expensive machinery. Furthermore, the maintenance of these systems requires specialized expertise and can lead to increased operational costs over time. This financial burden may hinder widespread adoption, particularly in cost-sensitive industries.
Limited Material Compatibility and Processing Speed
EBM faces challenges related to material compatibility and processing speed. While it excels at machining high-strength and difficult-to-process materials, it is less effective on softer materials or those that do not require extreme precision. The slower processing speed compared to other machining technologies also limits its scalability for mass production. Industries requiring rapid production cycles may find EBM less suitable for high-volume manufacturing, impacting its broader adoption across sectors that prioritize speed and cost-efficiency. These limitations restrict its market penetration in certain manufacturing environments.
Market Opportunities:
Expanding Applications in Emerging Industries
The Electron Beam Machining (EBM) market presents significant opportunities in emerging industries such as renewable energy and additive manufacturing. EBM’s ability to precisely machine complex geometries makes it ideal for producing components used in wind turbines, solar power systems, and fuel cells. As these industries continue to grow, driven by the shift towards sustainable energy, the demand for high-precision parts will increase, providing an opportunity for EBM to play a critical role. Furthermore, its integration into additive manufacturing processes for the production of custom parts in industries like aerospace and medical devices offers a promising growth avenue, particularly in sectors where personalization and precision are key.
Advancements in Technology Driving Market Growth
Ongoing advancements in EBM technology offer new opportunities for market growth. The development of faster and more energy-efficient electron beam generators could enhance processing speed and cost-effectiveness, broadening its appeal in high-volume production settings. Furthermore, improvements in automation and real-time monitoring systems can optimize EBM’s performance, reducing operator intervention and minimizing downtime. These technological improvements will make EBM more accessible and practical for a wider range of industries, expanding its market presence and increasing adoption across diverse sectors.
Market Segmentation Analysis:
By Type
The Electron Beam Machining (EBM) market is primarily divided into Vacuum EBM and Non-Vacuum EBM. Vacuum EBM holds a larger share due to its ability to provide high precision and clean machining, making it ideal for intricate parts in industries like aerospace and automotive. Non-vacuum EBM, while offering lower precision, is gaining traction for less complex applications that require quicker production at a lower cost.
- For instance, a notable technological achievement in non-vacuum EBM is its demonstrated ability to cut and weld S1100QL grade high-strength steel plates within a single machine setup, showcasing its high productivity.
By Application
EBM finds its primary use in Aerospace, Automotive, and Medical Devices. Aerospace remains the largest application, driven by the need for high-precision, lightweight, and durable components. The automotive sector is increasingly adopting EBM for the production of components for electric vehicles (EVs) and advanced powertrains. The medical device industry also benefits from EBM's precision, particularly for producing surgical tools and implants.
By End-Use
Key end-users driving EBM adoption include Aerospace, Automotive, Electronics, and Medical Devices. The aerospace sector leads, demanding high-precision, high-strength parts for aircraft engines and components. The automotive industry follows closely, driven by the shift towards electric vehicles and advanced manufacturing techniques. Electronics and medical device sectors are also significant contributors, leveraging EBM for the production of small, complex components.
- For instance, EBM technology demonstrates significant efficiency in the medical device sector by enabling the printing of over 100 acetabular cups in a single production run, which substantially reduces the cost per part.
Segmentations:
By Type
- Vacuum EBM
- Non-Vacuum EBM
By Application
- Aerospace
- Automotive
- Medical Devices
- Electronics
- Industrial
By End-Use
- Aerospace
- Automotive
- Electronics
- Medical Devices
- Industrial Machinery
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America: Leading in Aerospace and Automotive Sectors
North America holds a significant market share of 35% in the Electron Beam Machining (EBM) market, driven by the strong presence of key industries such as aerospace, automotive, and medical devices. The region's advanced manufacturing infrastructure and high demand for precision components make it a leader in EBM adoption. The aerospace sector, in particular, relies on EBM for producing intricate parts with tight tolerances, further boosting its use in the region. High investments in research and development (R&D) and technological advancements in EBM systems support continued growth, while stringent regulations for quality and safety standards reinforce the demand for this precision machining technology.
Europe: Innovation and Sustainable Manufacturing Practices
Europe accounts for a market share of 30% in the EBM market, with countries like Germany, France, and the UK being at the forefront of adopting this technology. The automotive and aerospace industries in Europe demand high-precision, energy-efficient parts, driving the market for EBM. The region’s emphasis on sustainability and eco-friendly manufacturing methods aligns with the material efficiency and waste reduction benefits of EBM, making it a preferred choice for many manufacturers. Europe’s focus on green technologies and innovations in materials science continues to present new opportunities for the expansion of EBM applications across various industries.
Asia-Pacific: Rapid Growth and Industrialization
The Asia-Pacific region holds a market share of 25% in the Electron Beam Machining market and is expected to experience the highest growth, fueled by rapid industrialization and significant investments in precision machining. Countries like China, Japan, and India are increasingly adopting EBM due to its ability to produce highly accurate components for industries such as electronics, automotive, and medical devices. The region’s expanding manufacturing capabilities, coupled with rising demand for high-performance parts, offer substantial opportunities for EBM technology. Additionally, the growing focus on infrastructure development and industrial modernization in emerging markets contributes to the increasing adoption of advanced machining technologies like EBM.
Key Player Analysis:
- Carl Zeiss AG
- GE Additive
- Pioneer Machinery
- Mitsubishi Electric Corporation
- TRUMPF GmbH
- MHI
- Precision Plasma
- KUKA AG
- Oxford Lasers
- Linde plc
Competitive Analysis:
The Electron Beam Machining (EBM) market is highly competitive, with several key players shaping its landscape. Prominent companies such as Mitsubishi Electric Corporation, Pro-Beam GmbH & Co. KGaA, Sciaky, Inc., and Bodycote PLC dominate the market by offering advanced EBM technologies tailored for aerospace, automotive, and medical device industries. These players focus on technological advancements, precision, and high-performance systems to meet the growing demand for intricate, high-precision components. Their investments in research and development (R&D) and strategic collaborations allow them to enhance product offerings and expand their market reach. Smaller firms also emerge with specialized EBM systems, competing on cost-effectiveness and niche applications. Competition remains intense as companies strive to innovate, reduce costs, and improve the efficiency of their EBM systems. The ongoing demand for highly accurate, energy-efficient, and cost-effective machining solutions will drive further advancements in the market.
Recent Developments:
- In June 2025, Carl Zeiss Vision International GmbH announced its agreement to acquire Brighten Optix, a company specializing in contact lenses and orthokeratology for managing myopia.
- In May 2025, it was announced that Mitsubishi Motors will launch a new battery electric vehicle in North America based on the next-generation Nissan LEAF, and in exchange, will supply a plug-in hybrid vehicle to Nissan for the same market.
- In July 2025, Linde plc announced major investments to supply the U.S. commercial space sector, including expanding its Mims, Florida facility and constructing a new air separation unit in Brownsville, Texas, to support rocket launch operations.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for precision machining will continue to drive growth in the Electron Beam Machining (EBM) market, particularly in aerospace, automotive, and medical device industries.
- Advancements in EBM technology, such as improved electron beam generators and faster processing speeds, will increase its adoption across more industries.
- Increased demand for high-performance materials and complex geometries will open new applications for EBM, especially in emerging sectors like renewable energy.
- The miniaturization trend in electronics will spur further adoption of EBM for the production of smaller, highly precise components.
- Investment in research and development (R&D) will result in more cost-effective EBM solutions, making the technology more accessible to small and medium-sized enterprises (SMEs).
- The rise of automation and AI-driven systems will enhance the efficiency and precision of EBM, reducing operational costs and improving productivity.
- Growing concerns over environmental impact will boost the demand for sustainable manufacturing technologies like EBM, known for its minimal material waste.
- Regional markets, particularly in Asia-Pacific, will experience rapid growth due to increased industrialization and investments in high-precision manufacturing.
- Partnerships and collaborations between key players and emerging startups will drive innovation and expand the application base of EBM technology.
- Continued advancements in aerospace, automotive, and electronics sectors will further solidify EBM’s role in producing highly intricate and high-performance components.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Electron Beam Machining, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electron Beam Machining market projected to grow between 2024 and 2032?
Which Electron Beam Machining market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electron Beam Machining market?
Who are the leading companies in the Electron Beam Machining market?
Which region commanded the largest share of the Electron Beam Machining market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Electron Beam Machining Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Electron Beam Machining Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 734.5 million → 2032: USD 1,161.9 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Electron Beam Machining Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Electron Beam Machining Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Electron Beam Machining Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Electron Beam Machining Market Drivers
- 3.3 Electron Beam Machining Market Restraints & Challenges
- 3.4 Electron Beam Machining Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Electron Beam Machining Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Electron Beam Machining Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Electron Beam Machining category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Electron Beam Machining Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Electron Beam Machining Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Electron Beam Machining market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Electron Beam Machining Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Electron Beam Machining Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Electron Beam Machining Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Electron Beam Machining (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Electron Beam Machining Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Electron Beam Machining Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Electron Beam Machining Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Electron Beam Machining Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Electron Beam Machining Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Electron Beam Machining Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Electron Beam Machining Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Electron Beam Machining Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Electron Beam Machining Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
