
Market Overview:
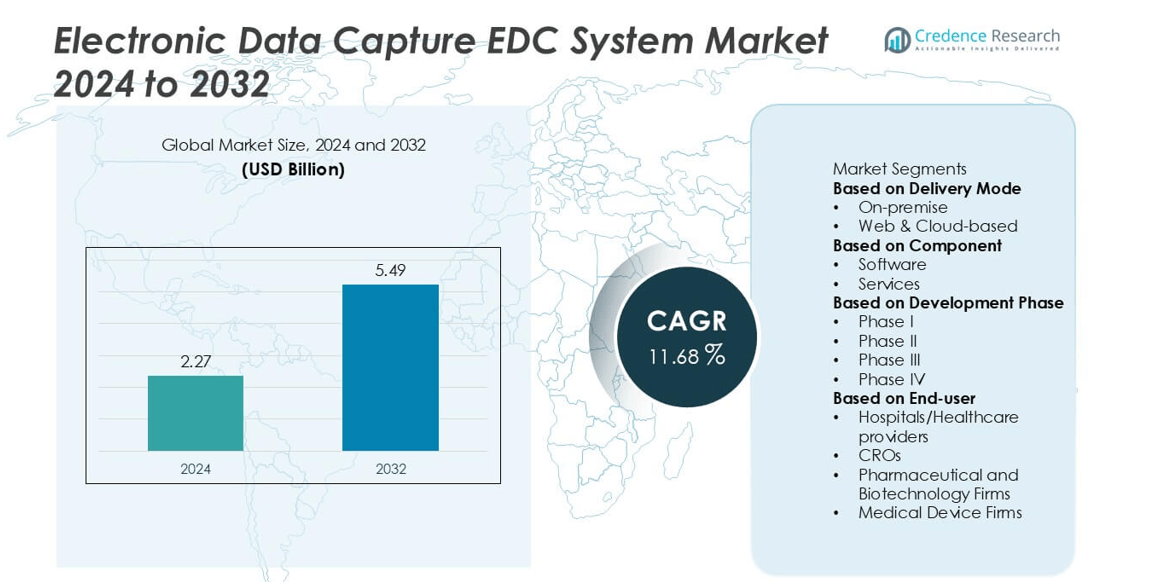
The Electronic Data Capture (EDC) System market was valued at USD 2.27 billion in 2024 and is projected to reach USD 5.49 billion by 2032, growing at a compound annual growth rate CAGR of 11.68% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electronic Data Capture EDC System Market Size 2024 | USD 2.27 billion |
| Electronic Data Capture EDC System Market, CAGR | 11.68% |
| Electronic Data Capture EDC System Market Size 2032 | USD 5.49 billion |
The Electronic Data Capture (EDC) System market is highly competitive, with key players including Medidata Solutions, Inc., IQVIA Inc., Oracle, Veeva Systems, Clario, Castor, Calyx, IBM, DATATRAK International, Inc., and OpenClinica, LLC leading global operations. These companies dominate through advanced EDC platforms that integrate cloud technologies, artificial intelligence, and real-time analytics to enhance clinical trial efficiency and compliance. North America remains the leading region, accounting for 42% of the global market share in 2024, driven by strong technological infrastructure, high clinical research activity, and early adoption of digital solutions. Europe and Asia-Pacific follow as significant growth regions supported by expanding R&D investments and digital transformation initiatives in clinical data management.
Market Insights
- The Electronic Data Capture (EDC) System market was valued at USD 2.27 billion in 2024 and is projected to reach USD 5.49 billion by 2032, growing at a CAGR of 11.68% during the forecast period.
- Growing adoption of decentralized and virtual clinical trials, increasing R&D investments, and demand for real-time data management are key drivers accelerating market growth.
- The market is witnessing trends such as integration of AI and machine learning, expansion of cloud-based EDC platforms, and rising preference for mobile-compatible solutions in clinical data collection.
- The competitive landscape includes major players such as Medidata Solutions, Oracle, IQVIA, Veeva Systems, and Clario, focusing on product innovation, strategic alliances, and global expansion.
- Regionally, North America holds 42% of the market share, followed by Europe with 27% and Asia-Pacific with 20%, while the web & cloud-based segment dominates by delivery mode with over 65% share in 2024.
Market Segmentation Analysis:
By Delivery Mode
The Electronic Data Capture (EDC) System market by delivery mode is segmented into on-premise and web & cloud-based solutions. The web & cloud-based segment dominated the market in 2024, accounting for over 65% of the total share. This dominance is driven by the growing adoption of decentralized clinical trials, real-time data accessibility, and reduced infrastructure costs. Cloud-based platforms offer scalability, remote monitoring, and integration with other eClinical solutions, making them the preferred choice for pharmaceutical and biotechnology companies seeking efficiency, security, and flexibility in managing clinical trial data.
- For instance, Medidata Solutions offers its cloud-based Rave EDC platform, which has been utilized in over 36,000 trials and has more than 700,000 certified site users. The platform is known for its ability to efficiently manage data in large-scale clinical trials and helps to streamline clinical data management processes.
By Component
Based on component, the market is divided into software and services. The software segment held the largest share, capturing around 58% of the market in 2024. This dominance is attributed to increasing demand for advanced data collection tools that ensure accuracy, compliance, and faster analysis. The growing need for real-time data validation, audit trails, and interoperability with clinical trial management systems has further accelerated software adoption. However, the services segment is expected to grow steadily as organizations increasingly rely on professional support for system integration, maintenance, and regulatory compliance.
- For instance, Veeva Systems enhanced its Vault EDC software with integrated query management to improve data quality and ensure continuous compliance with GxP guidelines such as FDA 21 CFR Part 11 and EMA GCP guidelines. The system uses automation to minimize manual data entry effort during clinical trial processes
By Development Phase
The EDC System market by development phase includes Phase I, Phase II, Phase III, and Phase IV clinical trials. The Phase III segment emerged as the leading sub-segment, holding approximately 45% market share in 2024. This phase involves large-scale trials with extensive patient data, driving demand for robust and efficient EDC systems to manage complex datasets. The need for data accuracy, regulatory adherence, and faster trial completion timelines supports the widespread use of EDC in this stage. Additionally, growing R&D investments and the rising number of late-stage trials continue to fuel this segment’s growth.
Key Growth Drivers
Rising Adoption of Decentralized and Virtual Clinical Trials
The increasing shift toward decentralized and virtual clinical trials is a major growth driver for the Electronic Data Capture (EDC) System market. Pharmaceutical and biotech companies are adopting remote trial models to enhance patient participation and reduce operational costs. EDC systems enable seamless data collection from multiple sources, including wearable devices and remote monitoring tools. Their ability to support real-time access, ensure data integrity, and enhance trial efficiency has made them indispensable in decentralized settings, driving widespread adoption across global clinical research operations.
- For instance, IQVIA integrated its Orchestrated Clinical Trials (OCT) platform with remote sensors capable of capturing numerous biometric data points per participant daily. The system helps manage large volumes of real-time data across various virtual and hybrid studies.
Growing Demand for Real-Time Data Management and Compliance
The demand for real-time, accurate, and compliant data management solutions is propelling the growth of EDC systems. As clinical trials generate vast amounts of data, sponsors increasingly rely on EDC platforms to ensure data consistency, regulatory compliance, and faster decision-making. These systems streamline data collection, validation, and reporting while adhering to Good Clinical Practice (GCP) and FDA 21 CFR Part 11 standards. The ability to reduce errors, enhance transparency, and accelerate approvals significantly boosts their adoption in the life sciences sector.
- For instance, Oracle Life Sciences deployed its Clinical One EDC platform, which is designed to support numerous concurrent trials globally, providing a unified platform for collecting, managing, and harmonizing data from various sources.
Increasing R&D Investments in Clinical Research
Rising R&D spending by pharmaceutical and biotechnology companies is a key factor fueling the EDC market. As organizations intensify their efforts to develop new therapies, they require robust digital tools to manage complex trial data efficiently. EDC systems provide centralized, secure platforms for collecting and analyzing patient information across multiple trial phases. The growing focus on reducing time-to-market and improving drug success rates has led to a surge in EDC deployment, especially in late-phase and multi-regional clinical trials.
Key Trends & Opportunities
Integration of Artificial Intelligence and Machine Learning
A major trend shaping the EDC market is the integration of AI and ML technologies. These innovations enhance data analytics, automate error detection, and improve predictive modeling for clinical outcomes. AI-enabled EDC platforms can identify data anomalies in real time, optimize patient recruitment, and forecast trial performance. This trend is opening new opportunities for precision-driven clinical research, helping sponsors derive actionable insights and accelerate trial timelines while maintaining regulatory compliance and data quality.
- For instance, Clario has deployed its Artificial Intelligence (AI), Machine Learning (ML), and Deep Learning (DL) capabilities more than 1,600 times in the clinical trials it has supported. The average clinical trial generates 3.6 million data points, and Clario uses AI to analyze vast amounts of data to enhance decision-making.
Expansion of Cloud-Based and Mobile EDC Solutions
The growing adoption of cloud-based and mobile EDC systems presents significant market opportunities. Cloud deployment offers scalability, cost-efficiency, and global data accessibility, while mobile integration supports remote data entry and monitoring. This trend aligns with the rise of hybrid and decentralized trials, enabling sponsors to collect real-time data from geographically dispersed participants. As clinical research organizations increasingly favor flexible, collaborative digital ecosystems, the demand for cloud and mobile EDC platforms continues to rise steadily.
- For instance, Castor launched its unified cloud and mobile eClinical platform supporting over 15,000 studies across more than 90 countries with secure data synchronization. The system supports decentralized and site-less clinical trials through its encrypted cloud infrastructure that meets global compliance standards, including GDPR.
Key Challenges
Data Security and Privacy Concerns
Despite their advantages, EDC systems face ongoing challenges related to data security and privacy. The handling of sensitive patient information across global networks exposes systems to cybersecurity threats and compliance risks. Ensuring adherence to data protection regulations such as HIPAA and GDPR requires continuous investment in encryption, access control, and monitoring. Any data breach or non-compliance can undermine trust, delay trials, and result in financial or legal repercussions, posing a major restraint to market growth.
High Implementation Costs and Technical Complexity
The high initial investment required for EDC system deployment remains a significant barrier, particularly for small and mid-sized clinical research organizations. Implementation involves costs related to software licensing, training, and integration with existing clinical systems. Additionally, technical complexity in system customization and maintenance often demands skilled IT resources. These challenges can delay adoption and limit market penetration, especially in emerging regions where budget constraints and limited digital infrastructure persist.
Regional Analysis
North America
North America held the largest share of the Electronic Data Capture (EDC) System market in 2024, accounting for over 42% of the total revenue. The region’s dominance is driven by the strong presence of pharmaceutical and biotechnology companies, advanced healthcare infrastructure, and high adoption of digital clinical solutions. Supportive regulatory frameworks from the U.S. FDA and growing investments in clinical research further strengthen market growth. The increasing focus on decentralized trials and integration of AI-driven analytics continues to enhance the adoption of EDC platforms across the United States and Canada.
Europe
Europe captured around 27% of the EDC System market share in 2024, supported by expanding clinical research activities and strong regulatory emphasis on data integrity. Countries such as Germany, the United Kingdom, and France lead the adoption due to advanced research ecosystems and widespread use of eClinical technologies. The European Medicines Agency’s (EMA) digital transformation initiatives and growing collaborations between research institutions and pharmaceutical companies are driving the use of EDC solutions. Additionally, increasing government funding and cross-border trials within the EU enhance market growth prospects across the region.
Asia-Pacific
The Asia-Pacific region accounted for about 20% of the EDC System market share in 2024 and is expected to register the fastest growth during the forecast period. Rapid expansion of clinical trial activities in countries such as China, India, Japan, and South Korea is fueling demand for advanced data management tools. Rising investments by multinational pharmaceutical companies, growing patient recruitment efficiency, and supportive government policies are accelerating EDC adoption. Furthermore, the increasing penetration of cloud technologies and cost-effective trial operations make Asia-Pacific an attractive destination for global clinical research outsourcing.
Latin America
Latin America represented around 6% of the global EDC System market share in 2024, driven by growing clinical trial activities and improving healthcare infrastructure. Brazil, Mexico, and Argentina are emerging as key contributors due to their expanding pharmaceutical sectors and favorable regulatory reforms. The region is witnessing increasing partnerships between local CROs and global sponsors, promoting the adoption of EDC systems to ensure compliance and efficiency. However, limited technical expertise and inconsistent digital adoption across countries remain challenges, though gradual technological advancements are expected to support steady market growth.
Middle East & Africa
The Middle East & Africa (MEA) region accounted for around 5% of the EDC System market share in 2024, with growth primarily led by the United Arab Emirates, Saudi Arabia, and South Africa. The region is gradually embracing digital transformation in clinical research, supported by government initiatives to strengthen healthcare innovation. Increasing investments in clinical trials, coupled with partnerships with international pharmaceutical companies, are driving EDC system adoption. However, limited infrastructure and lower R&D expenditure compared to other regions pose challenges. Despite this, ongoing modernization of healthcare systems offers promising growth potential for EDC providers in MEA.
Market Segmentations:
By Delivery Mode
- On-premise
- Web & Cloud-based
By Component
- Software
- Services
By Development Phase
- Phase I
- Phase II
- Phase III
- Phase IV
By End-user
- Hospitals/Healthcare providers
- CROs
- Pharmaceutical and Biotechnology Firms
- Medical Device Firms
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Electronic Data Capture (EDC) System market is characterized by the strong presence of leading players such as Medidata Solutions, Inc., DATATRAK International, Inc., IQVIA Inc., Clario, Oracle, Castor, Veeva Systems, IBM, Calyx, and OpenClinica, LLC. These companies focus on technological innovation, strategic partnerships, and product enhancements to strengthen their market positions. Cloud-based platforms, AI-driven analytics, and integration with other eClinical tools remain central to their competitive strategies. Major players are investing heavily in developing scalable, secure, and interoperable solutions to support decentralized and hybrid trials. Mergers, acquisitions, and collaborations with contract research organizations (CROs) are also prevalent, enabling companies to expand their global footprint and service capabilities. Continuous advancements in automation, compliance management, and real-time data processing are further intensifying competition, positioning technology differentiation and customer-centric service models as key success factors in the evolving EDC market landscape.
Key Player Analysis
- Medidata Solutions, Inc.
- DATATRAK International, Inc.
- IQVIA Inc.
- Clario
- Oracle
- Castor
- Veeva Systems
- IBM
- Calyx
- OpenClinica, LLC
Recent Developments
- In August 2025, Oracle Corporation announced enhancements to its Clinical One Data Collection EDC offering, adding AI-enabled EHR-EDC integration, expanded document-upload capabilities, and tighter safety-reporting workflows under ICH E2B(R3).
- In February 2025, Oracle was recognised as a Leader in the Everest Group PEAK Matrix® for life-sciences CTMS products, noting its ecosystem supports EDC integration, which underscores its positioning in EDC enablement.
- In October 2024, Medidata Solutions, Inc. announced the launch of Rave Lite, an extension of its Rave EDC product designed for Phase I and Phase IV trials.
- In March 2024, Veeva Systems announced that its Vault EDC platform had powered more than 1,000 study starts, marking a major adoption milestone
Report Coverage
The research report offers an in-depth analysis based on Delivery Mode, Component, Development Phase, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Electronic Data Capture (EDC) System market will continue to expand rapidly, driven by increasing digital transformation in clinical research.
- Adoption of decentralized and hybrid clinical trial models will boost demand for cloud-based EDC platforms.
- Artificial intelligence and machine learning integration will enhance data accuracy, analysis, and predictive insights in clinical trials.
- Strategic collaborations between pharmaceutical companies and technology providers will accelerate product innovation.
- Regulatory support for digital data collection will encourage wider implementation of compliant EDC systems.
- The growing focus on patient-centric trials will increase the use of mobile and remote data capture solutions.
- Emerging economies in Asia-Pacific will witness strong growth due to expanding clinical trial activities and technological adoption.
- Cybersecurity advancements will become a key priority to ensure data integrity and patient privacy.
- Increased use of interoperable systems will streamline data exchange across eClinical platforms.
- Continuous R&D investments will strengthen market competitiveness and drive technological evolution in EDC solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Decentralized and Virtual Clinical Trials
The shift toward decentralized and virtual clinical trials is increasing the need for robust EDC systems that can support remote data collection, real-time access, and integration with wearable devices, thereby enhancing patient participation and operational efficiency.
Growing Demand for Real-Time Data Management and Compliance
As clinical trials generate larger and more complex datasets, sponsors require EDC platforms that ensure data accuracy, regulatory compliance, and faster decision-making, driving adoption of advanced EDC solutions.
Increasing R&D Investments in Clinical Research
Pharmaceutical and biotechnology companies are boosting R&D spending to accelerate drug development, which in turn fuels demand for EDC systems that streamline data management across multiple trial phases and geographies.
Integration of Artificial Intelligence and Machine Learning
The incorporation of AI and ML into EDC platforms enables automated error detection, predictive analytics, and improved data quality, making these systems more attractive for sponsors seeking efficiency and actionable insights.
Expansion of Cloud-Based and Mobile EDC Solutions
The move toward cloud and mobile EDC platforms offers scalability, cost savings, and global accessibility, supporting the growing trend of hybrid and decentralized trials and enabling real-time data capture from diverse locations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Electronic Data Capture (EDC) Systems Market?
.At what Compound Annual Growth Rate is the Electronic Data Capture EDC System market projected to grow between 2025 and 2032?
What factors are driving the growth of the Electronic Data Capture (EDC) Systems Market?
What are some challenges faced by the Electronic Data Capture (EDC) SystemsMarket?
Who are the major players in the Electronic Data Capture (EDC) Systems Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Hospitals/Healthcare providers
- 1.2.2 CROs
- 1.2.3 Pharmaceutical and Biotechnology Firms
- 1.2.4 Medical Device Firms
- 1.3 By Component
- 1.3.1 Software
- 1.3.2 Services
- 1.4 By Delivery Mode
- 1.4.1 On-premise
- 1.4.2 Web & Cloud-based
- 1.5 By Development Phase
- 1.5.1 Phase I
- 1.5.2 Phase II
- 1.5.3 Phase III
- 1.5.4 Phase IV
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.27 billion → 2032: USD 5.49 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electronic Data Capture (EDC) Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electronic Data Capture (EDC) Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electronic Data Capture (EDC) Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electronic Data Capture (EDC) Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electronic Data Capture (EDC) Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electronic Data Capture (EDC) Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electronic Data Capture (EDC) Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electronic Data Capture (EDC) Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.27 billion → 2032: USD 5.49 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electronic Data Capture (EDC) Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals/Healthcare providers
- 12.3.7.2 CROs
- 12.3.7.3 Pharmaceutical and Biotechnology Firms
- 12.3.7.4 Medical Device Firms
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Software
- 12.4.7.2 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Delivery Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-premise
- 12.5.7.2 Web & Cloud-based
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Development Phase - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Phase I
- 12.6.7.2 Phase II
- 12.6.7.3 Phase III
- 12.6.7.4 Phase IV
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electronic Data Capture (EDC) Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electronic Data Capture (EDC) Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electronic Data Capture (EDC) Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electronic Data Capture (EDC) Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medidata Solutions, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 IQVIA Inc.
- 18.4 Oracle
- 18.5 Veeva Systems
- 18.6 Clario
- 18.7 Castor
- 18.8 Calyx
- 18.9 IBM
- 18.10 DATATRAK International, Inc.
- 18.11 OpenClinica, LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

