
Email Marketing Market Overview:
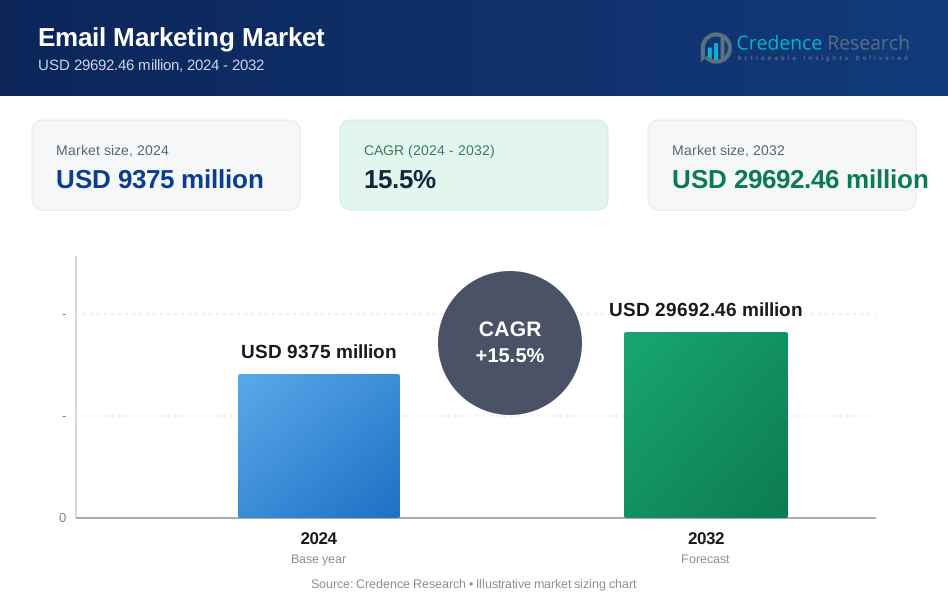
The email marketing market was valued at USD 9375 million in 2024 and is projected to reach USD 29692.46 million by 2032, growing at a CAGR of 15.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Email Marketing Market Size 2024 | USD 9375 million |
| Email Marketing Market, CAGR | 15.5% |
| Email Marketing Market Size 2032 | USD 29692.46 million |
Email Marketing Market Insights
- Market growth is driven by rising digital commerce, demand for direct customer engagement, and measurable campaign performance, with software leading the component segment at a market share of 68.9%.
- Key trends include automation, personalization, and AI-led analytics, while cloud-based deployment dominates with a market share of 74.3% due to scalability and ease of integration.
- Competitive intensity remains high as vendors invest in automation, CRM integration, and compliance features, while data privacy regulations and email fatigue act as key restraints.
- North America leads with a market share of 38.5%, followed by Europe at 27.4% and Asia Pacific at 24.6%, supported by digital maturity, enterprise adoption, and expanding SME usage.

Email Marketing Market Segmentation Analysis:
By Component
By component, software dominates the email marketing market with a market share of 68.9%. Organizations prefer software platforms to design, automate, and analyze email campaigns at scale. Email marketing software offers features such as audience segmentation, personalization, A/B testing, and performance analytics. Growing focus on data-driven marketing increases reliance on advanced tools. Integration with CRM and analytics platforms strengthens adoption. Services play a supporting role through consulting and campaign management. Software remains dominant due to recurring subscription models, continuous feature upgrades, and its central role in executing and optimizing email marketing strategies.
- For instance, Salesforce Email Studio processes over 4 trillion email sends annually and supports AI-based send-time optimization using billions of engagement signals.
By Deployment Mode
By deployment mode, cloud-based solutions lead the email marketing market with a market share of 74.3%. Businesses adopt cloud platforms for scalability, cost efficiency, and remote accessibility. Cloud deployment enables real-time campaign execution and analytics. Automatic updates reduce maintenance burden. Small and large enterprises favor cloud solutions for faster deployment and integration with digital ecosystems. On-premise deployment remains limited to organizations with strict data control needs. Cloud-based dominance continues due to flexibility, subscription pricing, and rising adoption of cloud-native marketing technologies.
- For instance, HubSpot cloud email tools handle billions of automated workflow actions each month while syncing data across CRM, email, and analytics modules.
By End User
By end user, small and medium enterprises account for a market share of 57.6%, leading email marketing adoption. SMEs use email marketing to reach targeted audiences with limited budgets. Cost-effective tools support customer engagement and retention. Easy-to-use platforms attract non-technical users. Personalized email campaigns help SMEs compete with larger brands. Large enterprises follow with complex campaign needs and global reach. SMEs remain dominant due to high volume adoption, affordability of cloud tools, and growing emphasis on direct digital communication.
Key Growth Drivers
Rising Adoption of Digital and Direct Marketing Channels
Businesses continue to shift marketing budgets toward digital and direct communication channels. Email marketing offers controlled reach, measurable performance, and cost efficiency. Companies use email campaigns to engage existing customers without reliance on third-party platforms. Growing digital commerce activity increases the need for direct messaging. Email supports promotions, product launches, and customer education. Marketers value clear metrics such as open rates and conversions. Integration with customer databases strengthens targeting accuracy. As organizations prioritize owned marketing channels, email marketing remains a core component of long-term digital engagement strategies.
- For instance, Mailchimp delivers a vast volume of messages and supports campaign tracking across a massive scale of monthly user interactions.
Growing Demand for Personalized and Automated Campaigns
Personalized communication has become essential for customer engagement. Email marketing platforms enable segmentation based on behavior, purchase history, and preferences. Automated workflows deliver timely messages without manual effort. Businesses use automation for welcome emails, reminders, and retention campaigns. Personalized content improves engagement and conversion rates. Data insights help refine messaging strategies. Automation allows teams to scale campaigns efficiently. This driver supports adoption across enterprises and SMEs. Demand for relevant, timely communication continues to strengthen the role of personalization and automation in email marketing growth.
- For instance, Adobe Campaign uses AI models trained on billions of customer interactions to generate dynamic email content and trigger automated journeys across email, web, and mobile channels.
Expansion of E-commerce and Online Customer Engagement
E-commerce growth increases reliance on continuous customer communication. Online retailers use email marketing to support promotions, cart recovery, and loyalty programs. Transactional emails enhance customer experience and trust. Brands depend on email to drive repeat purchases and traffic. Integration with e-commerce platforms improves targeting accuracy. Online customer engagement strategies rely heavily on email touchpoints. As digital shopping expands across regions, demand for structured email communication rises. This driver supports consistent growth of email marketing solutions across retail and consumer-focused industries.
Key Trends & Opportunities
Integration of AI and Advanced Analytics
AI adoption enhances email marketing effectiveness. Predictive analytics helps optimize send times and content selection. AI-driven tools improve subject line performance and audience targeting. Advanced analytics provide deeper campaign insights. Marketers use data to refine strategies and improve ROI. This trend creates opportunities for smarter platforms. AI integration strengthens differentiation among solution providers. Continuous improvement in analytics capabilities supports long-term market expansion.
- For instance, Oracle Responsys analyzes billions of customer events daily to drive AI-based audience selection and real-time email recommendations.
Growing Adoption Among Small and Medium Enterprises
SMEs increasingly adopt email marketing to build customer relationships. Cloud-based tools offer affordability and ease of use. SMEs benefit from automated campaigns and simple dashboards. Email marketing helps smaller businesses compete with larger brands. This trend expands the market user base. Vendors design SME-focused solutions to capture demand. Growing digital awareness among SMEs creates strong future growth opportunities.
- For instance, Zoho Corporation supports millions of small businesses globally, enabling automated email workflows triggered by CRM activities and website actions.
Key Challenges
Rising Concerns Around Data Privacy and Compliance
Data privacy regulations impact email marketing execution. Consent management requirements increase operational complexity. Compliance varies across regions, affecting global campaigns. Marketers must ensure lawful data usage. These requirements increase administrative burden. Non-compliance risks penalties and reputational damage. This challenge affects campaign flexibility and scalability.
Email Saturation and Declining Engagement Rates
High email volumes increase inbox competition. Users become selective about content. Open and click rates face pressure. Marketers must improve relevance and creativity. Poor targeting reduces effectiveness. Engagement challenges push brands to refine strategies. This challenge influences campaign performance and long-term effectiveness.
Regional Analysis
North America
North America holds a market share of 38.5% in the email marketing market, supported by advanced digital infrastructure and high adoption of data-driven marketing tools. Enterprises and SMEs actively use email platforms for customer engagement, retention, and automation. Strong presence of software vendors accelerates innovation in analytics and personalization. E-commerce, retail, and technology sectors drive large campaign volumes. Cloud-based solutions dominate due to scalability and integration benefits. The United States leads regional demand, while Canada supports growth through expanding SME adoption and rising focus on measurable digital marketing performance.
Europe
Europe accounts for a market share of 27.4%, driven by widespread digital transformation across enterprises. Businesses use email marketing to support customer communication while complying with strict data protection regulations. Countries such as the United Kingdom, Germany, and France lead adoption. Marketers emphasize consent-based campaigns and personalization. Cloud platforms gain traction among SMEs. Retail, BFSI, and travel sectors remain key users. Regulatory compliance shapes platform features and data governance. Europe maintains steady growth through structured marketing strategies and increasing focus on customer lifecycle management.
Asia Pacific
Asia Pacific holds a market share of 24.6%, reflecting rapid digitalization and expanding online business activity. Growing e-commerce usage and mobile-first consumers drive demand for email campaigns. SMEs adopt email marketing to reach large customer bases at low cost. Countries such as China, India, Japan, and Australia contribute strongly. Cloud-based tools attract cost-sensitive users. Localization and multilingual campaigns support regional adoption. Rising internet penetration and digital entrepreneurship sustain strong growth momentum across the region.
Rest of the World
The Rest of the World region represents a market share of 9.5%, supported by gradual digital marketing adoption. Latin America shows increasing use of email campaigns among retailers and service providers. The Middle East benefits from growing digital commerce and business automation. Africa remains in early adoption stages but shows rising interest among SMEs. Vendors expand through partnerships and localized offerings. Although smaller in size, the region presents long-term growth potential as digital infrastructure and online business activity continue to improve.
Email Marketing Market Segmentations:
By Component
- Software
- Services
By Deployment Mode
- Cloud-based
- On-premise
By End User
- Small and medium enterprises
- Large enterprises
By Industry Vertical
- Retail and e-commerce
- BFSI
- IT and telecom
- Healthcare
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights strong competition led by Salesforce, Adobe, HubSpot, Mailchimp, and Oracle. These players compete through advanced automation, analytics depth, and seamless integration with CRM and e-commerce platforms. Market leaders focus on personalization, AI-driven insights, and campaign optimization to improve engagement rates. Cloud-based delivery models dominate due to scalability and subscription pricing. Vendors invest in user-friendly interfaces to attract SMEs while supporting complex workflows for large enterprises. Data security and compliance features influence purchasing decisions, especially in regulated regions. Mid-sized platforms compete through niche positioning and flexible pricing. Overall competition remains high as innovation, ease of use, and measurable ROI shape buyer preferences in the email marketing market.
Key Player Analysis
- Salesforce
- Adobe
- HubSpot
- Mailchimp
- Oracle
- Microsoft
- Zoho Corporation
- SAP
- Campaign Monitor
- ActiveCampaign
Recent Developments
- In October 2025, Mailchimp (Intuit) released new Shopify-specific enhancements and email triggers, enabling deeper behavioral insights and improved omnichannel campaigns for holiday retail outreach.
- In March 2025, Adobe introduced AI agents within Adobe Experience Cloud to improve customer experience workflows and automate insightful campaign decisions.
- In 2025, Salesforce continued evolving Salesforce Marketing Cloud with advanced AI personalization and journey automation tools to help marketers target audiences and optimize email campaigns in real time.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Mode, End User, Industry Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Email marketing adoption will grow across all business sizes.
- Automation will become standard in campaign execution.
- Personalization will play a central role in customer engagement.
- AI-driven insights will improve targeting and timing.
- Cloud platforms will remain the preferred deployment model.
- SME usage will expand due to affordability and ease of use.
- Privacy-compliant campaign tools will gain importance.
- Integration with e-commerce platforms will increase.
- Asia Pacific will record faster adoption rates.
- Competition will intensify through innovation and feature expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Email Marketing market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Email Marketing market projected to grow between 2024 and 2032?
Which Email Marketing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Email Marketing market?
Who are the leading companies in the Email Marketing market?
Which region commanded the largest share of the Email Marketing market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Email Marketing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Email Marketing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9375 million → 2032: USD 29692.46 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Email Marketing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Email Marketing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Email Marketing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Email Marketing Market Drivers
- 3.3 Email Marketing Market Restraints & Challenges
- 3.4 Email Marketing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Email Marketing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Email Marketing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Email Marketing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Email Marketing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Email Marketing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Email Marketing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Email Marketing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Email Marketing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Email Marketing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Email Marketing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Email Marketing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Email Marketing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Email Marketing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Email Marketing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Email Marketing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Email Marketing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Email Marketing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Email Marketing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Email Marketing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
