
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Emission Monitoring System (EMS) Market Size 2024 | USD 4,350 million |
| Emission Monitoring System (EMS) Market, CAGR | 9.2% |
| Emission Monitoring System (EMS) Market Size 2032 | USD 8,796 million |
Market Overview:
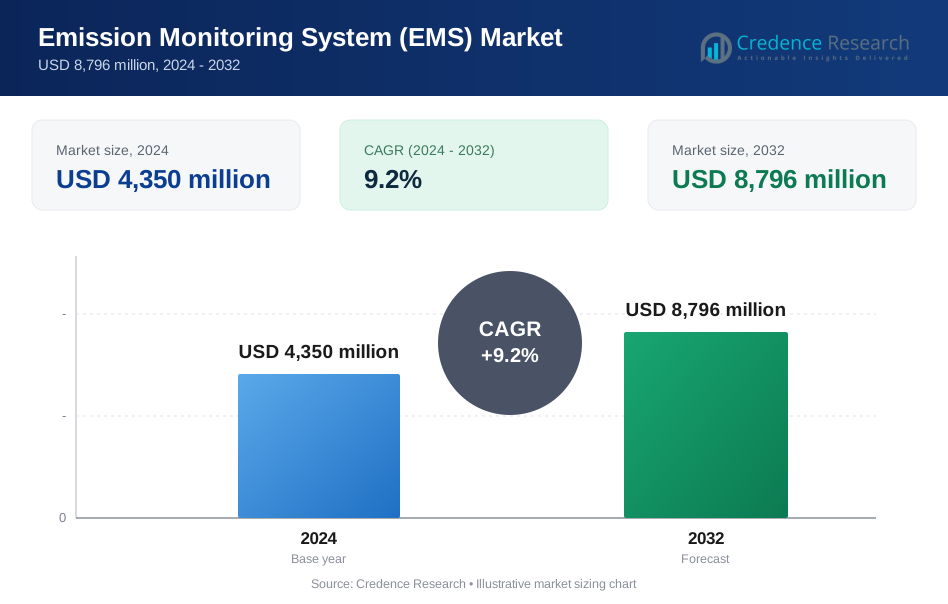
The Emission Monitoring System (EMS) Market is projected to grow from USD 4,350 million in 2024 to an estimated USD 8,796 million by 2032, with a compound annual growth rate (CAGR) of from 2024 to 2032.
The increasing demand for real-time monitoring of emissions, stricter environmental regulations, and growing awareness of climate change are key factors driving the growth of the EMS market. Governments worldwide are tightening emissions standards, making it mandatory for industries to implement advanced monitoring systems to track and manage their environmental impact. The industrial sector, particularly in manufacturing, energy, and transportation, is a major contributor to the demand for emission monitoring systems. The growing focus on reducing greenhouse gas emissions and the need to comply with national and international environmental standards are pushing industries to adopt EMS solutions. Moreover, the increasing emphasis on sustainability and corporate social responsibility (CSR) is encouraging companies to invest in emission monitoring systems to demonstrate their commitment to reducing their carbon footprint. Technological advancements in EMS, such as the integration of Internet of Things (IoT) devices, artificial intelligence (AI), and cloud computing, are further propelling market growth. These technologies enable real-time data collection, analysis, and reporting, making it easier for businesses to ensure compliance with environmental regulations and enhance operational efficiency. The development of remote monitoring systems that can track emissions from multiple sources simultaneously is also contributing to the market’s expansion.
Regionally, North America and Europe are leading the EMS market due to stringent environmental regulations and government incentives aimed at reducing emissions. The United States and key European nations have implemented policies that require industries to adopt emission monitoring technologies to meet national and international emissions reduction targets. In the Asia Pacific region, countries like China, India, and Japan are experiencing significant growth in the EMS market, driven by rapid industrialization and government initiatives to address pollution and reduce emissions.
Market insights:
- The Emission Monitoring System (EMS) market is projected to grow from USD 4,350 million in 2024 to USD 8,796 million by 2032, with a CAGR of 9.2% from 2024 to 2032.
- Key drivers include rising environmental regulations, the growing need for businesses to track and reduce emissions, and the increasing focus on sustainability and corporate responsibility.
- Technological advancements, such as IoT, AI, and cloud-based solutions, are enhancing EMS capabilities, driving demand for real-time emissions monitoring and compliance reporting.
- Stringent government policies and international climate agreements are pushing industries in sectors like manufacturing, energy, and transportation to adopt EMS solutions.
- High implementation costs and the complexity of integrating EMS into existing infrastructure may act as market restraints for small and medium-sized enterprises (SMEs).
- North America and Europe are the leading regions in EMS adoption, supported by stringent environmental laws and government incentives for emission reduction.
- The Asia Pacific region, particularly China, India, and Japan, is experiencing significant growth due to industrial expansion and increasing government efforts to reduce pollution and meet climate targets.
Market Drivers:
Stringent Environmental Regulations:
Governments worldwide are implementing stricter environmental regulations that require businesses to monitor and reduce their emissions. In 2021, the European Union's Green Deal set an ambitious goal to reduce net emissions by at least 55% by 2030. This regulation is pushing industries to adopt emission monitoring systems to comply with national and international environmental standards. According to the World Bank, 90% of the world's greenhouse gas emissions are covered by some form of carbon pricing or emissions reduction regulation, further driving the need for efficient EMS solutions to ensure compliance. For instance, in 2022, the United Nations Framework Convention on Climate Change (UNFCCC) reported that over 160 countries have signed up to the Paris Agreement, committing to measures that will require robust emission monitoring systems in place to track progress toward their national reduction targets. This global effort is bolstering demand for emission monitoring technologies across industries.
Technological Advancements in EMS:
The evolution of digital technologies such as the Internet of Things (IoT), Artificial Intelligence (AI), and cloud computing has significantly advanced the capabilities of emission monitoring systems. The integration of IoT devices enables real-time data collection and analysis, improving the accuracy of emission readings and simplifying compliance reporting. In 2022, the International Energy Agency (IEA) reported a 30% increase in the deployment of digital technologies within the industrial sector to monitor energy use and emissions. IBM's partnership with the World Economic Forum (WEF) has resulted in the development of AI-powered EMS solutions that analyze carbon emissions data in real-time, enabling businesses to make immediate adjustments to reduce their environmental impact.
Corporate Sustainability Initiatives:
As businesses face increasing pressure from stakeholders, including consumers and investors, to adopt sustainable practices, corporate sustainability initiatives are driving the growth of the EMS market. According to the Global Reporting Initiative (GRI), over 60% of large corporations worldwide are committed to net-zero emissions targets, with many incorporating advanced EMS into their operations to track progress. In 2023, the United Nations Global Compact reported that 87% of major corporations are now integrating sustainability into their corporate strategies, demonstrating a global shift toward greater environmental responsibility. For instance, Microsoft, which committed to becoming carbon negative by 2030, has implemented sophisticated emission monitoring systems across its global operations to track and report its emissions reduction progress.
Government Incentives and Policies:
Government incentives and policies play a crucial role in encouraging businesses to adopt emission monitoring systems. Governments are offering tax incentives, grants, and subsidies to help organizations implement clean technologies, including EMS. For instance, the U.S. government, through the Inflation Reduction Act (2022), allocated billions of dollars in tax incentives for companies that reduce their carbon footprint, promoting EMS adoption in various industries. The International Monetary Fund (IMF) projected that the global economy would need to invest an additional 2.3% of global GDP annually to meet climate change goals. As a result, governments across the world are enhancing policy frameworks to incentivize the use of EMS.
Market Trends:
Increased Adoption of Real-Time Monitoring Systems:
One of the key trends in the EMS market is the increasing adoption of real-time monitoring systems, which allow businesses to track emissions instantaneously and take corrective actions promptly. Governments are supporting this transition through various incentives and policies aimed at enhancing environmental sustainability. Real-time monitoring provides industries with valuable insights into their carbon footprints, helping them stay compliant with evolving regulations. For instance, the U.S. Environmental Protection Agency (EPA) has rolled out a number of programs that encourage companies to invest in real-time monitoring solutions to comply with air quality regulations. The EPA's budget for fiscal year 2023 allocated over $150 million for air quality management projects, which includes the development of real-time emission monitoring technologies.
Integration of Artificial Intelligence (AI) and Machine Learning (ML):
The integration of AI and ML in EMS is another notable market trend. These technologies enable advanced data analysis, helping industries optimize their operations for reduced emissions. AI-driven algorithms can predict future emissions based on historical data, automate reporting, and enhance compliance. Machine learning also improves the accuracy of emission forecasts, allowing companies to plan ahead for their sustainability goals. For instance, the World Bank's recent report highlighted the role of AI in emissions management, stating that AI can potentially reduce industrial emissions by up to 30% through better resource management and predictive maintenance. In 2022, the World Bank announced a $500 million investment into AI and climate-tech initiatives aimed at reducing industrial emissions globally. This technological push is driving the EMS market towards more intelligent, efficient systems that can provide greater insights into emission trends.
Focus on Carbon Capture and Storage (CCS):
As part of global efforts to meet net-zero emissions goals, industries are increasingly investing in carbon capture and storage (CCS) technologies. The integration of CCS with emission monitoring systems is becoming a significant trend. Governments and regulatory bodies are introducing incentives and regulations to encourage companies to adopt these technologies. The European Union, for example, has committed to investing €10 billion in the development and deployment of CCS technologies by 2025. In 2023, the European Investment Bank (EIB) allocated approximately €2 billion to fund CCS projects across Europe, with several large industrial projects adopting integrated EMS to monitor and manage the captured CO2. This growing focus on CCS is helping to further drive the EMS market, as companies seek solutions to not only monitor emissions but also manage and mitigate them.
Rise of Cloud-Based Emission Monitoring Solutions:
Cloud-based emission monitoring solutions are gaining popularity in the EMS market due to their scalability, accessibility, and cost-efficiency. Cloud platforms allow businesses to collect, store, and analyze emissions data remotely, reducing the need for on-premise infrastructure. The ease of access to data enables companies to comply with global emissions regulations more efficiently. The U.S. Department of Energy (DOE) has been promoting cloud-based monitoring systems through its clean energy programs, which include over $1 billion in grants and funding for the adoption of digital tools for energy efficiency and emissions management. Cloud-based solutions also allow for real-time updates and integration with other energy management systems, making it easier for companies to optimize their operations.
Market Challenge Analysis:
High Initial Implementation Costs:
One of the primary challenges facing the Emission Monitoring System (EMS) market is the high initial investment required for the implementation of advanced monitoring technologies. Small and medium-sized enterprises (SMEs) often face difficulties in allocating sufficient resources for these systems, particularly in industries where profit margins are already under pressure. While EMS solutions can lead to long-term operational efficiencies and regulatory compliance, the upfront costs associated with installing hardware, software, and integrating with existing infrastructure can be a significant barrier. The U.S. Environmental Protection Agency (EPA) has acknowledged that many small-scale industries struggle with the costs associated with meeting air quality standards, as these businesses lack the financial capacity to invest in advanced EMS technologies. In 2021, the EPA estimated that over 30% of businesses in the manufacturing sector would need financial assistance to comply with new emissions monitoring regulations, underscoring the economic challenge faced by these organizations.
Integration Complexities with Existing Systems:
Another major challenge in the EMS market is the complexity of integrating new monitoring systems with existing infrastructure. Many companies are operating legacy systems that were not designed to accommodate modern EMS technologies. Integrating these new systems can involve significant technical hurdles, including compatibility issues, data synchronization challenges, and the need for specialized personnel. Additionally, integrating cloud-based solutions with on-premise systems can be cumbersome, leading to increased time and costs during the transition. For instance, a report by the International Energy Agency (IEA) in 2022 highlighted that over 40% of industrial facilities in developed countries faced significant challenges in integrating modern emission monitoring technologies into their older production lines. These integration difficulties delay the implementation process and may cause temporary disruptions in operations, further discouraging some companies from adopting these systems.
Market Opportunities:
The growing global emphasis on sustainability presents significant opportunities for the Emission Monitoring System (EMS) market. With stricter environmental regulations and increasing pressure on businesses to reduce their carbon footprints, the demand for advanced monitoring systems is poised to rise. Governments worldwide, including those in Europe, North America, and Asia, are tightening emissions standards and offering incentives for companies that adopt clean technologies. As industries face mounting regulatory requirements, the need for efficient and reliable EMS solutions to ensure compliance and track progress toward sustainability goals becomes more pronounced. This offers a considerable growth opportunity for EMS providers to expand their customer base and innovate to meet the evolving needs of various industries, particularly in manufacturing, energy, and transportation.
Moreover, the continued advancements in digital technologies such as AI, IoT, and cloud computing open new avenues for growth in the EMS market. The integration of AI-driven analytics and cloud-based platforms enhances the capabilities of EMS by providing real-time data analysis and improving the overall efficiency of emission monitoring. These innovations not only streamline operations but also enable businesses to optimize their energy consumption and reduce emissions more effectively. As companies increasingly adopt digital solutions to enhance their sustainability initiatives, EMS providers can capitalize on the growing demand for smarter, more connected systems. This trend is further bolstered by corporate sustainability goals, which are becoming integral to business strategies, offering long-term opportunities for growth in the EMS market.
Market Segmentation Analysis:
By Type
The Emission Monitoring System (EMS) market is primarily segmented into two types: Continuous Emission Monitoring Systems (CEMS) and Predictive Emission Monitoring Systems (PEMS). CEMS are widely adopted due to their ability to provide real-time, continuous data on emissions, ensuring constant monitoring for regulatory compliance. They are essential in industries such as power generation and chemical manufacturing, where maintaining stringent emissions standards is crucial. On the other hand, PEMS, which use advanced predictive models to estimate emissions, are gaining popularity in industries looking to reduce operational costs and improve efficiency. By forecasting emissions, PEMS allow businesses to take proactive measures, preventing potential violations of environmental regulations.
By Component
The EMS market is also segmented by components, including hardware, software, and services. Hardware encompasses the physical instruments required for monitoring, such as sensors and analyzers. Software enables the collection, storage, and analysis of emissions data, often providing features like real-time monitoring, reporting, and compliance alerts. Services, including installation and deployment, training, and support & maintenance, are essential for ensuring that EMS systems operate effectively and remain updated. This segmentation reflects the growing demand for integrated solutions, with industries seeking comprehensive systems that combine hardware, software, and expert services to meet stringent emissions standards efficiently.
Segmentation:
Based on Type
- Continuous Emission Monitoring System (CEMS)
- Predictive Emission Monitoring System (PEMS)
Based on Component
- Hardware
- Software
- Services
- Installation & Deployment
- Training
- Support & Maintenance
Based on End-Use
- Oil & Gas
- Metals & Mining
- Power Generation
- Chemical & Fertilizer
- Pulp & Paper
- Pharmaceutical
- Others
Based on Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a dominant share of the global Emission Monitoring System (EMS) market, accounting for 35% of the total market share in 2024. This region’s strong regulatory environment, particularly in the United States and Canada, drives the adoption of EMS technologies. Government policies and initiatives focused on reducing emissions and promoting sustainability are major contributing factors. The U.S. Environmental Protection Agency (EPA) enforces stringent emission standards across various sectors, pushing companies to adopt advanced monitoring solutions to ensure compliance. For instance, the EPA’s enforcement of the Clean Air Act requires industries to maintain emission levels within specified limits, directly increasing the demand for reliable EMS.
Europe
Europe is another key player in the global EMS market, holding around 30% of the market share in 2024. The European Union’s ambitious environmental goals, particularly under the European Green Deal, are driving the adoption of emission monitoring technologies. The EU has set a target to achieve net-zero emissions by 2050, and interim goals include reducing greenhouse gas emissions by at least 55% by 2030. These regulations are encouraging industries to adopt advanced emission monitoring systems to meet compliance and reduce their carbon footprints. For instance, in 2022, the European Investment Bank (EIB) committed to support emission monitoring and carbon capture projects. The region’s commitment to climate change mitigation and its focus on sustainable development make Europe a significant market for EMS solutions, with a growing number of companies in manufacturing, energy, and transport sectors adopting these systems to meet regulatory requirements.
Asia Pacific
The Asia Pacific region is witnessing rapid growth in the EMS market, with an estimated market share of 25% in 2024, and this share is expected to increase steadily over the next few years. Countries such as China, India, and Japan are leading the charge due to rapid industrialization, urbanization, and growing environmental concerns. Governments in these countries are tightening emissions regulations and setting ambitious targets for carbon reduction. For instance, in 2022, the Chinese government announced a target to peak carbon emissions before 2030 and achieve carbon neutrality by 2060, which has significantly increased the demand for emission monitoring systems. Similarly, India’s adoption of stricter environmental norms, backed by its National Action Plan on Climate Change (NAPCC), is driving the EMS market growth in the region.
Key Player Analysis:
- ABB Ltd.
- Ametek, Inc.
- Emerson Electric Company
- General Electric Company
- Enviro Technology Services Plc.
- Horiba Ltd.
- Fuji Electric Co., Ltd.
- Rockwell Automation, Inc.
- Siemens AG
- Thermo Fisher Scientific Inc.
Competitive Analysis:
The Emission Monitoring System (EMS) market is highly competitive, with several key players striving to meet the increasing demand for advanced emission monitoring technologies. Companies focus on offering comprehensive solutions that integrate hardware, software, and services to ensure regulatory compliance and operational efficiency. Leading providers are investing in the development of innovative systems that leverage cutting-edge technologies like AI, IoT, and cloud computing to enhance real-time monitoring capabilities and predictive analytics. The market is also characterized by strategic partnerships, mergers, and acquisitions, as companies look to expand their product offerings and enter new markets. Additionally, firms are emphasizing after-sales services, such as installation, training, and ongoing support, to differentiate themselves from competitors. As environmental regulations become stricter across various industries, competition is expected to intensify, pushing companies to continuously innovate and improve their EMS solutions to meet evolving market needs and regulatory requirements.
Recent Developments:
- In April 2023, the U.S. National Aeronautics and Space Administration (NASA) launched an advanced device called Tropospheric Emissions: Monitoring of Pollution (TEMPO). Designed to monitor air pollution across North America, TEMPO offers exceptional accuracy in detecting and analyzing air quality. This innovative technology has the potential to reveal significant variations in pollution exposure, providing crucial insights into environmental health.
- In July 2023, following the acquisition of A1-CBISS Limited by the ENVEA Group in September 2021, the two entities, A1-CBISS Limited and ENVEA UK Limited, are set to merge. A1-CBISS Limited, based in Tranmere, UK, is recognized for its expertise as a turnkey solution provider and integrator of continuous emission monitoring systems.
- In August 2023, the 15th International Conference and Exhibition on Emission Monitoring (CEM) is scheduled to take place from September 20th to 22nd, 2023, in Barcelona, Spain.
Market Concentration & Characteristics:
The Emission Monitoring System (EMS) market exhibits a moderate to high concentration, with a few key players holding substantial market share, while numerous smaller companies provide specialized solutions. Larger firms dominate the market by offering comprehensive, integrated systems that combine hardware, software, and services. These players often have extensive resources for research and development, allowing them to lead in technological advancements, such as AI, IoT, and cloud-based solutions, which enhance the capabilities of EMS. Smaller companies, on the other hand, typically focus on niche applications or specific industries, providing tailored solutions that cater to unique regulatory or operational requirements. The market is characterized by continuous innovation, with companies striving to enhance product functionality, improve system accuracy, and comply with evolving environmental standards. As regulations become stricter globally, the EMS market will likely see further consolidation, with leading players strengthening their positions through mergers, acquisitions, and strategic collaborations.
Report Coverage:
The research report offers an in-depth analysis based on By type, By Component, By End-User, By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for emission monitoring systems will continue to grow as industries face stricter environmental regulations globally.
- Technological advancements in AI, IoT, and cloud computing will enhance the capabilities and efficiency of EMS solutions.
- Governments will increase incentives and regulations that drive businesses to adopt advanced emission monitoring technologies to meet sustainability goals.
- The adoption of predictive emission monitoring systems (PEMS) will rise due to their ability to forecast emissions and improve operational efficiency.
- Real-time emission monitoring solutions will become more critical as industries seek to stay compliant and mitigate environmental risks.
- Increased corporate sustainability efforts will drive the adoption of EMS, with businesses aiming for net-zero emissions.
- Emerging markets in Asia Pacific, particularly China and India, will see significant growth due to industrial expansion and stricter environmental policies.
- There will be a rise in demand for cloud-based EMS solutions as businesses seek cost-effective, scalable, and accessible data storage and analysis.
- The integration of advanced data analytics into EMS will provide companies with actionable insights to reduce emissions and optimize operations.
- Partnerships and collaborations between EMS providers and technology firms will accelerate the development of more innovative and customized solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations
Governments worldwide are enforcing stricter emissions standards, compelling industries to adopt advanced emission monitoring systems to ensure compliance and avoid penalties. This regulatory pressure is especially strong in North America and Europe, where environmental laws are particularly rigorous.
Technological Advancements in EMS
The integration of IoT, AI, and cloud computing into emission monitoring systems is enhancing real-time data collection, analysis, and reporting capabilities. These innovations make EMS solutions more accurate, efficient, and easier to integrate, driving broader adoption across industries.
Corporate Sustainability and Net-Zero Initiatives
Increasing pressure from stakeholders and the public for companies to demonstrate environmental responsibility is pushing organizations to invest in EMS. Many large corporations are setting net-zero targets and require robust monitoring systems to track and report their emissions reductions.
Government Incentives and Support
Many governments are offering tax breaks, grants, and subsidies to encourage the adoption of emission monitoring technologies. These incentives help offset high initial implementation costs, making EMS more accessible, especially for small and medium-sized enterprises.
Industrial Expansion in Emerging Markets
Rapid industrialization in Asia Pacific, particularly in China and India, is leading to increased emissions and stricter local regulations. This is driving significant demand for EMS solutions in these fast-growing economies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of Emission Monitoring System (EMS) Market?
What factors are driving the Emission Monitoring System (EMS) Market?
What are some challenges faced by the Emission Monitoring System (EMS) Market?
Who are the major players in the Emission Monitoring System (EMS) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Continuous Emission Monitoring System (CEMS)
- 1.2.2 Predictive Emission Monitoring System (PEMS)
- 1.3 By End-Use
- 1.3.1 Oil & Gas
- 1.3.2 Metals & Mining
- 1.3.3 Power Generation
- 1.3.4 Chemical & Fertilizer
- 1.3.5 Pulp & Paper
- 1.3.6 Pharmaceutical
- 1.3.7 Others
- 1.4 By Component
- 1.4.1 Hardware
- 1.4.2 Software
- 1.4.3 Services
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,350 million → 2032: USD 8,796 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Emission Monitoring System (EMS) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Emission Monitoring System (EMS) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Emission Monitoring System (EMS) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Emission Monitoring System (EMS) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Emission Monitoring System (EMS) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Emission Monitoring System (EMS) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Emission Monitoring System (EMS) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Emission Monitoring System (EMS) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,350 million → 2032: USD 8,796 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Emission Monitoring System (EMS) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Continuous Emission Monitoring System (CEMS)
- 12.3.7.2 Predictive Emission Monitoring System (PEMS)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oil & Gas
- 12.4.7.2 Metals & Mining
- 12.4.7.3 Power Generation
- 12.4.7.4 Chemical & Fertilizer
- 12.4.7.5 Pulp & Paper
- 12.4.7.6 Pharmaceutical
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Component - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hardware
- 12.5.7.2 Software
- 12.5.7.3 Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Emission Monitoring System (EMS) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Emission Monitoring System (EMS) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Emission Monitoring System (EMS) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Emission Monitoring System (EMS) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ametek, Inc.
- 18.4 Emerson Electric Company
- 18.5 General Electric Company
- 18.6 Enviro Technology Services Plc.
- 18.7 Horiba Ltd.
- 18.8 Fuji Electric Co., Ltd.
- 18.9 Rockwell Automation, Inc.
- 18.10 Siemens AG
- 18.11 Thermo Fisher Scientific Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

