
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Energy System OT Cybersecurity Market Size 2024 | USD 5,450 million |
| Energy System OT Cybersecurity Market, CAGR | 9.3% |
| Energy System OT Cybersecurity Market Size 2032 | USD 11,101 million |
Market Overview:
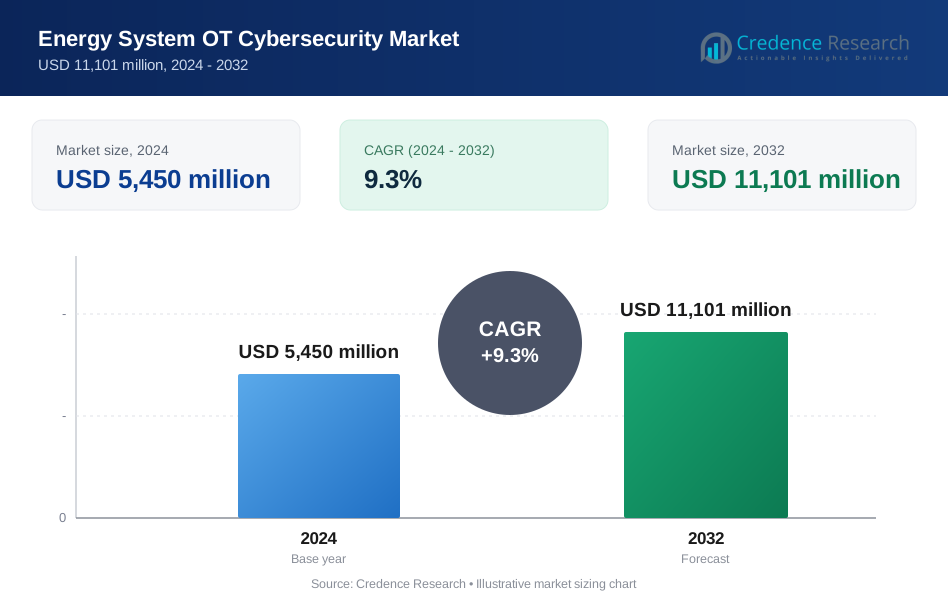
Energy System OT Cybersecurity Market size was valued at USD 5,450 million in 2024 and is anticipated to reach USD 11,101 million by 2032, at a CAGR of 9.3% during the forecast period (2024-2032).
Key market drivers include the growing complexity of energy infrastructure, increased regulatory scrutiny, and the emergence of advanced persistent threats (APTs). National security concerns and incidents such as ransomware attacks on power grids and oil pipelines have accelerated investment in cybersecurity frameworks across the energy sector. Additionally, the shift towards decentralized energy systems and the integration of renewable energy sources create new vulnerabilities in OT networks, demanding resilient and adaptive security architectures. Vendors are responding with solutions tailored to asset management, real-time threat detection, and incident response, which are now being embedded into control systems by default. The growing adoption of zero-trust security models and AI-based anomaly detection tools is reinforcing proactive defense mechanisms. Governments are also collaborating with private sector firms to establish national-level cybersecurity standards for energy systems.
Regionally, North America holds the largest market share due to early adoption of cybersecurity policies, substantial investments in energy modernization, and high awareness of OT vulnerabilities. Europe follows closely, driven by strong regulatory mandates under frameworks like NIS2 and the EU Cybersecurity Act. Asia Pacific is the fastest-growing region, fueled by rapid infrastructure development, increasing power demand, and emerging smart grid initiatives in China, India, and Southeast Asia. Meanwhile, Latin America and the Middle East are witnessing growing adoption as regional utilities enhance grid resilience. Africa shows gradual uptake, primarily in urbanized energy projects and donor-supported digital security programs. Public-private partnerships and regional cybersecurity roadmaps are supporting expansion across emerging markets. Demand for localized cybersecurity services and multilingual threat intelligence tools is also increasing in diverse regional markets.
Market Insights:
- The Energy System OT Cybersecurity Market was valued at USD 5,450 million in 2024 and is projected to reach USD 11,101 million by 2032, growing at a CAGR of 9.3% during the forecast period.
- Increasing cyberattacks on critical infrastructure and the rise of advanced persistent threats (APTs) are driving urgent cybersecurity investments across the energy sector.
- Regulatory mandates such as NERC CIP in North America and NIS2 in Europe are pushing energy providers to adopt robust OT security frameworks.
- Smart grid adoption and digital energy infrastructure are expanding the attack surface, boosting demand for AI-based monitoring and threat detection tools.
- Integration of decentralized energy systems and renewables introduces new vulnerabilities, requiring tailored cybersecurity solutions for remote and distributed assets.
- Legacy OT systems without modern security features present implementation challenges, especially where standardization and interoperability are lacking.
- North America holds the largest market share at 36%, followed by Europe at 29%, while Asia Pacific leads in growth due to infrastructure expansion and rising power demand.
Market Drivers:
Rising Cyber Threats and Vulnerabilities in Critical Infrastructure:
The growing sophistication and frequency of cyberattacks targeting energy infrastructure remain a key driver for the Energy System OT Cybersecurity Market. Threat actors are increasingly focusing on operational technology systems, which lack the mature security frameworks found in traditional IT environments. Incidents such as ransomware attacks on power grids and pipeline operators have highlighted vulnerabilities and triggered urgent responses from both government and industry. Organizations are prioritizing investments in cybersecurity to protect assets, maintain operational continuity, and ensure public safety. Attackers are exploiting legacy systems and outdated protocols that are prevalent in the energy sector. This escalating threat landscape is compelling utilities to modernize their cybersecurity strategies.
Regulatory Pressure and National Security Priorities Elevate Cyber Defense Investment:
Governments are mandating stricter compliance with cybersecurity regulations to safeguard critical infrastructure, which significantly drives the market forward. Regulatory frameworks such as NERC CIP in North America and NIS2 in Europe enforce minimum cybersecurity standards and reporting obligations for operators. These mandates push energy providers to adopt robust OT cybersecurity measures or face penalties. The Energy System OT Cybersecurity Market benefits from government funding initiatives and public-private collaborations aimed at building secure energy ecosystems. National security priorities are also aligned with OT cybersecurity, particularly as geopolitical tensions raise concerns about foreign interference in critical infrastructure. Organizations are expected to continuously assess and strengthen their cyber defense capabilities.
- For instance, the U.S. Department of Energy (DOE) established the Office of Cybersecurity, Energy Security, and Emergency Response (CESER) to coordinate national efforts in protecting critical energy assets, and recently announced a major investment in cybersecurity research to advance innovative solutions for the sector.
Digitalization and Smart Grid Adoption Increase Attack Surfaces:
Smart grid technologies and IIoT integration in energy systems have significantly expanded the number of endpoints and communication links, increasing cybersecurity risks. The Energy System OT Cybersecurity Market responds to these changes by delivering solutions that protect highly distributed and interconnected systems. Utilities are deploying real-time monitoring tools and anomaly detection systems to manage the growing complexity of digital operations. Cloud-based SCADA systems and remote-control functionalities, while enabling operational efficiency, create new vectors for cyber threats. This shift toward digital energy infrastructure demands agile, scalable, and continuous security management frameworks. Industry stakeholders are investing in tools that offer full visibility and threat mitigation across OT environments.
- For instance, a major North American utility company successfully mitigated a sophisticated cyber-attack on its smart grid infrastructure by leveraging a multi-layered cybersecurity strategy, including real-time monitoring, AI-driven threat detection, and advanced encryption.
Decentralized Energy Systems and Renewables Introduce New Cybersecurity Challenges:
The global transition toward decentralized power generation and renewable energy introduces a fragmented and less predictable network architecture. It poses significant cybersecurity challenges due to inconsistent protection levels across distributed assets. The Energy System OT Cybersecurity Market addresses these issues by delivering tailored solutions for microgrids, solar farms, and wind turbines. Operators must secure not only central systems but also endpoints located in remote or less regulated environments. Interoperability requirements across various vendors and technologies complicate cybersecurity enforcement. Real-time data exchange between edge devices and central command systems requires encryption, authentication, and constant validation. Companies are focusing on securing renewable energy assets to preserve energy reliability and prevent data breaches.
Market Trends:
Integration of AI and Machine Learning for Proactive Threat Detection:
The adoption of artificial intelligence (AI) and machine learning (ML) is a defining trend in the Energy System OT Cybersecurity Market. These technologies enhance threat detection by analyzing large volumes of operational data in real time and identifying anomalies that may indicate malicious activity. AI-powered systems can detect unknown threats faster than traditional rule-based models, which improves incident response and minimizes downtime. Vendors are incorporating ML algorithms into OT security platforms to automate risk assessment and continuously adapt to evolving attack patterns. It supports predictive analytics that helps operators prevent breaches before they occur. The ability to generate actionable insights from historical and real-time data positions AI-driven tools as a core element of cybersecurity strategies.
- For instance, Darktrace’s AI-powered OT cybersecurity platform uses self-learning AI to establish a baseline of normal operations and detect deviations in real time, enabling organizations to identify and respond to threats across both IT and OT environments without disrupting productivity.
Convergence of IT and OT Networks Necessitates Unified Security Architecture:
The growing convergence of IT and OT environments is reshaping security requirements, prompting a shift toward integrated cybersecurity frameworks. In the Energy System OT Cybersecurity Market, organizations are adopting unified platforms that protect both enterprise IT systems and operational infrastructure. This convergence increases the complexity of managing access controls, identity management, and threat visibility across traditionally separate domains. It drives demand for centralized security operations centers (SOCs) capable of overseeing both IT and OT ecosystems. Companies are investing in solutions that enable secure data flow between production systems and enterprise applications without compromising operational reliability. The need for end-to-end visibility, combined with regulatory pressure, reinforces the trend toward holistic cybersecurity management.
- For instance, Fortinet’s Security Fabric platform provides integrated cybersecurity solutions for both IT and OT environments, enabling organizations to achieve unified visibility, automated threat detection, and secure connectivity across critical infrastructure.
Market Challenges Analysis:
Complexity of Legacy Systems and Lack of Standardization Hinder Security Implementation:
Many energy infrastructures still operate on legacy OT systems that were never designed with cybersecurity in mind. These outdated platforms often lack encryption, access control, and basic network security features, making them highly vulnerable to modern threats. The Energy System OT Cybersecurity Market faces challenges in integrating advanced security tools with aging systems without disrupting critical operations. A lack of standardization across vendors and equipment types further complicates implementation, requiring custom configurations and increasing costs. Limited interoperability among devices reduces the effectiveness of centralized monitoring and control. Organizations must navigate technical and logistical barriers to build secure yet functional networks.
- For instance, Schneider Electric has worked closely with customers, national authorities, and OEMs to remediate improperly configured legacy OT systems, detect unprotected web management interfaces, and implement mitigation activities-demonstrating that legacy environments can be strengthened through coordinated action and secure-by-design processes.
Shortage of Skilled Workforce and Budget Constraints Limit Progress:
A significant barrier to growth in the Energy System OT Cybersecurity Market is the shortage of professionals with both OT and cybersecurity expertise. Bridging the skills gap is difficult because most cybersecurity training focuses on IT environments, leaving OT-specific threats and protocols under-addressed. Budget limitations within public utilities and small energy providers slow the adoption of comprehensive security programs. Organizations often delay upgrades due to high upfront costs and operational disruption risks. This reluctance creates security gaps and extends exposure windows. Without targeted investments in workforce development and financial planning, it remains difficult to implement scalable, long-term cybersecurity strategies.
Market Opportunities:
Growing Demand for Cybersecurity in Renewable and Decentralized Energy Networks:
The expansion of renewable energy and decentralized power systems presents a strong opportunity for the Energy System OT Cybersecurity Market. Solar farms, wind turbines, and microgrids require secure communication between distributed assets and central control systems. These systems often operate in remote or lightly protected environments, increasing the need for embedded cybersecurity solutions. The market can expand by offering lightweight, scalable security tools tailored for edge devices and field-level operations. Governments and energy providers are prioritizing security to support the resilience of green energy infrastructure. Vendors that provide flexible and interoperable cybersecurity platforms will be well-positioned to serve this growing demand.
Advancement of AI and Cloud-Based Cybersecurity Solutions Drives Adoption:
The rapid development of AI-driven cybersecurity tools and cloud-based platforms opens new growth avenues. The Energy System OT Cybersecurity Market can leverage these technologies to deliver real-time threat detection, predictive maintenance, and automated response. Cloud-enabled platforms offer scalable protection for energy providers with geographically dispersed assets. Companies are adopting these solutions to gain visibility, streamline incident response, and reduce reliance on on-site IT resources. AI-powered analytics also enable smarter risk management and resource allocation. The ability to integrate these tools with existing infrastructure makes them attractive across both developed and emerging energy markets.
Market Segmentation Analysis:
By Type
The Energy System OT Cybersecurity Market includes two primary segments: solutions and services. The solutions segment leads the market, driven by high demand for tools such as firewalls, intrusion detection systems, antivirus software, and identity access management tailored for OT environments. These tools enable real-time threat prevention and secure communication between operational assets. The services segment is expanding as organizations seek expert guidance for risk assessments, system integration, and managed security operations. Rising cyber threats and limited internal expertise are pushing utilities and energy providers to engage third-party service providers. Both segments are critical in building a layered cybersecurity strategy.
By Deployment
The market is categorized into on-premise and cloud deployment models. On-premise deployment holds the larger share due to the high sensitivity of OT systems, which require low-latency, uninterrupted access and strict control over data. It remains the preferred choice for operators managing critical infrastructure assets like substations and power plants. The cloud segment is expanding rapidly, supported by the need for centralized monitoring and scalable protection across geographically dispersed assets. Cloud-based platforms enable remote diagnostics, automated updates, and continuous monitoring, making them ideal for modern, distributed energy systems.
By End-User
End-users in the Energy System OT Cybersecurity Market include utilities, oil and gas companies, and renewable energy providers. Utilities dominate this segment due to their broad infrastructure networks and regulatory obligations. Oil and gas operators are adopting robust OT cybersecurity measures to protect pipelines, refineries, and drilling sites from growing threats. Renewable energy providers form the fastest-growing end-user group, driven by the proliferation of decentralized energy systems and the cybersecurity challenges of managing solar farms, wind turbines, and microgrids. Each end-user group requires tailored solutions to address sector-specific risks and operational complexities.
Segmentations:
By Type
- Network Security
- Application Security
- Endpoint Security
- Data Encryption
- Identity and Access Management
- Firewall
- Intrusion Detection System (IDS)/Intrusion Prevention System (IPS)
- Antivirus/Antimalware
- Risk and Compliance Management
- Security Information and Event Management (SIEM)
- Others
By Deployment
- On-Premise
- Cloud
By End-User
- Power Generation
- Transmission and Distribution (T&D)
- Oil and Gas
- Renewable Energy
- Water Utilities
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America Leads Due to Strong Regulatory Framework and Early Adoption
North America holds 36% of the global Energy System OT Cybersecurity Market, maintaining its lead due to advanced regulatory compliance and early technology integration. The region enforces strong standards through organizations like the North American Electric Reliability Corporation (NERC) and the Department of Energy, compelling utilities to prioritize cybersecurity investments. High-profile cyber incidents involving power infrastructure have driven rapid implementation of defense systems. Utilities in the U.S. and Canada deploy real-time monitoring, intrusion detection, and network segmentation to secure critical assets. The presence of top cybersecurity vendors and active collaboration with government agencies further strengthens the regional ecosystem. Energy operators continue to adopt zero-trust models and AI-based threat detection to manage operational risks.
Europe Advances with Regulatory Mandates and Energy Transition Goals
Europe accounts for 29% of the global Energy System OT Cybersecurity Market, supported by regulatory enforcement and clean energy expansion. The NIS2 Directive and EU Cybersecurity Act impose uniform cybersecurity standards across energy networks in member states. Countries such as Germany, France, and the Netherlands are securing smart grids, substations, and renewable energy projects through mandated risk assessments and incident response planning. Public funding and industry partnerships enable the deployment of secure communication and control systems across utility networks. The rollout of digital substations and cross-border energy exchanges increases exposure, requiring robust OT security. Organizations invest in compliance tools, endpoint protection, and advanced analytics to meet evolving cyber risk demands.
Asia Pacific Emerges as Fastest-Growing Market Due to Infrastructure Expansion
Asia Pacific holds 22% of the global Energy System OT Cybersecurity Market and shows the fastest growth due to widespread energy infrastructure development. Countries like China, India, Japan, and South Korea are modernizing power grids and increasing reliance on smart energy technologies. This growth drives demand for cybersecurity solutions that protect remote assets, decentralized systems, and IIoT deployments. Governments are introducing cybersecurity policies and expanding digital protection across national grids. Energy operators face complex environments with a mix of legacy systems and new technologies, prompting them to adopt scalable, cloud-based security frameworks. Vendors are capitalizing on regional demand by offering integrated solutions tailored for real-time monitoring and compliance.
Key Player Analysis:
- AT&T
- Schneider Electric
- Schweitzer Engineering Laboratories, Inc.
- Accenture
- Siemens
- ABB
- IBM Corporation
- General Electric
- Hitachi Energy Ltd.
- Eaton Corporation plc
Competitive Analysis:
The Energy System OT Cybersecurity Market exhibits intense competition, driven by escalating cyber threats and the digital transformation of critical infrastructure. Major players such as Siemens, ABB, Schneider Electric, IBM, and Accenture leverage their industrial expertise and global reach to offer integrated security solutions. Specialized firms like Fortinet, Palo Alto Networks, and Cisco Systems focus on advanced threat detection and response capabilities tailored for operational technology environments. Companies including Schweitzer Engineering Laboratories, Hitachi Energy, and Eaton Corporation provide hardware-centric security solutions, enhancing resilience in energy systems. It continues to evolve rapidly, with key players investing in artificial intelligence and machine learning to improve threat detection and response times. Strategic partnerships and acquisitions remain common strategies to expand market presence and address emerging security challenges.
Recent Developments:
- In November 2024, Accenture launched new generative AI-powered cybersecurity services, including deepfake protection and quantum-safe data security solutions.
- In November 2023, AT&T announced the creation of a standalone managed cybersecurity services business, focusing on network-embedded security and managed detection and response for critical infrastructure, including energy systems.
- In April 2025, Schneider Electric enhanced its MSS offering with real-time ICS vulnerability tracking, expanded managed detection and response, and broader cybersecurity controls management tailored for OT environments, supporting compliance and operational resilience in industrial settings.
Market Concentration & Characteristics:
The Energy System OT Cybersecurity Market is moderately concentrated, with a mix of global industrial leaders and specialized cybersecurity firms. It is characterized by rapid innovation, driven by escalating cyber threats and the digitalization of energy infrastructure. Key players such as Siemens, ABB, Schneider Electric, IBM, and Accenture leverage their industrial expertise and global reach to offer integrated security solutions. Specialized firms like Fortinet, Palo Alto Networks, and Cisco Systems focus on advanced threat detection and response capabilities tailored for operational technology environments. The market's growth is propelled by increasing cyber threats targeting critical infrastructure, prompting energy companies to invest more in robust cybersecurity solutions. Strategic partnerships and acquisitions are common strategies to expand market presence and address emerging security challenges. The integration of artificial intelligence and machine learning into security solutions is enhancing threat detection and response times, further shaping the market's evolution.
Report Coverage:
The research report offers an in-depth analysis based on Type, Deployment, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The convergence of IT and OT systems will continue to expand the attack surface, necessitating integrated security frameworks that provide unified visibility and control across both domains.
- The adoption of AI-driven threat detection and response tools will become standard, enabling faster identification of anomalies and reducing response times to cyber incidents.
- Cloud-based security solutions will gain traction, offering scalable and flexible protection for distributed energy assets and facilitating centralized management.
- The proliferation of distributed energy resources (DERs) like solar panels and battery storage systems will introduce new vulnerabilities, requiring specialized cybersecurity measures tailored to these technologies.
- Regulatory bodies worldwide will implement stricter cybersecurity mandates for critical infrastructure, compelling energy providers to enhance their security postures and compliance efforts.
- The shortage of skilled cybersecurity professionals will drive the demand for automated security solutions and managed security services to bridge the expertise gap.
- Investments in cybersecurity research and development will increase, focusing on developing resilient architectures and advanced defense mechanisms against sophisticated threats.
- Collaborations between governments and private sectors will intensify, aiming to share threat intelligence and develop standardized security protocols for the energy sector.
- The integration of cybersecurity considerations into the design phase of energy systems will become a best practice, promoting a proactive approach to security.
- Emerging technologies such as quantum computing and blockchain will be explored for their potential to enhance the security and integrity of energy system operations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Cyber Threats and Vulnerabilities in Critical Infrastructure
The increasing frequency and sophistication of cyberattacks targeting energy infrastructure, including ransomware and advanced persistent threats, are compelling utilities and energy providers to invest heavily in OT cybersecurity solutions to protect operational continuity and public safety.
Regulatory Pressure and National Security Priorities
Stricter government mandates such as NERC CIP in North America and NIS2 in Europe require energy operators to implement robust cybersecurity frameworks, driving market growth as organizations seek compliance and avoid penalties.
Digitalization and Smart Grid Adoption
The expansion of smart grids, IIoT, and digital energy infrastructure is increasing the number of endpoints and communication links, thereby expanding the attack surface and boosting demand for advanced, real-time monitoring and AI-based threat detection tools.
Decentralized Energy Systems and Renewables
The integration of decentralized power generation and renewable energy sources introduces new vulnerabilities across distributed assets, necessitating tailored cybersecurity solutions for remote and less regulated environments.
Convergence of IT and OT Networks
The merging of IT and OT environments in energy systems requires unified security architectures and centralized management, increasing demand for integrated cybersecurity platforms that provide end-to-end visibility and control.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size and future outlook of the Energy System OT Cybersecurity Market?
What is driving the growth of the Energy System OT Cybersecurity Market?
Why is there increased demand for OT cybersecurity in energy systems?
What technologies are shaping the future of this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Network Security
- 1.2.2 Application Security
- 1.2.3 Endpoint Security
- 1.2.4 Data Encryption
- 1.2.5 Identity and Access Management
- 1.2.6 Firewall
- 1.2.7 Intrusion Detection System (IDS)/Intrusion Prevention System (IPS)
- 1.2.8 Antivirus/Antimalware
- 1.2.9 Risk and Compliance Management
- 1.2.10 Security Information and Event Management (SIEM)
- 1.2.11 Others
- 1.3 By End-User
- 1.3.1 Power Generation
- 1.3.2 Transmission and Distribution (T&D)
- 1.3.3 Oil and Gas
- 1.3.4 Renewable Energy
- 1.3.5 Water Utilities
- 1.3.6 Others
- 1.4 By Deployment
- 1.4.1 On-Premise
- 1.4.2 Cloud
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,450 million → 2032: USD 11,101 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Energy System OT Cybersecurity Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Energy System OT Cybersecurity Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Energy System OT Cybersecurity Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Energy System OT Cybersecurity Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Energy System OT Cybersecurity Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Energy System OT Cybersecurity Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Energy System OT Cybersecurity Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Energy System OT Cybersecurity Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,450 million → 2032: USD 11,101 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Energy System OT Cybersecurity Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Network Security
- 12.3.7.2 Application Security
- 12.3.7.3 Endpoint Security
- 12.3.7.4 Data Encryption
- 12.3.7.5 Identity and Access Management
- 12.3.7.6 Firewall
- 12.3.7.7 Intrusion Detection System (IDS)/Intrusion Prevention System (IPS)
- 12.3.7.8 Antivirus/Antimalware
- 12.3.7.9 Risk and Compliance Management
- 12.3.7.10 Security Information and Event Management (SIEM)
- 12.3.7.11 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Power Generation
- 12.4.7.2 Transmission and Distribution (T&D)
- 12.4.7.3 Oil and Gas
- 12.4.7.4 Renewable Energy
- 12.4.7.5 Water Utilities
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-Premise
- 12.5.7.2 Cloud
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Energy System OT Cybersecurity End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Energy System OT Cybersecurity Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Energy System OT Cybersecurity Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Energy System OT Cybersecurity Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Siemens
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ABB
- 18.4 Schneider Electric
- 18.5 IBM Corporation
- 18.6 Accenture
- 18.7 General Electric
- 18.8 Hitachi Energy Ltd.
- 18.9 Eaton Corporation plc
- 18.10 Schweitzer Engineering Laboratories, Inc.
- 18.11 AT&T
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

