
Market overview
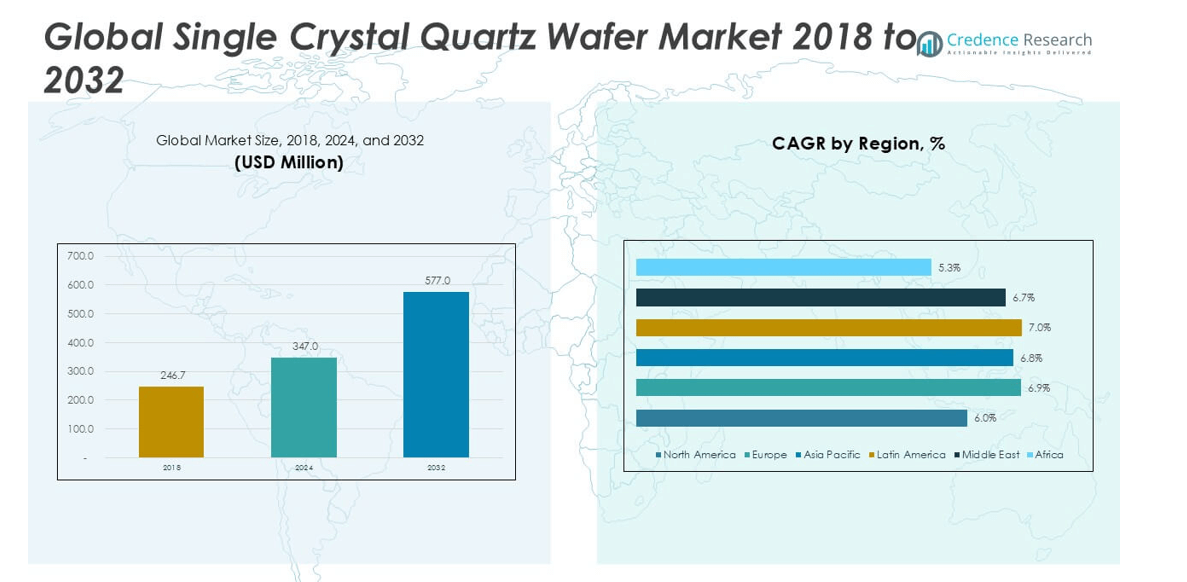
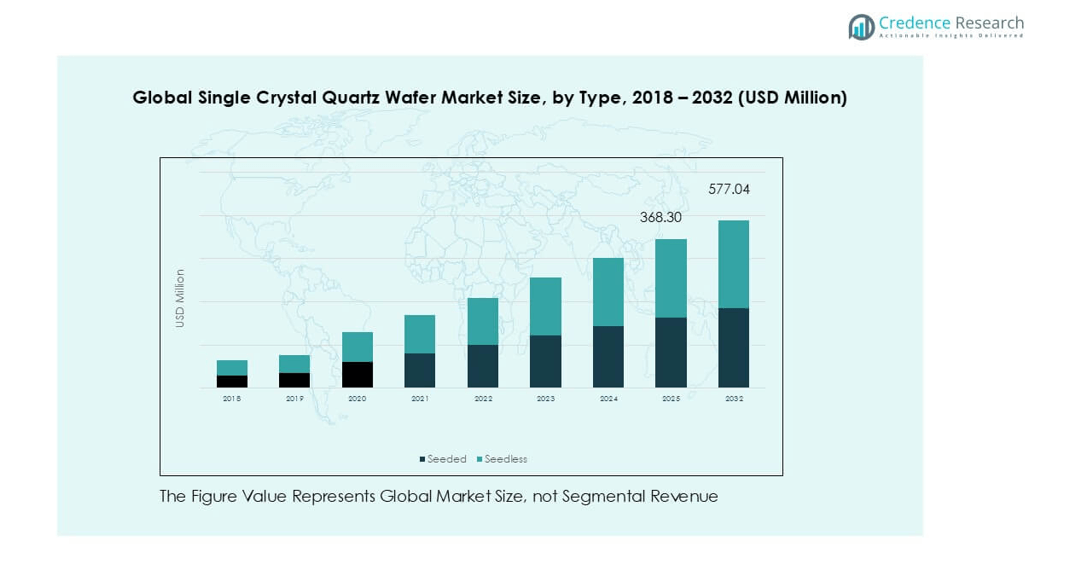
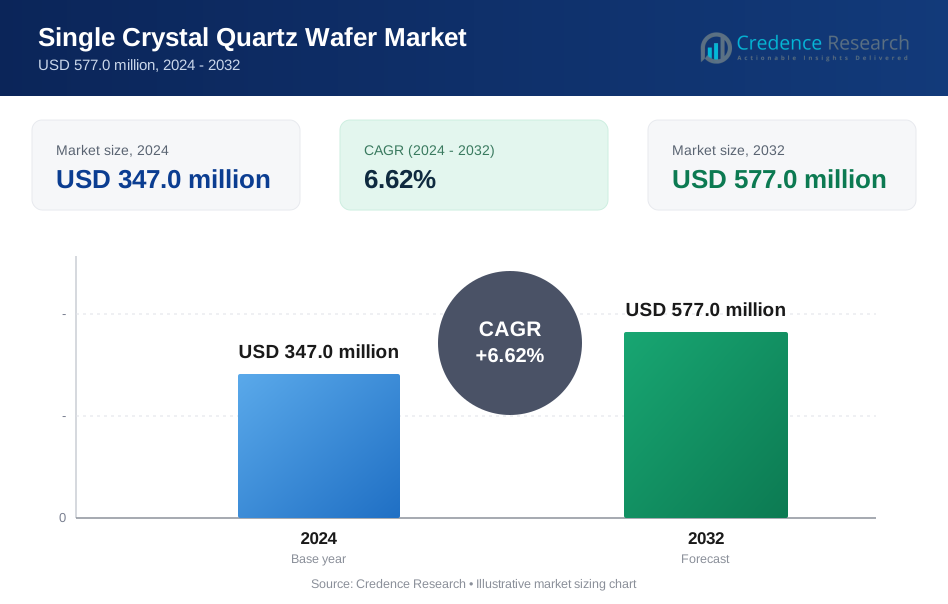
The global single crystal quartz wafer market size was valued at USD 246.7 million in 2018, growing to USD 347.0 million in 2024, and is anticipated to reach USD 577.0 million by 2032, at a CAGR of 6.62% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Single Crystal Quartz Wafer Market Size 2025 | USD 347.0 million |
| Single Crystal Quartz Wafer Market, CAGR | 6.62% |
| Single Crystal Quartz Wafer Market Size 2032 | USD 577.0 million |
The global single crystal quartz wafer market is led by established players including Corning Incorporated, NIHON DEMPA KOGYO CO., LTD., Semiconductor Wafer, Inc., MTI Corporation, Hangzhou Freqcontrol Electronic Technology Ltd., Xiamen Powerway, MicroChemicals GmbH, INSACO, Inc., and Vritra Technologies. These companies hold strong positions through advanced manufacturing capabilities, extensive product portfolios, and regional expansion strategies. Asia Pacific leads the market with a 34% share in 2024, driven by robust semiconductor and electronics manufacturing in China, Japan, South Korea, and Taiwan. Europe follows with 27%, supported by automotive and biotechnology applications, while North America holds 21%, underpinned by semiconductor R&D and MEMS adoption.
Market Insights
- The global single crystal quartz wafer market was valued at USD 246.7 million in 2018, reached USD 347.0 million in 2024, and is projected to hit USD 577.0 million by 2032, at a CAGR of 6.62%.
- Growth is driven by rising demand in semiconductors, MEMS devices, and biotechnology, where seeded wafers dominate with over 60% share due to their superior crystalline quality and defect control.
- Key trends include adoption of larger-diameter wafers (5–8 inches holding over 50% share) to support advanced IC packaging and higher yields, alongside increasing use in 5G electronics and microfluidic biotechnology platforms.
- The market is moderately consolidated, with players such as Corning Incorporated, NIHON DEMPA KOGYO, MTI Corporation, and Hangzhou Freqcontrol leading, while regional firms strengthen their presence through cost-effective production and strategic expansion.
- Regionally, Asia Pacific leads with 34% share, followed by Europe at 27% and North America at 21%, while Latin America, Middle East, and Africa collectively contribute around 18%.
Market Segmentation Analysis:
By Type
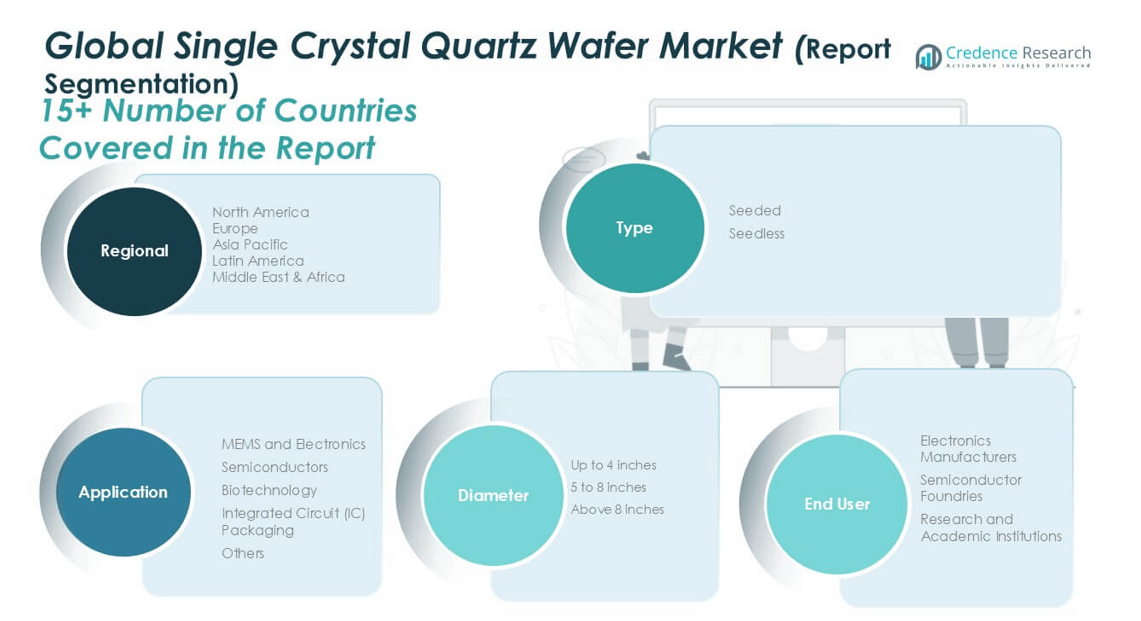
The seeded quartz wafer segment dominated the global single crystal quartz wafer market in 2024, holding over 60% share. Its leadership is driven by superior crystalline quality, uniform lattice structure, and high precision required in semiconductor manufacturing and MEMS devices. Seeded wafers are widely adopted due to their ability to maintain structural stability and reduce defect density, which is critical for advanced electronics. In contrast, seedless wafers, though cost-effective, remain limited to niche applications where ultra-high precision is not essential. Continuous growth in electronics miniaturization further strengthens demand for seeded wafers.
- For instance, Shin-Etsu Chemical is a producer of high-purity synthetic quartz wafers, including 200 mm sizes, used in the electronics and semiconductor industry. These materials are recognized for their excellent properties, such as thermal resistance and high light transmission. As a leading supplier of materials like photomask blanks, the company emphasizes defect-free products to ensure high-quality semiconductor manufacturing.
By Diameter
The 5 to 8 inches segment accounted for the largest share, representing over 50% of the market in 2024. This dominance stems from their balance of cost efficiency and compatibility with advanced semiconductor processes. These wafers are extensively used in MEMS fabrication, IC packaging, and next-generation electronics, where larger diameters support higher production yields and reduce overall costs per unit. The up to 4 inches segment serves legacy systems and specialized applications, while above 8 inches is emerging as demand grows for high-capacity semiconductor devices and advanced electronics manufacturing.
- For instance, Sumitomo Electric is a major player in the development and manufacturing of MEMS devices, including gyroscopes. The company leverages its expertise in wafer technology and mass production processes to produce high-quality sensors.
By Application
MEMS and electronics applications held the dominant position, contributing more than 35% share of the market in 2024. The segment’s leadership is supported by rising adoption of sensors, actuators, and RF devices across smartphones, automotive systems, and industrial equipment. Quartz wafers provide excellent thermal stability, frequency control, and durability, making them essential for MEMS production. Semiconductor and IC packaging applications are also expanding due to growing demand for miniaturized and high-performance chips. Meanwhile, biotechnology uses quartz wafers for diagnostic and microfluidic applications, adding niche growth opportunities for market participants.
Market Overview
Rising Demand in Semiconductor Manufacturing
The semiconductor industry is the largest growth driver for the single crystal quartz wafer market, accounting for consistent demand from advanced electronics, microchips, and integrated circuits. Quartz wafers provide superior crystalline purity, thermal stability, and low defect density, making them essential for achieving high yield in semiconductor fabrication. As global demand for computing power accelerates with AI, cloud infrastructure, and high-performance devices, quartz wafers serve as a critical material for ensuring efficiency in transistor scaling. The introduction of advanced nodes below 5 nm, coupled with large-scale investments by companies such as TSMC, Intel, and Samsung, continues to expand wafer consumption. Furthermore, the growth of consumer electronics and automotive electronics sustains this demand, particularly for power semiconductors and RF components.
- For instance, Intel's Fab 34 in Leixlip, Ireland, began high-volume manufacturing of its Intel 4 process technology using Extreme Ultraviolet (EUV) lithography in September 2023. Advanced manufacturing facilities like Fab 34 rely on highly sophisticated photomasks. The photomasks used in EUV lithography are reflective, and consist of a patterned absorber layer (typically tantalum-based) on top of a multilayer mirror stack of molybdenum and silicon, all built on a low-thermal expansion glass substrate.
Expansion of MEMS and Sensor Applications
The growth of micro-electromechanical systems (MEMS) is significantly boosting quartz wafer adoption, particularly for sensors in consumer electronics, automotive safety systems, and industrial automation. MEMS devices, such as accelerometers, gyroscopes, and pressure sensors, require high-quality quartz wafers for accurate signal processing and stability under diverse conditions. The rising integration of MEMS into smartphones, wearables, and IoT-enabled devices has created steady demand for wafer substrates with exceptional frequency stability and durability. Automotive demand, especially for ADAS and autonomous driving features, is another major driver, as quartz-based MEMS ensure safety-critical precision. The expansion of 5G networks and edge computing further supports MEMS adoption in RF filters and resonators. Companies are investing in wafer innovation to meet miniaturization requirements, which positions quartz wafers as a critical enabler of next-generation MEMS technology.
- For instance, Bosch Sensortec shipped over 1 billion MEMS sensors in 2024, and the sensors are most commonly built on silicon.
Increasing Use in Biotechnology and Life Sciences
Biotechnology has emerged as a new growth avenue for single crystal quartz wafers, driven by their use in diagnostic platforms, microfluidic chips, and biosensors. Quartz wafers provide superior optical clarity, chemical inertness, and resistance to bio-contaminants, making them ideal for life sciences research and clinical applications. Growing demand for point-of-care diagnostics, lab-on-chip devices, and DNA sequencing platforms fuels the adoption of quartz wafers in healthcare innovation. As healthcare systems worldwide expand investments in molecular diagnostics and precision medicine, quartz wafers play an essential role in developing miniaturized platforms with high analytical accuracy. The post-pandemic shift toward rapid testing and personalized diagnostics further accelerates their relevance. Biotechnology companies increasingly integrate quartz substrates to enhance device reliability and support advanced imaging. This convergence of healthcare and material science positions quartz wafers as a key growth enabler, expanding beyond electronics into a high-value, long-term opportunity.
Key Trends & Opportunities
Adoption of Larger-Diameter Quartz Wafers
A key trend shaping the market is the shift toward larger-diameter wafers, particularly 6-inch and 8-inch sizes, which enable higher throughput and improved cost efficiency. Semiconductor manufacturers are increasingly demanding larger wafer sizes to maximize output per production cycle and reduce defects in mass manufacturing. This transition is supported by advancements in crystal growth and precision-cutting technologies that ensure consistent wafer quality at larger diameters. As demand for high-performance devices grows across AI chips, memory devices, and advanced IC packaging, the adoption of larger quartz wafers creates opportunities for suppliers. Manufacturers investing in capacity expansion and high-purity production technologies are well-positioned to capture this trend.
- For instance, Shin-Etsu Chemical, a major supplier of semiconductor materials, produces 200 mm (8-inch) single-crystal silicon wafers. These wafers are manufactured with extremely low dislocation densities and other defect controls to maximize the number of functioning integrated circuit (IC) dies per wafer.
Integration into 5G and Advanced Electronics
The expansion of 5G networks and advanced electronics creates new opportunities for quartz wafer adoption in RF filters, oscillators, and resonators. Quartz wafers provide excellent frequency stability and low acoustic loss, which are critical for ensuring high data transfer speeds and reliability in 5G-enabled devices. Consumer demand for smartphones, IoT platforms, and connected vehicles further drives the integration of quartz-based components. This trend is amplified by ongoing miniaturization requirements, as wafers enable smaller, more efficient components without compromising performance. As telecom operators and electronics OEMs accelerate 5G deployment worldwide, quartz wafer demand is expected to grow strongly. This creates opportunities for suppliers to expand their product portfolios toward high-frequency and precision-grade wafers, aligning with the evolving needs of the next-generation communication ecosystem.
Key Challenges
High Manufacturing Costs and Process Complexity
One of the primary challenges in the single crystal quartz wafer market is the high cost of production. Growing quartz crystals of high purity requires controlled hydrothermal synthesis, long growth cycles, and significant energy input. Additionally, cutting, polishing, and defect inspection processes are resource-intensive, increasing overall costs for manufacturers. The complexity of maintaining defect-free lattice structures limits yield and makes large-scale production challenging. These factors create pricing pressure, particularly as customers seek cost reductions in semiconductor and MEMS production. Smaller manufacturers struggle to compete due to high capital requirements, creating barriers to entry in the market. Unless advancements in process automation and material efficiency are realized, high costs will remain a limiting factor for widespread adoption.
Supply Chain Vulnerabilities and Limited Material Sources
Another major challenge lies in supply chain vulnerabilities and dependence on limited sources of high-purity quartz. The raw material for single crystal quartz wafers is available only in select geographic locations, making supply sensitive to geopolitical and trade-related disruptions. Any shortage or price fluctuations in raw quartz directly impact wafer costs and availability for downstream industries. In addition, reliance on specialized crystal growth equipment and technology further narrows the supplier base, creating risks of concentration. The increasing demand from semiconductors, MEMS, and biotechnology sectors has amplified concerns regarding supply security. To address this challenge, manufacturers must diversify sourcing strategies and invest in synthetic quartz alternatives. Without proactive measures, supply chain risks may hinder consistent market growth and restrict the ability of producers to meet rising global demand.
Regional Analysis
North America
North America held a significant share of the global single crystal quartz wafer market, valued at USD 53.74 million in 2018 and reaching USD 72.94 million in 2024. By 2032, it is projected to grow to USD 115.41 million, advancing at a CAGR of 6.0%. The region accounted for nearly 21% of the global market in 2024, supported by strong semiconductor manufacturing and MEMS applications in the United States. Increasing adoption of advanced IC packaging and high-performance electronics continues to drive demand, reinforcing North America’s position as a key market in this industry.
Europe
Europe represented a major market, valued at USD 66.08 million in 2018 and expanding to USD 94.59 million in 2024. By 2032, it is expected to reach USD 160.94 million, registering a CAGR of 6.9%. With around 27% market share in 2024, Europe’s growth is driven by robust semiconductor R&D, advanced manufacturing in Germany, and demand for MEMS in automotive safety systems. Strong adoption in biotechnology and microfluidics further supports expansion, positioning Europe as a leading hub for high-value quartz wafer applications across multiple industries.
Asia Pacific
Asia Pacific dominated the market with the largest share, valued at USD 84.41 million in 2018 and increasing to USD 119.90 million in 2024. By 2032, it is projected to reach USD 201.96 million, growing at a CAGR of 6.8%. The region captured nearly 34% of the market in 2024, led by major semiconductor manufacturing bases in China, Japan, South Korea, and Taiwan. Rising demand for electronics, 5G infrastructure, and MEMS-based devices continues to drive strong adoption. Investments by global foundries and regional electronics firms ensure Asia Pacific remains the growth leader.
Latin America
Latin America’s market stood at USD 21.96 million in 2018 and grew to USD 31.48 million in 2024. By 2032, it is forecasted to reach USD 53.66 million, with the fastest regional CAGR of 7.0%. Holding about 9% share in 2024, the region benefits from growing demand for consumer electronics and increasing adoption of semiconductor technologies in Brazil and Mexico. Rising integration of quartz wafers in automotive electronics and healthcare applications further fuels growth. Expansion of manufacturing facilities and favorable trade policies position Latin America as an emerging growth market.
Middle East
The Middle East market was valued at USD 11.79 million in 2018 and increased to USD 16.62 million in 2024. It is projected to reach USD 27.70 million by 2032, advancing at a CAGR of 6.7%. Representing nearly 5% market share in 2024, regional growth is supported by adoption of quartz wafers in defense electronics, telecommunications, and emerging semiconductor manufacturing. Investments in technology hubs, particularly in the UAE and Saudi Arabia, are gradually driving adoption. While smaller compared to leading regions, the Middle East demonstrates steady growth prospects.
Africa
Africa accounted for a smaller share, valued at USD 8.76 million in 2018 and reaching USD 11.52 million in 2024. By 2032, the market is expected to grow to USD 17.37 million, with a CAGR of 5.3%, the lowest among all regions. The region represented nearly 4% of the global market in 2024, primarily driven by demand in telecommunications and healthcare applications. Limited local semiconductor production constrains growth, but rising adoption of consumer electronics and gradual investments in technology infrastructure are creating niche opportunities for quartz wafer demand across Africa.
Market Segmentations:
By Type
- Seeded
- Seedless
By Diameter
- Up to 4 inches
- 5 to 8 inches
- Above 8 inches
By Application
- MEMS and Electronics
- Semiconductors
- Biotechnology
- Integrated Circuit (IC) Packaging
- Others
By End User
- Electronics Manufacturers
- Semiconductor Foundries
- Research and Academic Institutions
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The global single crystal quartz wafer market features a moderately consolidated competitive landscape, with both established multinational corporations and specialized regional players competing for market share. Key participants such as Corning Incorporated, NIHON DEMPA KOGYO CO., LTD., Semiconductor Wafer, Inc., and MTI Corporation dominate due to their advanced manufacturing capabilities, strong distribution networks, and consistent investments in R&D. These companies focus on improving wafer quality, increasing diameter sizes, and reducing defect density to meet evolving demands in semiconductors, MEMS, and biotechnology. Regional firms, including Hangzhou Freqcontrol Electronic Technology Ltd. and Xiamen Powerway, are gaining ground by offering cost-effective solutions and expanding production capacity to serve local markets in Asia. Niche players such as INSACO, Inc. and MicroChemicals GmbH support the ecosystem by specializing in customized materials and chemical solutions. Strategic partnerships, facility expansions, and innovations in hydrothermal growth technologies remain central to competition, as companies strive to balance cost efficiency with performance.
Key Player Analysis
- Hangzhou Freqcontrol Electronic Technology Ltd
- Semiconductor Wafer, Inc.
- MTI Corporation
- Corning Incorporated
- Vritra Technologies
- Xiamen Powerway
- MicroChemicals GmbH
- NIHON DEMPA KOGYO CO., LTD.
- INSACO, Inc.
- Hangzhou Freqcontrol Electronic Technology Ltd.
- Other Key Player
Recent Developments
- In July 2025, Xiamen Powerway (PAM-XIAMEN) remains an active supplier of single crystal quartz wafers, specializing in X-cut, Y-cut, Z-cut, and ST-cut orientations up to 3-inch diameters.
- In July 2025, NDK highlighted its advancement in mass-producing high-uniformity quartz crystals using proprietary technologies. Their latest offering includes synthetic quartz wafers with AT-cut and tuning fork wafers, and a development plan for larger 6-inch wafers to cater to growing SAW device demand and frequency control in next-gen electronics.
- In August 2024, NDK (NIHON DEMPA KOGYO CO., LTD.) showcased its synthetic quartz crystals and quartz wafers for timing and optical applications at electronica India 2024, participating through a distributor's booth at the trade fair.
Report Coverage
The research report offers an in-depth analysis based on Type, Diameter, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily with rising demand from semiconductor manufacturing.
- Seeded quartz wafers will continue to dominate due to superior crystalline quality.
- Larger-diameter wafers will gain adoption to improve yields and production efficiency.
- MEMS and sensor applications will drive long-term growth across electronics and automotive.
- Biotechnology will emerge as a stronger end-use segment through diagnostics and lab-on-chip devices.
- Asia Pacific will remain the largest regional market with strong manufacturing capacity.
- Europe will strengthen its position through automotive electronics and biotechnology innovations.
- North America will grow steadily, supported by semiconductor R&D and MEMS adoption.
- Competitive intensity will increase as regional players expand capacity and global players invest in R&D.
- Supply chain diversification and technological advancements will shape cost efficiency and long-term sustainability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand in Semiconductor Manufacturing
The semiconductor industry is the largest growth driver, as single crystal quartz wafers are essential for high-yield, defect-free fabrication of advanced microchips and integrated circuits. The push for smaller nodes and higher performance in computing, AI, and consumer electronics is accelerating wafer consumption globally.
Expansion of MEMS and Sensor Applications
The proliferation of MEMS devices in smartphones, automotive safety systems, and industrial automation is fueling demand for high-quality quartz wafers. Their thermal stability and frequency control are critical for sensors and actuators, especially as miniaturization and integration into IoT and 5G devices increase.
Adoption of Larger-Diameter Wafers
Manufacturers are shifting toward 5–8 inch and larger wafers to improve production yields and cost efficiency in semiconductor and MEMS fabrication. This trend is driven by the need for higher throughput and advanced IC packaging, creating opportunities for suppliers with advanced crystal growth capabilities.
Growth in Biotechnology and Life Sciences
Quartz wafers are increasingly used in diagnostic platforms, microfluidic chips, and biosensors due to their optical clarity and chemical inertness. The expansion of point-of-care diagnostics, lab-on-chip devices, and precision medicine is opening new, high-value applications for quartz wafers beyond traditional electronics.
Integration into 5G and Advanced Electronics
The rollout of 5G networks and next-generation electronics is boosting demand for quartz wafers in RF filters, oscillators, and resonators. Their frequency stability and low acoustic loss are vital for high-speed, reliable data transmission in modern communication devices.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Single Crystal Quartz Wafer market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Single Crystal Quartz Wafer market projected to grow between 2025 and 2032?
Which Global Single Crystal Quartz Wafer market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Single Crystal Quartz Wafer market?
Who are the leading companies in the Global Single Crystal Quartz Wafer market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Seeded
- 1.2.2 Seedless
- 1.3 By Diameter
- 1.3.1 Up to 4 inches
- 1.3.2 5 to 8 inches
- 1.3.3 Above 8 inches
- 1.4 By End User
- 1.4.1 Electronics Manufacturers
- 1.4.2 Semiconductor Foundries
- 1.4.3 Research and Academic Institutions
- 1.5 By Application
- 1.5.1 MEMS and Electronics
- 1.5.2 Semiconductors
- 1.5.3 Biotechnology
- 1.5.4 Integrated Circuit (IC) Packaging
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 347.0 million → 2032: USD 577.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Single Crystal Quartz Wafer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Single Crystal Quartz Wafer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Single Crystal Quartz Wafer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Single Crystal Quartz Wafer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Single Crystal Quartz Wafer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Single Crystal Quartz Wafer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Single Crystal Quartz Wafer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Single Crystal Quartz Wafer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 347.0 million → 2032: USD 577.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Single Crystal Quartz Wafer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Seeded
- 12.3.7.2 Seedless
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Diameter - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Up to 4 inches
- 12.4.7.2 5 to 8 inches
- 12.4.7.3 Above 8 inches
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electronics Manufacturers
- 12.5.7.2 Semiconductor Foundries
- 12.5.7.3 Research and Academic Institutions
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 MEMS and Electronics
- 12.6.7.2 Semiconductors
- 12.6.7.3 Biotechnology
- 12.6.7.4 Integrated Circuit (IC) Packaging
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Single Crystal Quartz Wafer End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Single Crystal Quartz Wafer Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Single Crystal Quartz Wafer Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Single Crystal Quartz Wafer Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Corning Incorporated
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 NIHON DEMPA KOGYO CO., LTD.
- 18.4 Semiconductor Wafer, Inc.
- 18.5 MTI Corporation
- 18.6 Hangzhou Freqcontrol Electronic Technology Ltd.
- 18.7 Xiamen Powerway
- 18.8 MicroChemicals GmbH
- 18.9 INSACO, Inc.
- 18.10 Vritra Technologies
- 18.11 Shin-Etsu Chemical
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

