
Market overview
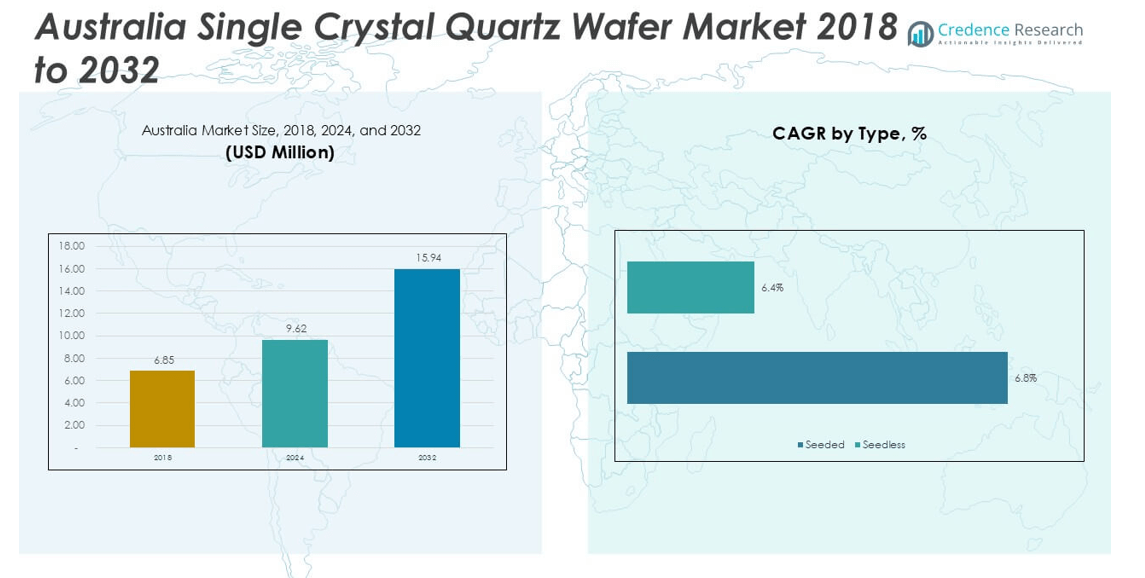
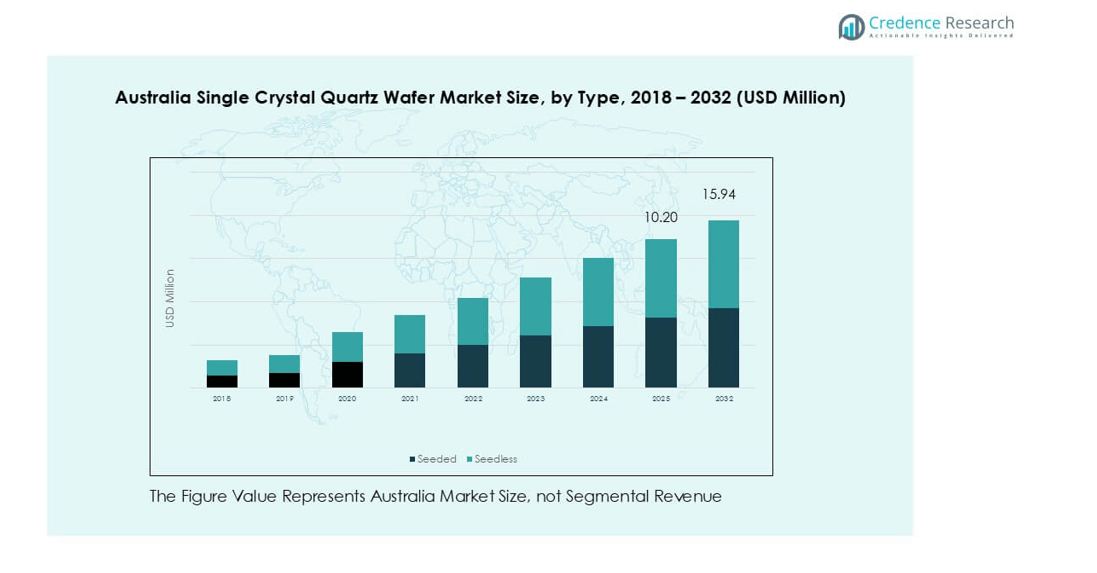
Australia Single Crystal Quartz Wafer market size was valued at USD 6.85 million in 2018, reached USD 9.62 million in 2024, and is anticipated to reach USD 15.94 million by 2032, at a CAGR of 6.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Single Crystal Quartz Wafer Market Size 2025 | USD 9.62 million |
| Australia Single Crystal Quartz Wafer Market, CAGR | 6.8% |
| Australia Single Crystal Quartz Wafer Market Size 2032 | USD 15.94 million |
The Australia single crystal quartz wafer market is shaped by leading players such as Jiaxing AOSITE Photonics Technology Co., Ltd., Semiconductor Wafer, Inc., MTI Corporation, Hangzhou Freqcontrol Electronic Technology Ltd., Ferrotec Global, MicroChemicals GmbH, NIHON DEMPA KOGYO CO., LTD., MSE Supplies Inc., and UniversityWafer, Inc. These companies compete through product quality, innovation, and partnerships with local distributors and research institutions. Regionally, New South Wales (NSW) leads the market with over 35% share in 2024, supported by its strong semiconductor research base, advanced electronics manufacturing, and government-backed innovation programs. Victoria follows with about 25% share, driven by biotechnology, healthcare, and renewable energy applications. Together, these regions account for over 60% of national demand, reinforcing their dominance in shaping Australia’s quartz wafer market landscape.
Market Insights
- The Australia single crystal quartz wafer market was valued at USD 9.62 million in 2024 and is projected to reach USD 15.94 million by 2032, growing at a CAGR of 6.8% during the forecast period.
- Strong demand from the semiconductor industry drives growth, supported by quartz wafers’ high purity, thermal stability, and reliability in advanced electronics and MEMS applications.
- Key trends include rising adoption of larger wafer diameters above 8 inches, expanding use in biotechnology and healthcare innovations, and opportunities in renewable energy and optoelectronics applications.
- The competitive landscape features global players such as Jiaxing AOSITE Photonics Technology, Semiconductor Wafer Inc., Ferrotec Global, and NIHON DEMPA KOGYO CO., LTD., focusing on product innovation, cost optimization, and strategic collaborations.
- Regionally, New South Wales leads with over 35% share, followed by Victoria at 25%, while by segment, semiconductors dominate with over 40% share, reinforcing their critical role in market expansion.
Market Segmentation Analysis:
By Type
The seeded segment dominated the Australia single crystal quartz wafer market in 2024, accounting for over 65% share. Seeded wafers are preferred due to their superior structural integrity, controlled crystal orientation, and consistent quality, which are essential in semiconductor and MEMS production. Their high adoption stems from established manufacturing practices and ability to support large-scale fabrication processes. The seedless type holds a smaller share, primarily used in niche applications where defect-free crystal growth is required, but limited scalability and higher production costs restrict broader market penetration.
- For instance, Shin-Etsu Chemical produces quartz wafers with diameters up to 200 mm for high-temperature semiconductor processing applications. The number of semiconductor chips produced per wafer is dependent on the size of the individual chip.
By Diameter
Quartz wafers with diameters of 5 to 8 inches led the market in 2024, holding around 55% share. This segment benefits from strong demand in semiconductor and electronics manufacturing, where mid-range wafer sizes balance cost-efficiency and performance. Larger diameters, such as above 8 inches, are gaining traction due to their role in advanced semiconductor devices, but their higher production complexity slows adoption. Smaller wafers, up to 4 inches, remain relevant in research, prototyping, and specialized electronics applications, though their commercial demand is relatively limited compared to mid-sized wafers.
- For instance, Heraeus Covantics (formerly Heraeus Quarzglas) produces high-purity quartz and fused silica components, such as process tubes, windows, and liners, for the equipment used to manufacture 12-inch wafers. These components are crucial for enabling next-generation power semiconductor production on standard silicon (Si) wafers, though some power devices are now being manufactured on other materials like silicon carbide (SiC).
By Application
The semiconductor segment captured the largest share of over 40% in 2024, driven by Australia’s growing focus on microelectronics and chip fabrication. Single crystal quartz wafers play a vital role in producing high-performance semiconductor devices, benefiting from rising demand in consumer electronics, automotive electronics, and communication technologies. MEMS and electronics also form a strong sub-segment, fueled by applications in sensors and precision instruments. Biotechnology and integrated circuit packaging contribute steadily, though their shares remain smaller, with growth linked to emerging healthcare applications and miniaturization in IC packaging technologies.
Key Growth Drivers
Rising Demand from Semiconductor Industry
The semiconductor sector is the primary growth driver for Australia’s single crystal quartz wafer market, holding significant influence on consumption volumes. Quartz wafers are indispensable in semiconductor manufacturing due to their thermal stability, high purity, and ability to maintain structural integrity under extreme conditions. The growing demand for advanced microchips used in consumer electronics, automotive electronics, and industrial automation has accelerated the adoption of these wafers. Australia’s semiconductor industry is also aligning with global supply chain expansion, supporting local wafer consumption. With global semiconductor sales expected to grow steadily, the demand for reliable substrates like quartz wafers continues to rise. This positions the semiconductor segment as a long-term anchor for market expansion, especially as investments in chip fabrication and microelectronics production increase across Asia-Pacific.
- For instance, Taiwan Semiconductor Manufacturing Company (TSMC) produced a total of 12.9 million 12-inch equivalent wafers in 2024, many requiring high-purity quartz substrates for lithography and etching processes.
Expansion of MEMS and Electronics Applications
Micro-electromechanical systems (MEMS) and electronic components represent another key growth driver for the Australia single crystal quartz wafer market. These wafers are extensively used in sensors, oscillators, and precision instruments, making them essential in automotive, aerospace, and telecommunications applications. The increasing adoption of MEMS in smartphones, wearable devices, and connected technologies has further boosted demand. Quartz wafers offer superior piezoelectric properties that make them ideal for frequency control and signal processing devices, strengthening their role in MEMS. Australia’s growing adoption of smart devices and IoT-enabled solutions provides a steady growth platform for this segment. The push for advanced sensor technologies in healthcare and defense industries also supports rising demand. With continuous miniaturization trends in electronics, quartz wafers are likely to remain critical in supporting the high precision and durability requirements of modern MEMS-based devices.
- For instance, Bosch Sensortec shipped over 1 billion MEMS sensors featuring integrated microcontrollers and software in 2024. In general, Bosch Sensortec's consumer-grade accelerometers and gyroscopes utilize standard silicon-based technology with capacitive detection, not quartz-based resonators.
Growth in Biotechnology and Healthcare Innovations
The biotechnology sector is emerging as a niche yet powerful driver for the Australia single crystal quartz wafer market. Quartz wafers are used in medical diagnostic systems, biosensors, and lab-on-chip devices due to their chemical inertness and stability. The growth of personalized medicine, point-of-care diagnostics, and advanced research applications has accelerated the integration of quartz wafers in biotech solutions. Australia’s focus on strengthening healthcare research infrastructure and increasing R&D investments supports this growth trajectory. Demand for high-performance substrates in biomedical devices, including DNA sequencing and microfluidic platforms, further underpins the segment’s relevance. The COVID-19 pandemic has also spurred greater interest in diagnostics and healthcare innovation, indirectly supporting quartz wafer adoption. As biotechnology companies in Australia and the wider Asia-Pacific region scale their research and production, quartz wafers are expected to play an expanding role in supporting innovation across diagnostic and therapeutic technologies.
Key Trends & Opportunities
Increasing Adoption of Larger Diameter Wafers
A major trend in the Australia single crystal quartz wafer market is the shift toward larger wafer diameters, particularly those above 8 inches. Larger wafers allow manufacturers to produce more chips per substrate, thereby improving cost-efficiency and productivity. While adoption remains limited by production complexities and higher costs, the trend is gaining traction in advanced semiconductor and electronics applications. As chip demand for data centers, AI, and 5G networks expands, the use of larger wafers offers clear opportunities for scaling production. Australia, benefiting from regional semiconductor investments, is well positioned to adopt these technologies in alignment with global manufacturing shifts.
- For instance, Intel operates 300 mm (12-inch) wafer fabs in Oregon and Ireland, each capable of processing over 40,000 wafers per month, supporting AI and high-performance computing chips.
Opportunities in Renewable Energy and Optoelectronics
Renewable energy and optoelectronics are emerging as new avenues for quartz wafer applications. Their use in solar technologies, photonic devices, and LED manufacturing presents growth opportunities for Australian producers and suppliers. The country’s commitment to renewable energy adoption and decarbonization targets strengthens the potential demand for quartz wafers in photovoltaic and optoelectronic systems. These applications require substrates with excellent transparency, stability, and precision, making quartz wafers highly suitable. Companies tapping into these emerging segments can diversify their revenue streams while supporting Australia’s broader sustainability agenda.
Key Challenges
High Manufacturing and Processing Costs
One of the main challenges in the Australia single crystal quartz wafer market is the high cost of production. Quartz wafer fabrication involves advanced processing techniques, stringent purity requirements, and significant capital investment in specialized equipment. These costs limit scalability and restrict adoption among smaller players. Additionally, the cost-sensitive nature of downstream industries like MEMS and semiconductors creates pressure on suppliers to maintain competitive pricing while ensuring product quality. The inability to achieve cost reductions at scale poses a barrier to broader market penetration and profitability, especially when competing with lower-cost international producers.
Limited Local Supply Chain and Dependence on Imports
Australia faces supply chain constraints in meeting the demand for single crystal quartz wafers due to limited domestic production capabilities. The market heavily relies on imports from established suppliers in Asia-Pacific and Europe, which exposes it to global price fluctuations and logistics challenges. Dependence on imports also creates vulnerability to trade disruptions, shipping delays, and geopolitical risks. The lack of a robust local supply chain limits Australia’s ability to capitalize fully on the growing semiconductor and electronics industries. Developing domestic manufacturing capabilities remains a challenge, requiring long-term investment and government support to reduce reliance on international suppliers.
Regional Analysis
New South Wales (NSW)
New South Wales dominated the Australia single crystal quartz wafer market in 2024, holding over 35% share. The state benefits from its strong presence of semiconductor research facilities, advanced electronics manufacturing, and university-led R&D programs. Sydney’s technology ecosystem further supports the integration of quartz wafers in MEMS and semiconductor applications. With government initiatives promoting high-tech industries and innovation hubs, NSW remains the leading region for market adoption. The concentration of skilled workforce and partnerships between academia and industry strengthen its leadership, making it the central hub for wafer demand and innovation in Australia.
Victoria (VIC)
Victoria accounted for around 25% share of the Australia single crystal quartz wafer market in 2024. Melbourne’s expanding biotechnology and healthcare sector has significantly contributed to the use of quartz wafers in biosensors, diagnostics, and lab-on-chip devices. The region’s investment in medical research institutes and advanced manufacturing clusters enhances market growth opportunities. Victoria’s push toward renewable energy technologies and integration of advanced materials in photonics also supports demand. Strategic collaborations with global semiconductor and biotech players ensure that Victoria remains a competitive and fast-growing contributor to the overall market landscape in Australia.
Queensland (QLD)
Queensland represented close to 15% share of the single crystal quartz wafer market in 2024, supported by growth in industrial electronics and mining technology applications. Brisbane’s focus on advanced materials research and the region’s growing renewable energy sector drive additional demand for quartz wafers in photovoltaic and optoelectronic systems. Government-backed initiatives to diversify Queensland’s economy beyond mining have created opportunities in advanced manufacturing and high-tech industries. The state’s research institutions continue to foster innovation in MEMS-based devices and semiconductor technologies, reinforcing Queensland’s position as a steadily growing region in the national wafer market.
Western Australia (WA)
Western Australia held about 13% share of the Australia single crystal quartz wafer market in 2024. The region’s demand is driven primarily by mining automation, defense electronics, and niche MEMS applications. WA’s strong focus on defense technology projects and advanced industrial solutions supports quartz wafer integration in specialized electronics. While it lacks the extensive R&D base of NSW or Victoria, investments in industrial innovation and collaborations with national research bodies help sustain its growth. WA’s growing interest in renewable energy and smart infrastructure further positions the state as a contributor to emerging applications within the wafer market.
South Australia (SA)
South Australia contributed roughly 12% share to the Australia single crystal quartz wafer market in 2024. The state has carved out a role in defense manufacturing and aerospace technology, driving demand for MEMS sensors and high-performance semiconductor devices. Adelaide’s innovation ecosystem, supported by defense contractors and aerospace projects, provides opportunities for quartz wafer use in specialized applications. The government’s support for advanced manufacturing, along with investments in research-driven industries, adds to the state’s steady market presence. Though smaller compared to NSW and Victoria, South Australia’s targeted strengths ensure its importance in niche and high-tech segments of the wafer market.
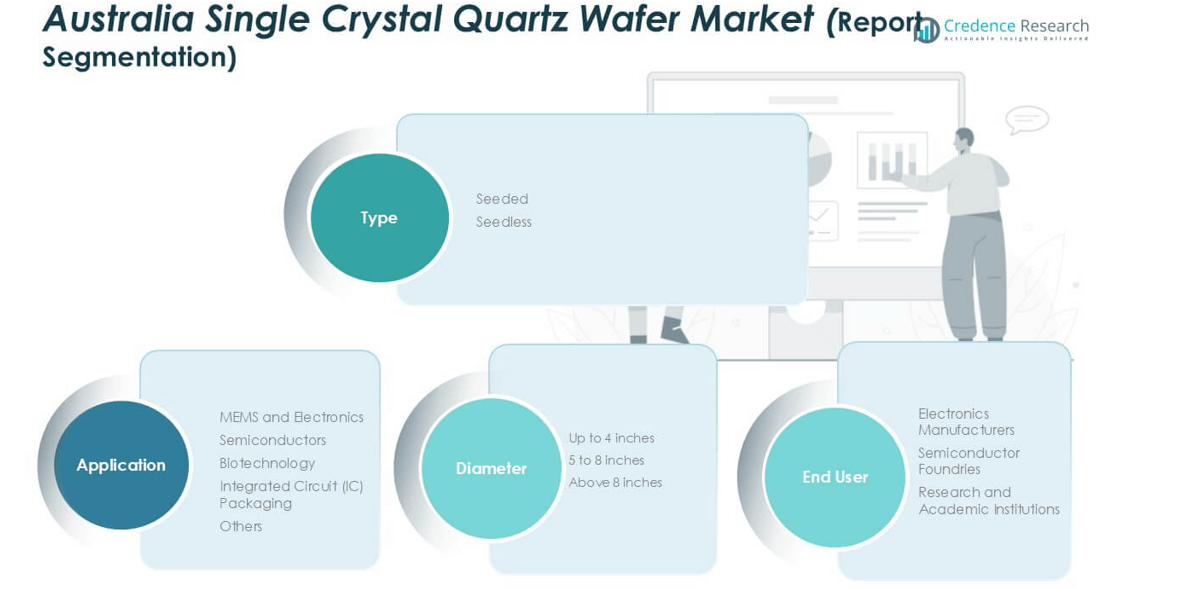
Market Segmentations:
By Type
- Seeded
- Seedless
By Diameter
- Up to 4 inches
- 5 to 8 inches
- Above 8 inches
By Application
- MEMS and Electronics
- Semiconductors
- Biotechnology
- Integrated Circuit (IC) Packaging
- Others
By End User
- Electronics Manufacturers
- Semiconductor Foundries
- Research and Academic Institutions
By Geography
- New South Wales (NSW)
- Victoria (VIC)
- Queensland (QLD)
- Western Australia (WA)
- South Australia (SA)
Competitive Landscape
The Australia single crystal quartz wafer market features a moderately fragmented competitive landscape, with participation from global suppliers, regional distributors, and specialized technology providers. Key companies such as Jiaxing AOSITE Photonics Technology Co., Ltd., Semiconductor Wafer, Inc., MTI Corporation, and Ferrotec Global maintain a strong presence by offering high-quality wafers tailored for semiconductor, MEMS, and biotechnology applications. Players like MicroChemicals GmbH, NIHON DEMPA KOGYO CO., LTD., and UniversityWafer, Inc. contribute by supplying research-grade wafers to universities and R&D institutions, supporting innovation. Competitive strategies focus on expanding product portfolios, advancing wafer diameter capabilities, and improving purity standards to align with the growing needs of semiconductor and electronics industries. Recent developments emphasize partnerships with local distributors and collaborations with research institutions to strengthen regional reach. The market also witnesses increasing emphasis on cost optimization and technological advancements, enabling players to address demand for larger wafers and high-performance substrates across diverse end-use sectors in Australia.
Key Player Analysis
- Jiaxing AOSITE Photonics Technology Co., Ltd.
- Semiconductor Wafer, Inc.
- MTI Corporation
- Hangzhou Freqcontrol Electronic Technology Ltd.
- Vritra Technologies
- Ferrotec Global
- MicroChemicals GmbH
- NIHON DEMPA KOGYO CO., LTD.
- MSE Supplies Inc.
- UniversityWafer, Inc.
- Other Key Players
Recent Developments
- In July 2025, Xiamen Powerway (PAM-XIAMEN) remains an active supplier of single crystal quartz wafers, specializing in X-cut, Y-cut, Z-cut, and ST-cut orientations up to 3-inch diameters.
- In July 2025, NDK highlighted its advancement in mass-producing high-uniformity quartz crystals using proprietary technologies. Their latest offering includes synthetic quartz wafers with AT-cut and tuning fork wafers, and a development plan for larger 6-inch wafers to cater to growing SAW device demand and frequency control in next-gen electronics.
- In August 2024, NDK (NIHON DEMPA KOGYO CO., LTD.) showcased its synthetic quartz crystals and quartz wafers for timing and optical applications at electronica India 2024, participating through a distributor's booth at the trade fair.
Report Coverage
The research report offers an in-depth analysis based on Type, Diameter, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily, driven by rising semiconductor and MEMS applications.
- Demand for larger wafer diameters will increase to support advanced chip production.
- Biotechnology and healthcare will create new opportunities for quartz wafer integration.
- Local collaborations between research institutions and global suppliers will strengthen innovation.
- Growing adoption of IoT and smart devices will fuel MEMS-based wafer demand.
- Renewable energy and optoelectronics applications will open additional growth avenues.
- Competition will intensify as players invest in high-purity and defect-free wafer production.
- Import dependence may decline gradually with efforts to build domestic supply chains.
- New South Wales and Victoria will continue to lead regional consumption and growth.
- Continuous miniaturization in electronics will ensure long-term relevance of quartz wafers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Semiconductor Industry Expansion
Australia's growing semiconductor sector is the primary driver for single crystal quartz wafer demand, as these wafers are essential for high-purity, thermally stable substrates in advanced chip manufacturing and microelectronics.
Rising MEMS and Electronics Applications
The proliferation of MEMS devices and precision electronics in automotive, telecommunications, and consumer devices is increasing the need for quartz wafers, which offer superior piezoelectric and frequency control properties.
Adoption of Larger Wafer Diameters
Manufacturers are shifting toward larger wafer sizes (above 8 inches) to boost chip yields and production efficiency, supporting the scaling of advanced semiconductor and electronics manufacturing in Australia.
Growth in Biotechnology and Healthcare
Quartz wafers are increasingly used in biosensors, diagnostics, and lab-on-chip devices due to their chemical inertness and stability, with Australia's investment in healthcare R&D fueling this segment.
Renewable Energy and Optoelectronics Opportunities
Emerging applications in solar technologies, photonics, and LED manufacturing are opening new avenues for quartz wafer use, aligning with Australia's renewable energy targets and technological innovation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Australia Single Crystal Quartz Wafer market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Australia Single Crystal Quartz Wafer market projected to grow between 2025 and 2032?
Which Australia Single Crystal Quartz Wafer market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Australia Single Crystal Quartz Wafer market?
Who are the leading companies in the Australia Single Crystal Quartz Wafer market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Seeded
- 1.2.2 Seedless
- 1.3 By Diameter
- 1.3.1 Up to 4 inches
- 1.3.2 5 to 8 inches
- 1.3.3 Above 8 inches
- 1.4 By Application
- 1.4.1 Semiconductors
- 1.4.2 MEMS and Electronics
- 1.4.3 Biotechnology
- 1.4.4 Integrated Circuit (IC) Packaging
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9.62 million → 2032: USD 15.94 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Single Crystal Quartz Wafer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Single Crystal Quartz Wafer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Single Crystal Quartz Wafer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Single Crystal Quartz Wafer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Single Crystal Quartz Wafer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Single Crystal Quartz Wafer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Single Crystal Quartz Wafer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Single Crystal Quartz Wafer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9.62 million → 2032: USD 15.94 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Single Crystal Quartz Wafer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Seeded
- 12.3.7.2 Seedless
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Diameter - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Up to 4 inches
- 12.4.7.2 5 to 8 inches
- 12.4.7.3 Above 8 inches
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Semiconductors
- 12.5.7.2 MEMS and Electronics
- 12.5.7.3 Biotechnology
- 12.5.7.4 Integrated Circuit (IC) Packaging
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Single Crystal Quartz Wafer End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Single Crystal Quartz Wafer Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Single Crystal Quartz Wafer Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Single Crystal Quartz Wafer Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Jiaxing AOSITE Photonics Technology Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Semiconductor Wafer, Inc.
- 18.4 MTI Corporation
- 18.5 Hangzhou Freqcontrol Electronic Technology Ltd.
- 18.6 Ferrotec Global
- 18.7 MicroChemicals GmbH
- 18.8 NIHON DEMPA KOGYO CO., LTD.
- 18.9 MSE Supplies Inc.
- 18.10 UniversityWafer, Inc.
- 18.11 Xiamen Powerway (PAM-XIAMEN)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

