
Equipment Monitoring Market Overview
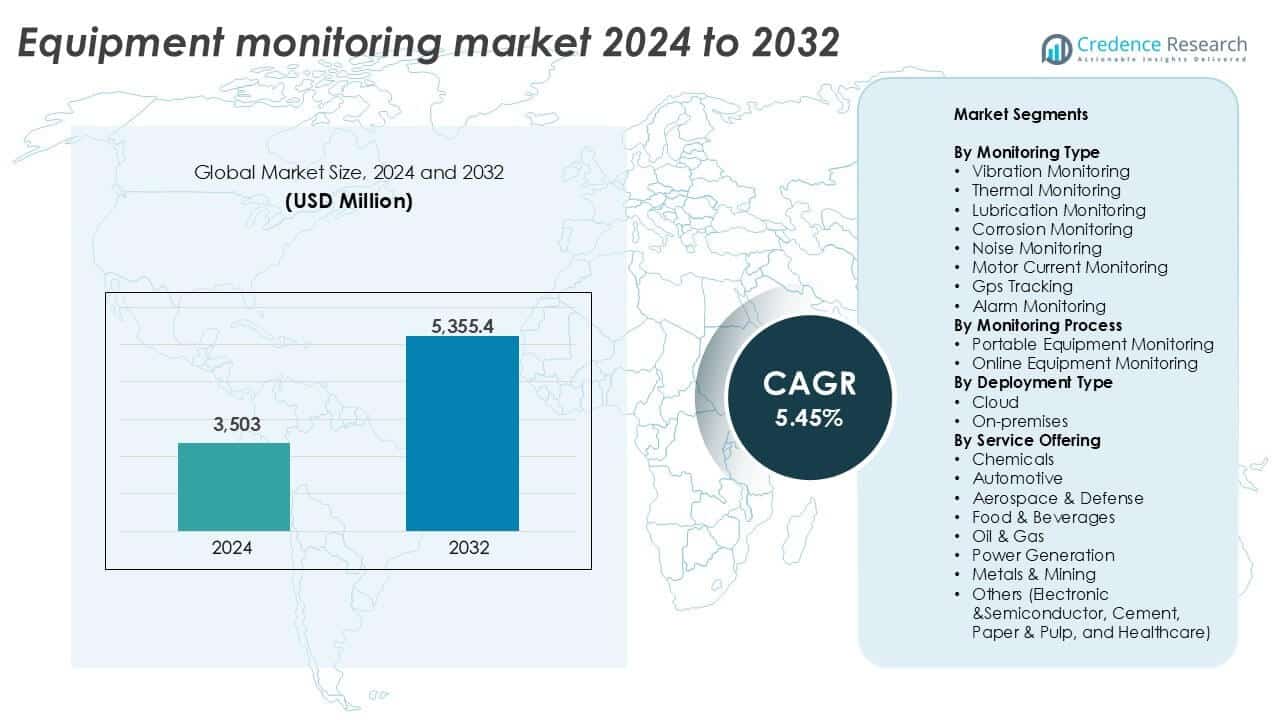
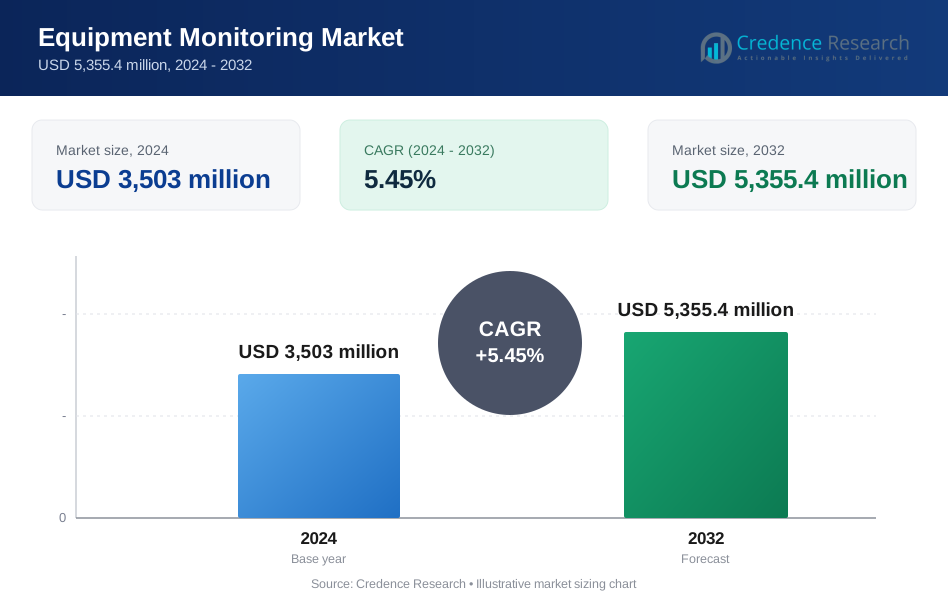
The Equipment Monitoring Market size was valued at USD 3,503 million in 2024 and is anticipated to reach USD 5,355.4 million by 2032, at a CAGR of 5.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Equipment Monitoring Market Size 2024 | USD 3,503 million |
| Equipment Monitoring Market, CAGR | 5.45% |
| Equipment Monitoring Market Size 2032 | USD 5,355.4 million |
Top players in the equipment monitoring market include ABB, Emerson Electric, General Electric, Honeywell International, Rockwell Automation, Schneider Electric, and SKF. These companies lead through strong portfolios in sensor technology, predictive maintenance software, and cloud-integrated monitoring platforms. Emerson and Honeywell focus on industrial IoT-driven solutions, while SKF and Schaeffler AG specialize in vibration and rotating equipment diagnostics. Rockwell Automation and Schneider Electric emphasize automation and system-wide integration. Regionally, North America leads the market with a 30.2% share in 2024, driven by early adoption of smart factory technologies, regulatory compliance, and presence of major vendors. Asia-Pacific follows closely, fueled by manufacturing expansion and digitalization initiatives.
Equipment Monitoring Market Insights
- The equipment monitoring market was valued at USD 3,503 million in 2024 and is projected to reach USD 5,355.4 million by 2032, growing at a CAGR of 5.45%.
- Rising demand for predictive maintenance and real-time fault detection in industrial assets drives steady market expansion.
- Key trends include increased adoption of IoT-based sensors, cloud platforms, and edge analytics across smart factories.
- Major players such as ABB, Honeywell, Emerson, and Schneider Electric lead with integrated solutions and global reach, while mid-size vendors offer niche, cost-effective tools.
- North America holds the largest share at 30.2%, followed by Asia-Pacific with 28%, driven by industrial growth; vibration monitoring leads among monitoring types with 25%+ share, and online monitoring dominates the monitoring process with over 60% share.
Equipment Monitoring Market Segmentation Analysis:
By Monitoring Type
Vibration monitoring holds the largest share in the equipment monitoring market, accounting for over 25% in 2024. Its dominance stems from wide adoption across manufacturing, oil & gas, and power industries. Vibration sensors detect early-stage faults in rotating machinery, reducing unplanned downtime. Equipment failures caused by imbalance, misalignment, or bearing wear can be predicted through real-time analysis. Thermal and motor current monitoring are also growing steadily due to rising usage in electrical equipment diagnostics. Lubrication and corrosion monitoring gain traction in marine and heavy industries where environmental exposure impacts performance.
- For instance, the Fluke 438-II Power Quality and Motor Analyzer, widely utilized across global industrial sectors, supports the simultaneous analysis of electrical power quality and mechanical motor performance including torque, efficiency, and NEMA thermal derating factors without the need for mechanical sensors.
By Monitoring Process
Online equipment monitoring leads this segment with more than 60% share in 2024. It enables continuous, real-time data collection, helping operators respond instantly to anomalies. The rise in automated plants and smart factories boosts the adoption of online systems. These systems integrate with SCADA and industrial IoT platforms for predictive maintenance. Portable equipment monitoring is favored in remote or small-scale facilities where full integration is not feasible. Portability supports diagnostics across multiple machines, but lacks the speed and detail of permanent systems.
- For instance, Emerson’s AMS Asset Monitor supports 24/7 remote vibration and temperature tracking, with over 30,000 units deployed across refineries and chemical plants globally.
By Deployment Type
Cloud-based deployment dominates the market with a share exceeding 55% in 2024. Its scalability, remote access, and lower upfront costs make it ideal for enterprises with distributed operations. Cloud solutions enable centralized data management and AI-powered analytics for condition monitoring. As industrial digitalization expands, cloud adoption accelerates, especially in predictive maintenance applications. On-premises deployment remains relevant for facilities with strict data control or cybersecurity protocols, particularly in defense, energy, and pharmaceutical sectors. However, higher maintenance costs and limited remote access challenge its growth.
Equipment Monitoring Market Key Growth Drivers
Rising Focus on Predictive Maintenance to Reduce Downtime
The equipment monitoring market gains strong momentum from the global shift toward predictive maintenance. Industries face mounting pressure to cut downtime and optimize asset utilization. Predictive solutions allow early detection of faults in motors, pumps, compressors, and turbines using vibration, thermal, and current sensors. This proactive approach helps avoid unplanned outages, costly repairs, and safety risks. Manufacturing, oil & gas, power generation, and aerospace sectors increasingly adopt condition-based monitoring systems. Advancements in IoT and real-time analytics support scalable predictive tools. Companies that implement these systems report up to 30% reduction in maintenance costs and 45% fewer breakdowns. Cloud platforms, wireless sensor networks, and machine learning models improve fault diagnostics and asset lifecycle management. As industries seek to improve operational efficiency and reduce total cost of ownership, predictive maintenance becomes a core investment area.
- For instance, GE Digital reported that customers using its APM (Asset Performance Management) software achieved up to 45% fewer equipment failures and 30% lower maintenance costs across heavy industries in 2023.
Increasing Integration of Industrial IoT and Smart Factory Solutions
Rapid adoption of industrial IoT (IIoT) solutions fuels demand for advanced equipment monitoring systems. Smart factories leverage sensor networks, edge devices, and cloud platforms to enable seamless equipment condition tracking. IoT-enabled monitoring solutions provide real-time data on temperature, vibration, pressure, noise, and lubricant levels, ensuring instant fault alerts. Edge computing reduces latency, enabling faster decision-making at the machine level. Integration with MES, ERP, and SCADA platforms enhances visibility across production lines. These technologies support remote diagnostics, predictive alerts, and performance benchmarking. Sectors such as automotive, electronics, and food processing invest heavily in IIoT-led monitoring to enhance productivity. The need for automated and data-driven maintenance strategies positions IIoT as a central growth catalyst. Governments and industrial consortiums also support digital factory initiatives, boosting market penetration.
- For example, Honeywell’s Forge platform, deployed in over 10,000 industrial facilities globally, offers unified asset health visibility through IIoT-connected sensors.
Regulatory Compliance and Worker Safety Requirements
Strict regulations around machine safety, emissions control, and environmental compliance accelerate the adoption of equipment monitoring systems. In hazardous industries like mining, oil & gas, and chemicals, authorities mandate regular equipment inspection and fault detection. Monitoring systems help track vibration thresholds, lubricant quality, temperature spikes, and gas leaks to avoid safety breaches. OSHA, EPA, ISO, and other regulatory bodies enforce standards for plant safety and reliability. Equipment monitoring enables early fault detection, preventing workplace injuries and catastrophic equipment failures. Real-time alarm monitoring, corrosion detection, and motor current analysis support safer operations. Companies also deploy these tools to meet insurance conditions and audit compliance. With rising focus on worker well-being and sustainability, the demand for monitoring solutions aligned with regulatory frameworks continues to grow.
Equipment Monitoring Market Key Trends & Opportunities
Surge in Demand for Cloud-Based Monitoring Platforms
The transition from on-premises to cloud-based equipment monitoring systems represents a major trend in the market. Cloud platforms offer scalability, real-time data access, and centralized dashboards, enabling remote monitoring across multiple locations. Industries with geographically dispersed assets like power utilities and transportation prefer cloud systems for better coordination and lower infrastructure costs. Vendors now offer AI-driven cloud platforms that integrate with ERP and maintenance planning systems. Predictive analytics on cloud help in diagnosing issues faster and planning service schedules more effectively. Small and medium enterprises also adopt cloud-based solutions due to lower entry costs and simplified deployment. Rising cybersecurity improvements, coupled with increasing internet penetration in industrial zones, support this transition. As digital transformation accelerates, cloud-based monitoring will create new opportunities for both software vendors and OEMs.
- For instance, Honeywell’s Forge Predictive Maintenance solution, deployed across 10,000+ assets globally, uses machine learning to forecast failures and optimize schedules.
Expansion of Monitoring Scope to Non-Traditional Parameters
Companies are now expanding equipment monitoring beyond traditional vibration and temperature metrics. Noise, lubrication quality, corrosion, and GPS tracking have emerged as critical parameters for performance monitoring. Advanced sensors and edge analytics make it feasible to track a broader range of data in real-time. In logistics, GPS-based monitoring helps in asset tracking and theft prevention. In heavy equipment, lubrication condition monitoring prevents internal wear and extends part life. Corrosion detection systems are vital for offshore rigs, pipelines, and marine infrastructure. These innovations open opportunities in niche applications such as wind farms, smart buildings, and defense logistics. OEMs and startups are developing customized solutions for industry-specific challenges. As the scope of equipment monitoring broadens, the market finds new end-use applications and customer segments.
Equipment Monitoring Market Key Challenges
High Cost of System Implementation and Sensor Deployment
Despite long-term cost savings, the high upfront investment in equipment monitoring systems remains a barrier, especially for small and mid-sized firms. These systems require installation of multiple sensors, software platforms, edge computing devices, and network infrastructure. Initial costs also include integration with existing equipment and staff training. Advanced monitoring systems with AI-based analytics or multi-sensor configurations further increase deployment costs. For legacy machinery, retrofitting compatible monitoring solutions may involve hardware upgrades or customization. Many businesses hesitate to invest due to uncertain return on investment or budget limitations. Limited government support or subsidies for industrial digitalization in some regions also slows adoption. Vendors must offer flexible pricing models, including pay-as-you-go or subscription-based offerings, to improve accessibility.
Data Security Risks and Lack of Standardization
As equipment monitoring shifts toward cloud and IoT-based architectures, data security becomes a growing concern. Sensitive machine performance data and operational parameters transmitted over networks can be vulnerable to cyberattacks or unauthorized access. Industries like defense, pharmaceuticals, and critical infrastructure sectors enforce strict cybersecurity protocols, making them cautious about cloud-based solutions. A lack of unified data standards and protocol compatibility also hampers interoperability among systems from different vendors. Disconnected data silos limit real-time insights and system-wide optimization. Without clear standards, large-scale integration remains difficult. Industry stakeholders and regulators must collaborate to establish secure, interoperable frameworks for equipment monitoring to build long-term trust and adoption.
Equipment Monitoring Market Regional Analysis
North America
North America dominates the equipment monitoring market with a share of over 30% in 2024. The region benefits from early adoption of predictive maintenance technologies across manufacturing, oil & gas, and aerospace sectors. U.S.-based companies lead investments in IoT-enabled monitoring, AI-driven analytics, and cloud platforms. Strong regulatory focus on workplace safety and machine reliability drives adoption in hazardous industries. High labor costs push companies to automate diagnostics and reduce unplanned downtime. Major OEMs and software vendors are based in this region, enabling faster solution deployment. The U.S. and Canada see continued investment in smart factory infrastructure.
Europe
Europe holds around 25% share in the equipment monitoring market, supported by stringent environmental and safety regulations. Countries like Germany, France, and the UK lead adoption due to strong industrial bases and high automation levels. The presence of established automotive, energy, and chemical manufacturing hubs supports widespread deployment. EU initiatives promoting Industry 4.0 accelerate integration of real-time monitoring and predictive maintenance. Demand rises from sectors prioritizing energy efficiency and emissions compliance. The shift to hybrid manufacturing models fuels the need for advanced diagnostics. Europe also focuses on data privacy, influencing deployment preferences across industries.
Asia-Pacific
Asia-Pacific captures over 28% share in the equipment monitoring market in 2024, making it a fast-growing region. China, Japan, India, and South Korea drive growth through large-scale industrial expansion and digitalization efforts. Rapid infrastructure development and increasing manufacturing output fuel demand for reliable equipment performance. Governments support smart manufacturing through policies like “Made in China 2025” and “Digital India.” Local firms invest in cost-effective condition monitoring to reduce maintenance overhead. Japan and South Korea adopt advanced solutions in electronics and automotive sectors. The region sees rising demand for cloud and wireless sensor-based monitoring platforms.
Latin America
Latin America accounts for about 7% of the equipment monitoring market, with Brazil and Mexico leading adoption. Growth is driven by increasing investment in oil & gas, mining, and food processing industries. Companies seek to improve equipment uptime and reduce costly maintenance shutdowns. Economic modernization and infrastructure upgrades encourage condition monitoring deployment. The region shows growing interest in cloud-based solutions to overcome hardware cost barriers. OEMs target Latin America with portable and scalable systems. However, budget limitations and lack of skilled workforce restrict widespread adoption. Despite these hurdles, awareness about predictive maintenance is steadily rising.
Middle East & Africa
The Middle East & Africa represent a 5% share in the equipment monitoring market, with growing adoption in oil & gas, utilities, and mining sectors. The Gulf Cooperation Council (GCC) countries invest heavily in asset-intensive industries that require robust monitoring. Real-time systems are deployed to ensure safety, reduce unplanned downtime, and comply with regulatory norms. Africa sees slow but rising adoption, especially in South Africa and Nigeria, driven by energy and mining projects. Cloud-based and mobile-compatible solutions gain traction due to limited IT infrastructure. Vendor partnerships and training programs are essential to support growth in this region.
Equipment Monitoring Market Segmentations:
By Monitoring Type
- Vibration Monitoring
- Thermal Monitoring
- Lubrication Monitoring
- Corrosion Monitoring
- Noise Monitoring
- Motor Current Monitoring
- Gps Tracking
- Alarm Monitoring
By Monitoring Process
- Portable Equipment Monitoring
- Online Equipment Monitoring
By Deployment Type
- Cloud
- On-premises
By Service Offering
- Chemicals
- Automotive
- Aerospace & Defense
- Food & Beverages
- Oil & Gas
- Power Generation
- Metals & Mining
- Others (Electronic &Semiconductor, Cement, Paper & Pulp, and Healthcare)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The equipment monitoring market features a moderately consolidated competitive landscape, led by global industrial automation and technology firms. Key players such as ABB, Emerson Electric, General Electric, and Honeywell International dominate through comprehensive portfolios and strong global presence. These companies offer integrated monitoring platforms with advanced sensor technologies and cloud connectivity. Firms like SKF and Schaeffler AG maintain leadership in rotating equipment diagnostics, leveraging decades of mechanical expertise. Rockwell Automation, Schneider Electric, and National Instruments invest heavily in predictive maintenance software and edge analytics. Players focus on strategic acquisitions, cloud partnerships, and product innovations to enhance market reach. For instance, Emerson’s Plantweb platform and GE’s Predix solution showcase the shift toward data-driven asset management. Emerging players and regional specialists compete by offering cost-effective, scalable, and portable systems tailored for mid-size enterprises. The market remains dynamic, with rising investments in AI-based monitoring and condition analytics reshaping competitive priorities.
Key Player Analysis
- ABB
- ALS Limited
- Emerson Electric
- Fortive Corporation
- General Electric
- Honeywell International
- National Instruments
- Parker Hannifin Corporation
- Rockwell Automation, Inc.
- Schaeffler AG
- Schneider Electric Co.
- SKF
Recent Developments
- In June 2024, Teledyne FLIR LLC, a defense industry company, announced the launch of the SV89 Vibration Monitoring Solution Kits and FLIR SV88, which assist customers in monitoring critical equipment by continuously detecting faults, alerting to potential defects and future problems and analyzing vibration. The SV88 and SV89 Vibration Monitoring Solution Kits' multi-communication protocols, IP66 rating, wireless functionality, and rugged design enable customers to make crucial data-driven decisions that prolong the life of expensive equipment by warning of possible problems.
- In May 2024, Datadog, Inc., a company that is focused on developing the monitoring and security platform for cloud applications, revealed the launch of the IT Event Management to its suite of AIOps (artificial intelligence for information technology operations) capabilities. Datadog's event management feature allows it to intelligently combine, correlate, and enhance all alert events and significant signals from both Datadog and other third-party observability tools into a single, coherent view. By reducing alert fatigue, this technique enables teams to concentrate their efforts and resources on fixing problems.
Report Coverage
The research report offers an in-depth analysis based on Monitoring Type, Monitoring Process, Deployment Type, Service Offering and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for predictive maintenance solutions will increase across asset-intensive industries.
- Integration of AI and machine learning will improve fault detection accuracy.
- Cloud-based monitoring platforms will become the preferred deployment model.
- Adoption of wireless and portable sensors will expand in remote and mobile applications.
- Manufacturing and energy sectors will drive steady investment in real-time monitoring.
- Vibration and thermal monitoring will remain critical for rotating equipment diagnostics.
- Edge computing will enable faster decision-making at the equipment level.
- Regulatory compliance and safety mandates will push monitoring adoption in hazardous sectors.
- Asia-Pacific will emerge as the fastest-growing regional market due to industrial expansion.
- Market competition will intensify with new players offering scalable and cost-effective solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Equipment monitoring market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Equipment monitoring market projected to grow between 2024 and 2032?
Which Equipment monitoring market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Equipment monitoring market?
Who are the leading companies in the Equipment monitoring market?
Which region commanded the largest share of the Equipment monitoring market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,503 million → 2032: USD 5,355.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Equipment Monitoring Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Equipment Monitoring Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Equipment Monitoring Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Equipment Monitoring Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Equipment Monitoring Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Equipment Monitoring Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Equipment Monitoring Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Equipment Monitoring Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,503 million → 2032: USD 5,355.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Equipment Monitoring Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Equipment Monitoring Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Equipment Monitoring Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Equipment Monitoring Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

