
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Caffeinated Beverage MarketSize 2024 | USD 66,440.56 million |
| Europe Caffeinated Beverage Market, CAGR | 4.16% |
| Europe Caffeinated Beverage Market Size 2032 | USD 92,025.58 million |
Market Overview
Europe Caffeinated Beverage market size was valued at USD 66,440.56 million in 2024 and is anticipated to reach USD 92,025.58 million by 2032, at a CAGR of 4.16% during the forecast period (2024-2032).
The Europe Caffeinated Beverage market is witnessing steady growth, driven by rising consumer demand for energy drinks, coffee, and tea. Increasing health-consciousness has led to a shift towards functional beverages, with consumers seeking options that offer both caffeine and additional health benefits, such as low-calorie, organic, and fortified beverages. Additionally, the popularity of on-the-go consumption, particularly among busy professionals and younger demographics, is contributing to market expansion. Innovative product offerings, including cold brews, energy shots, and ready-to-drink coffee, are further fueling market growth. The growing trend of functional ingredients, such as vitamins and adaptogens, being incorporated into caffeinated beverages, is also gaining momentum. With increasing awareness of the health benefits and convenience of caffeinated beverages, the market is expected to continue expanding at a steady pace, supported by both innovation in product development and a shift in consumer preferences towards healthier alternatives.
The European Caffeinated Beverage market is diverse, with key players operating across various regions, each catering to distinct consumer preferences. In the UK, Germany, and France, coffee and energy drinks dominate, fueled by strong coffee cultures and a rising demand for functional beverages. Companies like Nestlé and The Coca-Cola Company play a significant role, offering a wide range of products from energy drinks to ready-to-drink coffees. In Southern Europe, particularly Italy and Spain, coffee remains integral to daily life, while energy drinks are gaining popularity among younger demographics. Key players such as Red Bull and PepsiCo have a strong presence in these regions. The Netherlands, Sweden, and Poland also represent growing markets, driven by innovation in healthier and organic caffeinated drinks. The competition is intense, with both global and regional brands constantly innovating to meet the demands of health-conscious consumers seeking convenience and functionality.
Market Insights
- The Europe Caffeinated Beverage market was valued at USD 66,440.56 million in 2024 and is expected to reach USD 92,025.58 million by 2032, growing at a CAGR of 4.16% during the forecast period (2024-2032).
- The global caffeinated beverage market was valued at USD 252,050.67 million in 2024 and is expected to reach USD 369,284.04 million by 2032, growing at a CAGR of 4.89%.
- Increasing health consciousness is driving demand for healthier and functional beverages, including low-calorie and organic options.
- Innovation in product offerings, such as cold brew coffee and energy shots, is gaining popularity as consumers seek variety and convenience.
- Competition is intensifying with global players like Nestlé, PepsiCo, and Red Bull, alongside local brands focused on catering to regional tastes.
- Regulatory pressures related to caffeine content and sugar levels are shaping product formulations across European markets.
- The UK, Germany, and France dominate the market, driven by established coffee cultures and the growing demand for energy drinks.
- Consumer preference for sustainable packaging and eco-friendly sourcing is influencing brand strategies across the region.
Report Scope
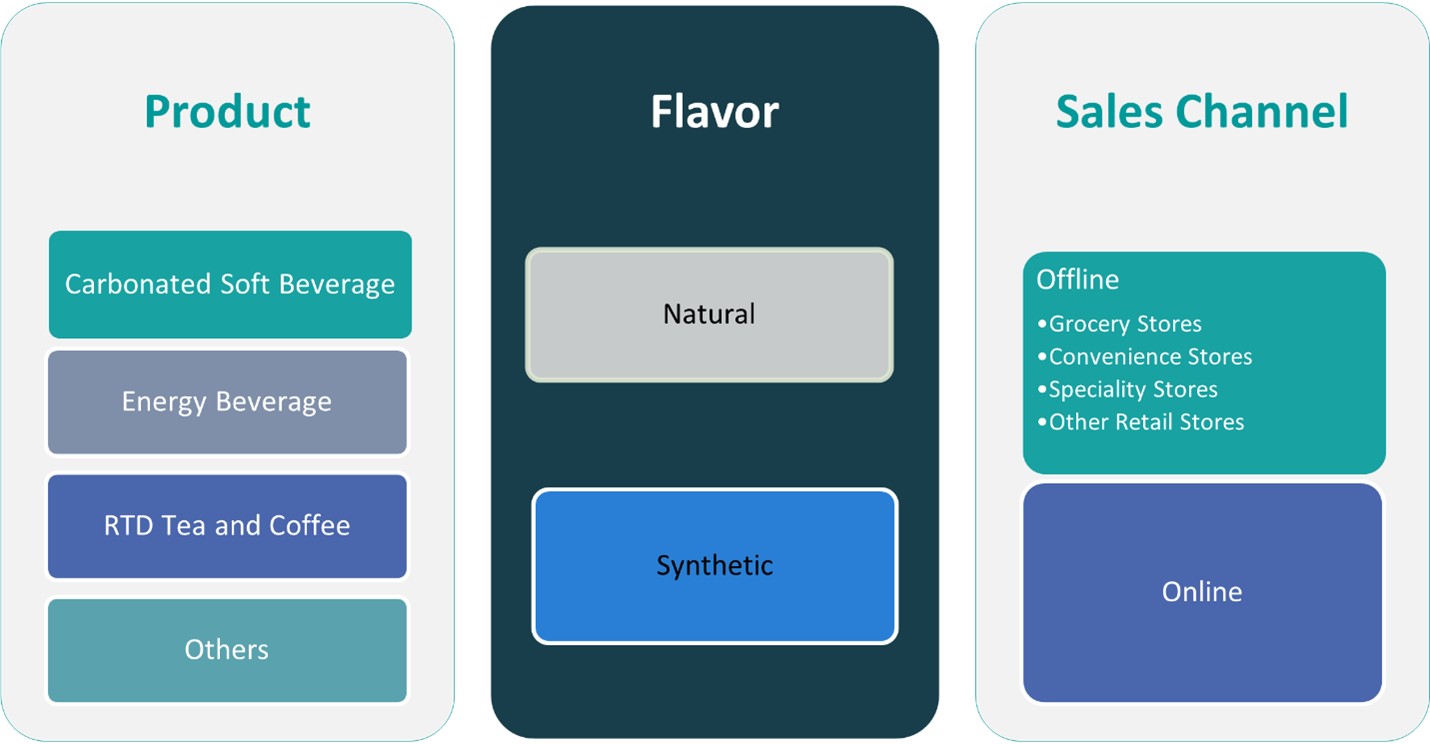
This report segments the Europe Caffeinated Beverage Market as follows:
Market Drivers
Rising Demand for Energy Drinks
One of the primary drivers of the Europe Caffeinated Beverage market is the increasing demand for energy drinks. Energy drinks have gained significant popularity among young adults, athletes, and busy professionals who seek a quick boost of energy. For instance, the European energy drinks market is expanding due to increasing consumer demand for functional beverages that enhance mental alertness and physical stamina. This growing preference is driven by the fast-paced lifestyle and the need for sustained energy throughout the day. With high caffeine content and added ingredients such as taurine, B-vitamins, and electrolytes, these beverages offer consumers the convenience of both energy and hydration in a single product. This demand has led to a surge in product innovation, with energy drinks being available in various flavors and formulations. The expanding market for energy drinks is expected to continue driving growth in the overall caffeinated beverage sector in Europe.
Growing Popularity of Coffee and Tea
Coffee and tea remain staples in the European diet, with coffee being one of the most widely consumed beverages. The growing coffee culture in Europe, especially in countries like Italy, France, and the UK, is fueling demand for caffeinated beverages. Alongside traditional coffee, the rise of specialty coffees, such as cold brew, espresso, and single-origin coffee, has attracted a new generation of coffee enthusiasts. The increasing number of coffee shops, cafes, and premium coffee brands also contributes to the growth of this market segment. Similarly, the health benefits associated with tea, particularly green and herbal varieties, have led to an increase in consumer preference for caffeinated tea options. As these beverages are widely consumed both at home and on-the-go, they are crucial contributors to the market’s expansion.
Shift Towards Functional Beverages
Another key driver of the European caffeinated beverage market is the growing trend of functional beverages. Consumers are increasingly seeking products that provide more than just caffeine, opting for beverages that offer added health benefits such as vitamins, antioxidants, and adaptogens. For instance, consumers in Europe are increasingly seeking beverages that provide energy, mental focus, and physical performance benefits. Functional beverages are becoming increasingly popular due to their ability to cater to the health-conscious consumer who is looking for products that contribute to overall wellness. Caffeinated drinks that contain added ingredients like vitamins, electrolytes, and amino acids appeal to consumers who are not only seeking an energy boost but also looking to support their physical and mental well-being. The demand for such beverages is growing in line with rising health awareness and the preference for products that offer multiple benefits.
Convenience and On-the-Go Consumption
The fast-paced lifestyle of modern consumers has significantly influenced the growth of the Europe Caffeinated Beverage market. With busy work schedules, long commutes, and active social lives, many consumers are turning to caffeinated beverages for convenience. Ready-to-drink (RTD) options, including bottled coffee, iced tea, and energy shots, have become popular choices for individuals who want quick access to their caffeine fix while on the go. This convenience factor has led to the rise of convenience stores and online platforms offering a wide variety of caffeinated beverages, catering to the needs of consumers who prioritize ease of consumption. As the demand for on-the-go, ready-to-consume beverages increases, the market for caffeinated drinks is expected to see continued growth in the coming years.
Market Trends
Innovation in Product Offerings
A significant trend shaping the Europe Caffeinated Beverage market is the continuous innovation in product offerings. Consumers are increasingly seeking variety and unique flavors in their caffeinated drinks, which has driven the development of new and exciting products. Companies are introducing novel beverage formulations such as cold brew coffee, energy shots, and sparkling caffeinated drinks, which appeal to a wide range of preferences. Additionally, there is an increasing focus on premium products, including single-origin coffees and specialty teas, which cater to the growing demand for high-quality and artisanal options. This trend reflects the evolving taste preferences of consumers, who are now more inclined to experiment with different types of caffeinated beverages beyond traditional coffee and energy drinks.
Growing Demand for Healthier Alternatives
Another key trend in the European caffeinated beverage market is the rising demand for healthier alternatives. As health-consciousness among consumers continues to grow, there is a shift towards beverages with lower sugar content, fewer artificial additives, and organic ingredients. For instance, beverage manufacturers in Europe are reformulating products to include natural ingredients and reduce sugar content to meet consumer health demands. Many consumers are opting for caffeine-rich drinks that are naturally sweetened or contain functional ingredients such as antioxidants, vitamins, and adaptogens. The popularity of plant-based caffeine sources, such as yerba mate, guayusa, and matcha, is also on the rise, as these ingredients are perceived to offer additional health benefits. This shift is prompting manufacturers to reformulate existing products and develop new beverages that align with the preferences of health-focused consumers.
Sustainability and Eco-Friendly Packaging
Sustainability has become an increasingly important factor in consumer purchasing decisions within the European Caffeinated Beverage market. As environmental concerns grow, more consumers are prioritizing eco-friendly products, and beverage companies are responding by adopting sustainable practices. For instance, Europe’s beverage industry is prioritizing sustainable packaging solutions to align with consumer expectations and regulatory requirements. Many brands are now focusing on sourcing coffee and tea from environmentally responsible farms, supporting fair trade, and reducing their carbon footprints. Additionally, there is a growing emphasis on eco-friendly packaging, with an increasing number of companies opting for recyclable, biodegradable, or compostable materials. This trend towards sustainability is not only driven by consumer preferences but also by regulatory pressures to reduce waste and promote environmental responsibility in the food and beverage industry.
Rise of Digital and Online Sales Channels
The rise of e-commerce and digital platforms is transforming the way caffeinated beverages are marketed and sold in Europe. Consumers are increasingly turning to online channels for purchasing their favorite caffeinated drinks, including RTD coffee, energy drinks, and specialty teas. Online retailers, including both major e-commerce platforms and niche health-focused websites, have made it easier for consumers to access a wider variety of products, often at competitive prices. In addition, many brands are utilizing social media and digital marketing strategies to engage directly with consumers, offering promotions, subscription services, and personalized product recommendations. This shift to digital sales channels is helping companies tap into new markets and reach a broader audience while catering to the growing demand for convenience and personalized shopping experiences.
Market Challenges Analysis
Health Concerns and Regulatory Pressure
A key challenge facing the European caffeinated beverage market is the increasing concern over the health impacts of high caffeine consumption. With growing awareness about the risks of excessive caffeine intake, such as potential adverse effects on heart health, sleep patterns, and overall well-being, consumers are becoming more cautious in their choices. For instance, the European Food Safety Authority (EFSA) has published guidelines on safe caffeine consumption levels, advising on potential risks associated with excessive intake. This trend is further compounded by stricter regulations being introduced across various European countries to limit caffeine content in certain products, particularly energy drinks. As governments tighten regulations and impose mandatory warning labels on high-caffeine beverages, manufacturers must adapt their product formulations to comply with these rules. This may involve reformulating beverages to reduce caffeine levels or creating new products that meet regulatory standards while still appealing to health-conscious consumers.
Intense Competition and Market Saturation
Another significant challenge is the intense competition and market saturation within the caffeinated beverage sector. With numerous brands vying for consumer attention, the market has become highly fragmented, making it difficult for new entrants to gain a foothold. Established companies, both global giants and regional players, dominate the market, leaving limited room for smaller or emerging brands. In addition, the fast pace of product innovation has led to an oversaturation of options, making it harder for brands to stand out. This competitive pressure not only intensifies marketing efforts but also increases the need for differentiation through unique flavors, healthier options, or sustainability initiatives. As competition grows and consumer expectations evolve, companies must continually innovate while managing costs and ensuring product quality to maintain a competitive edge.
Market Opportunities
The Europe Caffeinated Beverage market presents numerous opportunities for growth, particularly with the rising consumer demand for healthier and functional products. As consumers become more health-conscious, there is a growing interest in beverages that not only provide caffeine but also offer additional benefits such as vitamins, antioxidants, and adaptogens. Brands that can innovate by incorporating functional ingredients into their caffeinated beverages have a unique opportunity to cater to this expanding segment. Furthermore, the increasing preference for natural and organic ingredients presents a significant opportunity for companies to tap into the clean label trend, which focuses on transparent, healthy, and sustainably sourced products. This trend aligns with consumers' desire for beverages that are both energizing and beneficial to their overall well-being, presenting a clear pathway for market expansion.
Additionally, the rise of online sales channels and digital engagement offers significant opportunities for companies in the caffeinated beverage market. With the growing shift towards e-commerce, especially post-pandemic, beverage brands have the chance to expand their reach through online platforms. Direct-to-consumer models, subscription services, and personalized offerings enable companies to connect with a broader audience and cater to individual preferences. Moreover, social media and digital marketing present opportunities for brands to engage with younger demographics, who are increasingly inclined to purchase caffeinated beverages online. By leveraging these digital tools and platforms, brands can not only enhance visibility but also foster customer loyalty and drive sales. As the market continues to evolve, companies that embrace both innovation in product development and digital strategies will be well-positioned to capitalize on these opportunities.
Market Segmentation Analysis:
By Product:
The Europe Caffeinated Beverage market is segmented into four primary product categories: carbonated soft beverages, energy beverages, ready-to-drink (RTD) tea and coffee, and others. Among these, energy beverages continue to drive substantial growth due to their popularity with young adults, athletes, and busy professionals seeking quick energy boosts. The demand for energy drinks is fueled by their high caffeine content combined with ingredients like taurine and B-vitamins, which appeal to those leading active lifestyles. RTD tea and coffee have also gained traction, especially with the increasing preference for convenient, on-the-go beverages. These products offer both caffeine and additional health benefits, making them popular among health-conscious consumers. Carbonated soft beverages, traditionally a significant segment, are experiencing slower growth due to rising health concerns about sugar and artificial additives, pushing manufacturers to offer healthier alternatives. Other segments, including functional beverages with added vitamins or minerals, are growing as consumers seek more personalized options.
By Flavor:
In terms of flavor, the Europe Caffeinated Beverage market is divided into two main categories: natural and synthetic flavors. The natural flavor segment is experiencing increased demand due to the growing trend toward clean-label and healthier products. Consumers are becoming more aware of the ingredients in their beverages, opting for natural flavors derived from fruits, herbs, and other organic sources. This shift is especially evident in the RTD tea and coffee markets, where consumers seek beverages that taste authentic and offer additional health benefits. On the other hand, synthetic flavors remain prevalent in the energy beverage segment, where bold and unique flavors are often designed to stand out in a crowded market. Synthetic flavors are cost-effective and allow for a broader range of taste profiles. However, with increasing demand for natural, plant-based options, brands are beginning to balance both flavor types, incorporating natural ingredients where possible without compromising on taste.
Segments:
Based on Product:
- Carbonated Soft Beverage
- Energy Beverage
- RTD Tea and Coffee
- Others
Based on Flavor:
- Natural
- Synthetic
Based on Sales Channel:
- Offline
- Grocery Stores
- Convenience Stores
- Speciality Stores
- Other Retail Stores
- Online
Based on the Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
Regional Analysis
UK
UK holds a significant share of the Europe Caffeinated Beverage market, accounting for approximately 18% of the total market share. The country's strong coffee culture, coupled with increasing demand for energy drinks and ready-to-drink coffee, positions it as one of the largest markets in the region. The growing trend of convenience and health-conscious consumption has further fueled the market in the UK, with consumers opting for low-calorie, organic, and functional caffeinated beverages. The development of premium coffee options and energy drinks tailored to specific consumer needs is contributing to the market's expansion. Additionally, the rise of online sales channels and digital marketing strategies has allowed brands to reach a broader audience, making the UK a key market in the European caffeinated beverage sector.
Germany
Germany is another major player in the European market, holding a market share of around 15%. Known for its robust coffee culture, Germany remains a leader in the demand for both traditional coffee and innovative coffee-based beverages. The popularity of energy drinks and functional caffeinated beverages, particularly those with added health benefits, has also grown in recent years. Consumers in Germany are increasingly inclined toward products that offer a balance of taste and functionality, such as organic and low-sugar options. The market is also driven by a preference for high-quality coffee and the rise of specialty coffee shops. Germany's large consumer base, combined with its well-established retail networks, ensures its dominant position in the European caffeinated beverage market.
France
France, accounting for approximately 12% of the market share, is another important region for the Europe Caffeinated Beverage market. Coffee is deeply ingrained in French culture, and the demand for high-quality, gourmet coffee products continues to rise. RTD coffee and energy drinks are becoming increasingly popular, especially among younger consumers seeking convenience and functional benefits. Additionally, the trend toward healthier and more sustainable products is influencing purchasing decisions, with organic and low-sugar options gaining popularity. The market in France is supported by both a strong café culture and a growing retail landscape that caters to on-the-go consumers, positioning the country as a key player in the market.
Italy and Spain
In Southern Europe, Italy and Spain collectively account for approximately 20% of the market share. Italy's strong espresso culture and demand for premium coffee products drive its segment of the market. As consumers seek more convenient coffee options, the demand for RTD coffee is growing, particularly in urban areas. In Spain, energy drinks are particularly popular, with the younger demographic driving this demand. Both countries are witnessing an increasing shift toward healthier caffeinated beverages, such as functional drinks with added vitamins or antioxidants. The combination of traditional coffee culture and modern beverage preferences makes Southern Europe a region of significant opportunity for the caffeinated beverage market.
Key Player Analysis
- Nestlé
- Red Bull
- Arla Foods
- Britvic PLC
- PepsiCo
- The Coca-Cola Company
- 5-hour ENERGY
Competitive Analysis
The Europe Caffeinated Beverage market is highly competitive, with leading players like Nestlé, Red Bull, Arla Foods, Britvic PLC, PepsiCo, The Coca-Cola Company, and 5-hour ENERGY dominating the landscape. Nestlé leads with a diverse portfolio, including coffee-based beverages like Nescafé and premium offerings such as Starbucks-branded drinks, capitalizing on its strong distribution network. Competitive strategies often include the development of healthier alternatives, with a focus on low-calorie, low-sugar, and functional ingredients such as vitamins, antioxidants, and adaptogens. Additionally, brands are increasingly prioritizing sustainability, incorporating eco-friendly packaging and sourcing ingredients responsibly, in response to consumer demand for environmentally conscious products. Strong marketing campaigns, digital engagement, and celebrity endorsements are common tactics used to enhance brand visibility and consumer loyalty. As consumer preferences continue to shift toward personalized and on-the-go options, companies are also leveraging e-commerce platforms to expand their reach, offering subscription models and direct-to-consumer services. Innovation in flavor offerings and the expansion of product lines to include premium and organic options are essential for brands looking to maintain a competitive edge in this rapidly evolving market.
Recent Developments
- In March 2025, PepsiCo expanded its Pepsi MAX Caffeine Free line with a new 500ml bottle in the UK, responding to rising demand for caffeine-free and sugar-free colas among younger consumers.
- In February 2025, Coca-Cola introduced Simply Pop, a prebiotic, fruit juice-enriched soda targeting the “better-for-you” market segment, competing with brands like Poppi and Olipop.
- In January 2025, Nestlé implemented a new global organizational structure for its Waters & Premium Beverages division, operating as a standalone business.
- In June 2024, the Starbucks Corporation, one of the renowned brands in caffeinated beverages industry launched new range of Caramel Vanilla Swirl Iced Coffee, handcrafted energy drinks and few other products. Starbucks Tripleshot Energy drink, recently launched offering is characterized by 65mg of caffeine content, protein, B vitamins. The products is provided in three flavor choices including dark caramel, bold mocha, and rich vanilla.
- In February 2024, Dunkin’, one of the applauded brands in food & beverages industry introduced SPARKD' Energy by Dunkin’, iced beverages equipped with minerals, vitamins and some amount of caffeine. The flavors include berry burst entailing strawberry and raspberry, and peach sunshine featuring lychee and juicy peach flavors.
Market Concentration & Characteristics
The Europe Caffeinated Beverage market exhibits moderate to high concentration, with a few dominant players controlling a significant portion of the market share. Major companies like Nestlé, Red Bull, The Coca-Cola Company, PepsiCo, and Arla Foods hold a strong presence, supported by their extensive distribution networks and established brand recognition. However, the market also includes a growing number of regional and niche players offering unique, often health-focused products, creating a dynamic competitive environment. The market is characterized by innovation, with brands constantly introducing new flavors, functional ingredients, and healthier alternatives to cater to evolving consumer preferences. Convenience is a key factor driving growth, as busy lifestyles fuel demand for ready-to-drink (RTD) and on-the-go beverages. Additionally, sustainability is becoming increasingly important, with both large and small companies focusing on eco-friendly packaging and sustainable sourcing to appeal to environmentally conscious consumers. This mix of global leaders and emerging brands ensures a competitive and rapidly evolving market.
Report Coverage
The research report offers an in-depth analysis based on Product, Flavor, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for healthier, low-sugar, and organic caffeinated beverages will continue to rise as consumers become more health-conscious.
- Functional beverages with added vitamins, minerals, and adaptogens will see increased popularity, catering to wellness-focused consumers.
- Energy drinks will maintain strong growth, particularly among younger demographics and active individuals seeking a quick energy boost.
- The trend toward sustainability will drive more brands to adopt eco-friendly packaging and sustainable sourcing practices.
- Ready-to-drink (RTD) coffee and tea products will experience significant growth, fueled by consumer demand for convenience.
- Online sales and e-commerce platforms will become increasingly important, with direct-to-consumer models gaining traction.
- Brands will invest in innovative flavor profiles and premium products to differentiate themselves in a competitive market.
- Regional preferences will continue to shape product offerings, with companies tailoring their beverages to local tastes and cultural preferences.
- Personalization in beverages, such as customized drinks or subscription services, will gain popularity, providing consumers with more tailored options.
- Market consolidation may occur as larger companies acquire smaller, innovative brands to expand their portfolios and meet shifting consumer demands.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Functional and Healthier Beverages
European consumers are increasingly seeking caffeinated beverages that offer added health benefits, such as low-calorie, organic, and fortified options. This shift is driven by greater health consciousness and a desire for products that support wellness, fueling innovation and growth in the market.
Growth of On-the-Go and Convenience Consumption
Busy lifestyles and the need for quick energy boosts have led to a surge in demand for ready-to-drink (RTD) coffee, tea, and energy drinks. The popularity of portable, single-serve formats is expanding the market, especially among younger demographics and professionals.
Product Innovation and Diversification
Manufacturers are continuously introducing new flavors, functional ingredients (like adaptogens and vitamins), and premium offerings such as cold brew and specialty coffees. This innovation attracts consumers looking for variety and unique experiences, supporting market expansion.
Sustainability and Eco-Friendly Packaging
Increasing consumer and regulatory focus on sustainability is prompting brands to adopt recyclable, biodegradable, and compostable packaging, as well as responsibly sourced ingredients. These initiatives resonate with environmentally conscious consumers and enhance brand loyalty.
Expansion of Digital and E-Commerce Channels
The rise of online retail and direct-to-consumer models is making caffeinated beverages more accessible, allowing brands to reach a broader audience and offer personalized experiences. Digital marketing and subscription services are further driving sales and consumer engagement.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Caffeinated Beverage?
What factors are driving the growth of the Europe Caffeinated Beverage?
What are some challenges faced by the Europe Caffeinated Beverage?
Who are the major players in the Europe Caffeinated Beverage?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Flavor
- 1.2.1 Natural
- 1.2.2 Synthetic
- 1.3 By Product
- 1.3.1 Carbonated Soft Beverage
- 1.3.2 Energy Beverage
- 1.3.3 RTD Tea and Coffee
- 1.3.4 Others
- 1.4 By Sales Channel
- 1.4.1 Offline
- 1.4.2 Grocery Stores
- 1.4.3 Convenience Stores
- 1.4.4 Speciality Stores
- 1.4.5 Other Retail Stores
- 1.4.6 Online
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 66,440.56 million → 2032: USD 92,025.58 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Caffeinated Beverage Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Caffeinated Beverage Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Caffeinated Beverage Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Caffeinated Beverage Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Caffeinated Beverage Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Caffeinated Beverage Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Caffeinated Beverage Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Caffeinated Beverage Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 66,440.56 million → 2032: USD 92,025.58 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Caffeinated Beverage Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Flavor - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Natural
- 12.3.7.2 Synthetic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Carbonated Soft Beverage
- 12.4.7.2 Energy Beverage
- 12.4.7.3 RTD Tea and Coffee
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Offline
- 12.5.7.2 Grocery Stores
- 12.5.7.3 Convenience Stores
- 12.5.7.4 Speciality Stores
- 12.5.7.5 Other Retail Stores
- 12.5.7.6 Online
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Caffeinated Beverage Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Europe Caffeinated Beverage Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Europe Caffeinated Beverage Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Nestlé
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Red Bull
- 17.4 Arla Foods
- 17.5 Britvic PLC
- 17.6 PepsiCo
- 17.7 The Coca-Cola Company
- 17.8 5-hour ENERGY
- 17.9 Monster Beverage Corporation
- 17.10 Starbucks Corporation
- 17.11 Danone
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

