
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Elevator Modernization Market Size 2023 | USD 3,552.58 million |
| Europe Elevator Modernization Market, CAGR | 11.75% |
| Europe Elevator Modernization Market Size 2032 | USD 8,637.15 million |
Market Overview
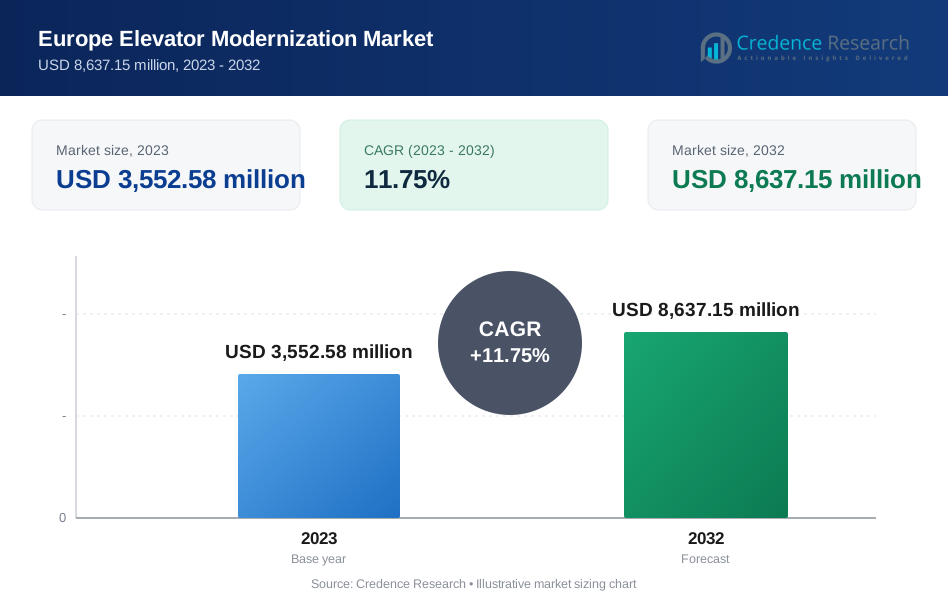
The Europe Elevator Modernization market is projected to grow from USD 3,552.58 million in 2023 to USD 8,637.15 million by 2032, at a compound annual growth rate (CAGR) of 11.75%.
The Europe Elevator Modernization market is driven by the increasing demand for energy-efficient solutions and the growing need to enhance the safety and performance of aging elevator systems. As urbanization accelerates, there is a rising focus on upgrading older buildings to meet modern standards, improving accessibility, and ensuring compliance with stringent regulations. Additionally, the adoption of smart elevator technologies, such as IoT integration and predictive maintenance, is gaining traction, offering enhanced operational efficiency and reducing downtime. Environmental concerns are also pushing the market towards sustainable solutions, with energy-efficient elevator systems contributing to lower carbon footprints. Furthermore, advancements in digitalization, such as remote monitoring and data analytics, are transforming the modernization process, enabling real-time performance tracking and optimization. These trends are expected to drive the market’s growth, as businesses and residential complexes prioritize modernization to meet the evolving demands of the built environment.
The Europe Elevator Modernization market is driven by demand across various regions, with Western Europe, particularly Germany and the UK, leading the charge due to their robust construction and renovation sectors. Germany, with its advanced manufacturing and strict regulations on energy efficiency, plays a pivotal role in shaping the market. The UK, with its focus on sustainability and smart building integration, also significantly contributes to market growth. Southern European nations like Italy and Spain are seeing steady progress in modernization driven by urban regeneration projects and energy-efficient solutions. In Eastern Europe, countries like Russia, Poland, and Sweden are gradually adopting modernization efforts, spurred by increasing urbanization and sustainability initiatives. Key players in the market include KONE Corporation, Schindler Group, Thyssenkrupp AG, Otis Elevator Company, and Orona Group, among others. These companies are at the forefront of providing innovative solutions in energy-efficient and smart elevator systems.
Market Insights
- The Europe Elevator Modernization market was valued at USD 3,552.58 million in 2023 and is expected to reach USD 8,637.15 million by 2032, growing at a CAGR of 11.75%.
- Increasing demand for energy-efficient and smart elevators is a key market driver, as building owners focus on sustainability.
- Urbanization and the need for infrastructure upgrades across Europe are significantly fueling the modernization market.
- Smart elevator integration with IoT and AI is emerging as a key trend, offering better efficiency and user experience.
- The market is highly competitive, with key players such as KONE Corporation, Schindler Group, and Otis Elevator Company dominating the landscape.
- High initial investment costs and potential disruption to building operations during modernization are major market restraints.
- Western Europe, led by Germany and the UK, holds the largest market share, followed by steady growth in Southern and Eastern Europe regions.
Market Drivers
Growing Demand for Energy Efficiency
The increasing emphasis on energy efficiency is one of the key drivers of the Europe Elevator Modernization market. With rising energy costs and environmental concerns, building owners are seeking ways to reduce energy consumption. Modernizing elevators with energy-efficient technologies, such as LED lighting, regenerative drives, and efficient motors, allows buildings to lower their carbon footprints and operating costs. For instance, the European Lift Association (ELA) states that energy-efficient elevators can cut energy use by up to 50%. The European Union’s stringent environmental regulations and incentives further fuel this demand, making elevator modernization a cost-effective and sustainable choice for property owners.
Safety and Compliance with Regulations
Safety is a critical factor driving elevator modernization in Europe. As older elevator systems age, their safety standards may become outdated, potentially posing risks to building occupants. Regulatory changes, such as the European Lift Directive, mandate regular safety inspections and updates to ensure compliance with current standards. For instance, Directive 2014/33/EU establishes essential safety requirements and conformity assessment procedures for lifts and safety components within the European Union. Modernizing elevators not only enhances safety but also ensures compliance with legal requirements, reducing the risk of fines or liability issues. Upgraded systems with advanced safety features, such as emergency communication systems and anti-vandalism technologies, further enhance building security.
Technological Advancements
Technological innovations in elevator systems are revolutionizing the modernization market in Europe. The integration of smart technologies, such as IoT-enabled elevators, predictive maintenance systems, and AI-powered data analytics, enhances operational efficiency and reliability. These advancements allow building managers to monitor elevator performance in real-time, identify potential issues before they occur, and optimize energy consumption. As these technologies become more affordable and accessible, property owners are increasingly investing in elevator upgrades to stay competitive and ensure smoother, faster, and more efficient transportation within buildings.
Urbanization and Building Renovations
The rapid pace of urbanization and the need for building renovations are significant drivers of the elevator modernization market. As cities grow, many older buildings require modernization to meet current standards and accommodate the increasing demand for vertical transportation. Upgrading elevators improves building functionality, enhances accessibility, and adds value to properties. With more buildings undergoing renovations to meet modern requirements, elevator modernization has become a critical component of the redevelopment process, driving sustained market growth across Europe.
Market Trends
Integration of Smart Technologies
A key trend in the Europe Elevator Modernization market is the increasing integration of smart technologies. IoT-enabled elevators, equipped with sensors and connectivity features, allow real-time monitoring and predictive maintenance. These elevators can collect data on usage patterns, performance, and potential issues, enabling proactive repairs and minimizing downtime. For instance, Bosch's smart elevator management solutions offer real-time monitoring and predictive maintenance, enhancing operational efficiency and reducing downtime. Additionally, AI-driven analytics optimize energy usage and efficiency, making elevator systems more responsive and intelligent. As demand for smart building solutions rises, elevator modernization increasingly includes these advanced technologies to improve both operational efficiency and the user experience.
Personalized User Experiences
Elevator modernization is also driven by the demand for enhanced user experiences. Customized elevator solutions are becoming more common, with features such as personalized user interfaces, voice activation, and touchless controls gaining popularity. These upgrades not only improve convenience but also cater to the needs of a more tech-savvy and health-conscious user base. Touchless technologies, for example, are especially relevant in the post-pandemic era, as building owners prioritize hygiene and safety in their modernization efforts. For instance, touchless elevator controls have become increasingly popular to enhance hygiene and user convenience. Such enhancements contribute to a smoother, more comfortable ride for passengers and meet the evolving expectations of building occupants.
Focus on Sustainability and Green Solutions
Sustainability continues to be a prominent trend in the elevator modernization market, with a growing focus on eco-friendly and energy-efficient solutions. Regenerative drives, energy-saving LED lighting, and low-power standby modes are becoming standard features in modernized elevators. These technologies reduce the overall energy consumption of elevator systems, contributing to lower operational costs and reduced carbon emissions. As regulations on energy efficiency become more stringent, elevator modernization serves as a cost-effective strategy for achieving sustainability goals while ensuring compliance with green building certifications like BREEAM and LEED.
Retrofitting and Flexibility in Design
Another notable trend in Europe’s elevator modernization market is the increased focus on retrofitting and flexible design solutions. Property owners are opting to modernize existing elevator systems rather than replace them entirely, making retrofitting an attractive option. This approach allows for cost savings while still benefiting from the latest technologies and improvements in safety, efficiency, and design. Additionally, flexible designs that accommodate various building types and requirements are gaining traction, as elevator systems must be tailored to fit diverse structural constraints and performance needs. This trend ensures that elevator modernization projects can be adapted to a wide range of buildings, from historical landmarks to new constructions.
Market Challenges Analysis
High Initial Investment and Budget Constraints
One of the key challenges in the Europe Elevator Modernization market is the high initial investment required for upgrades. While modernizing elevators offers long-term benefits such as improved efficiency and reduced operating costs, the upfront costs of advanced technologies, such as smart systems and energy-efficient components, can be substantial. Many property owners, especially in older buildings, may face budget constraints that limit their ability to invest in full-scale modernization projects. For instance, the initial investment for purchasing and installing elevators or escalators can be substantial, especially for high-rise buildings or large-scale infrastructure projects. This challenge is particularly relevant in smaller commercial properties or residential buildings where the return on investment may not be immediately evident. Despite the long-term savings, securing financing for modernization efforts remains a significant hurdle in the market.
Disruption to Building Operations
Another challenge faced during elevator modernization is the potential disruption to building operations. Elevator upgrades often require significant downtime, which can cause inconvenience for building occupants, especially in high-traffic buildings like office complexes and residential towers. The logistics of carrying out the modernization work without disrupting daily activities, such as coordinating downtime, managing access to floors, and ensuring safety, can be complex. Additionally, in densely populated urban areas, obtaining the necessary permits and approvals for modernization can further delay the process. Property owners must carefully balance the need for modernization with minimizing disruption to their tenants and ensuring that building operations continue smoothly.
Market Opportunities
Growth in Smart Building Infrastructure
The growing trend towards smart buildings presents significant opportunities for the Europe Elevator Modernization market. As more buildings adopt smart technologies, the integration of elevators with advanced systems such as IoT, AI, and predictive analytics becomes increasingly important. Modernized elevators equipped with smart features can optimize performance, enhance energy efficiency, and improve the overall user experience. Building owners are increasingly looking for ways to integrate elevators with their broader smart building infrastructure, offering opportunities for elevator manufacturers and service providers to offer tailored modernization solutions. With the growing demand for interconnected and intelligent building systems, this shift opens up new avenues for innovation and market expansion.
Focus on Retrofitting and Sustainability Initiatives
As sustainability becomes a top priority for property owners and developers, retrofitting existing elevator systems presents a lucrative opportunity in the Europe Elevator Modernization market. Retrofitting allows building owners to upgrade their systems to meet current energy efficiency and safety standards without the need for a complete overhaul. As environmental regulations tighten and green building certifications become more prevalent, the demand for energy-efficient elevator systems will continue to rise. Elevator modernization, with a focus on reducing energy consumption and lowering carbon footprints, aligns with these sustainability goals. By offering cost-effective and eco-friendly modernization solutions, businesses in the elevator sector can capitalize on the growing trend towards environmentally conscious building practices and secure a competitive edge in the market.
Market Segmentation Analysis:
By Type:
The Europe Elevator Modernization market is segmented by elevator type, including traction systems, hydraulic systems, and machine room-less (MRL) elevators. Traction systems dominate the market due to their energy efficiency, smooth operation, and suitability for high-rise buildings. As the demand for vertical transportation increases in urban centers, modernization efforts in traction systems focus on improving speed, energy consumption, and safety features. Hydraulic elevators, which are more common in low- to mid-rise buildings, are also undergoing modernization to enhance efficiency and reduce maintenance costs. On the other hand, MRL elevators, which eliminate the need for a machine room, are gaining popularity in new and existing buildings due to their space-saving design and energy efficiency. Modernizing MRL systems enhances their performance, offering an attractive solution for space-conscious buildings. Each system has distinct advantages that cater to different building requirements, driving demand for specific modernization solutions across Europe.
By Application:
The application segment of the Europe Elevator Modernization market includes residential, commercial, industrial, and institutional buildings. Residential buildings, particularly in densely populated urban areas, are driving the demand for modernization to accommodate higher traffic volumes, improve energy efficiency, and enhance the user experience with advanced features like smart controls and safety systems. Commercial buildings, including offices and retail spaces, focus on upgrading elevator systems for better performance, aesthetics, and compliance with accessibility regulations. In industrial buildings, the need for durable and high-capacity elevators that can handle heavy loads is fueling modernization efforts. Lastly, institutional buildings, such as hospitals and educational facilities, require elevators that meet strict safety standards while offering efficient and reliable transportation for a diverse range of users. Each application type presents unique demands for elevator upgrades, further contributing to the overall growth of the modernization market across Europe.
Segments:
Based on Type:
- Traction System
- Hydraulic System
- Machine Room-Less (MRL) Elevators
Based on Application:
- Residential Buildings
- Commercial Buildings
- Industrial Buildings
- Institutional Buildings
Based on Component:
- Control System
- Door System
- Cab Enclosure
- Power Units
- Others
Based on the Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
Regional Analysis
Western Europe: Germany and the UK
Germany leads the Europe Elevator Modernization market with a market share of around 30%, driven by its robust manufacturing industry, high urban density, and stringent regulations for building safety and energy efficiency. The country has made significant strides in smart building integration, with increasing demand for IoT-enabled elevators and energy-efficient solutions. Modernization projects are particularly prevalent in large commercial complexes and residential buildings, where demand for improved accessibility and enhanced safety features is high. The UK, with its focus on retrofitting buildings to meet sustainability targets, holds approximately 25% of the market share. The demand for energy-efficient, smart elevator systems is further fueled by regulations such as the UK’s energy efficiency standards and the push toward green building certifications.
Southern Europe: Italy and Spain
Southern Europe, with key players in Italy and Spain, holds around 15% of the Europe Elevator Modernization market. In Italy, ongoing urban regeneration projects, particularly in historic buildings, have contributed to a rising demand for elevator upgrades. Modernization efforts in these regions focus on energy efficiency, safety, and space optimization, with a focus on hydraulic and MRL systems. Spain, which has seen a resurgence in construction and renovation activities, contributes approximately 10% of the market share. The Spanish market is driven by government incentives for energy-efficient technologies and the increasing adoption of smart building systems, making it an attractive region for modernization investments.
Eastern and Northern Europe: Russia, Sweden, and Poland
Eastern and Northern Europe represent approximately 20% of the market share, with Russia, Sweden, and Poland contributing to steady growth. Russia, despite economic challenges, still represents a significant portion of the market, with modernization efforts focused on upgrading aging systems in residential and commercial buildings. Sweden and Poland, with a growing emphasis on sustainability and energy-efficient elevator systems, contribute about 10% and 8% of the market share, respectively. Sweden’s commitment to reducing carbon emissions and Poland’s increasing urbanization have accelerated the demand for modernized elevator solutions, particularly in commercial and institutional buildings. The market share in these regions is expected to grow steadily as urbanization and building modernization projects increase, along with the adoption of eco-friendly elevator technologies.
Key Player Analysis
- KONE Corporation
- Schindler Group
- Thyssenkrupp AG
- Otis Elevator Company
- Orona Group
- Stannah Lifts Holdings Ltd
- Wittur Group
- Sicher Elevator Co., Ltd.
- Ascendor GmbH
- Kleemann Hellas SA
Competitive Analysis
The Europe Elevator Modernization market is highly competitive, with several leading players contributing to the market's growth. KONE Corporation, Schindler Group, Thyssenkrupp AG, Otis Elevator Company, Orona Group, Stannah Lifts Holdings Ltd, Wittur Group, Sicher Elevator Co., Ltd., Ascendor GmbH, and Kleemann Hellas SA are some of the key players that dominate the industry. These companies focus on delivering advanced modernization services that include energy-efficient systems, smart elevators, and enhanced safety features. Market leaders are increasingly adopting cutting-edge technologies such as IoT, AI integration, and predictive maintenance to meet the rising demand for intelligent, sustainable elevator solutions.
For instance, Schindler introduced a modular lift generation equipped with touchless technology, improved connectivity, and additional digital services. Innovation plays a crucial role in gaining a competitive edge, with a strong emphasis on integrating smart controls and energy-saving features in modernization projects. Companies are also focusing on sustainability by offering eco-friendly solutions that align with the growing demand for energy-efficient building systems across Europe. Furthermore, many players are expanding their service offerings through partnerships and acquisitions to enhance their regional presence and broaden their product portfolios. As the market grows, differentiation through technology and customized solutions is becoming increasingly important. Companies are also striving to meet evolving safety regulations and the specific needs of various building types, ranging from residential to commercial and industrial properties. The competition remains dynamic, with constant efforts to improve service quality, operational efficiency, and customer satisfaction.
Recent Developments
- In December 2024, Fujitec Indonesia successfully delivered 19 modernized elevators to the iconic Wisma 46office building in Jakarta. This modernization includes the introduction of the EZSHUTTLE destination dispatch system, which automates elevator assignments based on passenger destinations, improving operational efficiency.
- In October 2024, Otis Elevator announced its involvement in the modernization of elevators at the Eiffel Towerin Paris, enhancing the duolift™ elevators that serve millions of visitors annually. Additionally, they are set to begin modernization work at the Burj Khalifa in Dubai, which will include a 10-year maintenance and upgrading contract for 34 elevators.
- In September 2024, KONE Corporation unveiled its ambitious strategy called "Rise" for 2025-2030, which emphasizes driving modernization to unlock growth opportunities and enhance customer experiences. This strategy includes a focus on digital transformation and sustainability initiatives.
- In September 2024, Thyssenkrupp AG (TK Elevator) was awarded a contract to modernize escalators for the Cologne subway system in Germany. The project includes installing 23 victoria-type escalators equipped with MAX Smart Maintenance technology, which aims to reduce maintenance efforts and enhance operational efficiency.
Market Concentration & Characteristics
The Europe Elevator Modernization market exhibits a moderately concentrated structure, with a few large players holding a significant share while numerous smaller companies cater to niche segments. The market is driven by a combination of well-established global firms and regional players offering tailored solutions for specific building types and modernization needs. Key players focus on high-quality, energy-efficient modernization services, incorporating advanced technologies like smart controls, IoT integration, and predictive maintenance systems. This focus on innovation is a key characteristic, as companies aim to differentiate themselves by offering more sustainable, reliable, and cost-effective solutions. The market's competitive nature is further enhanced by the increasing demand for eco-friendly systems, which encourages both large and smaller players to invest in green technologies. Additionally, the market is characterized by a diverse range of applications, from residential buildings to large-scale commercial and industrial properties, which requires companies to offer customized solutions for each segment. Furthermore, regional regulations and government incentives for energy-efficient solutions are influencing the strategies of key market players, with many expanding their portfolios and services to meet evolving compliance standards. The market is expected to continue evolving as companies invest in digital transformation and smart building technologies to stay competitive and meet the growing demand for modernization.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Component and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europe Elevator Modernization market is expected to continue growing due to the increasing demand for energy-efficient and smart building solutions.
- Government regulations and incentives promoting sustainability will drive further adoption of eco-friendly elevator modernization technologies.
- The rise of smart buildings and IoT integration will lead to a higher demand for advanced elevator systems that enhance user experience and operational efficiency.
- As urbanization continues, the need to modernize aging infrastructures in both residential and commercial buildings will increase.
- The integration of AI and predictive maintenance in elevators will revolutionize the market, reducing downtime and enhancing service reliability.
- Market players will increasingly focus on providing customized solutions to meet the specific needs of different building types and regions.
- The emphasis on safety features and regulatory compliance will drive investments in advanced elevator systems with improved safety protocols.
- Growing concerns around climate change will push more building owners to invest in energy-efficient elevator modernization solutions to reduce their carbon footprint.
- The demand for machine room-less (MRL) elevators will rise due to space-saving advantages and lower energy consumption.
- Partnerships, mergers, and acquisitions will become more common as companies look to expand their regional presence and enhance technological offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Elevator Modernization market?
What factors are driving the growth of the Europe Elevator Modernization market?
What are the key segments within the Europe Elevator Modernization market?
What are some challenges faced by the Europe Elevator Modernization market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Elevator Modernization Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Region & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Europe Elevator Modernization Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 3,552.58 million → 2032: USD 8,637.15 million)
- 2.1.2 Volume & Revenue – Regional Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Elevator Modernization Segmentation Snapshot
- 2.2.1 Market Split by Country – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Elevator Modernization Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Elevator Modernization Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Country
- 3.2 Europe Elevator Modernization Drivers
- 3.3 Europe Elevator Modernization Restraints & Challenges
- 3.4 Europe Elevator Modernization Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Elevator Modernization Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Elevator Modernization Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regional & Country Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Elevator Modernization category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Elevator Modernization Attractiveness Analysis
- 4.1.1 By Country – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Country – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Country – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Country Opportunity Scorecards
- 4.5.1 Priority Country 1
- 4.5.2 Priority Country 2
- 4.5.3 Priority Country 3
- 4.5.4 Priority Country 4
Note: Priority countries are selected from within the region covered by the study. Numbered entries are indicative and are populated with relevant country names based on market size, growth potential, and strategic relevance.
Chapter 5. Europe Elevator Modernization Cross-Border Trade & Market Access Analysis
- 5.1 Intra-Regional & Extra-Regional Trade Overview
- 5.1.1 Regional Export Value by Country (2023)
- 5.1.2 Regional Export Volume by Country (2023) (Volume Where Applicable)
- 5.1.3 Regional Import Value by Country (2023)
- 5.1.4 Regional Import Volume by Country (2023) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: Cross-border analysis applies where relevant to Europe Elevator Modernization. Country trade flows distinguish intra-regional activity from trade with markets outside the region. Regional external trade totals exclude intra-regional flows to avoid double counting. Classifications and transaction measures follow the market scope; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Elevator Modernization Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Elevator Modernization Share Analysis – 2023
- 6.2.1 Regional Revenue Share by Company
- 6.2.2 Regional Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Country
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Regional Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Europe Elevator Modernization Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure by Country Within the Region
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Elevator Modernization (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Europe Elevator Modernization
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Europe Elevator Modernization – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Country Market Analysis – Regional Overview
- 8.1 Country Market Overview Within the Region
- 8.1.1 Country Volume Share Within the Region (Where Applicable)
- 8.1.2 Country Revenue Share Within the Region
- 8.1.3 Market Volume by Country (Where Applicable)
- 8.1.4 Market Revenue by Country
- 8.1.5 Country Forecasts Through 2032
- 8.2 Cross-Country Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Europe Elevator Modernization – Priority Country 1
Chapter 10. Europe Elevator Modernization – Priority Country 2
Chapter 11. Europe Elevator Modernization – Priority Country 3
Chapter 12. Europe Elevator Modernization – Priority Country 4
Chapter 13. Europe Elevator Modernization Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Regional Market Focus & Country Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – Country-Level Estimates & Regional Aggregation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
