
Market Overview
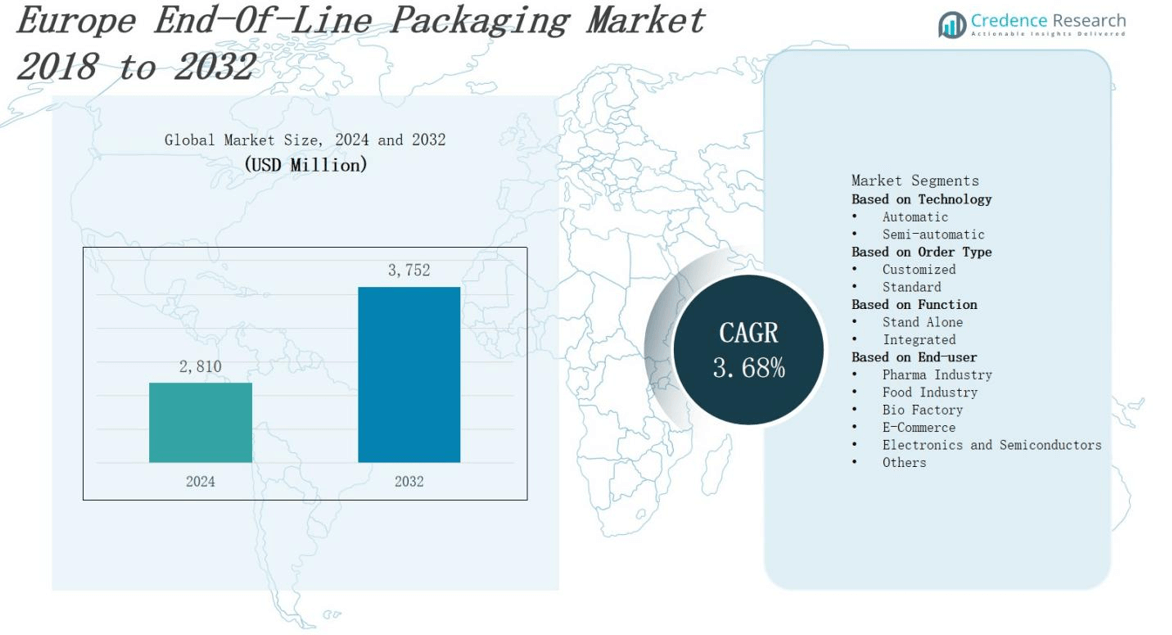
In 2024, the Europe end‑of‑line packaging market was valued at USD 2,810 million and is projected to reach USD 3,752 million by 2032, reflecting a CAGR of 3.68%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe End Of Line Packaging Market Size 2024 | USD 2,810 million |
| Europe End Of Line Packaging Market, CAGR | 3.68% |
| Europe End Of Line Packaging Market Size 2032 | USD 3,752 million |
Manufacturers in the Europe end‑of‑line packaging market drive growth through automation investments, robotics and smart conveyors that improve throughput and reduce labor costs. Rising e‑commerce volumes prompt adoption of integrated labeling, wrapping and palletizing solutions to meet fast delivery expectations. Stricter sustainability regulations encourage use of recyclable materials and energy‑efficient machinery. Digitalization enables real‑time monitoring and predictive maintenance that minimize downtime. Customization demands drive flexible packaging lines capable of handling diverse product formats. Labor shortages reinforce demand for automated systems. Manufacturers leverage Industry 4.0 technologies and collaborative robots to enhance operational efficiency and align with evolving regulatory and consumer expectations.
Western Europe leads with 50% share and high adoption of automated palletizing solutions, driven by Robert Bosch GmbH and OPTIMA Packaging Group GmbH. Northern Europe holds 30% share and prioritizes sustainable wrappers and robotics from Festo Inc and Fromm Group. Eastern Europe accounts for 20% share, where Endoline Machinery Ltd and RADPAK modernize lines with retrofit kits. The Europe end‑of‑line packaging market features modular conveyors by Flex Link and Quin Systems Ltd. Coesia Group, B&R and DS Smith compete on integrated labeling and wrap cells. Shemesh Automation LTD offers specialized end‑of‑line solutions.
Market Insights
- In 2024, the Europe end‑of‑line packaging market reached USD 2,810 million and it will attain USD 3,752 million by 2032 at a 3.68% CAGR.
- It drives growth through automation investments, robotics and smart conveyors that improve throughput and reduce labor costs in the Europe end‑of‑line packaging market.
- Rising e‑commerce volumes prompt integrated labeling, wrapping and palletizing solutions to meet fast delivery expectations in the Europe end‑of‑line packaging market.
- Stricter sustainability regulations encourage recyclable materials and energy‑efficient machinery across the Europe end‑of‑line packaging market.
- Digitalization enables real‑time monitoring and predictive maintenance that minimize downtime in the Europe end‑of‑line packaging market.
- Western Europe leads with 50% share, Northern Europe follows with 30%, and Eastern Europe holds 20% in the Europe end‑of‑line packaging market.
- It leverages modular, scalable lines and retrofit solutions to support diverse formats and extend machine lifecycles in the Europe end‑of‑line packaging market.
Market Drivers
Automation and Efficiency
Manufacturers invest in robotics and smart conveyors to improve throughput and reduce labor costs. It responds to rising wage pressure across the region. The Europe end‑of‑line packaging market benefits from modular systems that adapt to seasonal demand. Operators achieve faster cycle times and lower error rates. Automated palletizing and wrapping machines handle high volumes with minimal supervision. It supports workforce shortages by shifting manual tasks to machines.
E‑Commerce and Delivery Pressure
Online retail growth fuels demand for rapid order fulfilment and integrated labelling solutions. The Europe end‑of‑line packaging market gains from inline printers that apply shipping information at high speeds. Providers offer scalable modules that integrate with warehouse management systems. Customers expect accurate labelling, swift shrink wrapping and secure pallet attachments. It cuts lead time between packing and dispatch. Companies deploy turnkey lines to satisfy tight delivery windows.
Sustainability and Compliance
Regulatory mandates push equipment manufacturers to use recyclable materials and energy‑efficient motors. The Europe end‑of‑line packaging market adapts by offering lightweight film wrappers and eco‑friendly stretch films. It meets strict emissions standards and waste reduction targets. OEMs design machines with lower power consumption and recyclable components. Customers seek equipment that complies with circular economy policies. Suppliers routinely audit lifecycle footprint and certify machinery under recent EU directives.
- For instance, Baumüller has introduced high-torque electric motors with over 90% efficiency, replacing hydraulic drives in shredders to significantly reduce energy consumption and raw material use, while incorporating liquid cooling systems that enhance power density and enable heat reuse for other applications.
Digitalization and Flexibility
Advanced control systems with real‑time monitoring and predictive maintenance minimize downtime and extend machine life. The Europe end‑of‑line packaging market leverages IoT platforms to track performance metrics and schedule service interventions. Operators adjust line speed and format without halting production. It supports quick format changeovers and volume shifts. Vendors integrate touchscreen interfaces and cloud reporting tools. Companies gain full visibility and efficient troubleshooting across complex packaging lines.
- For instance, Johnson & Johnson integrated automation and digitalization through a unified data architecture on their packaging lines, reducing material waste by 18% and increasing production speed by 30%.
Market Trends
Rise of Modular, Scalable Packaging Lines
Manufacturers deploy modular line architectures that adapt to volume shifts and format changes. The Europe end‑of‑line packaging market experiences demand for preconfigured modules that integrate palletizing, labelling and wrapping. It enables rapid line scale‑up without major capital overhaul. Providers sell plug‑and‑play units that accelerate installation and commissioning. Production leads choose modular systems to avoid production stops. It reduces risk by isolating maintenance to specific modules.
- For instance, ABB offers plug-and-play robotic palletizing cells that speed up installation and commissioning, reducing downtime substantially.
Integration of Collaborative Robots and Humans
Collaboration between robotics and human operators drives efficiency gains. The Europe end‑of‑line packaging market integrates collaborative robots that handle varied unit loads and adjust to line pace. It frees workers from repetitive tasks and scales throughput. System designers embed safety features that enable human‑machine interaction. Early adopters report lower cycle times and higher uptime. It fosters workforce reskilling and redirects labor to quality control.
- For instance, in warehouse operations, cobots optimize picking routes and handle heavy loads, enabling human workers to focus on complex tasks, which can double or even triple productivity while reducing physical fatigue.
Adoption of Predictive Maintenance and Analytics
Connectivity between equipment and cloud platforms drives predictive interventions. The Europe end‑of‑line packaging market connects PLCs and sensors to real‑time analytics dashboards. It triggers maintenance alerts before breakdowns occur. Service teams schedule repairs during planned stops and preserve line availability. Data scientists fine‑tune algorithms that calculate asset health scores. It optimizes spare‑parts inventory and prolongs machinery lifecycle. End users gain clear visibility into performance metrics.
Embrace of Sustainable, Mono‑Material Wrappers
Demand for recyclable films and bio‑based wrap propels material innovation. The Europe end‑of‑line packaging market embraces mono‑material structures that simplify recycling. It tests compostable films and minimize waste streams. Machine vendors adapt roll dispensers and seal jaws to handle new substrates. Sustainability leads audit machinery energy consumption and seek certified components. It aligns equipment selection with corporate net‑zero ambitions. Clients compare lifecycle assessments when selecting packaging lines.
Market Challenges Analysis
Complex Regulatory and Compliance Requirements
Manufacturers face stricter waste directives and extended producer responsibility schemes across Europe. The Europe end‑of‑line packaging market must adapt to Packaging and Packaging Waste Regulation revisions and updated operational guidelines. It requires rapid updates to machinery, documentation and quality protocols. New certification demands slow equipment deployment and cross‑border coordination. Companies invest in audit processes and traceability systems to prove compliance and align with sustainability goals. It exposes OEMs to fines, reputational risks and project delays if inspections fail. Stakeholders struggle with varied national interpretations of EU codes and enforcement timelines.
High Capital Investment and Integration Complexity
Automated line deployment triggers large upfront expenditures for robotics, conveyors and control systems. The Europe end‑of‑line packaging market burdens operators with high lease or purchase costs and substantial maintenance support agreements. It challenges mid‑sized companies with limited budgets and resource constraints. Integrators must align new equipment with legacy IT, PLC architectures and enterprise software. Firms allocate resources to system training, pilot runs and extensive integration testing. It exposes projects to schedule slippage, technical hurdles and cost overruns. Vendors negotiate financing plans and extended service contracts, yet tight margins persist across supply chains.
Market Opportunities
Expansion of Smart Packaging Services
Manufacturers integrate digital serialization and track‑and‑trace solutions into end‑of‑line operations. The Europe end‑of‑line packaging market benefits from service contracts that include remote monitoring and performance analytics. It creates recurring revenue for OEMs. Software partnerships enable subscription offerings and software updates. Clients gain visibility across supply chains and speed recalls. OEMs can bundle installation, training and support packages. Providers strengthen customer relationships through data insights and proactive maintenance plans.
Growth in Retrofit and Upgrade Solutions
Industry players target aging packaging lines with modernization kits and control system replacements. The Europe end‑of‑line packaging market sees demand for modular upgrades that avoid full system purchases. It lowers capital burden for mid‑sized operators. Integrators supply plug‑in modules for robotics, sensors and HMI panels. Clients select phased implementation and finance plans. OEMs extend machine lifecycle and performance. Providers establish aftermarket channels for spare parts and training services.
Market Segmentation Analysis:
By Technology
Manufacturers deploy automatic systems to handle high volumes with consistent speed and precision. The Europe end‑of‑line packaging market favors fully automatic solutions for food, beverage and pharmaceutical lines with minimal manual input. Semi‑automatic equipment serves niche operations that require lower capital and flexible production. Suppliers offer convertibility between modes to meet seasonal demand. It reduces downtime and simplifies maintenance through standardized components. OEMs support hybrids that shift between manual and automated tasks.
- For instance, Coca-Cola Europacific Partners Germany commissioned three high-speed Krones lines in Lüneburg, including a glass bottling system capable of processing 60,000 containers per hour, highlighting the demand for fully automatic, high-throughput solutions.
By Order Type
Clients specify customized lines that adapt to unique product dimensions and labeling requirements. The Europe end‑of‑line packaging market experiences rising orders for tailored configurations that support brand identity and small‑batch production. Standard systems dominate high‑volume lines with proven reliability and lower price points. Suppliers maintain core platforms that integrate popular modules across orders. It streamlines commissioning through repeatable designs and robust support networks. OEMs expand service offerings to include rapid configuration adjustments.
- Fpr instance, Rovema GmbH helped Myllyn Paras, a traditional Finnish food company, by installing modular packaging machines that allow easy switching between bag shapes and formats, including paper packaging, supporting sustainability and small-batch production needs.
By Function
Operators select stand‑alone machines for targeted functions such as wrapping or palletizing where line integration proves unnecessary. The Europe end‑of‑line packaging market shows strong demand for integrated solutions that combine labeling, coding and wrapping in continuous workflows. It reduces floor space by consolidating tasks into unified cells. Providers design scalable cells that support multiple functions without separate modules. Clients benefit from single‑vendor accountability and faster troubleshooting. OEMs highlight turnkey systems that simplify project management.
Segments:
Based on Technology
- Automatic
- Semi-automatic
Based on Order Type
- Customized
- Standard
Based on Function
- Stand Alone
- Integrated
Based on End-user
- Pharma Industry
- Food Industry
- Bio Factory
- E-Commerce
- Electronics and Semiconductors
- Others
Based on the Region:
- Europe
- Germany
- France
- U.K.
- Italy
- Poland
- Spain
- Sweden
- Rest of Europe
Regional Analysis
Western Europe
Western Europe commands 50% share of the Europe end‑of‑line packaging market. Germany drives demand for automatic palletizing solutions and conveyors. Major OEMs install new lines in packaging facilities to meet high throughput needs. It benefits from robust manufacturing hubs and advanced logistics networks. France and the UK invest in digital labeling modules to improve traceability. Clients prioritize energy‑efficient machines that reduce operational costs. Stakeholders expand retrofit projects to modernize aging lines.
Northern Europe
Northern Europe holds 30% share of the Europe end‑of‑line packaging market. It focuses on compliance with strict environmental standards and carbon reduction targets. Sweden and Denmark adopt mono‑material wrappers and compostable films. Operators deploy semi‑automatic lines to support niche food producers and beverage brands. It leverages digital monitoring to schedule maintenance and avoid downtime. Local integrators partner with OEMs to deliver turnkey solutions that meet sustainability goals. Investment in collaborative robots continues to address labor shortages.
Eastern Europe
Eastern Europe accounts for 20% share of the Europe end‑of‑line packaging market. Poland and Czech Republic lead growth in beverage and consumer goods lines. Manufacturers upgrade standard wrapping and labeling machines to support export requirements. It benefits from lower labor costs and competitive investment incentives. Suppliers offer retrofit kits that boost performance without full line replacement. It maintains focus on standard order types that require minimal custom setup. Regional distributors expand service networks to reduce downtime and improve responsiveness.
Key Player Analysis
- OPTIMA Packaging Group GmbH
- RADPAK
- Fromm Group
- Endoline Machinery Ltd
- Robert Bosch GmbH
- Quin Systems Ltd
- Festo Inc
- DS Smith
- Flex Link
- Shemesh Automation LTD
- Coesia Group
- B&R
Competitive Analysis
Leading OEMs compete on automation features and service networks. The Europe end‑of‑line packaging market splits between global integrators like Robert Bosch GmbH and Coesia Group, mid‑size specialists such as OPTIMA Packaging Group GmbH and Endoline Machinery Ltd, plus niche innovators like Shemesh Automation LTD and RADPAK. It rewards suppliers that deliver rapid line commissioning, flexible format changeovers and remote support packages. B&R and Festo Inc leverage control expertise to boost system uptime. DS Smith and Fromm Group emphasize sustainable materials and energy‑efficient designs. Flex Link and Quin Systems Ltd target modular conveyors that adapt to volume shifts. It values partners that integrate predictive maintenance dashboards and offer retrofit kits for legacy lines. Providers gain advantage by aligning financing options with budget constraints of mid‑tier operators. Competition intensifies on digitalization, service‑level agreements and solution scalability. OEMs invest in customized training programs and spare‑parts inventories to enhance responsiveness and project support.
Recent Developments
- In May 2025, Labelexpo unveiled new folding‑carton printing technology, broadening its packaging solutions to accommodate emerging print methods.
- In July 2024, Coesia acquired a minority stake in PWR (Packaging with Robots) to enhance its automated end‑of‑line robotics and vision‑system offerings.
- In February 2025, FROMM Packaging Systems launched the Paperpad Machine, delivering precise void‑filling for efficient end‑of‑line operations.
- In February 2024, The Cut’it! Ranpak introduced the EVO automated in‑line packaging machine, ensuring materials meet the EU’s 40% void‑fill directive with minimal waste.
Market Concentration & Characteristics
Major global integrators and mid‑size specialists dominate the Europe end‑of‑line packaging market and account for over 60% of installed capacity. It exhibits moderate concentration with top ten OEMs offering turnkey automation, retrofit kits and service contracts. Niche vendors capture specialized segments through flexible conveyors, collaborative robots and mono‑material wrappers. It demands high capital investment, robust financing plans and strong aftermarket networks. Buyers seek integrated solutions that combine palletizing, labeling and wrapping into single cells. It rewards suppliers that deliver rapid commissioning, predictive maintenance dashboards and remote support. End users benefit from scalable platforms that accommodate volume shifts without full line replacement. It reflects a balance between large‑scale production needs and small‑batch customization, driving OEMs to expand modular architectures, training services and spare‑parts availability.
Report Coverage
The research report offers an in-depth analysis based on Technology, Order Type, Fundtion, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Manufacturers will adopt advanced automation technologies to accelerate production speeds and increase overall line efficiency.
- Producers will integrate collaborative robotics into end‑of‑line automation to automate manual tasks and improve consistency.
- Regulators will mandate recyclable film usage on packaging lines to satisfy strict environmental compliance standards.
- Operators will implement predictive maintenance powered by real‑time analytics to minimize downtime and maximize uptime.
- Clients will adopt modular end‑of‑line systems that allow quick capacity adjustments and seamless production scalability.
- Operations teams will deploy IoT‑enabled control platforms to monitor line performance and optimize output proactively.
- Suppliers will install collaborative robots alongside operators to automate tasks and enhance line safety reliably.
- Companies will upgrade end‑of‑line equipment with retrofit kits that extend equipment lifespan and boost performance.
- OEMs will offer service contracts that include remote support, predictive analytics and scheduled maintenance visits.
- Brands will demand customized end‑of‑line solutions that handle niche production runs, support brand differentiation strategies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe end of line packaging market?
What are the key segments within the Europe end of line packaging market?
What are some challenges faced by the Europe end of line packaging market?
Who are the major players in the Europe end of line packaging market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 2,640.63 million → Forecast year: USD 3,861.89 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe End-of-Line Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe End-of-Line Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe End-of-Line Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe End-of-Line Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe End-of-Line Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe End-of-Line Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe End-of-Line Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe End-of-Line Packaging Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 2,640.63 million → Forecast year: USD 3,861.89 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe End-of-Line Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Europe End-of-Line Packaging Geographic Market Outlook
- 13.1 Regional Market Size and Country-Level Shares, 2032
- 13.2 Country Market Size Comparison, 2032
- 13.3 Country Market Forecasts
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Europe End-of-Line Packaging Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Europe End-of-Line Packaging Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2032
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
