
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Functional Yogurt Market Size 2024 | USD 5,787.41 Million |
| Europe Functional Yogurt Market, CAGR | 6.58% |
| Europe Functional Yogurt MarketSize 2032 | USD 10,273.25 Million |
Market Overview
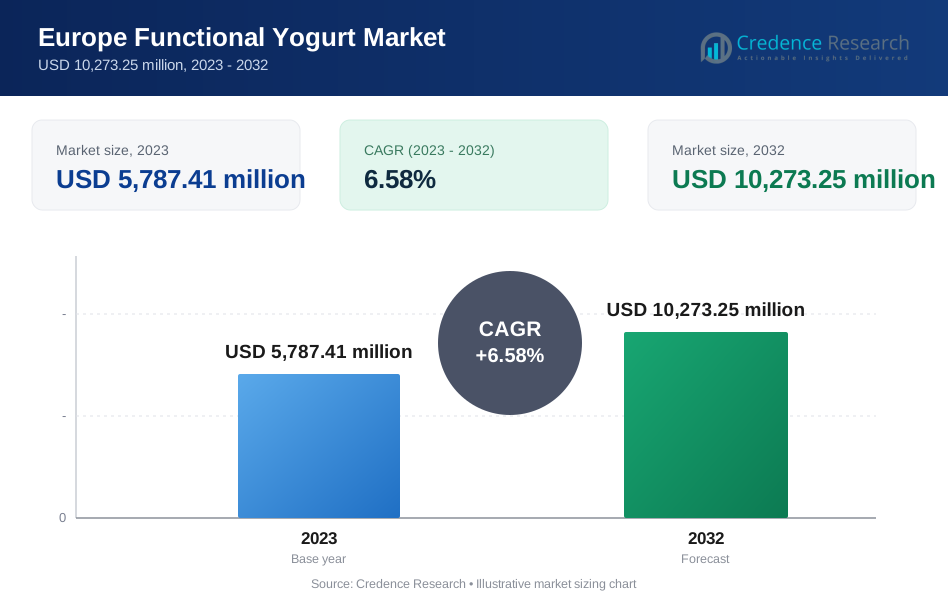
The Europe Functional Yogurt Market is projected to grow from USD 5,787.41 million in 2023 to USD 10,273.25 million by 2032, reflecting a CAGR of 6.58%.
The Europe Functional Yogurt market is driven by the growing consumer demand for healthier and functional food options, with increasing awareness of the benefits of probiotics, vitamins, and other functional ingredients in yogurt. The rise in health-consciousness, particularly in response to digestive health concerns, supports the market's growth. Additionally, the convenience of ready-to-eat, nutrient-rich yogurt products appeals to busy lifestyles. Technological advancements in yogurt production, including innovations in flavor, texture, and fortification, are also contributing to market expansion. Trends toward plant-based and lactose-free variants further cater to diverse dietary preferences, boosting consumer adoption. Furthermore, rising disposable incomes and a focus on maintaining a balanced diet are prompting more consumers to choose functional yogurt as a daily snack or meal replacement. These factors, combined with the increasing popularity of yogurt as a functional food, are propelling the market forward in Europe.
The Europe Functional Yogurt market is characterized by strong competition and regional diversity, with key players strategically positioned across various regions. Western Europe leads the market, with companies like Danone, Nestlé, and Lactalis dominating the market in countries such as the UK, Germany, and France. These regions benefit from a high level of consumer awareness regarding health and wellness, driving demand for probiotic, organic, and low-fat yogurt products. In Eastern Europe, companies such as Müller Group and FAGE are gaining traction as demand for functional yogurt rises, especially in countries like Russia and Poland. Southern Europe, with players like Yoplait and Arla Foods, is also witnessing growth as health-conscious trends spread across Italy, Spain, and Greece. Smaller markets such as Switzerland, Belgium, and Austria are increasingly important as brands focus on premium, organic, and plant-based yogurt offerings to cater to niche consumer segments.
Market Insights
- The Europe Functional Yogurt market was valued at USD 5,787.41 million in 2023 and is expected to grow at a CAGR of 6.58%, reaching USD 10,273.25 million by 2032.
- Increasing consumer awareness about the health benefits of probiotics and digestive wellness is driving the market.
- The growing preference for low-fat, organic, and plant-based yogurt options is also contributing to market expansion.
- Rising demand for convenient on-the-go yogurt formats, like drinkable and single-serve options, aligns with busy lifestyles.
- Innovation in product offerings, such as new flavors and functional ingredients, is enhancing market growth.
- Intense competition among key players, including Danone, Nestlé, and Lactalis, has led to price pressures and innovation in product formulations.
- Regional growth varies, with Western Europe dominating, while Eastern and Southern Europe exhibit growing demand, driven by health trends and increasing yogurt consumption.
Market Drivers
Rising Health Consciousness
Probiotic-rich yogurt is gaining popularity as consumers become more aware of its digestive health benefits. Probiotics are known to support gut health, leading to increased demand for yogurt products fortified with these beneficial bacteria. For instance, a report by the International Probiotic Association indicates that around 70% of people consume yogurt for general health and wellness, and 60% specifically for digestive health. Additionally, functional yogurts fortified with vitamins and minerals are increasingly sought after for their immune-boosting properties, especially during flu and cold seasons. With a growing understanding of the gut-brain connection, many consumers are choosing yogurts that promote gut health, reflecting a broader shift towards functional foods that contribute to overall well-being.
Premiumization and Innovation
As consumers prioritize quality, there is a clear trend toward premium yogurt products made with high-quality, natural ingredients. Many are willing to pay a premium for yogurt that is organic, low in sugar, or rich in protein. Manufacturers are continuously innovating with unique formulations, such as calcium-fortified yogurts that support bone health. For instance, according to a report by Amati Associates, consumers are increasingly seeking premium yogurt products that offer additional health benefits, such as probiotics and omega-3 fatty acids. This drive for premium, health-oriented options reflects a broader shift in consumer preferences towards products that offer both nutritional value and quality.
Convenience and On-the-Go Consumption
The busy lifestyle of many European consumers has led to the rise of drinkable yogurt formats, offering a convenient and portable way to enjoy yogurt. This on-the-go option allows consumers to easily incorporate yogurt into their daily routine without compromising on nutritional value. Furthermore, yogurt is increasingly being seen as a healthy snack option. When paired with fruits, nuts, or granola, yogurt offers a satisfying and nutritious snack that appeals to those seeking quick, healthy alternatives to traditional snack foods.
Diverse Product Offerings
The variety of flavors and textures in functional yogurt caters to a wide range of consumer preferences, from traditional to exotic. This diversity in product offerings ensures that there is something for every taste, encouraging greater consumer adoption. The growing popularity of plant-based diets has also driven the demand for vegan and lactose-free yogurt alternatives. These options cater to the needs of consumers seeking dairy-free, plant-based products, further expanding the market for functional yogurt.
Market Trends
Health and Wellness Focus
The growing consumer awareness of the gut-microbiome connection has significantly contributed to the demand for probiotic-rich yogurts. Probiotics are recognized for their role in supporting digestive health, leading to a surge in popularity for yogurts containing these beneficial bacteria. Additionally, functional yogurts fortified with immune-boosting ingredients like vitamins and minerals are gaining traction, especially during flu and cold seasons, as consumers seek products that enhance their overall health. For example, a survey by the National Institutes of Health found that consumers are increasingly choosing foods with added vitamins and minerals to boost their immune systems. Mental health claims are also becoming prominent in the market, with some yogurts being marketed as supporting mental well-being, capitalizing on the growing interest in the gut-brain axis and its impact on mental health.
Plant-Based and Alternative Dairy
The rise of plant-based diets and increasing lactose intolerance are driving demand for dairy-free yogurt alternatives made from plant-based milks like almond, soy, oat, and coconut. These options provide consumers with the same creamy, nutritious benefits as traditional dairy yogurts, catering to a growing segment of the population. Furthermore, manufacturers are continuously innovating with new plant-based ingredients and fermentation techniques to replicate the taste, texture, and nutritional profile of dairy yogurt. This innovation is making plant-based yogurt more appealing, bridging the gap between vegan and non-vegan diets and expanding the market for alternative dairy products.
Convenience and On-the-Go Consumption
The convenience of yogurt in drinkable formats has become a significant trend, offering consumers a refreshing and portable way to enjoy their favorite dairy product. This on-the-go option is particularly attractive to busy individuals who seek healthy, easy-to-consume snacks. In addition, single-serve yogurt portions have gained popularity, providing a convenient and portion-controlled snack that caters to fast-paced lifestyles. These trends in convenience align with the growing demand for quick, nutritious options, making yogurt a preferred choice for consumers looking for a healthy, hassle-free snack.
Premiumization and Innovation
Consumers are increasingly willing to pay a premium for yogurts made with high-quality, natural ingredients, such as organic milk, exotic fruits, and other premium additives. This shift towards premium products reflects a broader trend toward better-quality food choices. In response, manufacturers are continually innovating with new flavors and textures, offering exciting combinations that cater to diverse taste preferences. For instance, a survey by the Dairy Farmers of Canada found that consumers are willing to pay more for yogurts that feature unique and seasonal flavors. Limited-edition and seasonal flavors are also creating a sense of excitement around functional yogurt, driving consumer interest and further distinguishing brands in a competitive market. These innovations in premium products help position functional yogurt as a premium, health-focused food choice.
Market Challenges Analysis
Intense Competition and Price Pressure
The Europe functional yogurt market is facing significant competition, with numerous established players and emerging brands competing for market share. This intense rivalry puts pressure on manufacturers to differentiate themselves through product innovation, quality, and brand loyalty. For instance, companies like Danone have introduced new flavors and probiotic-rich formulations to attract health-conscious consumers. However, the fierce competition often leads to price wars, which can erode profit margins for manufacturers. As prices are pushed lower to attract consumers, maintaining profitability becomes increasingly challenging, especially for brands that prioritize premium ingredients and unique formulations. Companies must balance price sensitivity with the need for quality and innovation to stay competitive in this rapidly evolving market.
Evolving Consumer Preferences and Regulatory Challenges
Consumer preferences are evolving rapidly, placing significant pressure on manufacturers to adapt and innovate. There is a growing demand for healthier, natural products, which pushes brands to reformulate their offerings to meet these expectations. Additionally, the rise of plant-based diets challenges traditional dairy-based yogurt manufacturers to expand their product lines or risk losing market share to dairy-free alternatives. Simultaneously, regulatory hurdles are becoming more stringent, particularly within the European Union, where food labeling, health claims, and ingredient sourcing are tightly controlled. Manufacturers must navigate these regulations to avoid costly fines or reputational damage. Ensuring that health claims are substantiated is also a challenge, as regulatory bodies closely scrutinize such statements. In parallel, maintaining the viability of probiotics during production and storage adds another layer of complexity, requiring precise control over temperature, pH, and oxygen exposure. Educating consumers on the benefits of probiotics and their importance for gut health is essential to capitalize on this growing trend. Furthermore, sustainability and ethical sourcing are increasingly important to consumers, pushing brands to source ingredients responsibly and adopt eco-friendly practices. This shift in consumer values means manufacturers must find ways to meet both health-conscious and environmentally aware demands while staying compliant with regulations.
Market Opportunities
The Europe Functional Yogurt market presents significant opportunities driven by the increasing demand for health-focused products. Consumers are becoming more health-conscious, leading to a shift toward functional foods that provide added benefits beyond basic nutrition. This trend is particularly evident in the growing preference for probiotic-rich yogurts, as consumers seek digestive health solutions and immune-boosting products. Manufacturers can capitalize on this demand by offering yogurts that are enriched with probiotics, vitamins, and other functional ingredients. Additionally, the expanding awareness of mental health and the gut-brain connection presents new avenues for yogurt brands to market products that support cognitive well-being, further enhancing the appeal of functional yogurt.
Another opportunity lies in the rising popularity of plant-based diets. With an increasing number of consumers turning to vegan or lactose-free alternatives, there is a growing market for plant-based yogurt options. Manufacturers can leverage this shift by developing plant-based yogurt alternatives made from non-dairy milks like almond, soy, oat, and coconut. Innovations in plant-based formulations, such as improving taste, texture, and nutritional value, offer a competitive edge in this fast-evolving segment. Furthermore, as sustainability and ethical sourcing become more important to consumers, brands that adopt eco-friendly packaging and transparent sourcing practices are likely to gain consumer loyalty. By embracing these opportunities, manufacturers can meet the diverse needs of health-conscious consumers and position themselves as leaders in the growing functional yogurt market.
Market Segmentation Analysis:
By Product Type:
The Europe Functional Yogurt market is diverse, with several product types catering to different consumer needs. Probiotic yogurt is one of the largest segments, driven by the growing awareness of digestive health and the benefits of probiotics. This segment is experiencing robust demand as consumers increasingly seek products that support gut health and boost immunity. Greek yogurt also holds a significant share due to its higher protein content and thicker texture, making it a popular choice among health-conscious consumers. Low-fat yogurt is another key segment, appealing to individuals looking for healthier, lower-calorie options. Organic yogurt is gaining traction as consumers prioritize natural, chemical-free products, aligning with the growing trend toward organic and clean-label foods. Flavored yogurt, which offers a variety of taste options, continues to be popular, particularly among younger consumers and those seeking convenience without compromising on taste.
By Application:
In terms of application, the health and wellness segment is the largest and fastest-growing in the Europe Functional Yogurt market. Consumers are increasingly turning to functional yogurts for their potential health benefits, including immune support and digestive health. Sports nutrition is another prominent application, as athletes and active individuals seek high-protein, nutrient-dense yogurts to support recovery and energy levels. Yogurts fortified with vitamins, minerals, and other functional ingredients are gaining popularity in this segment. The weight management segment is also expanding as consumers look for low-calorie, low-fat yogurt options to aid in weight control and satiety. Lastly, other applications include yogurts targeted at specific health conditions or dietary preferences, such as lactose-free or plant-based varieties, catering to a diverse consumer base with unique nutritional needs.
Segments:
Based on Product Type:
- Probiotic Yogurt
- Greek Yogurt
- Low-fat Yogurt
- Organic Yogurt
- Flavored Yogurt
Based on Application:
- Health and Wellness
- Sports Nutrition
- Weight Management
- Others
Based on Ingredient:
- Probiotics
- Prebiotics
- Vitamins and Minerals
- Proteins
Based on Distribution Channel:
- Supermarkets/Hypermarkets
- Online Retailers
- Specialty Stores
- Convenience Stores
- Others
Based on the Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
Regional Analysis
Western Europe
Western Europe continues to be the largest and most mature market for functional yogurt. Countries such as the UK, Germany, France, and Italy drive this market segment, supported by a high level of awareness regarding health and wellness. In particular, the UK accounts for a notable share due to its strong demand for probiotics, low-fat, and organic yogurt options. France, known for its yogurt consumption culture, is shifting towards more health-conscious products, including probiotic and organic options, which further fuels the market. Similarly, Germany's large health and wellness sector is driving demand for functional yogurt products, with a significant focus on functional benefits such as digestive health and immunity support. This region is projected to hold the largest share of the market, accounting for around 60% by 2032.
Eastern Europe
Eastern Europe presents promising growth potential in the functional yogurt market. While the region traditionally lags behind Western Europe in yogurt consumption, there has been a noticeable increase in demand for functional products as health awareness rises. Russia, Poland, and Romania are key contributors to this growth, with a growing interest in probiotic and low-fat yogurts, as well as the expansion of plant-based alternatives. The market share in Eastern Europe is expected to grow steadily, with a projected increase in consumer preference for functional dairy products. The region’s market share is expected to reach approximately 20% by 2032, with Russia leading in terms of volume and product variety.
Southern Europe and Rest of Europe
Southern Europe, including Italy, Spain, and Greece, is seeing increased demand for functional yogurt, driven by both traditional yogurt consumption and a shift towards health-oriented products. In these countries, health and wellness trends are gaining momentum, particularly in Italy and Spain, where yogurt is deeply ingrained in the culture. These regions are expected to capture a growing share of the market, projected to account for around 10% of the European market by 2032. Meanwhile, the Rest of Europe, which includes smaller markets like Switzerland, Austria, and Belgium, is also seeing positive growth, albeit at a slower pace compared to larger regions. These countries contribute to the overall market with a niche focus on organic, low-fat, and premium functional yogurts, which cater to the specific preferences of their consumers.
Key Player Analysis
- Danone
- Lactalis Group Danone
- Nestlé
- Lactalis
- Müller Group
- FAGE
- Arla Foods
- Yoplait
- Valio
- Onken
- Emmi
- Liberte
- Alpro
- Skyr
- Ehrmann
- Milbona
- Stonyfield
Competitive Analysis
The Europe Functional Yogurt market is highly competitive, with several key players dominating the landscape. Leading companies such as Danone, Nestlé, Lactalis, Müller Group, FAGE, Arla Foods, Yoplait, Valio, Onken, Emmi, Liberte, Alpro, Skyr, Ehrmann, Milbona, and Stonyfield are leveraging diverse strategies to maintain their market positions. Leading players are focusing on product innovation and differentiation to meet the increasing demand for health-focused, probiotic, and organic yogurt products. Companies are also capitalizing on growing consumer preferences for convenient on-the-go options, such as drinkable and single-serve yogurts. Additionally, there is a notable emphasis on creating plant-based and lactose-free alternatives to cater to the rising demand for vegan and allergy-friendly products. To remain competitive, brands are investing in research and development to enhance the nutritional value of their offerings, such as fortifying yogurts with vitamins, minerals, and other functional ingredients. Pricing strategies and promotions play a significant role in maintaining customer loyalty amidst the highly competitive landscape. For example, many brands are now using recyclable materials and ensuring their supply chains are ethically managed. The market is also witnessing strategic partnerships, acquisitions, and regional expansions, particularly in emerging markets, to capitalize on the growing demand for functional yogurt across Europe. Moreover, sustainability and ethical sourcing are becoming increasingly important, with companies adopting eco-friendly packaging and promoting transparency in their ingredient sourcing practices.
Recent Developments
- In February 2024, Epigamia, a brand known for its innovative dairy products, launched a new variant of Greek yogurt that combines the creaminess of yogurt with the wholesome goodness of oats and a seed mix. This product aims to cater to health-conscious consumers looking for nutritious and satisfying snack options.
- In April 2024, Danone North America introduced REMIX, an innovative line of yogurts and dairy snacks designed to cater to diverse snacking preferences throughout the day. This launch reflects the growing trend of consumers seeking convenient, flavorful, and nutritious options for snacking.
- In March 2024, Bored Cow made waves in the dairy alternative market by launching its innovative animal-free yogurt, touted as the “first of its kind.” This groundbreaking product is crafted using fermented proteins, offering a sustainable and ethical alternative to traditional dairy yogurt without compromising on taste or texture.
- In 2023, Chobani, has introduced Chobani® Zero Sugar* Drinks. This innovative zero sugar beverage offers a healthier option for consumers looking to reduce their sugar intake while enjoying the goodness of yogurt. The launch of Chobani’s zero sugar drinks demonstrates the brand’s commitment to meeting evolving consumer preferences for healthier alternatives.
- In 2023, Chobani presents the Low-Fat Greek Yogurt Shake, tailored to meet the needs of health-conscious consumers looking for a convenient, nutritious on-the-go snack. This delectable shake harmonizes the benefits of Greek yogurt with a gratifying and delightful taste, offering individuals a wholesome choice for their fast-paced lives.
- In 2023, Califia Farms also entered the yogurt market with its Dairy-Free Yogurt Cultured Nutmilk Drink. This plant-based yogurt alternative is made from nut milk and offers a dairy-free option for consumers with specific dietary preferences or restrictions. The introduction of such dairy-free alternatives reflects the increasing demand for plant-based products in the market.
- In 2023, Morinaga launched an Aloe Yogurt Drink specifically targeting consumers looking for refreshing and hydrating yogurt options. This product combines the benefits of yogurt with the soothing properties of aloe vera, providing a unique and invigorating experience for consumers.
Market Concentration & Characteristics
The Europe Functional Yogurt market is moderately concentrated, with a few key players holding significant market share, while numerous smaller and regional brands contribute to its diversity. Major companies leverage their strong distribution networks, brand recognition, and innovation capabilities to dominate the market. These players focus on expanding their product portfolios by introducing new formulations, such as probiotic-rich, low-fat, organic, and plant-based yogurts, to cater to the growing demand for health-conscious and specialized products. The market is also characterized by a high level of product differentiation, with brands offering a wide range of flavors, textures, and functional benefits to appeal to diverse consumer preferences. In addition, the rise of convenience-driven consumption has led to the growth of on-the-go formats like drinkable yogurt and single-serve cups, further intensifying competition. Regional differences in consumer preferences, health awareness, and dietary habits also influence market dynamics. As a result, companies are increasingly focusing on localized marketing strategies, product innovations, and distribution channels to tap into both mature and emerging markets. Sustainability practices, such as eco-friendly packaging and ethical sourcing, are becoming key differentiators for brands seeking to strengthen their position in the market. Despite the presence of dominant players, the market remains competitive with opportunities for smaller brands to grow.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Ingredient, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europe Functional Yogurt market is expected to continue growing at a strong pace, driven by increasing health-consciousness among consumers.
- Demand for probiotic-rich and gut health-focused yogurt products will likely rise as consumers prioritize digestive wellness.
- The shift toward plant-based and lactose-free yogurt alternatives will gain momentum, reflecting growing vegan and allergy-sensitive dietary trends.
- Convenience will remain a key factor, with more consumers opting for on-the-go formats such as drinkable yogurt and single-serve options.
- Innovation in product formulations, including low-sugar, high-protein, and organic offerings, will be essential to meet diverse consumer preferences.
- Companies will increasingly focus on sustainability, with a push for eco-friendly packaging and ethical sourcing of ingredients.
- Regional growth is expected, with Eastern and Southern Europe witnessing increased demand for functional yogurt due to rising health awareness.
- Premiumization trends will continue, with consumers willing to pay more for high-quality, natural ingredients and specialized products.
- Marketing strategies will become more personalized, leveraging digital channels to target specific health-conscious consumer segments.
- Strategic partnerships and acquisitions will increase as companies seek to expand their product portfolios and market reach across Europe.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Functional Yogurt market?
What factors are driving the growth of the Europe Functional Yogurt market?
What are the key segments within the Europe Functional Yogurt market?
What are some challenges faced by the Europe Functional Yogurt market?
Who are the major players in the Europe Functional Yogurt market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Functional Yogurt Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Functional Yogurt Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 5,787.41 million → 2032: USD 10,273.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Functional Yogurt Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Functional Yogurt Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Functional Yogurt Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Functional Yogurt Market Drivers
- 3.3 Europe Functional Yogurt Market Restraints & Challenges
- 3.4 Europe Functional Yogurt Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Functional Yogurt Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Functional Yogurt Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Functional Yogurt category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Functional Yogurt Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Functional Yogurt Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Functional Yogurt market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Functional Yogurt Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Functional Yogurt Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Functional Yogurt Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Functional Yogurt (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Functional Yogurt Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Functional Yogurt Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Functional Yogurt Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Functional Yogurt Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Functional Yogurt Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Functional Yogurt Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Functional Yogurt Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Functional Yogurt Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Functional Yogurt Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
