
Market Overview:
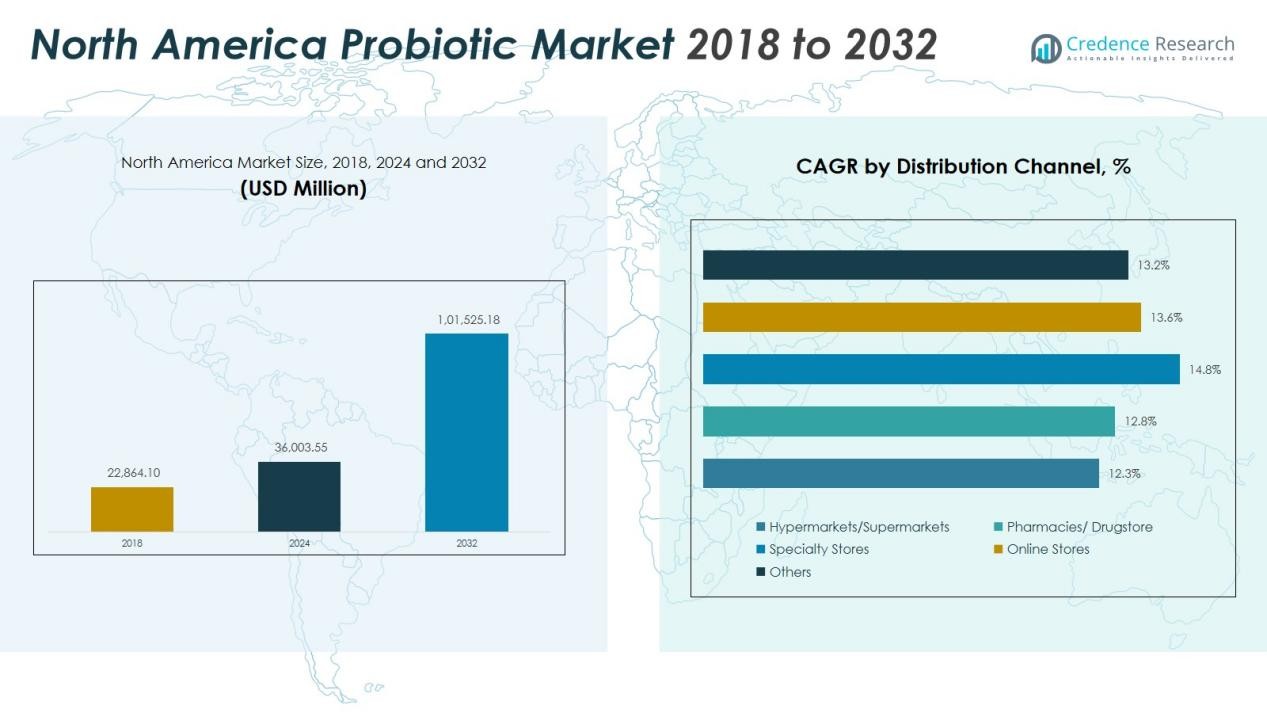
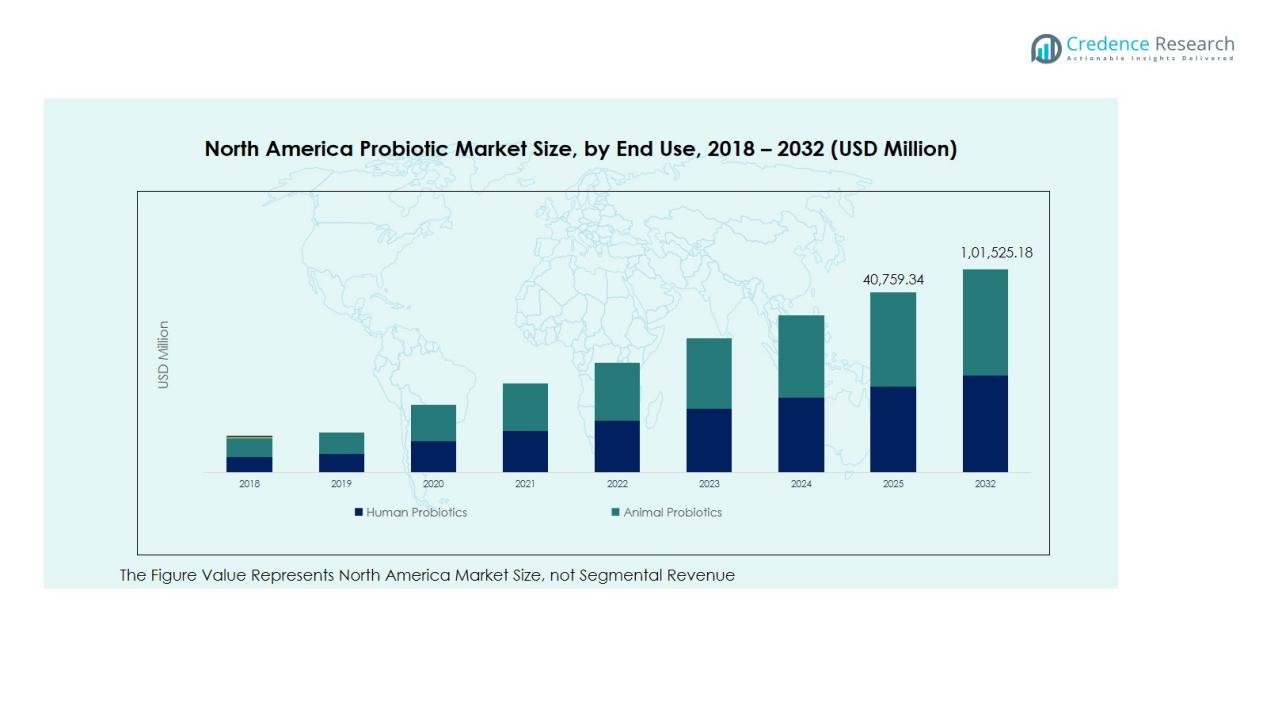
The North America Probiotic Market size was valued at USD 22,864.10 million in 2018 to USD 36,003.55 million in 2024 and is anticipated to reach USD 1,01,525.18 million by 2032, at a CAGR of 11.55% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Probiotic Market Size 2024 | USD 36,003.55 Million |
| North America Probiotic Market, CAGR | 11.55% |
| North America Probiotic Market Size 2032 | USD 1,01,525.18 Million |
The North America Probiotic Market is driven by growing health consciousness and a shift toward preventive healthcare solutions. Strong demand for functional foods, along with a preference for clean-label and natural ingredients, is stimulating product innovation. The growing elderly population and rising digestive health issues are also fueling adoption across both retail and online distribution channels.
Regionally, the United States dominates the North America Probiotic Market with over 75% share in 2024, driven by a mature functional food sector and advanced clinical research. Canada is showing strong growth supported by expanding retail availability of probiotic dairy and supplements. Mexico is emerging as a promising market, supported by increasing disposable incomes and wider acceptance of fortified food products.
Market Insights:
- Rising health awareness and preventive healthcare are driving strong probiotic adoption across North America.
- Consumers are increasingly choosing probiotic-enriched foods and beverages to support digestive and immune health.
- Functional dairy, yogurt, and fermented beverages remain leading categories fueling consistent product demand.
- Technological innovation in strain encapsulation is improving shelf life, stability, and therapeutic efficiency.
- Regulatory challenges related to labeling and strain validation continue to slow market entry and product launches.
- The United States leads the regional market with advanced research facilities and high consumer awareness.
- Canada and Mexico show steady and emerging growth respectively, supported by expanding retail presence and rising disposable incomes.
Market Drivers:
Rising Health Awareness and Preventive Healthcare Focus
Consumers are becoming more conscious of digestive and immune health, fueling demand for probiotics. The growing preference for preventive healthcare over curative treatments supports steady adoption. Functional foods and beverages fortified with probiotic strains are gaining traction across retail platforms. The North America Probiotic Market benefits from increasing consumer trust in natural solutions that enhance overall wellness.
- For Instance, The number of Colony Forming Units (CFUs) of Lacticaseibacillus casei Shirota in a 65 mL bottle of Yakult varies by region. The UK version contains at least 20 billion CFUs, while the standard formulas in markets like India and Australia contain at least 6.5 billion CFUs.
Expansion of Functional Food and Beverage Segment
The rapid expansion of functional dairy, yogurt, and fermented beverages drives the regional probiotic demand. Manufacturers are launching new products with clinically tested strains to attract health-focused consumers. It is supported by growing supermarket penetration and strong marketing emphasizing digestive balance and immunity benefits. The integration of probiotics into everyday food products is strengthening brand loyalty and consumer engagement.
- For instance, in August 2025, Danone’s Activia introduced its Proactive Yogurt line in the U.S., formulated with billions of live probiotics and 3 grams of prebiotic fiber per serving, alongside a 25% reduction in sugar content to enhance digestive health and consumer appeal.
Technological Advancements and Product Innovation
Advances in strain isolation and encapsulation technologies are improving product shelf life and effectiveness. Companies are investing in research partnerships to develop targeted probiotic formulations for different health needs. It enables better strain delivery and higher survival rates through gastrointestinal passage. These technological innovations are helping brands expand into new applications such as nutraceuticals, infant nutrition, and sports supplements.
Rising Geriatric Population and Lifestyle-Related Disorders
An aging population with higher rates of digestive issues and metabolic disorders supports market expansion. Probiotic supplements are increasingly used to manage gut imbalance and enhance nutrient absorption. The growing incidence of obesity, stress-related digestive problems, and antibiotic use also contributes to demand. The North America Probiotic Market is gaining strong traction among adults seeking daily digestive and immune support solutions.
Market Trends:
Growing Shift Toward Non-Dairy and Plant-Based Probiotic Products
Consumers are showing stronger demand for non-dairy probiotic options due to rising lactose intolerance and vegan preferences. Companies are responding with plant-based formulations made from soy, oats, almonds, and coconut. It supports broader accessibility among consumers seeking sustainable and allergen-free products. Non-dairy probiotic beverages, gummies, and powders are gaining popularity across supermarkets and online platforms. Manufacturers are expanding product portfolios with natural flavors and organic ingredients to attract health-conscious buyers. The North America Probiotic Market is moving toward inclusivity, appealing to both vegan and flexitarian consumers through diversified product innovation.
- For Instance, Israeli agrifoodtech startup Wonder Veggies received its first granted patent for technology to infuse probiotics into fresh produce. The technology enables viable endophytic bacteria to survive throughout the shelf life of the produce, which the company claims can be up to 14 days in leafy greens.
Integration of Personalized Nutrition and Digital Health Solutions
Personalized nutrition is becoming a major trend shaping the probiotic industry in North America. Digital platforms now offer microbiome testing and customized probiotic recommendations, creating higher consumer engagement. It reflects a transition from generic supplementation to tailored wellness strategies. Technology-driven solutions are helping brands deliver specific formulations that target gut, immune, and mental health needs. Collaborations between biotech firms and nutrition companies are strengthening this personalized approach. The growing integration of health apps, e-commerce, and data-driven formulations is transforming how consumers interact with probiotic products and track their health outcomes.
- For instance, in June 2025, The Vitamin Shoppe partnered with GenoPalate to launch an at-home DNA nutrition kit that analyzes over 400 genetic markers to curate personalized probiotic and vitamin regimens based on the user’s microbiome and genetic traits.
Market Challenges Analysis:
Complex Regulatory Framework and Labeling Inconsistencies
Regulatory variations across the United States, Canada, and Mexico pose challenges for probiotic manufacturers. Companies face difficulty in obtaining approvals and maintaining label claims that comply with regional health authorities. It limits product launches and delays innovation cycles. The absence of standardized guidelines for probiotic strain efficacy and dosage reduces consumer trust. Manufacturers must invest in rigorous clinical validation and documentation to maintain credibility. The North America Probiotic Market faces pressure to align scientific evidence with evolving health and safety regulations.
High Product Sensitivity and Supply Chain Constraints
Probiotics are living organisms that require strict temperature control and stable packaging during storage and transport. Small deviations in handling conditions can reduce product viability and potency. It creates added cost burdens for producers and distributors. Limited availability of high-quality raw materials and strain-specific cultures further complicates supply consistency. Shelf life issues in fermented and supplement-based probiotics restrict market penetration in remote regions. These operational and logistical challenges continue to affect profitability and scalability for several market participants.
Market Opportunities:
Expanding Applications Beyond Digestive Health
Probiotics are gaining recognition for benefits beyond gut wellness, including immunity, skin health, and mental well-being. Scientific research continues to uncover links between gut microbiota and mood regulation, creating new opportunities for functional supplements. It encourages companies to introduce multi-benefit formulations addressing stress, metabolism, and skincare. The North America Probiotic Market is witnessing increasing collaborations between nutraceutical and pharmaceutical sectors to explore these diversified applications. Such innovation broadens consumer reach and strengthens long-term growth prospects across emerging health categories.
Rising Demand for E-Commerce and Customized Nutrition Solutions
E-commerce platforms are becoming a key growth driver for probiotic brands targeting tech-savvy consumers. Online sales enable direct-to-consumer engagement and flexible subscription-based distribution models. It provides opportunities for personalization through microbiome testing and tailored probiotic blends. Companies leveraging digital health tools and data-driven insights are gaining a competitive edge. Strategic partnerships with wellness apps and digital pharmacies support brand visibility and consumer trust. Growing digital adoption continues to open new channels for targeted marketing and product expansion in the regional market.
Market Segmentation Analysis:
By Type
Probiotic food and beverages dominate the North America Probiotic Market, driven by strong demand for functional dairy, fermented drinks, and non-dairy alternatives. Yogurt, kefir, and fortified beverages remain key revenue contributors. It benefits from consumer preference for convenient and natural digestive health solutions. Dietary supplements such as capsules, gummies, and powders are expanding rapidly, supported by clinical validation and online retail growth. The animal feed segment continues to grow steadily, driven by rising awareness of gut health and productivity in livestock.
- For Instance, Danone North America launched Activia Proactive, a new line of low-fat yogurt with simpler ingredients and 25% less sugar than its classic low-fat version. Activia Proactive also contains billions of live probiotics and prebiotic fiber to support digestive health.
By Ingredient
Bacteria-based probiotics hold the largest market share due to their proven health benefits and widespread application in food and dietary supplements. Strains such as Lactobacillus and Bifidobacterium are widely used for improving immunity and digestion. It continues to attract significant research and investment for strain-specific functionality. Yeast-based probiotics, primarily Saccharomyces boulardii, are gaining popularity for their role in gastrointestinal health and antibiotic resistance support.
- For instance, Yakult's Original fermented milk drink sold in the UK and Europe delivers at least 20 billion CFUs of Lacticaseibacillus casei Shirota in each 65 mL bottle, ensuring consistent probiotic intake per serving
By End-Use
Human probiotics lead the market with strong consumer adoption in functional foods, supplements, and fortified beverages. Growing awareness of gut-brain and gut-skin connections supports their integration into wellness routines. It shows consistent demand across adult and elderly populations. Animal probiotics, though smaller in share, are expanding with rising adoption in poultry, swine, and cattle feed to enhance immunity and growth efficiency.
Segmentations:
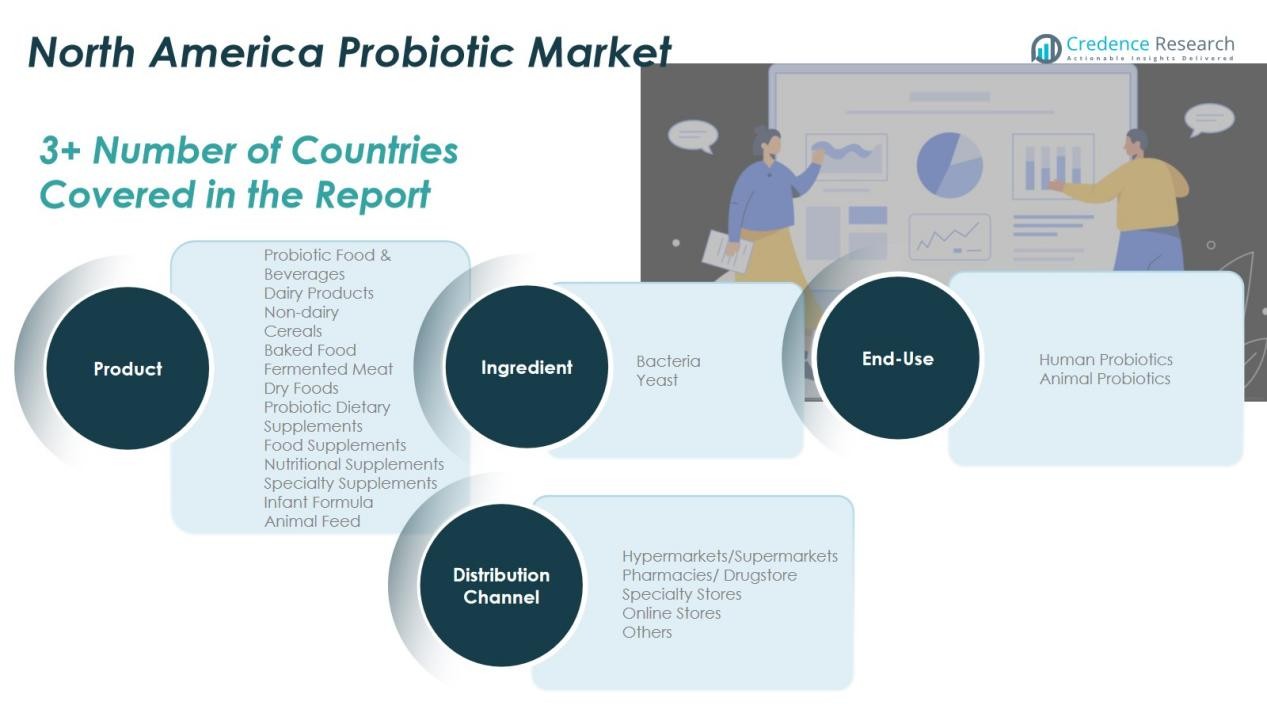
By Type
Probiotic Food & Beverages
- Dairy Products
- Non-dairy
- Cereals
- Baked Food
- Fermented Meat
- Dry Foods
Probiotic Dietary Supplements
- Food Supplements
- Nutritional Supplements
- Specialty Supplements
- Infant Formula
- Animal Feed
By Ingredient
- Bacteria
- Yeast
By End-Use
- Human Probiotics
- Animal Probiotics
By Distribution Channel
- Hypermarkets/Supermarkets
- Pharmacies/Drugstores
- Specialty Stores
- Online Stores
- Others
By Country
- United States
- Canada
- Mexico
Regional Analysis:
United States Dominating the Regional Market Landscape
The United States accounts for the largest share of the regional probiotic industry, driven by strong consumer awareness and a mature health supplements market. Robust demand for probiotic yogurt, functional beverages, and dietary capsules fuels consistent revenue growth. It benefits from advanced research capabilities, high disposable income, and widespread retail availability. Key manufacturers focus on strain innovation and product diversification to meet growing wellness trends. The North America Probiotic Market gains significant momentum in the U.S. due to strong distribution networks and supportive clinical studies that validate probiotic efficacy.
Canada Demonstrating Steady Market Growth
Canada exhibits steady growth supported by rising healthcare spending and interest in preventive nutrition. Expanding supermarket and pharmacy chains have improved product accessibility across urban and suburban regions. It experiences increasing acceptance of probiotic-enriched dairy, gummies, and supplements among younger consumers. Government emphasis on food safety and clear labeling standards promotes trust in branded probiotic products. The country’s focus on clean-label and organic formulations continues to strengthen its probiotic market position.
Mexico Emerging as a High-Potential Market
Mexico shows promising potential driven by improving income levels and growing urbanization. Probiotic beverages and fortified foods are gaining traction among consumers seeking digestive support and immune balance. It benefits from expanding awareness campaigns and wider distribution through modern retail formats. Local manufacturers are partnering with global brands to enhance product quality and strain diversity. Rapid adoption of affordable probiotic solutions positions Mexico as a key contributor to regional expansion and future demand growth.
Key Player Analysis:
- Yakult Honsha Co. Ltd
- Danone S.A.
- Nestlé S.A.
- Hansen Holding A/S
- BioGaia AB
- Probi AB
- General Mills, Inc.
- Lallemand Inc.
- Kerry Group plc
- Lifeway Foods, Inc.
- Archer Daniels Midland Company (ADM)
- UAS Laboratories
- i-Health, Inc. (Culturelle)
- Seed Health
- DuPont (IFF – International Flavors & Fragrances)
- NOW Foods
Competitive Analysis:
The North America Probiotic Market is highly competitive with several global and regional players operating across multiple product categories. Leading companies such as Yakult Honsha Co. Ltd, Danone S.A., Nestlé S.A., Chr. Hansen Holding A/S, BioGaia AB, Probi AB, General Mills, Inc., Lallemand Inc., Kerry Group plc, and Lifeway Foods, Inc. dominate the landscape through extensive product portfolios and strong distribution networks. It is characterized by continuous product innovation, partnerships, and acquisitions aimed at expanding probiotic applications beyond digestive health. Major players are focusing on developing strain-specific formulations and functional beverages that address immunity and mental wellness. Investments in research, clinical validation, and clean-label formulations are intensifying competition, while digital retail channels and personalized nutrition trends create new growth opportunities across the region.
Recent Developments:
- In July, 2025, Danone completed the acquisition of a majority stake in Kate Farms, a U.S.-based plant-based nutrition company, enhancing its specialized nutrition portfolio.
- In October 2025, BioGaia announced the publication of a scientific study on its new patented probiotic strain Lactobacillus reuteri BG-R46® in the journal Beneficial Microbes, highlighting its role in gut and immune health.
Report Coverage:
The research report offers an in-depth analysis based on Type, Ingredient, End-Use, Distribution Channel and Country. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The North America Probiotic Market is expected to expand steadily driven by increasing consumer awareness of preventive healthcare.
- Growing focus on gut health and immunity will continue to influence product innovation across the food and supplement sectors.
- It will witness greater adoption of non-dairy and plant-based probiotic products, appealing to vegan and lactose-intolerant consumers.
- Advancements in microbiome research will support the development of targeted and clinically validated probiotic strains.
- Personalized nutrition and microbiome testing will shape product customization and marketing strategies.
- E-commerce and direct-to-consumer platforms will strengthen brand reach and customer engagement across the region.
- Collaborations between biotech and food companies will accelerate product diversification and regulatory compliance.
- It will experience higher demand for probiotics addressing skin health, mood balance, and metabolic wellness.
- Sustainable sourcing, clean-label formulations, and transparent labeling will remain key consumer priorities.
- Increasing adoption in animal feed will contribute to improved livestock productivity and overall market expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health Awareness and Preventive Healthcare Focus
Consumers in North America are increasingly prioritizing digestive and immune health, leading to greater adoption of probiotic-enriched foods and supplements as part of preventive healthcare routines.
Expansion of Functional Food and Beverage Segment
The rapid growth of functional dairy, yogurt, and fermented beverages, along with innovative non-dairy alternatives, is fueling demand for probiotics across retail and online channels.
Technological Advancements and Product Innovation
Advances in strain encapsulation and targeted formulations are improving product stability, efficacy, and shelf life, enabling brands to expand into new applications such as infant nutrition and sports supplements.
Growing Shift Toward Non-Dairy and Plant-Based Probiotic Products
Increasing lactose intolerance and vegan preferences are driving demand for plant-based probiotic options, prompting manufacturers to diversify portfolios with soy, oat, almond, and coconut-based products.
Integration of Personalized Nutrition and Digital Health Solutions
The adoption of microbiome testing and personalized probiotic recommendations through digital platforms is enhancing consumer engagement and supporting the shift toward tailored wellness solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the North America Probiotic Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the North America Probiotic Market projected to grow between 2024 and 2032?
Which segment held the largest share of the North America Probiotic Market in 2024?
What are the primary factors fueling the growth of the North America Probiotic Market?
Who are the leading companies in the North America Probiotic Market?
Which country commanded the largest share of the North America Probiotic Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Probiotic Food & Beverages
- 1.2.2 Probiotic Dietary Supplements
- 1.2.3 Animal Feed
- 1.3 By End-Use
- 1.3.1 Human Probiotics
- 1.3.2 Animal Probiotics
- 1.4 By Ingredient
- 1.4.1 Bacteria
- 1.4.2 Yeast
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 36,003.55 million → 2032: USD 101,525.18 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Probiotics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Probiotics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Probiotics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Probiotics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Probiotics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Probiotics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Probiotics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Probiotics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 36,003.55 million → 2032: USD 101,525.18 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Probiotics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Probiotic Food & Beverages
- 12.3.7.2 Probiotic Dietary Supplements
- 12.3.7.3 Animal Feed
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Human Probiotics
- 12.4.7.2 Animal Probiotics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Ingredient - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Bacteria
- 12.5.7.2 Yeast
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 North America Probiotics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North America Probiotics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North America Probiotics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North America Probiotics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Yakult Honsha Co. Ltd
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Danone S.A.
- 18.4 Nestlé S.A.
- 18.5 Chr. Hansen Holding A/S
- 18.6 BioGaia AB
- 18.7 General Mills, Inc.
- 18.8 Lallemand Inc.
- 18.9 Kerry Group plc
- 18.10 Lifeway Foods, Inc.
- 18.11 Archer Daniels Midland Company (ADM)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

