
Car plants, process rules and aircraft set sealing demand
The Europe gasket and seals market was valued at USD 14.45 billion in 2025 and is projected to increase from USD 15.16 billion in 2026 to USD 23.35 billion by 2035, registering a CAGR of 4.92% during 2026–2035. Demand comes from carmakers and their tier suppliers, refineries, chemical plants and gas networks, aircraft programs and maintenance buyers that replace worn seals in fleets and machinery. Germany held the largest share, 28.5% in 2025, because it builds more cars than any other European country and hosts the head offices of several leading sealing makers. Rest of Europe is the fastest-growing area at 5.5% a year, as car and battery assembly keeps moving toward Central Europe. The main regulatory change is the EU review of a group-wide PFAS restriction, which could phase out fluoropolymer seal grades after transition periods.
Which sealing products and buyers sit inside the estimate?
The estimate counts static gaskets in metallic, semi-metallic and non-metallic designs, dynamic seals such as shaft seals, O-rings and molded packing, and motor vehicle body seals, valued at the manufacturer selling price in the EU, the United Kingdom, the EFTA countries and Turkey.
Liquid sealants, adhesives, sealing tapes and complete mechanical seal cartridges sit outside the estimate. Carmakers and machine builders buy seals on multiyear part-number awards after validation testing, while refineries and chemical plants buy flange gaskets and packing through distributors on framework contracts that reward stock depth and fast delivery.
Europe Gasket and Seals Market Insights
- The market is valued at USD 14.45 billion in 2025 and is projected to reach USD 23.35 billion by 2035, growing at a 4.92% CAGR as electrified cars and emission rules raise sealing content.
- Germany led with 28.5% of 2025 value, because it produced 4,032,756 cars in 2025 and hosts major sealing makers.
- Molded Packing & Seals held 27.0% of 2025 value, while Semi-metallic Gaskets grow fastest at 5.9% a year on flange tightness rules.
- EU buyers registered 1,880,370 battery-electric cars in 2025, a 17.4% share, which adds battery, cooling and connector seals per vehicle.
- Trelleborg completed the purchase of German profile maker M+R Dichtungstechnik in September 2026, adding facade, solar and wind seals.
Molded seals lead while semi-metallic gaskets grow fastest
O-rings and molded parts lead as methane rules lift flange gaskets
Based on product, the market is categorized into metallic, semi-metallic and non-metallic gaskets, shaft seals, molded packing and seals, and motor vehicle body seals. Molded Packing & Seals led with 27.0% of 2025 value because O-rings and molded parts sit in every hydraulic, pump and battery assembly, and Hutchinson opened an automated O-ring and bonded seal hub in Mannheim on Sept. 30, 2025, to serve Germany, Northern Europe and Eastern Europe. Semi-metallic Gaskets grow fastest at 5.9% a year as oil and gas operators had to file leak detection and repair programs under the EU methane regulation by May 5, 2025, which favors spiral wound and kammprofile gaskets on critical flanges.
Car plants set volume while Airbus backlogs pull aerospace seals
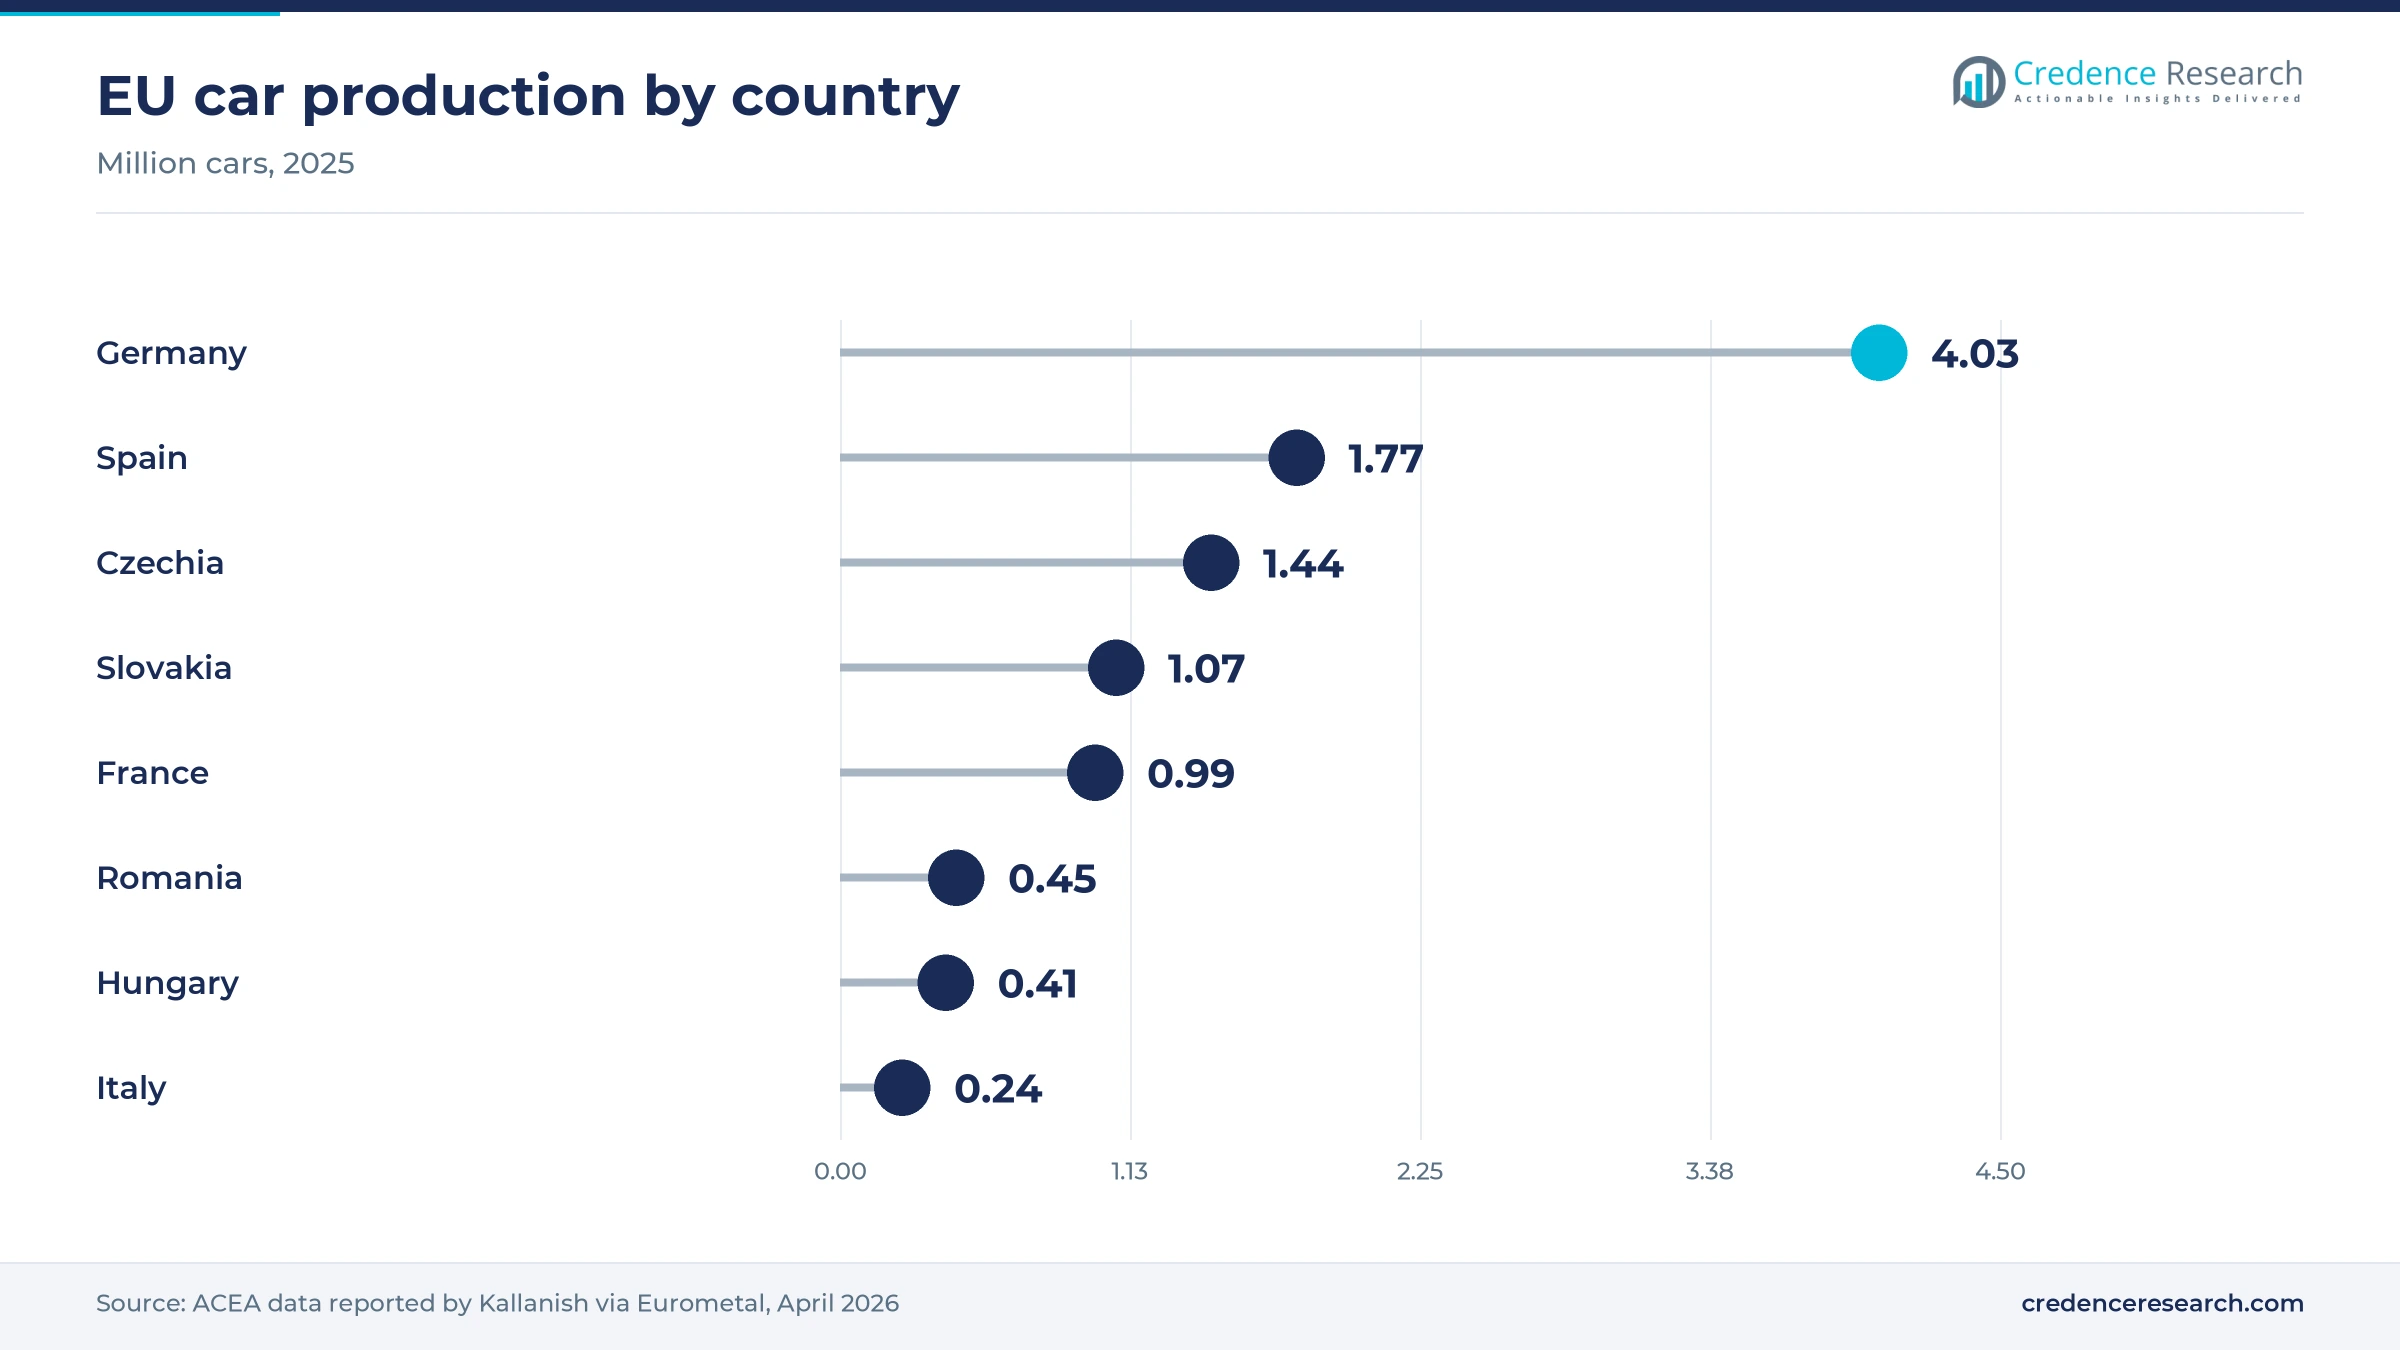
Based on application, the market is categorized into automotive, electrical and electronics, marine and rail, industrial and manufacturing, aerospace, oil and gas, chemicals and petrochemicals, and others. Automotive led with 34.0% of 2025 value because EU plants built 11,470,235 cars in 2025, according to ACEA data reported by Kallanish, and each car carries engine, transmission, thermal and body sealing sets. Aerospace grows fastest at 6.2% a year as Airbus booked 1,000 gross orders in 2025, so fuel, hydraulic and airframe seal schedules climb at its European assembly lines.
Design-stage awards keep OEMs ahead as aging fleets lift aftersales
Based on end user, the market is categorized into original equipment manufacturers and the aftersales market. Original Equipment Manufacturer (OEM) buyers led with 62.0% of 2025 value because carmakers, machine builders and aircraft programs specify seals at the design stage, and ElringKlinger reported a first high-volume order from a global battery manufacturer in its 2025 results. The Aftersales Market grows fastest at 5.4% a year as the EU car fleet reached about 256 million vehicles in 2024 and trucks averaged 14 years of age, according to ACEA. Older vehicles in that fleet need more replacement gaskets and seals in workshops.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Molded Packing & Seals | 27.0% | Semi-metallic Gaskets | 5.9% |
| By Application | Automotive | 34.0% | Aerospace | 6.2% |
| By End User | Original Equipment Manufacturer (OEM) | 62.0% | Aftersales Market | 5.4% |
Part-number contracts and compounds shape seal prices
Seal and gasket prices are set per part number, and OEM contracts fix them for the life of a vehicle or machine program, usually with annual productivity cuts and raw material clauses. Natural rubber averaged USD 2.18 per kilogram for RSS3 in 2025, according to the World Bank Pink Sheet, down from USD 2.28 in 2024, so compound costs eased slightly while labor and energy stayed high. Catalog prices for plant buyers run far above OEM levels because distributors hold thousands of sizes in stock. Suppliers do not publish OEM contract prices, so those ranges are Credence Research estimates.
| Product or reference | Typical price or fee | Basis |
|---|---|---|
| Natural rubber RSS3, annual average 2025 | USD 2.18 per kg | World Bank Pink Sheet, February 2026 |
| Natural rubber TSR20, annual average 2025 | USD 1.77 per kg | World Bank Pink Sheet, February 2026 |
| SKF 40 x 62 x 6 mm FKM radial shaft seal, pack of 20 | About EUR 18.32 per seal before VAT | RS Components Ireland list price, November 2026 |
| KLINGER DN50 PN40 spiral wound gasket, single piece | GBP 160.44 per piece | ManoMano U.K. marketplace listing, November 2026 |
| OEM car door and window body seal set | About EUR 40-90 per vehicle | Credence Research estimate from profile length and compound cost |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Electrified cars, methane rules and aircraft lift demand
Electrified cars widen sealing content per vehicle
Electrified cars widen the sealing bill of materials, because battery packs, cooling plates and power electronics need seals that a combustion car does not carry, while hybrids keep their engine gaskets. EU buyers registered 1,880,370 battery-electric cars in 2025, a 17.4% share, and hybrids took 34.5% of the market, ACEA reported. BMW began series production of the iX3, its first Neue Klasse model, in Debrecen, Hungary, in late October 2025. The European Commission's automotive package of Dec. 16, 2025, replaced the full 2035 phase-out with a 90% tailpipe reduction target, so engine and exhaust gasket demand continues in hybrids. Suppliers that cover both battery seals and engine gaskets protect their content per car.
Methane rules tighten flange and valve sealing
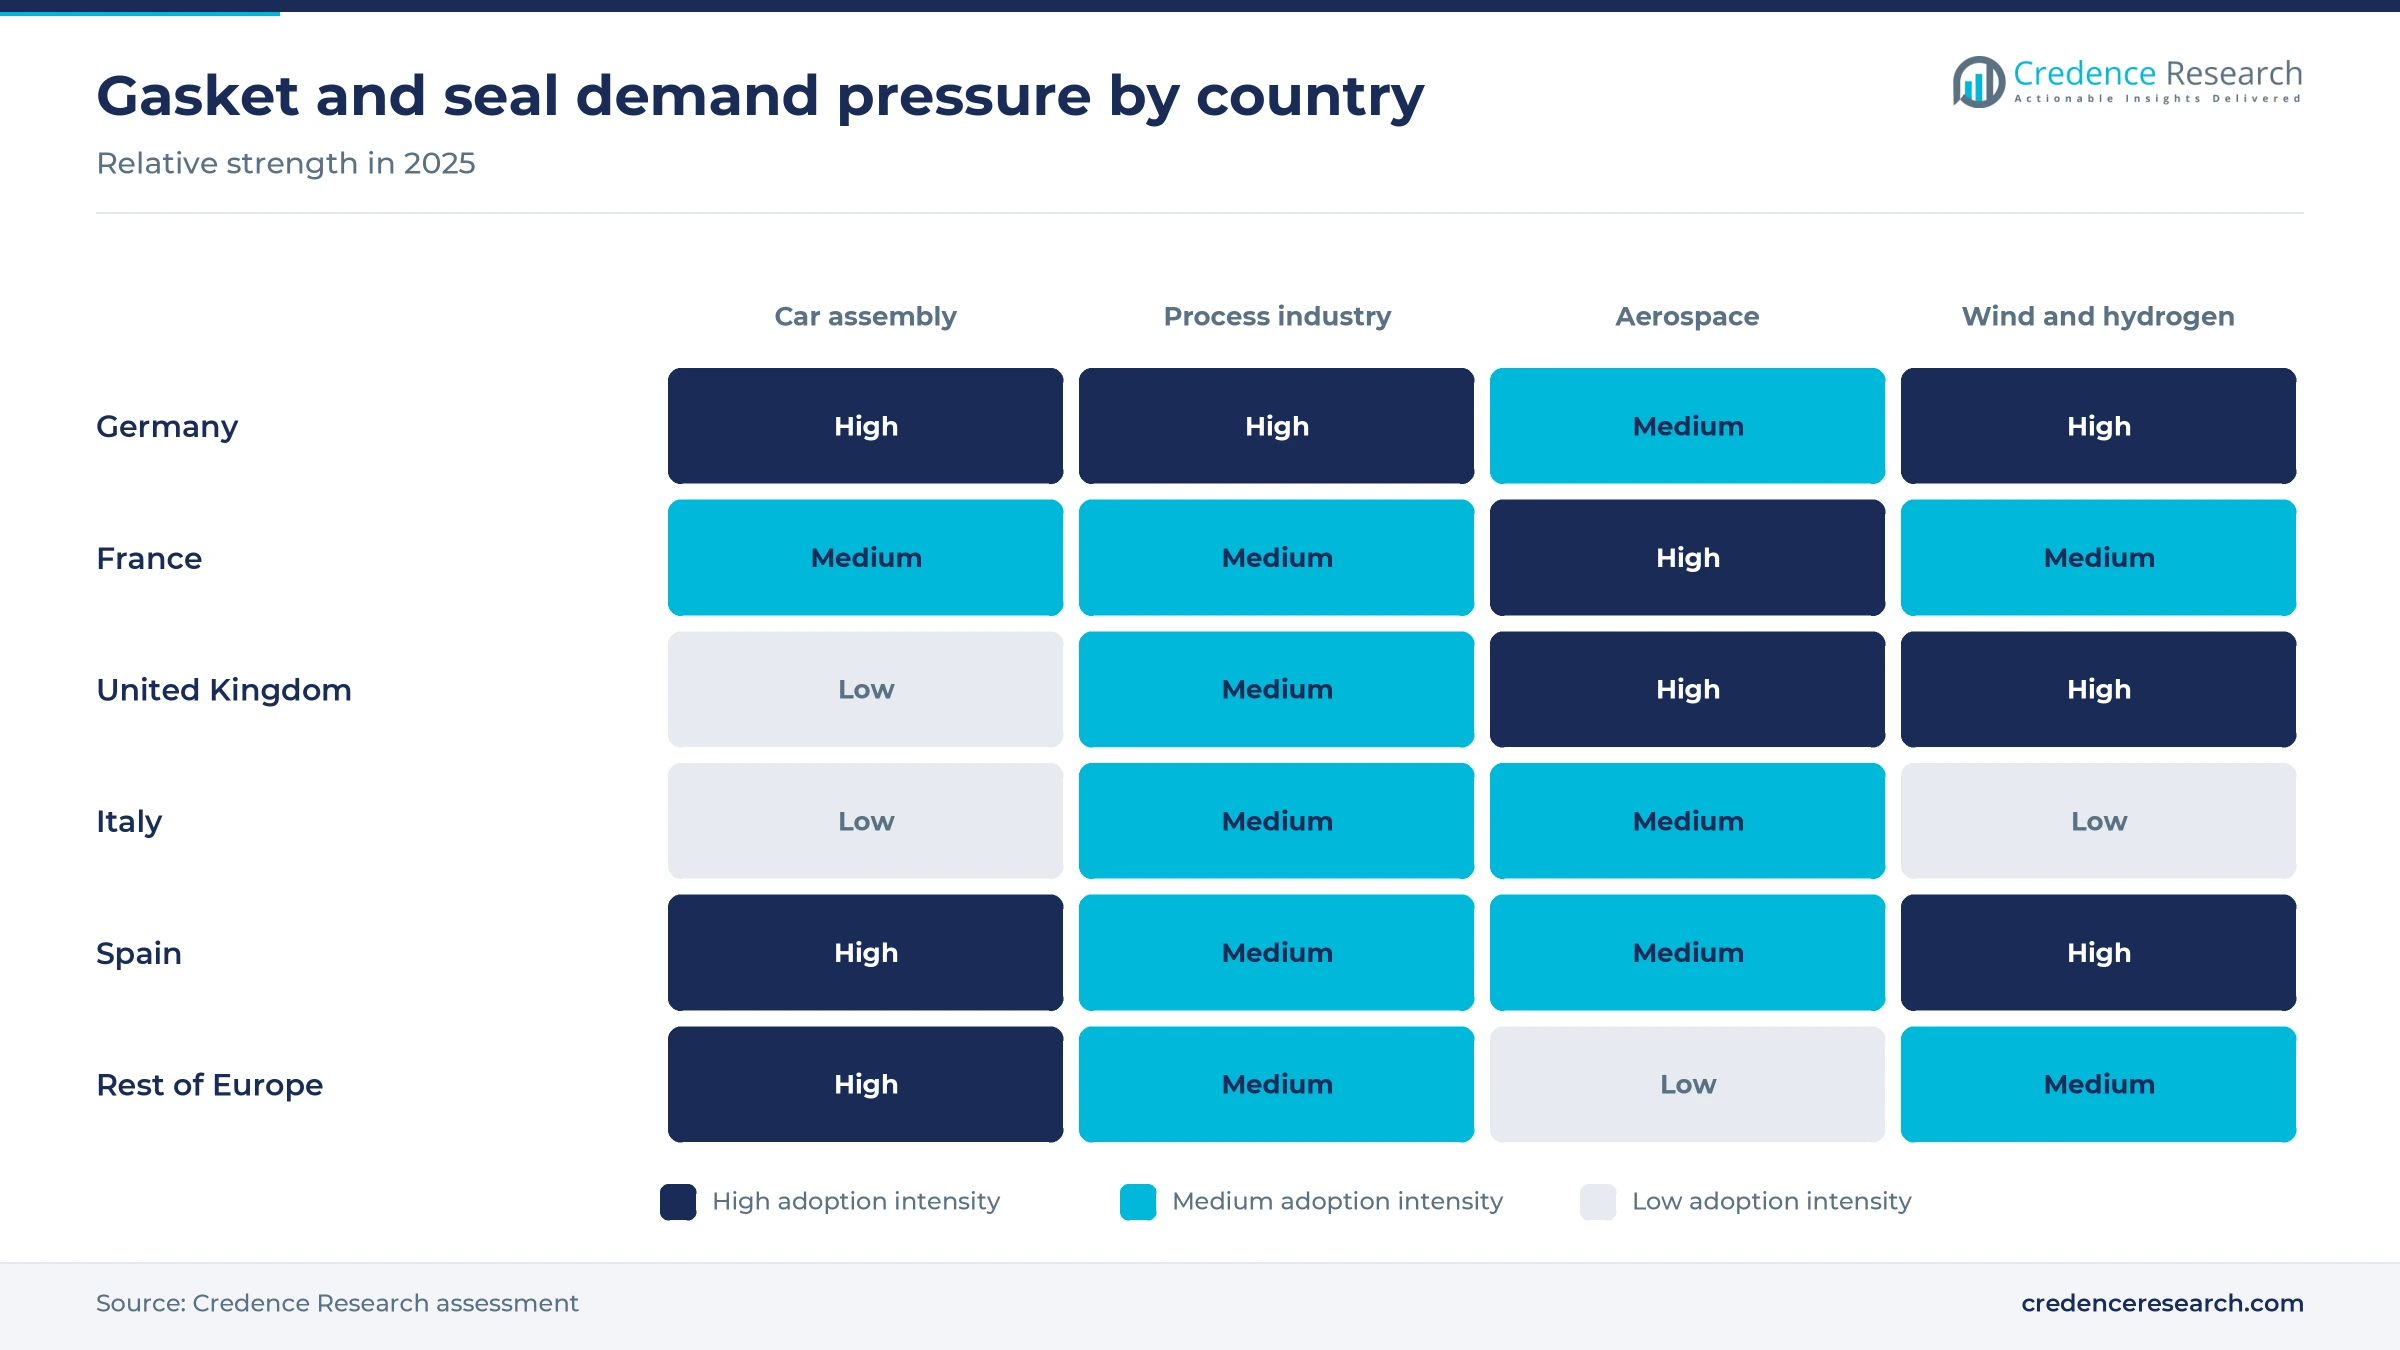
The EU methane regulation turns flange and valve tightness into a compliance matter for gas networks, LNG terminals and producers, which favors low-emission gaskets and packing. The regulation entered into force on Aug. 4, 2024, and routine venting and flaring by oil and gas operators has been prohibited since Feb. 5, 2026, with narrow exceptions. Importers must show by Jan. 1, 2027, that new contracts cover oil or gas monitored to equivalent standards, and annual reporting of import methane intensity starts on Aug. 5, 2028. Operators respond by replacing stem packing on industrial valves and gaskets on leaking flanges during planned shutdowns, which gives certified low-emission products a specification edge.
Aircraft build rates lift high-specification seals
Aircraft production pulls the most demanding seals in the region, because fuel, hydraulic and cabin systems need qualified fluorosilicone, PTFE and metal seals that few suppliers can certify. Airbus delivered 793 commercial aircraft in 2025, up from 766 in 2024, including 607 from the A320 family, the company reported in January 2026. Its backlog reached a record 8,754 aircraft at year-end 2025, which secures several years of seal call-offs. A220 deliveries rose to 93 from 75, adding volume on a program that ramps further. Qualified seal suppliers gain long contracts, although each new part needs lengthy approval, which limits new entrants.
Wind buildout adds outdoor sealing demand
Wind farms add demand for seals that survive moisture, salt and temperature swings in nacelles, gearboxes, pitch systems and towers. Europe installed 19.1 GW of new wind capacity in 2025, bringing the total to 304 GW, and expects 151 GW of additions from 2026 to 2030, WindEurope reported. Only 2 GW of the 2025 total was offshore, the lowest since 2016, and repowering of older onshore sites added another 2 GW, so the expected offshore catch-up from 2026 brings large-diameter seal orders. Trelleborg completed the purchase of M+R Dichtungstechnik of Seligenstadt, Germany, in September 2026, a maker of rubber profiles that also serves solar and wind customers. Makers of wind turbine components that sign multiyear service agreements give seal suppliers recurring replacement orders.
Automation, fluorine-free compounds and hydrogen stacks
Seal makers shift toward automated tooling and stock hubs
Seal makers are shifting toward in-house tooling and automated warehouses to cut lead times for bespoke parts, creating openings for fast prototype and small-batch supply across machinery and medical uses. Trelleborg completed the purchase of Nexus Elastomer Molds of Eberstalzell, Austria, a maker of liquid silicone rubber tools and automated production cells, on Jan. 7, 2026. Freudenberg Sealing Technologies dedicated an 8,800 square meter warehouse in Hamburg on Sept. 19, 2025, with 22 robots and more than 30,000 pre-stored articles. KLINGER Spain bought the Basque gasket makers Productos Salinas and Juntas Besma in September 2024. Suppliers that own tooling can quote bespoke seals in weeks instead of months.
Fluorine-free compounds gain ground in new designs
Design engineers are shifting toward fluorine-free elastomers in new programs to reduce exposure to a future PFAS restriction, creating openings for EPDM, HNBR and specialty compounds in battery and fluid systems. Freudenberg Sealing Technologies launched an elastomer O-ring for battery cells in April 2025 as an alternative to PFAS-containing thermoplastic and FKM seals, and said it cut leakage by roughly 90% in customer projects with cells running at up to 60 C. The European Sealing Association said in August 2025 that sealing applications were officially in focus in the revised proposal, the European Rubber Journal reported. ECHA's risk committee adopted its final opinion on March 2, 2026, calling for further EU-wide action, law firm CMS reported. Compound developers with validated substitutes therefore gain early design wins in new programs.
Electrolyzer stacks open a new sealing niche
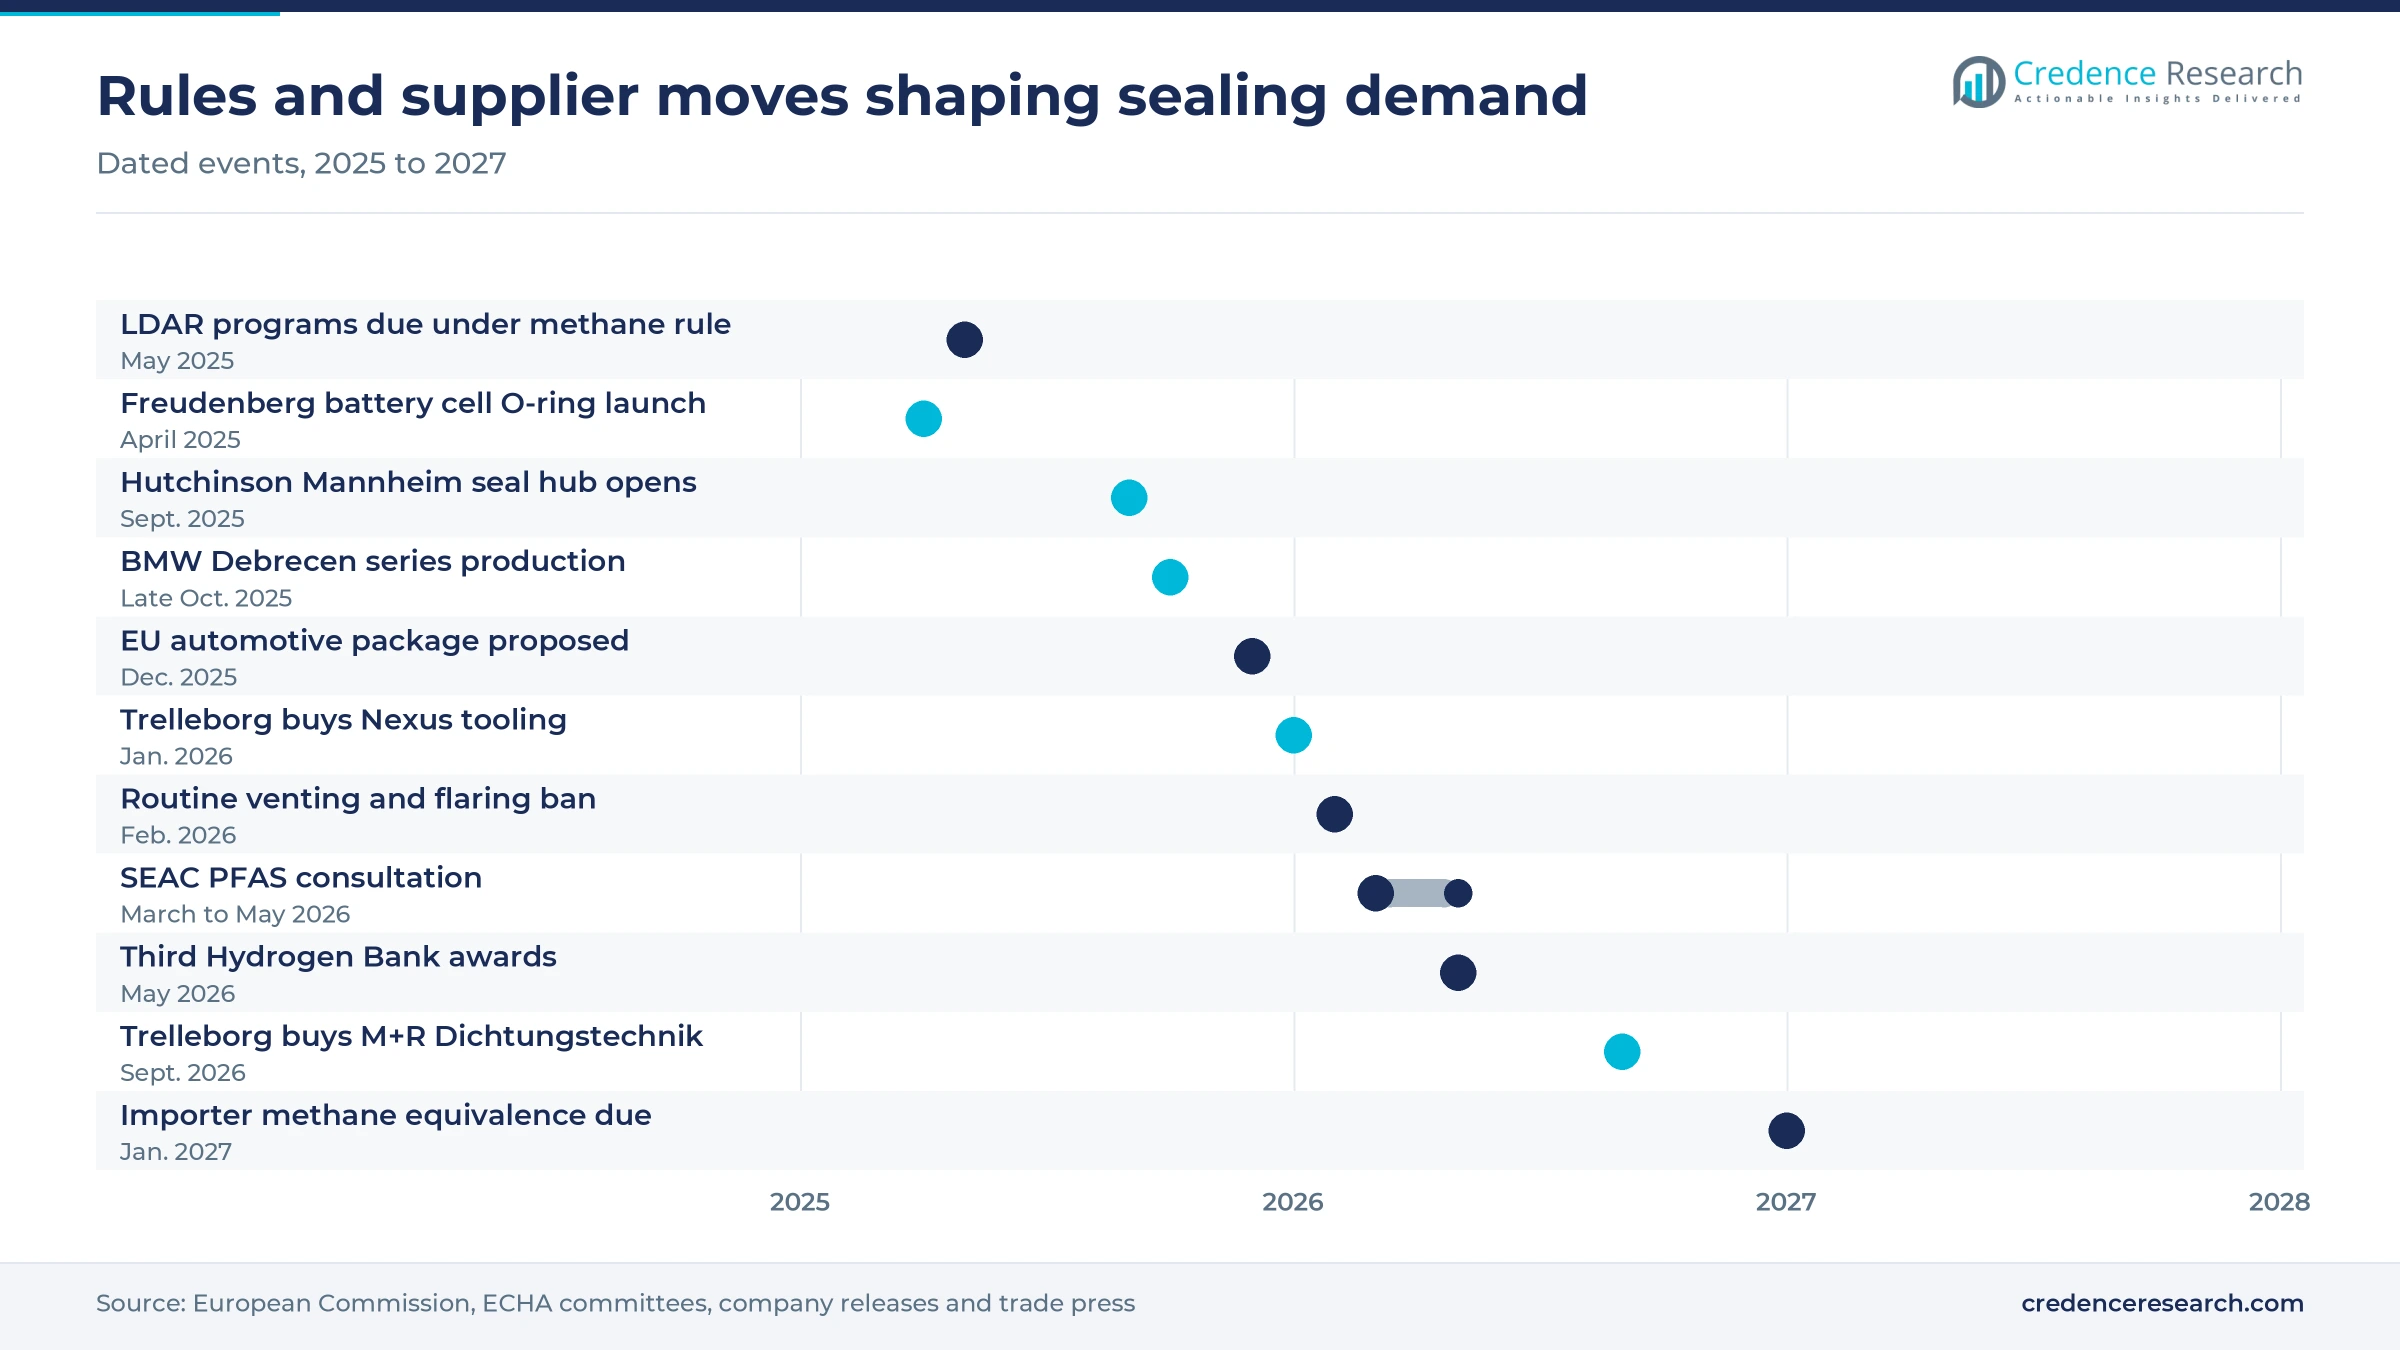
Hydrogen electrolyzers offer a new outlet for plate-integrated gaskets, because each stack needs hundreds of seals that must hold pressure and resist deionized water or lye for years. The third European Hydrogen Bank auction awarded EUR 1.09 billion to nine projects with almost 1.1 GW of electrolyzer capacity in May 2026, S&P Global reported. The winners sit in Denmark, Finland, Germany, Norway, Spain, Greece and Austria, which spreads stack assembly across the region. Freudenberg Sealing Technologies offers EPDM and FKM gaskets overmolded onto composite and metal stack plates. Stack makers that buy gasket-plate units cut assembly time, which favors sealing suppliers with overmolding lines.
EU-made batteries and fleet rules open pack-sealing work
EU-made batteries and corporate fleet rules open a sealing opportunity in battery cells, pack housings, cooling circuits and high-voltage connectors for suppliers located near new European gigafactories. The European Commission proposed a Battery Booster Strategy with EUR 1.8 billion for a fully EU-made battery value chain in its December 2025 automotive package. The same package sets Member State targets from 2030 for zero- and low-emission corporate cars and vans, which make up about 60% of new EU car registrations, according to the Commission. Plug-in hybrids took 9.4% of 2025 EU registrations, up from 7.2%, ACEA data show, and each carries both a battery pack and an engine. Pack makers that localize supply favor seal suppliers with plants and validation labs inside the EU for faster approval of new pack designs.
PFAS rules, car output cuts and engine decline weigh
PFAS restriction threatens fluoropolymer seal lines
A group-wide PFAS restriction would hit seals made from PTFE, FKM and FFKM, which serve hot, chemical and high-pressure duties. The SEAC draft opinion opened a consultation from March 26 to May 25, 2026, and proposes only an interim, time-limited derogation for sealing uses, with transition periods of five or twelve years. The European Sealing Association said its objective is an exemption for fluoropolymers. Chemical plant suppliers are most exposed until the final opinion arrives.
Car output cuts hit plants in several countries
Car production fell sharply in several European countries in 2025, which cut call-offs for engine, body and thermal seals. Italian output dropped 22.9% to 237,975 cars and Swedish output fell 12.8% to 247,972, according to ACEA data reported by Kallanish. Seal plants that depend on one or two local car plants are most exposed, because lost volume cannot be moved quickly to other customers. Suppliers spread across several carmakers absorb these shifts better than single-customer sites.
Engine decline erodes classic gasket volumes
The shift to electric cars removes cylinder head, exhaust and oil pan gaskets from a growing share of new vehicles. Petrol car registrations in the EU fell 18.7% in 2025, cutting their share to 26.6% from 33.3% in 2024, according to ACEA. ElringKlinger closed or began closing four sites in Germany and North America in 2025 and launched its STREAMLINE cost program. Gasket makers that rely on engine parts are most exposed unless they win battery and thermal sealing work.
Commercial vehicle slump trims heavy-duty demand
Weak van and truck markets reduced demand for heavy-duty engine, axle and transmission seals in 2025. Van registrations fell 8.8% and truck registrations fell 6.2% in 2025, while EU van production dropped 6.5%, according to ACEA. Suppliers of heavy-duty gaskets and shaft seals are most exposed, because truck makers order in large batches and cut schedules quickly. The aging truck fleet supports aftermarket sales, which only partly offsets the weaker original equipment volumes.
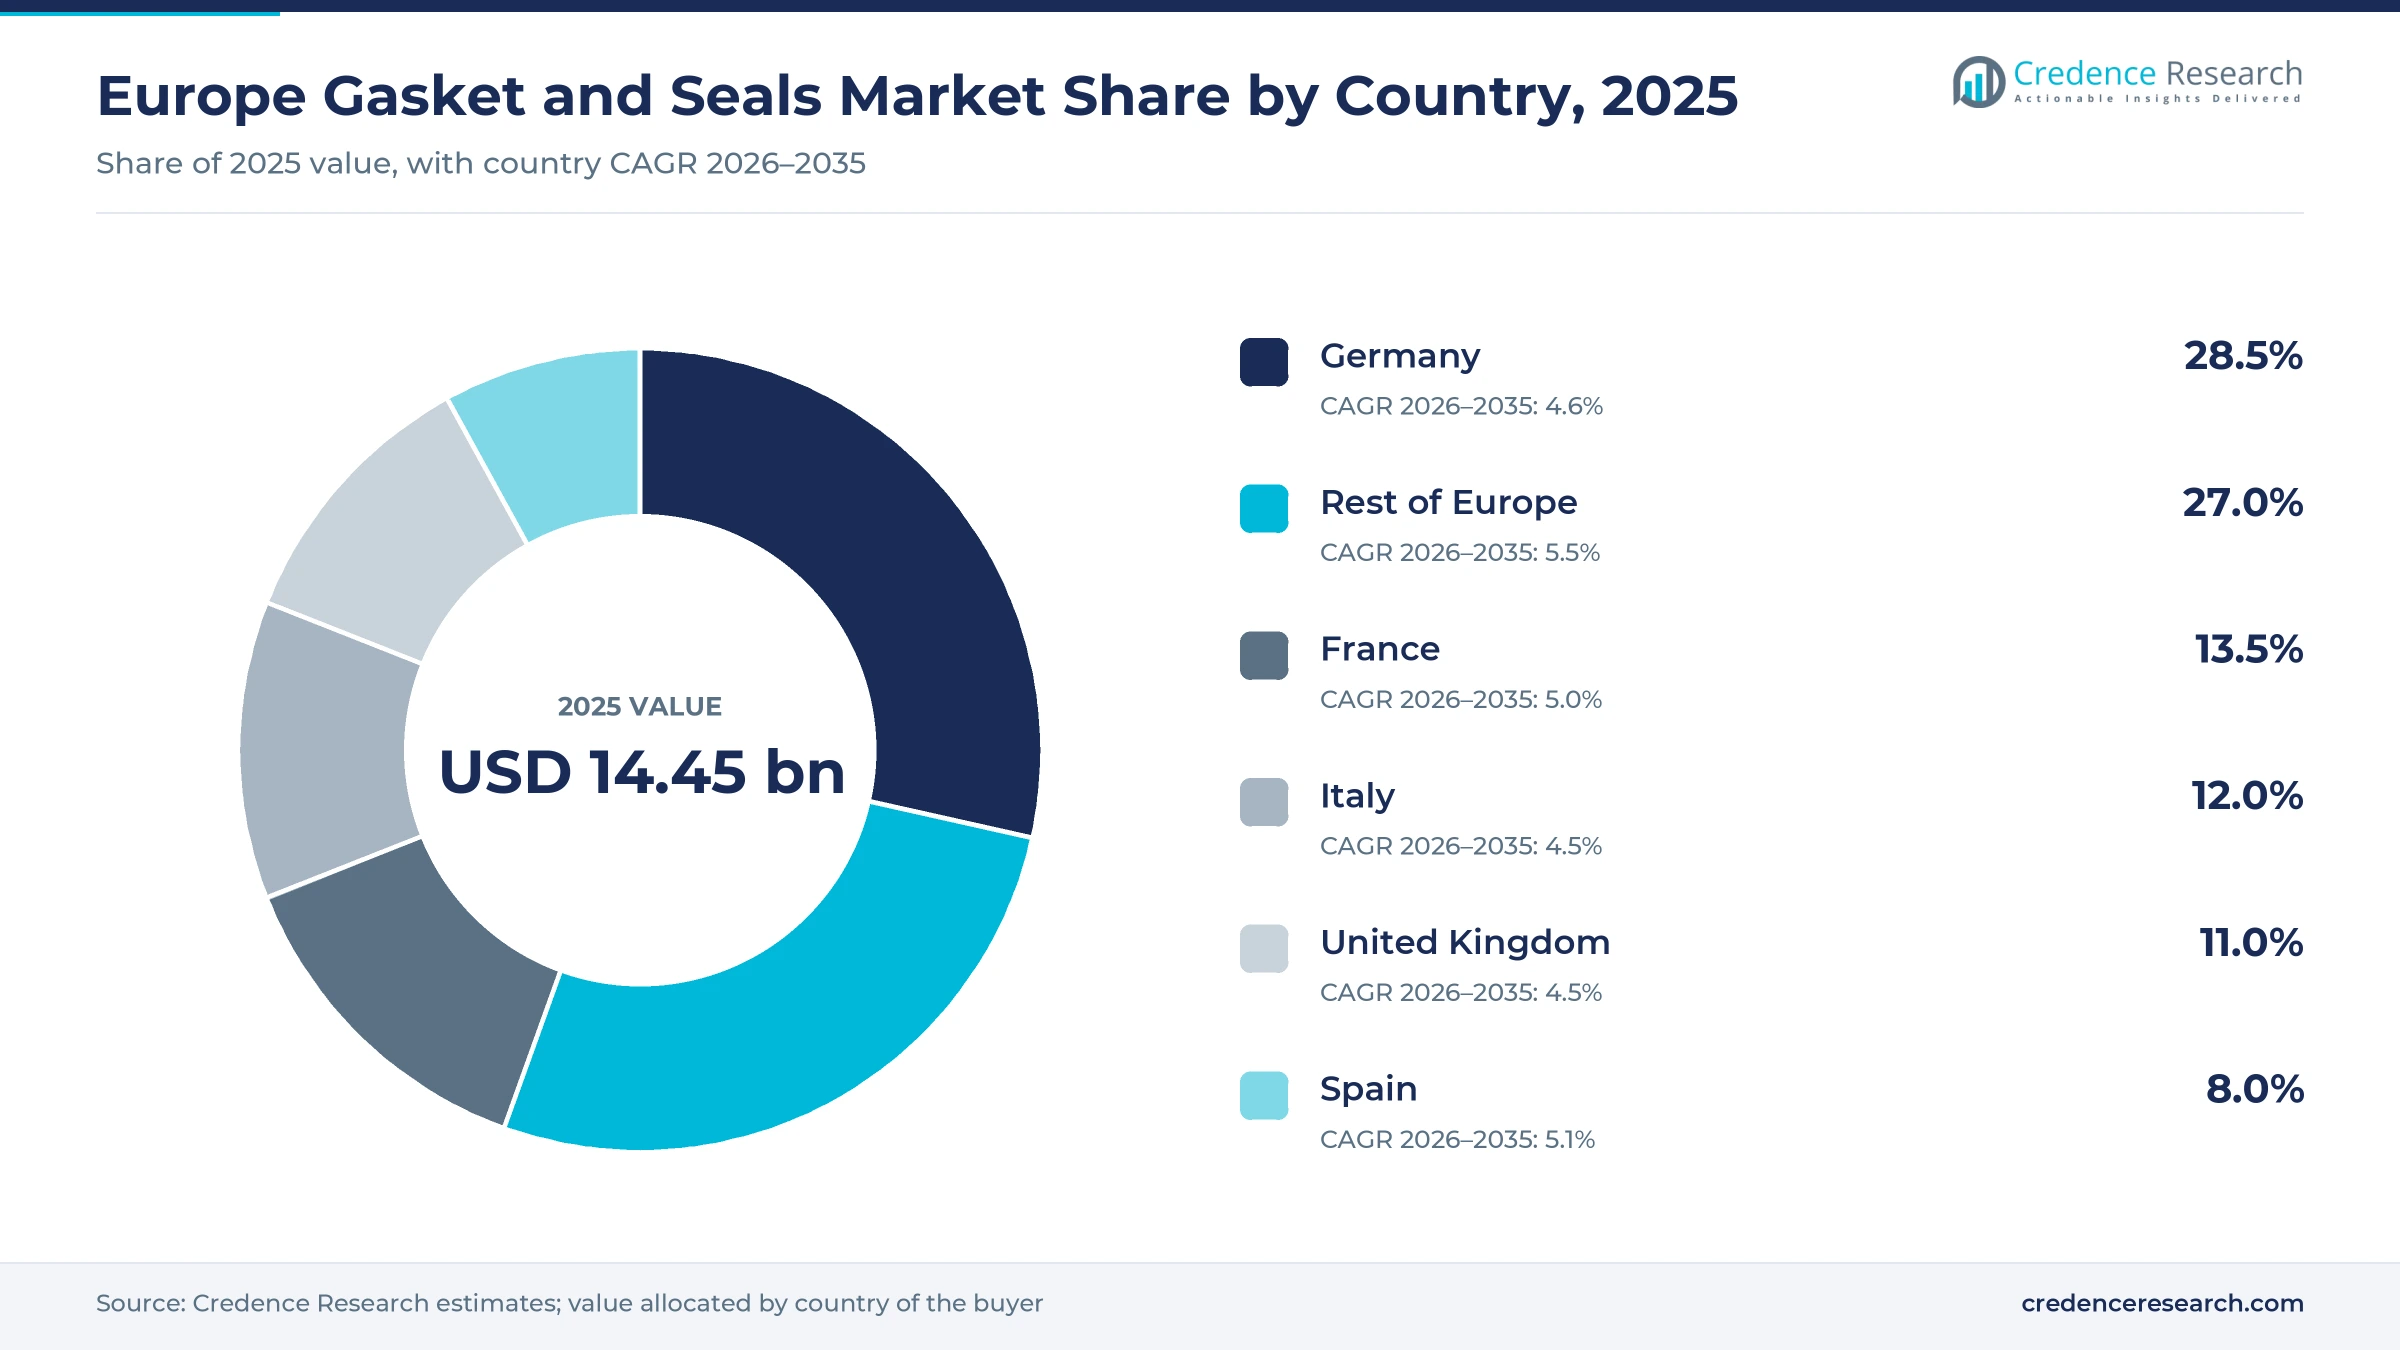
Germany leads as Central Europe grows fastest
| Country | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Germany | 4.12 | 28.5% | 4.6% |
| Rest of Europe | 3.90 | 27.0% | 5.5% |
| France | 1.95 | 13.5% | 5.0% |
| Italy | 1.73 | 12.0% | 4.5% |
| United Kingdom | 1.59 | 11.0% | 4.5% |
| Spain | 1.16 | 8.0% | 5.1% |
Germany leads on car output and supplier depth
Germany held 28.5% of 2025 value and grows at 4.6% a year, because it built 4,032,756 cars in 2025, up 2.3%, according to ACEA data reported by Kallanish, and hosts the head offices of Freudenberg and ElringKlinger. Its chemical parks add steady demand for spiral wound and kammprofile flange gaskets. German plants also made 21% of the cars sold in the EU in 2025, according to ACEA, so German seal demand tracks EU car sales as much as domestic output.
France grows on car output and aircraft assembly
France held 13.5% of 2025 value and grows at 5.0% a year, slightly faster than the regional average, because car production rose 15.5% to 986,275 units in 2025, according to ACEA data reported by Kallanish. That 15.5% gain was the largest among the ten biggest EU car producers in 2025, which lifts OEM seal call-offs at French plants. Airbus programs anchor the aircraft seal demand described above, and France was one of only three countries to connect new offshore wind turbines in 2025.
Italy faces weak car output but holds process demand
Italy held 12.0% of 2025 value and grows at 4.5% a year, among the slowest rates, because the car output decline noted above cuts OEM seal volumes. Process industry demand holds up better, and KLINGER Italy acquired Trust Valves of Rovello Porro, a valve distributor serving oil and gas, chemical and water treatment plants, effective July 10, 2025, which widens its plant service offer alongside gaskets. Public data on Italian seal consumption by industry are thin, so this share carries a wide error range.
United Kingdom relies on aerospace and energy users
The United Kingdom held 11.0% of 2025 value and grows at 4.5% a year, below the regional rate because van production fell 70.2% in 2025, according to ACEA, while aerospace, North Sea energy and offshore wind hold industrial demand steady. Public data on U.K. seal consumption by industry are thin, so this share carries a wide error range.
Spain grows on assembly plants and hydrogen projects
Spain held 8.0% of 2025 value and grows at 5.1% a year, because it remains the second-largest EU car producer with 1,766,325 cars in 2025, even after a 5.7% fall, according to ACEA data reported by Kallanish. Freudenberg Sealing Technologies opened a 6,800 square meter carbon-neutral plant in Parets del Valles near Barcelona in February 2024, investing more than EUR 11 million. Spanish projects also won funding in the hydrogen auction noted above.
Rest of Europe grows fastest on Central European plants
Rest of Europe held 27.0% of 2025 value and grows fastest at 5.5% a year, because Czechia built 1,440,985 cars and Slovakia 1,073,050 cars in 2025, with Slovak output up 8.1%, according to ACEA data reported by Kallanish. The Debrecen plant noted above adds electric car volume in Hungary. Hutchinson's Mannheim hub, noted above, also serves Eastern European customers from Germany.
Acquisitions, hubs and battery seals mark 2025-2026
| Development | Status and market relevance |
|---|---|
| In April 2025, Freudenberg Sealing Technologies launched a new elastomer material for battery cell O-rings as an alternative to PFAS-containing seals. | Launch; the company says the seals can be injection molded in large series for battery cell makers. |
| In September 2025, Freudenberg Sealing Technologies dedicated an 8,800 square meter automated warehouse in Hamburg, Germany. | Completed investment; the site supplies general industry and technical trade customers with faster picking of stocked seals. |
| In September 2025, Hutchinson inaugurated an automated 3,600 square meter O-ring and bonded seal distribution center in Mannheim, Germany. | Operational launch; the hub serves Germany, Northern Europe and Eastern Europe with 17,000 bin positions. |
| In January 2026, Trelleborg completed the acquisition of Nexus Elastomer Molds, an Austrian maker of liquid silicone rubber tooling. | Completed acquisition; it brings tooling and automated cells in house for Trelleborg Sealing Solutions and its medical unit. |
| In September 2026, Trelleborg completed the acquisition of M+R Dichtungstechnik of Seligenstadt, Germany. | Completed acquisition; it adds extruded rubber profiles for facades, solar and wind sold mainly in Central Europe. |
Compounds, overmolding and metal gaskets define performance
- Fluorine-free elastomer compounds replace FKM and thermoplastics in battery cells and fluid systems, which lowers PFAS exposure for carmakers while keeping electrolyte and coolant leakage low over the service life.
- Overmolded gasket-plate units bond EPDM or FKM seals directly onto metal or composite plates, which speeds assembly of electrolyzer stacks and battery packs and removes a separate gasket handling step.
- Spiral wound and kammprofile gaskets combine metal windings or grooved cores with graphite or PTFE facings to hold tightness on high-pressure flanges.
- Liquid silicone rubber molding produces precise, flash-free seals in automated cells, which suits medical, connector and small-batch industrial parts.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Full-line groups lead while flange specialists hold niches
Competition in the Europe gasket and seals market turns on compound know-how, OEM approvals and service reach rather than on price alone. Freudenberg Sealing Technologies and Trelleborg Sealing Solutions run the broadest European ranges, and Trelleborg added tooling and profile makers in Austria and Germany in 2026. SKF and Parker pair seals with bearings and fluid power systems. ElringKlinger and Dana Victor Reinz serve engine, battery and aftermarket gasket buyers, while Hutchinson supplies body and precision sealing systems. KLINGER, Flexitallic and James Walker compete in flange gaskets and packing for refineries, chemical plants and power stations. Carmakers usually approve two sources per part, while process plants often standardize on one gasket brand per site. The ten companies profiled below cover elastomer seals, gaskets and body sealing.
How is the supply side organized and where do margins sit?
Supply in the region runs in three distinct tiers of companies. Full-line groups such as Freudenberg, Trelleborg, SKF and Parker cover elastomer compounding, molding and global OEM programs, which gives them the testing and approval resources that carmakers and aircraft makers require. Automotive specialists such as ElringKlinger, Dana Victor Reinz and Hutchinson focus on engine gaskets, battery seals and body sealing systems. A third tier of flange and packing specialists, including KLINGER, Flexitallic and James Walker, serves process plants through local service centers. Entry barriers sit in compound know-how, OEM approval and tooling. Margins are highest in qualified aerospace and process sealing and thinnest in high-volume automotive parts.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Freudenberg Sealing Technologies (Freudenberg Group) | Full-line supplier | Simmerring shaft seals, O-rings, battery and electrolyzer gaskets for OEM and industry |
| Trelleborg Sealing Solutions (Trelleborg AB) | Full-line supplier | Polymer seals, O-rings, rotary and hydraulic seals, liquid silicone rubber parts |
| SKF Group | Bearing and seal maker | Radial shaft seals and industrial seals sold with bearings and services |
| ElringKlinger AG | Automotive specialist | Cylinder head and specialty gaskets plus battery and fuel cell components |
| Dana Incorporated (Victor Reinz) | Automotive specialist | Victor Reinz engine gaskets and seal kits for OEM and aftermarket |
| Hutchinson (TotalEnergies) | Automotive and precision specialist | Body sealing systems, O-rings and bonded seals for vehicles and industry |
| KLINGER Group | Industrial gasket specialist | Fiber, graphite, PTFE and spiral wound flange gaskets, packing and valves |
| Parker Hannifin Corporation | Full-line supplier | O-rings, hydraulic and pneumatic seals and aerospace sealing systems |
| James Walker Group | Industrial seal specialist | Compression packing, gaskets and high-performance elastomer seals for energy and process |
| Flexitallic Group | Industrial gasket specialist | Spiral wound, kammprofile and soft gaskets with bolting engineering services |
Content per car and compliance decide the winners
Credence Research's view is that content per car and compliance work decide the winners in the Europe gasket and seals market. Electrified cars add battery, cooling and connector seals, but suppliers lose classic engine gaskets as petrol volumes fall, so the net gain depends on winning new battery programs. Process plant buyers will pay for certified low-emission gaskets as methane rules bite, which favors flange specialists with testing records. The PFAS decision is the largest single risk, and buyers should qualify fluorine-free alternatives now for every application where they can match performance.
Earlier estimate rolled forward and tested top down
The report uses 2025 as the base year and forecasts to 2035. The earlier Credence Research estimate for 2024 was rolled forward one year at its own growth rate and tested top down against the size of global sealing demand, the region's share of car output and an estimate of sales by the leading European sealing makers. Country and segment shares are Credence Research estimates based on car production, process industry activity, aircraft output and wind installations. Sources include ACEA, European Commission, World Bank and WindEurope data, company releases, distributor list prices and trade press. No interviews or surveys were conducted for this update of the estimate.
Electrified cars and process compliance carry growth to 2035
Growth to 2035 depends on how quickly car production stabilizes, how the PFAS restriction is finalized and how fast aircraft and hydrogen programs ramp. The base case assumes car output stays near 2025 levels, electrified cars keep raising seal content per vehicle and fluoropolymer seals receive multiyear transition periods. Semi-metallic gaskets and aerospace seals should gain share as methane compliance and aircraft backlogs pull high-specification parts. Central Europe should keep adding assembly capacity, while Germany remains the largest single country market through the forecast period. The main risk to this path is a strict PFAS ban with short transitions, which would force requalification of many fluoropolymer seals in chemical and aircraft uses.
PFAS rules and car output set the range of outcomes
The spread of outcomes depends mainly on the final PFAS restriction and on how fast European car production recovers. A strict ban with short transitions would force costly requalification of fluoropolymer seals, while a broad sealing derogation would leave current product lines intact. Aircraft build rates and methane compliance work set the upside, because both pull high-margin seals.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 3.5% | USD 20.69 billion | A strict PFAS ban arrives with short transitions and car output keeps falling |
| Base | 4.92% | USD 23.35 billion | Standard PFAS transition periods apply and car output stays near 2025 levels |
| Upside | 6.1% | USD 25.87 billion | Sealing uses win a broad derogation and aircraft and hydrogen programs ramp on plan |
Frequently Asked Questions
How big is the Europe gasket and seals market?
How large is Germany in European gasket and seal demand?
Which product type holds the largest share?
Who are the main gasket and seal suppliers in Europe?
How do Trelleborg and Freudenberg differ in this market?
What lead times are realistic for bespoke seals?
How will PFAS rules affect high-temperature seals?
Which application grows fastest?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Molded Packing & Seals
- 1.2.2 Non-metallic Gaskets
- 1.2.3 Shaft Seals
- 1.2.4 Motor Vehicle Body Seals
- 1.2.5 Semi-metallic Gaskets
- 1.2.6 Metallic Gaskets
- 1.3 By Application
- 1.3.1 Automotive
- 1.3.2 Industrial & Manufacturing
- 1.3.3 Oil & Gas
- 1.3.4 Chemicals & Petrochemicals
- 1.3.5 Electrical & Electronics
- 1.3.6 Aerospace
- 1.3.7 Marine & Rail
- 1.3.8 Others
- 1.4 By End User
- 1.4.1 Original Equipment Manufacturer (OEM)
- 1.4.2 Aftersales Market
- 1.5 By Country
- 1.5.1 Germany
- 1.5.2 France
- 1.5.3 United Kingdom
- 1.5.4 Italy
- 1.5.5 Spain
- 1.5.6 Rest of Europe
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 14.45 billion → 2035: USD 23.35 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Gasket and Seals Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Gasket and Seals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Gasket and Seals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Gasket and Seals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Gasket and Seals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Gasket and Seals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Gasket and Seals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Gasket and Seals Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 14.45 billion → 2035: USD 23.35 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Gasket and Seals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Molded Packing & Seals
- 12.3.7.2 Non-metallic Gaskets
- 12.3.7.3 Shaft Seals
- 12.3.7.4 Motor Vehicle Body Seals
- 12.3.7.5 Semi-metallic Gaskets
- 12.3.7.6 Metallic Gaskets
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automotive
- 12.4.7.2 Industrial & Manufacturing
- 12.4.7.3 Oil & Gas
- 12.4.7.4 Chemicals & Petrochemicals
- 12.4.7.5 Electrical & Electronics
- 12.4.7.6 Aerospace
- 12.4.7.7 Marine & Rail
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Original Equipment Manufacturer (OEM)
- 12.5.7.2 Aftersales Market
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Country - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Germany
- 12.6.7.2 France
- 12.6.7.3 United Kingdom
- 12.6.7.4 Italy
- 12.6.7.5 Spain
- 12.6.7.6 Rest of Europe
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Gasket and Seals End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Gasket and Seals Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Country-Level Shares, 2025
- 14.2 Country Market Size Comparison, 2025
- 14.3 Country Market Forecasts, 2025-2035
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Gasket and Seals Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Gasket and Seals Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Freudenberg Sealing Technologies (Freudenberg Group)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Trelleborg Sealing Solutions (Trelleborg AB)
- 18.4 SKF Group
- 18.5 ElringKlinger AG
- 18.6 Dana Incorporated (Victor Reinz)
- 18.7 Hutchinson (TotalEnergies)
- 18.8 KLINGER Group
- 18.9 Parker Hannifin Corporation
- 18.10 James Walker Group
- 18.11 Flexitallic Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

