
Market Overview
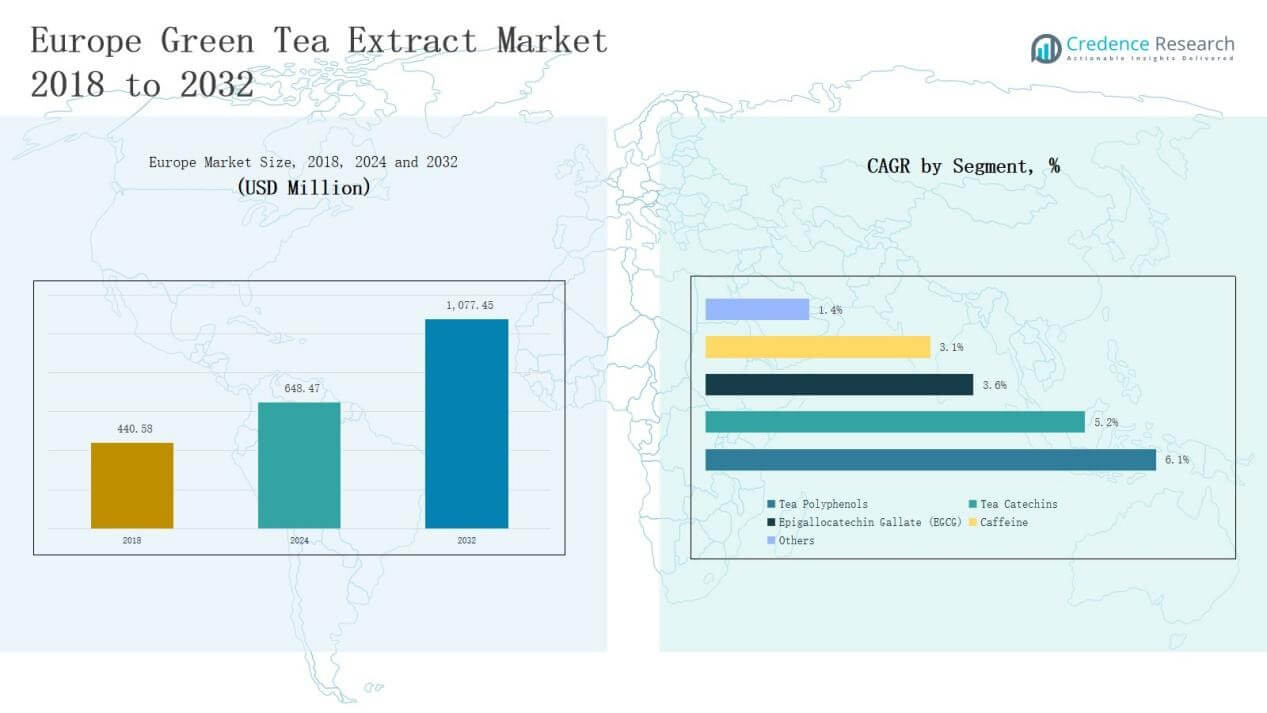
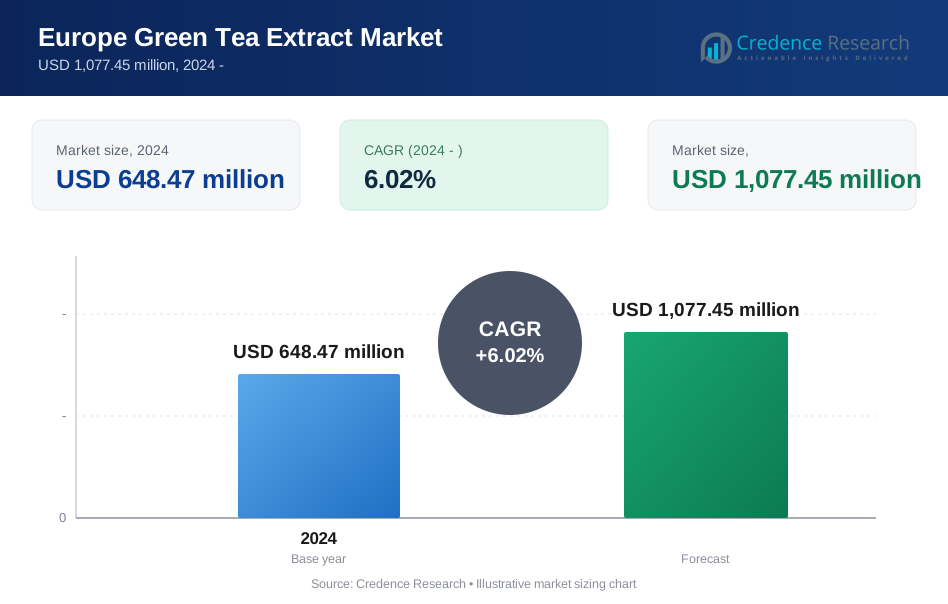
Europe Green Tea Extract Market size was valued at USD 440.58 million in 2018, reaching USD 648.47 million in 2024, and is anticipated to attain USD 1,077.45 million by 2032, at a CAGR of 6.02% during the forecast period (2024–2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Green Tea Extract Market Size 2024 | USD 648.47 Million |
| Europe Green Tea Extract Market, CAGR | 6.02% |
| Europe Green Tea Extract Market Size 2032 | USD 1,077.45 Million |
The Europe Green Tea Extract Market is highly competitive, with leading players including Tate & Lyle PLC, MartinBauer Group, DSM Nutritional Products, Givaudan, and Unilever’s Lipton brand, supported by regional specialists such as Pukka Herbs, Clipper Teas, Yogi Tea Europe GmbH, Nexira, Naturex SA, Pierre Fabre Group, Arkopharma, and Robertet Group. These companies focus on product innovation, sustainable sourcing, and expanding applications across nutraceuticals, functional beverages, and cosmetics to strengthen market presence. Regionally, Germany leads with a 34% share in 2024, driven by strong nutraceutical adoption, advanced retail infrastructure, and increasing consumer demand for clean-label, premium formulations.
Market Insights
- The Europe Green Tea Extract Market grew from USD 440.58 million in 2018 to USD 648.47 million in 2024 and is projected to reach USD 1,077.45 million by 2032.
- Tea Catechins lead the market with a 38% share in 2024, driven by strong demand in nutraceuticals and beverages for their antioxidant, weight management, and anti-aging benefits.
- Powder form dominates with a 46% share in 2024, supported by its stability, longer shelf life, solubility, and widespread use across supplements, functional foods, and cosmetics.
- Nutraceuticals & Dietary Supplements hold the largest application share at 41% in 2024, boosted by rising health awareness, EGCG-rich formulations, and preventive healthcare adoption in Europe.
- Germany leads regionally with 34% share in 2024, followed by the United Kingdom at 28%, France at 19%, Italy at 12%, and Rest of Europe at 7%.
Market Segment Insights
By Product Type
Tea Catechins dominate the Europe Green Tea Extract Market with a 38% share in 2024, supported by their wide recognition as natural antioxidants with proven health benefits. They are increasingly used in cardiovascular health, weight management, and anti-aging solutions, making them the preferred ingredient across nutraceuticals and beverages. Growing consumer demand for clean-label products and functional ingredients has further fueled catechin adoption, while expanding clinical evidence supporting their efficacy continues to strengthen this segment’s market leadership.
For instance, Kemin Industries Europe launched green tea-derived functional ingredients under its Phenolic Antioxidants portfolio, targeting clean-label beverage fortification and anti-aging solutions.
By Form
Powder form leads the Europe market with a 46% share in 2024, reflecting its versatility and strong demand from food, nutraceutical, and cosmetic industries. Powdered extracts are widely favored due to their stability, ease of transport, and longer shelf life compared to liquid or capsule alternatives. They offer excellent solubility in formulations, making them suitable for beverages, supplements, and functional foods. Rising application in sports nutrition and fortified food categories has reinforced powdered extracts as the most dominant form in Europe.
For instance, Nestlé Health Science expanded its Optifast powdered meal replacement range in Europe, highlighting demand for convenient, protein-rich nutrition in weight management and sports categories.
By Application
Nutraceuticals & Dietary Supplements remain the largest application segment, accounting for 41% of the Europe Green Tea Extract Market in 2024. This dominance is driven by rising consumer preference for natural supplements targeting weight management, immunity boosting, and overall wellness. Growing demand for EGCG-rich formulations in capsule and powder formats has strengthened the role of green tea extracts in preventive healthcare. Increasing health awareness, coupled with Europe’s aging population, continues to support strong growth momentum within the nutraceuticals segment.
 Key Growth Drivers
Rising Demand for Nutraceuticals and Functional Foods
The growing consumer shift toward preventive healthcare is a primary driver of the Europe Green Tea Extract Market. Nutraceuticals and functional foods enriched with green tea extracts are gaining traction due to their antioxidant, anti-inflammatory, and weight management benefits. Rising cases of lifestyle-related diseases, combined with increasing consumer preference for natural and plant-based products, are accelerating demand. This trend is particularly strong in developed European countries, where health-conscious consumers are seeking supplements that align with clean-label and organic claims.
For instance, Arkopharma launched green-tea-extract-based weight management capsules in France under its Arkocaps line, responding to growing demand for plant-based and clean-label dietary supplements.
Expanding Applications in Cosmetics and Personal Care
Green tea extract has become a critical ingredient in cosmetics due to its anti-aging, anti-inflammatory, and skin-protective properties. Growing consumer focus on natural skincare and rising demand for herbal beauty products are boosting market expansion. Major European cosmetic brands increasingly incorporate EGCG-rich formulations into facial creams, serums, and hair care products to appeal to eco-conscious consumers. Regulatory encouragement for safer, plant-derived cosmetic ingredients is further driving adoption. This diversification of applications ensures steady demand beyond traditional nutraceutical and food categories.
For instance, Beiersdorf’s Nivea introduced a Naturally Good Green Tea Face Cream in Germany, formulated with green tea extract to address consumer demand for sustainable, plant-based ingredients.
Strong R&D Investments and Product Innovation
Continuous investments in research and development by both multinational players and regional firms are fueling innovation in Europe’s green tea extract market. Companies are focusing on developing high-purity extracts, EGCG-enriched products, and sustainable sourcing practices to meet evolving consumer expectations. Partnerships between research institutions and nutraceutical companies are also contributing to new clinical validations, enhancing consumer trust. The emphasis on customized formulations, such as capsules, functional beverages, and powders, strengthens market penetration across diverse applications while ensuring long-term growth momentum.
Key Trends & Opportunities
Clean-Label and Organic Product Preference
European consumers increasingly favor clean-label and organic products, creating opportunities for green tea extract producers. Extracts marketed as non-GMO, sustainably sourced, and free from synthetic additives are enjoying strong growth across nutraceuticals, food, and cosmetics. Manufacturers investing in organic-certified extracts are well-positioned to capture premium segments. With rising demand for transparency and traceability in sourcing, brands emphasizing sustainability and ethical practices are expected to gain consumer trust, strengthening their competitive edge in the European marketplace.
For instance, Taiyo GmbH introduced its Sunphenon organic green tea extract range in Europe, emphasizing EU-organic certification and clean-label positioning for functional beverages.
Growth in Functional Beverages Market
The functional beverages sector in Europe presents a strong opportunity for green tea extract integration. Rising consumer preference for ready-to-drink teas, energy drinks, and wellness beverages enriched with catechins and EGCG is boosting demand. Health-conscious millennials and urban consumers are driving this shift, seeking convenient formats for daily nutrition. Manufacturers are increasingly collaborating with beverage brands to introduce innovative, plant-based drinks with added health benefits. This trend highlights the potential of green tea extracts to expand further in Europe’s dynamic beverage industry.
For instance, At Vitafoods Europe 2024, Indena, in partnership with dsm-firmenich, showcased new dietary supplements combining botanicals with biotics. These products target gut health, brain health, and healthy aging and were presented in easy-to-use formats like gummies and oral dispersible granules.
Key Challenges
High Production and Extraction Costs
One of the major challenges in the Europe Green Tea Extract Market is the high cost of production and extraction. Advanced processing techniques required to preserve active compounds like EGCG significantly increase expenses. Sourcing high-quality raw materials further adds to operational costs, especially for organic-certified products. These higher costs often lead to premium pricing, which can restrict accessibility among price-sensitive consumers. Companies face the dual challenge of balancing affordability with quality while maintaining competitiveness in both domestic and export markets.
Regulatory Compliance and Quality Standards
Stringent regulations across Europe regarding dietary supplements, food additives, and cosmetic ingredients pose challenges for green tea extract manufacturers. Compliance with European Food Safety Authority (EFSA) and other regional standards requires significant documentation, testing, and approval timelines. Variations in labeling, dosage restrictions, and health claims across different countries further complicate market entry. Non-compliance risks include product recalls, fines, and reputational damage. Companies must continually invest in quality assurance, certifications, and regulatory expertise to maintain credibility and ensure long-term success.
Market Saturation and Intense Competition
The Europe Green Tea Extract Market faces growing competition from multinational corporations and specialized regional players. Established companies dominate through broad product portfolios, advanced research capabilities, and strong distribution networks, making it difficult for smaller players to gain share. Market saturation in mature countries such as Germany, the UK, and France further intensifies competition, forcing companies to differentiate through innovation or pricing strategies. This competitive pressure often limits margins, creating challenges for sustainable growth in a crowded market landscape.
Regional Analysis
Germany
Germany holds a 34% share of the Europe Green Tea Extract Market in 2024, making it the regional leader. Strong consumer preference for nutraceuticals and functional foods drives growth. The country benefits from advanced retail infrastructure and a health-conscious population that values clean-label products. Pharmaceutical and dietary supplement companies continue to integrate high-purity catechins and EGCG into formulations, reinforcing Germany’s market dominance. Regulatory clarity and established quality standards also encourage innovation. German cosmetic brands further expand usage, ensuring diverse applications for sustained demand.
United Kingdom
The United Kingdom captures a 28% share of the market in 2024, supported by strong demand for nutraceuticals, functional beverages, and herbal teas. Established companies such as Twinings and Unilever’s Lipton brand strengthen the segment through wide distribution and product variety. Consumer awareness of preventive health and preference for organic products enhances growth. The UK also benefits from advanced R&D facilities and regulatory frameworks that encourage natural ingredient adoption. Cosmetics and personal care segments add momentum, widening the market scope.
France
France accounts for a 19% share of the market in 2024, reflecting its strong tradition of herbal wellness and natural product consumption. French companies emphasize sustainable sourcing and innovation across food, nutraceutical, and cosmetic sectors. Demand for green tea extracts in dietary supplements and beauty products continues to grow, supported by rising awareness of skin health and aging concerns. Northern France plays a pivotal role with robust retail and R&D infrastructure. Domestic players compete effectively alongside multinational corporations, ensuring steady expansion.
Italy
Italy holds a 12% share of the Europe Green Tea Extract Market in 2024, supported by rising health consciousness and interest in premium wellness products. Northern Italy drives most of the demand due to strong retail penetration and consumer preference for high-quality, organic formulations. Pharmaceutical and nutraceutical companies adopt EGCG-rich extracts to meet growing demand for natural healthcare products. Italian cosmetic brands also highlight green tea extracts in skincare applications, widening usage. Local firms compete with multinational players through specialized, innovative extracts.
Rest of Europe
The Rest of Europe contributes a 7% share in 2024, covering Spain, the Netherlands, and other regional markets. Growth is supported by increasing adoption of functional foods, beverages, and dietary supplements. Rising disposable income and awareness of natural wellness products help expand demand across these countries. Cosmetics and personal care segments show significant growth potential, particularly in Spain. Smaller domestic producers also focus on sustainable, organic offerings to compete with multinational firms. Although smaller in size, the region represents emerging opportunities.
Market Segmentations:
By Product Type
- Tea Catechins
- Epigallocatechin Gallate (EGCG)
- Polyphenols
- Others
By Form
- Powder
- Liquid
- Capsule/Tablets
By Application
- Pharmaceuticals
- Nutraceuticals & Dietary Supplements
- Food & Beverages
- Cosmetics & Personal Care
- Others
By Distribution Channel
- Online Stores
- Specialty Stores
- Supermarkets/Hypermarkets
- Pharmacies
- Others
By Region
- Germany
- UK
- France
- Italy
- Spain
- Rest of Europe
Competitive Landscape
The Europe Green Tea Extract Market is highly competitive, shaped by the presence of multinational corporations and strong regional specialists. Leading players such as Tate & Lyle, MartinBauer Group, DSM Nutritional Products, Givaudan, and Unilever’s Lipton brand dominate with extensive product portfolios, global distribution networks, and advanced research capabilities. Regional players including Pukka Herbs, Clipper Teas, and Yogi Tea Europe GmbH enhance competition by focusing on organic, clean-label, and sustainably sourced extracts that appeal to health-conscious consumers. Companies invest heavily in product innovation, clinical validation, and eco-friendly sourcing to strengthen market positioning. Strategic collaborations with pharmaceutical, nutraceutical, and cosmetic firms further expand applications across dietary supplements, functional beverages, and personal care. Growing demand for EGCG-rich and high-purity formulations has led to intensified R&D investments, while competitive pricing and private-label growth in retail channels continue to challenge established brands. This dynamic landscape fosters innovation and ensures consistent market growth.
Key Players
- Tate & Lyle PLC
- Twinings
- Unilever (Lipton brand)
- MartinBauer Group
- DSM Nutritional Products
- Givaudan
- Nexira
- Naturex SA
- Pierre Fabre Group
- Arkopharma
- Robertet Group
- Sensient Technologies
- Pukka Herbs
- Clipper Teas
- Yogi Tea Europe GmbH
- Finlays
Recent Developments
- In October 2024, PLT Health Solutions added Cellflo6, a patented green tea extract, to its portfolio to support energy, sports performance, and overall wellness with applications in beverages and dietary supplements.
- In July 2024, the RASFF (EU safety alert system) flagged a supplement from Germany for missing mandatory labelling of EGCG in green tea extract. ss
Report Coverage
The research report offers an in-depth analysis based on Product Type, Form, Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for nutraceuticals will continue driving adoption of green tea extracts across Europe.
- Functional beverages will expand as a major application segment supported by health-conscious consumers.
- Cosmetic brands will increasingly integrate green tea extracts in skincare and haircare products.
- Organic and clean-label extracts will gain stronger consumer preference across multiple product categories.
- Pharmaceutical applications will grow with rising research on therapeutic benefits of catechins and EGCG.
- Retail and e-commerce channels will enhance accessibility, strengthening sales in both urban and rural markets.
- Private-label brands will intensify competition by offering affordable green tea extract-based products.
- Sustainability and traceability in sourcing will become critical factors influencing consumer trust.
- Innovation in high-purity and customized formulations will shape new growth opportunities for manufacturers.
- Emerging regions within Europe will witness higher adoption, widening the overall market base.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Green Tea Extract Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Green Tea Extract Market projected to grow between 2025 and 2032?
Which Europe Green Tea Extract Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe Green Tea Extract Market?
Who are the leading companies in the Europe Green Tea Extract Market?
Which region commanded the largest share of the Europe Green Tea Extract Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Green Tea Extract Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Green Tea Extract Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 648.47 million → forecast year: USD 1,077.45 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Green Tea Extract Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Green Tea Extract Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Green Tea Extract Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Green Tea Extract Market Drivers
- 3.3 Europe Green Tea Extract Market Restraints & Challenges
- 3.4 Europe Green Tea Extract Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Green Tea Extract Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Green Tea Extract Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Green Tea Extract category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Green Tea Extract Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Green Tea Extract Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Green Tea Extract market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Green Tea Extract Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Green Tea Extract Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Green Tea Extract Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Green Tea Extract (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Green Tea Extract Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Green Tea Extract Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Green Tea Extract Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Green Tea Extract Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Green Tea Extract Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Green Tea Extract Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Green Tea Extract Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Green Tea Extract Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Green Tea Extract Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
