
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Medical Radiation Detection, Monitoring And Safety Market Size 2023 | USD 884.69 Million |
| Europe Medical Radiation Detection, Monitoring And Safety Market, CAGR | 6.74% |
| Europe Medical Radiation Detection, Monitoring And Safety Market Size 2032 | USD 1,490.69 Million |
Market Overview
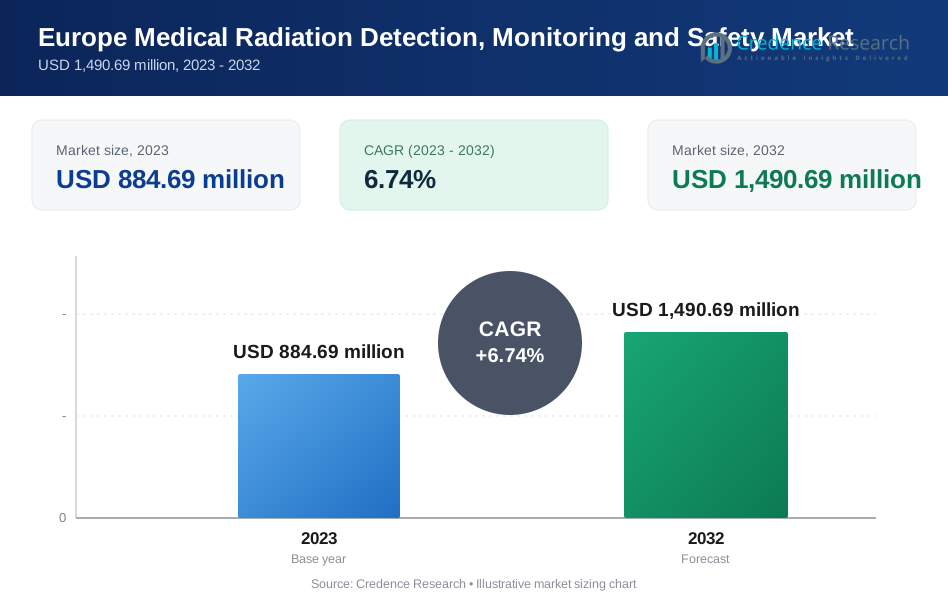
The Europe Medical Radiation Detection, Monitoring And Safety Market is projected to grow from USD 884.69 million in 2023 to USD 1,490.69 million by 2032, registering a CAGR of 6.74% during the forecast period.
The Europe medical radiation detection, monitoring, and safety market is driven by the increasing adoption of advanced imaging technologies, such as computed tomography (CT) and magnetic resonance imaging (MRI), which require enhanced radiation safety measures. Rising concerns about the adverse health effects of prolonged radiation exposure have led to stricter regulatory guidelines, boosting the demand for radiation detection and monitoring devices. Additionally, the growing prevalence of cancer and the expansion of nuclear medicine and radiotherapy treatments further support market growth. Industry trends indicate a shift toward more portable and wearable radiation detection devices, improving convenience and real-time monitoring capabilities for healthcare professionals. Technological advancements in integrating artificial intelligence (AI) for better radiation dose management and data analytics are gaining traction, enhancing operational efficiency and patient safety. The market is also witnessing increased investments in research and development to produce more efficient and cost-effective radiation safety solutions, contributing to its steady expansion.
The Europe medical radiation detection, monitoring, and safety market is characterized by diverse growth opportunities across key regions such as the UK, Germany, France, and Italy. Leading players in the market, including Mirion Technologies, IBA Dosimetry GmbH, PTW Freiburg GmbH, and Thermo Fisher Scientific Inc., play a significant role in driving technological advancements and expanding market presence. These companies offer a wide range of radiation detection devices, from gas-filled detectors to scintillators and solid-state detectors, catering to various applications such as diagnostic imaging, nuclear medicine, and radiation therapy. As healthcare systems in Europe modernize and regulatory standards become stricter, the demand for reliable radiation safety equipment is on the rise. Companies like Sun Nuclear Corporation, Fluke Biomedical, and Tracerco are also contributing to the market with innovative solutions, ensuring the protection of both patients and healthcare professionals in radiology departments and treatment centers.
Market Insights
- The Europe medical radiation detection, monitoring, and safety market was valued at USD 884.69 million in 2023 and is projected to reach USD 1,490.69 million by 2032, growing at a CAGR of 6.74%.
- Increasing demand for advanced diagnostic imaging technologies is driving market growth, especially in radiology departments.
- The adoption of portable and wearable radiation detectors is a prominent trend, offering flexibility and real-time monitoring for healthcare professionals.
- Stringent regulatory standards in Europe require healthcare facilities to invest in state-of-the-art radiation detection systems to ensure patient and staff safety.
- High initial costs of advanced radiation safety equipment and the complexity of regulatory compliance are key market restraints.
- The UK and Germany are key regions driving market demand due to their advanced healthcare infrastructures and high adoption rates of medical imaging technologies.
- Competitive players like Mirion Technologies, Thermo Fisher Scientific, and IBA Dosimetry are leading the market with innovative solutions.
Market Drivers
Increasing Regulatory Compliance and Safety Standards
Stringent regulatory frameworks and enhanced safety standards related to radiation protection are significantly influencing market growth. Regulatory bodies such as the European Atomic Energy Community (EURATOM) enforce directives that mandate radiation exposure monitoring and safety guidelines for healthcare workers and patients. For instance, the Basic Safety Standards Directive 2013/59/EURATOM lays down basic safety standards for protection against the dangers arising from exposure to ionizing radiation. Compliance with these regulations drives investments in sophisticated radiation detection systems, including personal dosimeters and area monitors, to ensure occupational safety and reduce radiation risks. The growing emphasis on regulatory compliance encourages healthcare facilities to adopt advanced radiation protection solutions, fostering market expansion.
Expanding Use of Radiotherapy and Nuclear Medicine
The rising prevalence of cancer in Europe has led to the increased adoption of radiotherapy and nuclear medicine procedures, boosting the demand for medical radiation detection and safety equipment. Radiotherapy treatments involve the use of high-energy radiation to target cancer cells, necessitating stringent radiation safety protocols to minimize exposure risks. Additionally, nuclear medicine procedures, which utilize radioactive isotopes for imaging and treatment, further drive the requirement for robust monitoring systems. For instance, Nuclear Medicine Europe reported significant advancements and increased adoption of nuclear medicine procedures across the continent. The expanding application of these therapies supports the sustained growth of radiation detection and monitoring technologies.
Rising Demand for Advanced Diagnostic Imaging Technologies
The growing adoption of advanced diagnostic imaging technologies, including X-ray systems, computed tomography (CT) scans, and magnetic resonance imaging (MRI), is a major driver of the Europe medical radiation detection, monitoring, and safety market. These imaging systems are integral to modern healthcare, offering critical insights for accurate diagnosis and treatment planning. However, their increased use elevates the need for effective radiation safety measures to protect both patients and healthcare professionals from harmful exposure. As hospitals and diagnostic centers invest in advanced imaging solutions, the demand for radiation detection and monitoring devices continues to surge across Europe.
Technological Advancements in Radiation Safety Solutions
Technological innovations in radiation detection and safety systems are transforming the market landscape. The integration of artificial intelligence (AI) and data analytics enhances radiation dose management and real-time monitoring capabilities, improving safety outcomes. Furthermore, the development of portable and wearable radiation detectors increases convenience for healthcare professionals. These advancements, coupled with the growing focus on cost-effective and user-friendly solutions, contribute to the evolving dynamics of the Europe medical radiation detection, monitoring, and safety market.
Market Trends
Rising Investment in Hybrid Radiation Safety Solutions
The demand for hybrid radiation safety solutions that combine detection, monitoring, and protection capabilities into a single system is growing. These comprehensive solutions streamline radiation safety management, offering greater efficiency and reliability. For instance, the European Commission's Joint Research Centre has explored the potential for using unmanned systems for radiation measurements and sampling, highlighting the integration of multiple functionalities into single systems. Innovations integrating shielding materials with real-time monitoring sensors reflect this trend, reducing the need for multiple standalone devices. Hybrid solutions cater to the evolving needs of modern healthcare facilities seeking cost-effective, integrated safety systems, further propelling market advancements.
Increased Adoption of Portable and Wearable Radiation Detection Devices
The Europe medical radiation detection, monitoring, and safety market is witnessing a significant shift toward portable and wearable radiation detection devices. These innovations offer healthcare professionals enhanced mobility and convenience, enabling real-time radiation exposure monitoring. Wearable dosimeters, which integrate advanced sensors, provide continuous data collection without hindering routine activities. The rising preference for these compact, user-friendly devices reflects the growing need for efficient radiation safety measures in dynamic clinical environments, such as diagnostic imaging departments and oncology units.
Integration of Artificial Intelligence for Dose Optimization
Artificial intelligence (AI) is increasingly transforming radiation safety and monitoring practices by enabling intelligent dose optimization and predictive analytics. AI-driven radiation detection systems help healthcare providers accurately track exposure levels and predict potential risks, leading to more personalized radiation management strategies. Advanced algorithms allow for automated data analysis, minimizing human errors while enhancing safety protocols. This trend aligns with the broader movement toward precision medicine and reflects growing investments in smart healthcare technologies across Europe.
Growing Focus on Radiation Safety Training and Awareness
Increased emphasis on radiation safety training and education for healthcare workers is emerging as a notable trend. Regulatory mandates across Europe stress the importance of training programs to ensure compliance with radiation safety standards and to mitigate exposure risks. The proliferation of online and simulation-based training platforms has made radiation safety education more accessible, further enhancing awareness among medical professionals. This heightened focus on skill enhancement drives demand for advanced monitoring equipment that supports safety compliance efforts.
Market Challenges Analysis
High Costs of Advanced Radiation Detection Systems
One of the key challenges facing the Europe medical radiation detection, monitoring, and safety market is the high initial cost associated with advanced radiation detection systems. While these devices offer superior functionality, precision, and real-time monitoring capabilities, their high purchase and maintenance costs can be a barrier, particularly for smaller healthcare facilities or institutions with limited budgets. Additionally, continuous advancements in technology often lead to rapid obsolescence, requiring ongoing investments in system upgrades and training. This financial burden may discourage some healthcare providers from adopting the latest solutions, thereby limiting the widespread deployment of state-of-the-art radiation safety equipment across all medical settings.
Regulatory and Compliance Complexities
The complexity of navigating regulatory requirements across Europe presents another challenge for the medical radiation safety market. While stringent regulations are essential for ensuring radiation protection, they also require significant time and effort for healthcare facilities to stay compliant. Different countries within Europe may have varying safety standards and certification processes, complicating the implementation of uniform radiation safety measures across the region. For instance, the European Society of Radiology (ESR) released findings from a large survey that assessed compliance with the European Council Basic Safety Standards Directive (BSSD) radiation protection requirements, highlighting the need for coordinated intervention to address compliance issues. Furthermore, healthcare organizations must continuously adapt to evolving regulations and invest in staff training and equipment upgrades to meet the latest safety standards. These challenges can delay the adoption of new technologies and increase operational costs, hindering market growth.
Market Opportunities
Expanding Demand in Emerging Healthcare Markets
The growing healthcare infrastructure in emerging European markets presents a significant opportunity for the medical radiation detection, monitoring, and safety industry. As these regions invest in modern healthcare facilities and diagnostic technologies, there is an increasing need for advanced radiation safety equipment. The expansion of radiology departments, oncology centers, and diagnostic imaging services in countries with evolving healthcare systems offers a vast market for radiation detection and monitoring solutions. Companies can leverage this opportunity by providing tailored, cost-effective products designed for these markets, ensuring compliance with European safety regulations while enhancing patient and healthcare worker protection.
Technological Advancements and Innovation
Continued advancements in technology open new avenues for growth in the European medical radiation detection market. Innovations such as AI-powered radiation dose management systems and integrated safety solutions create opportunities to improve the efficiency and accuracy of radiation monitoring. These technological enhancements offer better management of radiation exposure, providing healthcare facilities with real-time data for informed decision-making. Additionally, there is growing potential in developing hybrid systems that combine radiation detection, monitoring, and protection into a single device, streamlining operations and reducing costs for healthcare providers. The market for portable and wearable radiation detection devices is also expanding, driven by the increasing demand for mobility and ease of use in clinical settings. By focusing on innovation, the market can address evolving safety needs while positioning itself for sustained growth.
Market Segmentation Analysis:
By Type:
The Europe medical radiation detection, monitoring, and safety market is segmented into three primary types: gas-filled detectors, scintillators, and solid-state detectors. Gas-filled detectors, such as ionization chambers, are commonly used for radiation monitoring due to their ability to accurately measure a wide range of radiation levels. Scintillators, which emit light when exposed to radiation, are often used in diagnostic imaging and radiation therapy due to their sensitivity and fast response times. Solid-state detectors, known for their compact size and high precision, are increasingly favored in medical applications, particularly in portable devices. These detectors provide real-time data, making them ideal for continuous monitoring. Each type offers distinct advantages in terms of sensitivity, response time, and application suitability, with varying levels of cost and complexity, allowing healthcare providers to select the most appropriate solutions based on specific needs and radiation exposure levels.
By Application:
The medical radiation detection market in Europe is also segmented by application, including radiation therapy, diagnostic imaging, and nuclear medicine. Radiation therapy, which utilizes high-energy radiation to treat cancer, drives demand for advanced radiation safety devices to minimize exposure to healthy tissues. Diagnostic imaging, encompassing techniques like X-rays and CT scans, relies on radiation detection to ensure safety while delivering accurate diagnostic results. The increasing use of medical imaging systems in both routine and specialized healthcare applications contributes to the market's growth. Nuclear medicine, which involves the use of radioactive isotopes for diagnosis and treatment, further amplifies the need for radiation monitoring solutions. Each application requires tailored radiation detection and safety systems to address specific risks and regulatory requirements, thus expanding the market opportunities in these segments.
Segments:
Based on Type:
- Gas-Filled Detectors
- Scintillators
- Solid-State Detectors
Based on Application:
- Radiation Therapy
- Diagnostic Imaging
- Nuclear Medicine
Based on End-user:
- Hospitals
- Diagnostic Centers
- Ambulatory Surgical Centers
Based on the Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
Regional Analysis
UK and Germany
The United Kingdom holds a significant share of the Europe medical radiation detection, monitoring, and safety market, accounting for approximately 25% of the total market in 2023. This can be attributed to the country's advanced healthcare infrastructure and the growing demand for diagnostic imaging and radiation therapy in medical institutions. The UK's regulatory framework and focus on patient safety further drive the adoption of advanced radiation detection and safety solutions. Additionally, the increasing prevalence of cancer and the adoption of nuclear medicine therapies are contributing factors to the market's growth. Germany, holding a market share of around 28%, is a key player in the European market. The country has a robust healthcare system, with widespread use of medical radiation technologies in diagnostic imaging, radiotherapy, and nuclear medicine. Germany’s strong emphasis on technological innovation and research in healthcare further strengthens its position in the market. Government regulations and compliance with safety standards are critical drivers for the demand for radiation monitoring solutions, particularly in radiology and oncology departments.
France and Italy
France, with a market share of approximately 18%, is another prominent player in the European medical radiation detection market. The country’s increasing focus on patient safety and expanding healthcare services has fueled the demand for advanced radiation monitoring systems. Additionally, France’s ongoing investments in the healthcare sector, including diagnostic imaging and cancer treatment centers, contribute to the overall market growth. The French government’s stringent radiation safety regulations ensure that medical facilities adopt the latest monitoring technologies to meet compliance standards. Italy, contributing about 14% to the market, benefits from its growing healthcare infrastructure, particularly in major cities. The rise in medical imaging applications and the demand for precision in radiation therapy treatments support the need for enhanced detection and safety systems. Italy’s regulatory focus on radiation exposure reduction also drives the adoption of advanced monitoring solutions.
Spain and Russia
Spain holds a market share of around 9%, driven by the increasing demand for radiation safety devices in diagnostic imaging and nuclear medicine applications. The country's healthcare sector continues to modernize, with a focus on expanding access to advanced medical treatments, including cancer therapies. Spain’s regulatory framework for radiation safety ensures that healthcare providers invest in up-to-date radiation detection systems. Russia, contributing around 8% to the market, is seeing growing adoption of medical radiation technologies. The country’s healthcare system is evolving with advancements in radiology and oncology, resulting in an increased need for radiation safety solutions. Russian healthcare facilities are increasingly focusing on meeting international safety standards, which is fostering market growth for radiation detection and monitoring equipment.
Rest of Europe
The Rest of Europe, encompassing countries such as Belgium, Netherlands, Austria, Sweden, Poland, Denmark, Switzerland, and other regions, collectively account for about 16% of the European medical radiation detection market. The increasing healthcare investments in these countries, along with the rising demand for diagnostic imaging and radiation therapy services, are driving market growth. Countries like Switzerland and Sweden have well-established healthcare systems with high adoption rates of advanced medical technologies, contributing significantly to the market share in this segment. Moreover, the consistent efforts to improve radiation safety regulations and enhance healthcare infrastructure across the region further support the market’s expansion. The Rest of Europe segment highlights the regional diversity in healthcare adoption and the rising focus on patient safety in radiation-related medical procedures.
Key Player Analysis
- Mirion Technologies, Inc.
- IBA Dosimetry GmbH
- PTW Freiburg GmbH
- AmRay Medical
- Thermo Fisher Scientific Inc.
- Mirion Technologies, Inc.
- Sun Nuclear Corporation
- Fluke Biomedical
- Tracerco
- Landauer Nordic AB
- LabLogic Systems Ltd.
Competitive Analysis
The Europe medical radiation detection, monitoring, and safety market is highly competitive, with leading players offering advanced solutions to meet the growing demand for radiation safety. Key players include Mirion Technologies, IBA Dosimetry GmbH, PTW Freiburg GmbH, AmRay Medical, Thermo Fisher Scientific Inc., Sun Nuclear Corporation, Fluke Biomedical, Tracerco, Landauer Nordic AB, and LabLogic Systems Ltd. The key companies in the market are focusing on product innovation and technological advancements to meet the increasing demand for precise and efficient radiation detection systems. Many players are enhancing their portfolios by integrating cutting-edge technologies, such as artificial intelligence and portable detection systems, to improve the accuracy and convenience of monitoring radiation exposure. For instance, advancements in machine learning algorithms have significantly improved the accuracy of radiation detection systems, enabling better discrimination between different types of radiation. The market is also driven by players' emphasis on compliance with stringent European regulations and safety standards. This has led to increased investments in R&D and strategic partnerships to introduce solutions that offer real-time data collection, better mobility, and higher safety levels for both patients and healthcare professionals. Moreover, manufacturers are expanding their product offerings to include systems suitable for various applications such as diagnostic imaging, nuclear medicine, and radiation therapy. As competition intensifies, companies are looking to differentiate themselves by offering customized solutions, improving user experience, and expanding their market reach across multiple regions in Europe. Strategic acquisitions and collaborations are also playing a key role in enhancing market positioning.
Recent Developments
- In September 2024, Landauer released updates to its dosimetry account management platform, myLDR, including the Signature Suite for compliance documentation. This upgrade simplifies compliance workflows by enabling digital signatures, secure report archiving, and instant notifications for participants.
- In April 2024, Mirion Technologies launched the InstadoseVUE wireless dosimeter, a next-generation wearable radiation monitoring device. This product features advanced wireless, processing, and communication technologies, providing stable connectivity, faster dose communication, and increased battery life. It also includes an electronic display for on-screen device status and dose communication insights, aiming to redefine radiation safety in workplaces.
- In April 2024, Sun Nuclear Corporation announced the release of SunCHECK Version 5.0 software for comprehensive Quality Management in radiation therapy. The update introduced features such as plan feasibility evaluation, plan complexity metrics, and expanded device integration to optimize workflows and prioritize patient safety.
- In May 2023, IBA Dosimetry GmbH launched DOSE-X, a next-generation reference class electrometer, in April 2023. This innovation was showcased at the ESTRO 2023 conference in May 2023, highlighting its high-precision technology, remote access capabilities, and API-driven functionality, setting new standards in the Absolute Dosimetry market.
Market Concentration & Characteristics
The Europe medical radiation detection, monitoring, and safety market exhibits moderate concentration, with a few key players dominating the landscape while also allowing room for emerging companies to carve a niche. Leading companies hold substantial market shares due to their established brand presence, broad product portfolios, and ongoing investments in research and development. However, the market is characterized by intense competition, as smaller players and innovative startups introduce new, cost-effective solutions with specialized features like portability and real-time data integration. This dynamic environment fosters continuous innovation, driving advancements in radiation detection technologies. The market is highly regulated, with companies needing to comply with stringent European safety standards and certifications, which shapes the product offerings. Companies focus on creating solutions that balance advanced technology with ease of use, as healthcare facilities seek systems that are both reliable and efficient. The demand for integrated systems that combine various safety measures, such as radiation detection, monitoring, and protective equipment, is growing, reflecting the need for streamlined operations in healthcare settings. The increasing focus on patient safety and the growing prevalence of diagnostic imaging and radiotherapy applications are driving this concentration. Overall, the market’s characteristics reflect a blend of technological innovation, regulatory compliance, and a competitive landscape that is pushing companies to continually enhance product performance and user experience.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-user and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europe medical radiation detection, monitoring, and safety market is expected to experience steady growth, driven by advancements in medical imaging and radiation therapy.
- Increasing investments in healthcare infrastructure across Europe will fuel the demand for radiation safety solutions.
- The adoption of portable and wearable radiation detection devices is anticipated to rise, providing greater flexibility and real-time monitoring capabilities.
- The shift towards integrated radiation safety systems, combining detection, monitoring, and protective measures, will gain momentum.
- Rising awareness of radiation safety among healthcare professionals and patients will contribute to market expansion.
- Strict regulatory frameworks across Europe will continue to push healthcare facilities to adopt advanced radiation detection technologies.
- Emerging technologies, such as AI-powered radiation monitoring systems, are expected to play a key role in improving radiation dose management and safety.
- The demand for radiation safety solutions in nuclear medicine and diagnostic imaging will continue to grow, expanding market opportunities.
- Increased focus on cancer treatment and diagnostic procedures will drive further demand for radiation safety equipment.
- Companies will increasingly collaborate and innovate to deliver cost-effective, high-performance radiation detection solutions tailored to diverse healthcare applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Medical Radiation Detection, Monitoring & Safety Market?
What factors are driving the growth of the Europe Medical Radiation Detection, Monitoring & Safety Market?
What are the key segments within the Europe Medical Radiation Detection, Monitoring & Safety Market?
What are some challenges faced by the Europe Medical Radiation Detection, Monitoring & Safety Market?
Who are the major players in the Europe Medical Radiation Detection, Monitoring & Safety Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Medical Radiation Detection, Monitoring and Safety Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Medical Radiation Detection, Monitoring and Safety Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 884.69 million → 2032: USD 1,490.69 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Medical Radiation Detection, Monitoring and Safety Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Medical Radiation Detection, Monitoring and Safety Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Medical Radiation Detection, Monitoring and Safety Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Medical Radiation Detection, Monitoring and Safety Market Drivers
- 3.3 Europe Medical Radiation Detection, Monitoring and Safety Market Restraints & Challenges
- 3.4 Europe Medical Radiation Detection, Monitoring and Safety Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Medical Radiation Detection, Monitoring and Safety Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Medical Radiation Detection, Monitoring and Safety Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Medical Radiation Detection, Monitoring and Safety category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Medical Radiation Detection, Monitoring and Safety Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Medical Radiation Detection, Monitoring and Safety Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Medical Radiation Detection, Monitoring and Safety market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Medical Radiation Detection, Monitoring and Safety Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Medical Radiation Detection, Monitoring and Safety Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Medical Radiation Detection, Monitoring and Safety Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Medical Radiation Detection, Monitoring and Safety (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Medical Radiation Detection, Monitoring and Safety Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Medical Radiation Detection, Monitoring and Safety Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Medical Radiation Detection, Monitoring and Safety Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Medical Radiation Detection, Monitoring and Safety Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Medical Radiation Detection, Monitoring and Safety Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Medical Radiation Detection, Monitoring and Safety Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Medical Radiation Detection, Monitoring and Safety Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Medical Radiation Detection, Monitoring and Safety Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Medical Radiation Detection, Monitoring and Safety Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
