
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Modular Data Center Market Size 2024 | USD 9,019.25 million |
| Europe Modular Data Center Market, CAGR | 16.38% |
| Europe Modular Data Center Market Size 2032 | USD 33,056.71 million |
Market Overview
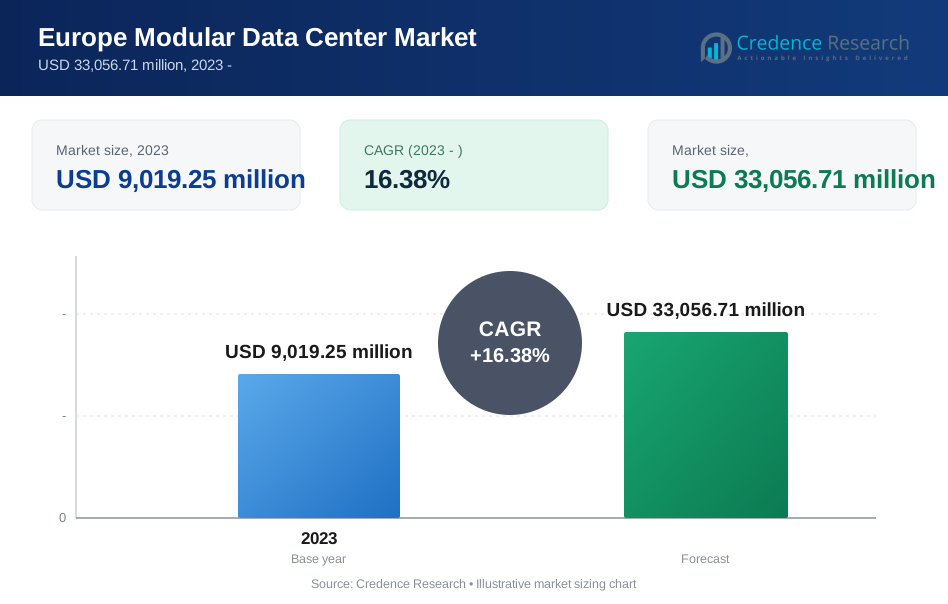
The Europe Modular Data Center Market is projected to grow from USD 9,019.25 million in 2023 to an estimated USD 33,056.71 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 16.38% from 2024 to 2032. This substantial market expansion is driven by increasing demand for scalable, energy-efficient, and cost-effective data center solutions across industries.
Key market drivers include the rising adoption of cloud services, edge computing, and the surge in data consumption, which necessitates the construction of new data centers. Additionally, the need for faster deployment and improved energy efficiency makes modular data centers a preferred choice over traditional options. Trends such as growing investments in digital transformation, advancements in 5G technology, and the increasing use of artificial intelligence are further fueling market growth in the region.
Geographically, the market is experiencing strong growth across key European countries, including the UK, Germany, France, and the Netherlands, due to high demand for advanced IT infrastructure. These countries are also seeing increased government initiatives to enhance data security and energy efficiency in data centers. Prominent players in the European modular data center market include Schneider Electric, Huawei Technologies, IBM Corporation, and Vertiv Group, who are focusing on innovative solutions to meet the dynamic needs of businesses and drive the sector forward.
Market Drivers
Growing Demand for Scalable and Flexible Data Infrastructure
One of the primary drivers of the Europe modular data center market is the growing need for scalable and flexible data infrastructure. Businesses across various sectors are experiencing unprecedented growth in data generation, driven by the rapid adoption of digital transformation, cloud computing, and big data analytics. Traditional data centers often require significant time and capital investment to build or expand, which poses challenges for companies needing to respond quickly to changing market demands or technological advancements. In contrast, modular data centers offer a scalable solution, enabling organizations to expand their IT capacity incrementally as needed.Modular data centers are pre-engineered and pre-fabricated units that can be quickly deployed or reconfigured to meet specific operational requirements. This flexibility is particularly attractive to industries such as telecommunications, healthcare, and financial services, where rapid expansion or changes in data processing capacity are often required. The modular approach reduces deployment times from years to just a few months, allowing businesses to maintain competitive advantage without the long delays associated with traditional infrastructure development. For instance, Equinix, a leading data center provider, deployed modular data centers in Frankfurt and Amsterdam to rapidly expand their capacity and meet growing demand for edge computing services. These modular units were operational within months, allowing Equinix to quickly respond to market needs and support the increasing data processing requirements of their customers in key European markets. Furthermore, the ability to tailor modular systems to current needs while leaving room for future expansion makes them a cost-effective and practical solution in the fast-evolving European business landscape.
Rise of Edge Computing and 5G Networks
The emergence of edge computing and the rollout of 5G networks are major catalysts for the growth of the modular data center market in Europe. Edge computing involves processing data closer to the source of generation, reducing latency and improving real-time data analysis. This paradigm shift is being driven by the increasing use of Internet of Things (IoT) devices, autonomous vehicles, and smart cities, which generate vast amounts of data requiring immediate processing at the edge of the network rather than in centralized data centers.Modular data centers are ideally suited for edge computing environments due to their compact size, portability, and ability to operate in diverse environments. These centers can be deployed closer to where data is generated, ensuring faster data processing and more efficient use of network resources. The roll-out of 5G networks is further accelerating the need for modular data centers, as 5G technology increases the speed and volume of data transmission, necessitating more localized data processing capabilities. With 5G infrastructure continuing to expand across Europe, industries such as telecommunications, manufacturing, and transportation are increasingly relying on modular data centers to support the low-latency requirements of edge computing applications.
Increasing Focus on Energy Efficiency and Sustainability
Energy efficiency and sustainability are critical concerns for businesses and governments across Europe, particularly as data centers have become significant consumers of energy. Modular data centers offer a more energy-efficient alternative to traditional data centers, as they are designed with optimized energy management systems, advanced cooling solutions, and the ability to integrate renewable energy sources. The growing focus on reducing carbon footprints and complying with environmental regulations is driving many European companies to adopt modular data center solutions.Governments in Europe are also introducing stringent regulations and incentives to promote energy-efficient infrastructure. The European Union’s focus on sustainability, exemplified by initiatives such as the European Green Deal, aims to make the region climate-neutral by 2050. Data center operators are under pressure to reduce energy consumption and increase the use of green energy. Modular data centers, with their energy-efficient designs and capacity to incorporate sustainable technologies, are an attractive solution to meet these regulatory demands. They also offer reduced operational costs by lowering energy usage, making them a financially viable option for companies looking to minimize long-term expenditures while adhering to environmental goals.
Rapid Deployment and Cost Savings
The ability to rapidly deploy modular data centers is a significant driver of their increasing adoption across Europe. As businesses face mounting pressure to scale their operations and remain agile in a fast-paced digital environment, the long lead times associated with traditional data center construction are often seen as a barrier to growth. Modular data centers can be pre-fabricated and assembled offsite, significantly reducing the time required for deployment. In some cases, modular data centers can be operational within a few weeks, enabling businesses to quickly respond to changing market conditions or technological needs.The cost savings associated with modular data centers are also a major driver of market growth. Traditional data centers require substantial upfront capital investment, which can strain the financial resources of companies, especially small and medium-sized enterprises (SMEs). In contrast, modular data centers allow for a pay-as-you-grow approach, enabling businesses to invest in additional capacity only as needed. This flexibility reduces the risk of over-investing in infrastructure that may not be fully utilized in the short term. Additionally, modular data centers can be easily relocated or reconfigured, providing further cost savings by extending the useful life of the infrastructure and allowing it to adapt to changing business needs.Moreover, modular data centers offer reduced operational costs due to their energy-efficient designs and lower maintenance requirements. By minimizing downtime and providing quicker returns on investment, they help businesses maintain a competitive edge in a market where speed and cost-efficiency are paramount. These advantages make modular data centers an attractive option for businesses looking to optimize their IT infrastructure while managing costs effectively.
Market Trends
Integration of Advanced Technologies
One of the most significant trends in the Europe modular data center market is the integration of advanced technologies such as artificial intelligence (AI), machine learning (ML), and the Internet of Things (IoT). These technologies enhance the operational efficiency and performance of modular data centers, enabling organizations to optimize resource allocation, energy consumption, and overall management. AI and ML algorithms can analyze vast amounts of operational data in real time, identifying patterns and anomalies that allow for predictive maintenance and proactive adjustments to cooling and power systems. This leads to improved energy efficiency and reduced operational costs.Moreover, the IoT plays a crucial role in the evolution of modular data centers by enabling seamless connectivity and communication between devices and systems. Smart sensors monitor environmental conditions, power usage, and equipment performance, providing critical insights for effective management. As organizations increasingly rely on data-driven decision-making, the demand for modular data centers equipped with these advanced technologies continues to grow. For instance, a recent study by Gartner predicts that by 2025, 75% of enterprise-generated data will be created and processed outside traditional centralized data centers, highlighting the growing importance of modular and edge data centers equipped with advanced technologies. This trend reflects the broader shift towards smart infrastructure, where interconnected systems enhance operational agility and resilience in an ever-evolving digital landscape.
Emphasis on Sustainability and Energy Efficiency
Another prominent trend is the increasing emphasis on sustainability and energy efficiency within the modular data center market. With growing awareness of climate change and environmental responsibility, businesses and governments are prioritizing eco-friendly practices and solutions. Modular data centers, designed with energy-efficient technologies and sustainable materials, are gaining traction as a viable option for organizations looking to reduce their carbon footprint.This trend is further supported by stringent regulations and initiatives across Europe aimed at promoting greener data center operations. The European Union's Green Deal and various national policies encourage the adoption of renewable energy sources, energy-efficient designs, and waste reduction strategies in data center construction and operation. For instance, a report by the European Commission estimates that data centers in Europe consume around 77 terawatt-hours (TWh) of electricity annually, emphasizing the need for more energy-efficient and sustainable solutions in the modular data center market.Companies are increasingly seeking modular data centers that can integrate renewable energy solutions, such as solar panels and wind turbines, to power their operations. Additionally, many modular designs incorporate advanced cooling technologies that significantly reduce energy consumption compared to traditional systems. For instance, a case study by Schneider Electric showcases a modular data center solution that achieved a Power Usage Effectiveness (PUE) of 1.2, indicating a high level of energy efficiency compared to the industry average of 1.8 to 2.0.By focusing on sustainability and energy efficiency, organizations not only comply with regulatory requirements but also achieve long-term cost savings and enhance their corporate social responsibility profiles. For instance, a survey conducted by the Uptime Institute revealed that over 80% of data center operators consider energy efficiency and sustainability as critical factors when making infrastructure decisions, reflecting the growing emphasis on eco-friendly practices in the modular data center market. As the market for modular data centers evolves, this trend will continue to shape investment decisions and influence design choices, driving the development of greener and more efficient data center solutions across Europe.For instance, the European Code of Conduct for Data Centre Energy Efficiency, a voluntary initiative launched by the European Commission, has seen a significant increase in participation, with over 300 data centers across Europe adopting best practices for energy efficiency and sustainability. This demonstrates the industry's commitment to addressing environmental concerns and improving overall operational efficiency in the modular data center market.
Market Restraints and Challenges
Regulatory and Compliance Issues
One of the primary challenges facing the Europe modular data center market is the complex landscape of regulatory and compliance requirements. Each European country has its own set of regulations governing data protection, environmental standards, and building codes, which can complicate the deployment of modular data centers. The General Data Protection Regulation (GDPR) is a notable example, imposing strict guidelines on data handling and privacy that organizations must adhere to when operating data centers. Failure to comply with these regulations can lead to significant fines and reputational damage.Additionally, the stringent environmental regulations aimed at reducing carbon emissions and promoting energy efficiency pose challenges for the construction and operation of modular data centers. Companies must navigate various approvals and certifications, which can prolong project timelines and increase costs. These regulatory hurdles may deter smaller organizations from investing in modular solutions, limiting market growth. To address these challenges, modular data center providers must remain vigilant in understanding and complying with evolving regulations across different jurisdictions, which can require significant resources and expertise.
High Initial Investment Costs
Despite their long-term cost benefits, the initial investment required for modular data centers can be a significant barrier for many businesses. While modular designs offer flexibility and scalability, the upfront costs associated with acquiring and deploying these systems can be daunting, particularly for small and medium-sized enterprises (SMEs) with limited budgets. The capital required for infrastructure, technology integration, and necessary certifications can strain financial resources and may lead some organizations to delay or forgo investments in modular data centers altogether.Moreover, organizations may face challenges in justifying these initial costs to stakeholders, particularly when the benefits of modular solutions are more apparent in the long term. The perception of high upfront costs can hinder the decision-making process and slow down adoption rates within the market. To overcome this challenge, modular data center providers must demonstrate the value proposition of their solutions, focusing on the total cost of ownership and potential savings achieved through improved energy efficiency and operational flexibility. By effectively communicating these benefits, providers can help mitigate concerns about initial investment costs and encourage broader adoption of modular data center solutions in Europe.
Market Segmentation Analysis
By Component
The Europe modular data center market is characterized by various components and services that cater to diverse organizational needs. Solutions include All-in-One Modules, which integrate essential IT, power, and cooling systems into a compact, easily deployable unit, making them ideal for organizations seeking quick setups. Individual Modules offer customization, allowing businesses to select specific IT, power, or cooling components for flexibility in meeting operational requirements. IT Modules encompass servers and storage systems that enable scalability in processing capabilities, while Power Modules focus on efficient energy supply and management, essential for reliable operations. Additionally, Cooling Modules are designed to maintain optimal temperatures, enhancing energy efficiency. The Services segment includes Design and Consulting for tailored solutions, Integration and Deployment support for seamless system integration, and Maintenance & Support to ensure the reliability and longevity of modular data center solutions.
By Organization Size
Both large enterprises and small to medium enterprises (SMEs) are increasingly adopting modular data centers, albeit for different reasons. Large corporations leverage their substantial budgets to invest in modular solutions that enhance operational efficiency and manage vast amounts of data effectively. In contrast, SMEs are turning to modular data centers due to their lower initial costs and inherent flexibility, allowing these smaller organizations to scale their IT infrastructure without the significant capital outlay required for traditional data center setups. This shift highlights the versatility and accessibility of modular solutions across varying organizational sizes.
Segments
Based on Component
- Solutions
- All-in-One Modules
- Individual Modules
- IT
- Power
- Cooling
- Services
- Design and Consulting
- Integration and Deployment
- Maintenance and Support
Based on Organization Size
- Large Enterprises
- Small & Medium Enterprises (SMEs)
Based on Industry Vertical
- Banking, Financial Services, and Insurance (BFSI)
- IT & Telecom
- Government & Defense
- Healthcare
- Others
Based on Region
- Western Europe
- Northern Europe
- Southern Europe
- Eastern Europe
Regional Analysis
Western Europe (40%)
Western Europe holds the largest share of the modular data center market, accounting for approximately 40% of the total market. Countries like Germany, the United Kingdom, and France are at the forefront of adopting modular solutions, driven by a strong demand for advanced IT infrastructure, particularly in sectors such as banking, finance, and telecommunications. The region's emphasis on energy efficiency and sustainability, supported by stringent regulatory frameworks like the European Green Deal, further accelerates the adoption of modular data centers. Additionally, major tech hubs in cities like London and Berlin foster innovation and investment in modular technologies.
Northern Europe (25%)
Northern Europe contributes around 25% to the market share, with countries such as Sweden, Finland, and Denmark leading in modular data center adoption. The region benefits from its favorable climate, which aids in energy-efficient cooling solutions, making modular data centers more viable. Moreover, governments in these countries actively promote green energy initiatives, encouraging the integration of renewable energy sources in data center operations. The robust digital infrastructure and high internet penetration in Northern Europe further drive demand for scalable and flexible data solutions.
Key players
- Dell Inc.
- Vertiv Group Corp.
- Eaton
- Schneider Electric
- Baselayer Technology, LLC
- Rittal GmbH & Co. KG
- Cannon Technologies Ltd.
- PCX Holding LLC
- IBM
- HPE Company
- Diversitec, Inc.
- Iron Mountain Corporation
- Rahi Systems
- Stulz GmbH
- Instant Data Centers LLC
- Colt Group SA
- Bladeroom Group Ltd.
- ZTE Corporation
Competitive Analysis
The Europe modular data center market is highly competitive, with key players leveraging their technological expertise and innovative solutions to gain market share. Dell Inc. and IBM lead with comprehensive product portfolios that include robust IT solutions and integrated modular systems, catering to large enterprises' diverse needs. Vertiv Group Corp. and Schneider Electric emphasize energy efficiency and sustainability, aligning with regional regulatory demands. Eaton and Rittal GmbH focus on modular designs that enhance scalability, appealing to SMEs and large corporations. Meanwhile, newer entrants like Baselayer Technology and Instant Data Centers LLC are carving niches through specialized offerings that target specific industry needs. Overall, the competitive landscape is characterized by ongoing technological advancements, strategic partnerships, and a strong focus on meeting customer demands for flexibility and efficiency.
Recent Developments
- In February 2023, Vertiv introduced the Vertiv MegaMod and Vertiv MegaMod Plus, a turnkey prefabricated modular (PFM) data centre solution for the EMEA market. These solutions are deployable in expandable units of 0.5 or 1 megawatts for IT loads up to 2 megawatts or more.
- In October 2024, Eaton launched its new SmartRack modular data center solution. This offering combines racks, cooling, and service enclosures to withstand up to 150kW of equipment load, designed to meet the growing demand for edge computing, machine learning, and AI applications.
- In April 2024, Bladeroom was recognized as one of Europe's fastest-growing companies by the Financial Times, highlighting their success in the modular data center market. They continue to promote their sustainable data center solutions, emphasizing energy efficiency and environmental responsibility.
- In September 2023, Schneider Electric expanded its modular data center portfolio with the launch of the EcoStruxure Modular Data Center All-In-One Solution for the European market. This solution is designed to address the growing demand for edge computing and rapid deployment of IT infrastructure.
- In June 2024, Rittal introduced its new RiMatrix Next Generation (NG) modular data center platform in Europe. This platform offers enhanced flexibility and scalability for various data center applications, from edge to core deployments.
- In March 2024, IBM announced a partnership with a European telecom provider to deliver modular edge data centers across multiple countries in Europe, leveraging IBM's expertise in hybrid cloud and AI technologies.
- In November 2023, HPE expanded its GreenLake edge-to-cloud platform with new modular data center offerings for the European market, focusing on sustainability and energy efficiency.
Market Concentration and Characteristics
The Europe modular data center market exhibits moderate to high concentration, characterized by a mix of established multinational corporations and emerging players. Major companies like Dell Inc., IBM, Schneider Electric, and Vertiv Group Corp. dominate the market, leveraging their extensive resources, technological expertise, and broad product portfolios to maintain a competitive edge. These leaders focus on innovation, sustainability, and energy efficiency, aligning with the growing demand for environmentally friendly data solutions. Additionally, the presence of specialized firms like Baselayer Technology and Instant Data Centers LLC reflects a trend towards niche offerings tailored to specific industry needs, enhancing market diversity. The competitive landscape is further shaped by strategic partnerships and collaborations, enabling companies to expand their reach and enhance service offerings. Overall, the market is characterized by dynamic growth driven by technological advancements, evolving customer requirements, and regulatory influences focused on energy efficiency and sustainability.
Report Coverage
The research report offers an in-depth analysis based on Component, Organisation Size, Industry Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europe modular data center market is expected to experience robust growth, projected to expand significantly due to increasing data demands and digital transformation initiatives across various sectors.
- As businesses prioritize agility and scalability, modular solutions will become increasingly popular, allowing organizations to expand their data center capacity seamlessly and cost-effectively.
- Growing environmental awareness will drive the demand for energy-efficient modular data centers, as companies aim to reduce their carbon footprints and comply with stringent regulations.
- Continuous advancements in technologies such as AI, IoT, and 5G will enhance the functionality and efficiency of modular data centers, enabling faster processing and improved resource management.
- The rise of edge computing will significantly influence the modular data center landscape, as organizations seek localized data processing solutions to meet the low-latency demands of emerging applications.
- The increasing emphasis on sustainability will lead to greater integration of renewable energy sources in modular data center operations, further reducing energy costs and environmental impact.
- Future modular solutions will emphasize customization and flexibility, allowing organizations to tailor their data center environments to specific operational needs and industry requirements.
- Continued investments from both public and private sectors in digital infrastructure will bolster the modular data center market, supporting innovation and expanding market opportunities.
- As regulations around data security and environmental sustainability evolve, modular data centers will play a crucial role in helping organizations maintain compliance while optimizing their operations.
- The market will likely see the emergence of new entrants offering innovative solutions, contributing to increased competition and driving technological advancements within the modular data center sector.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Scalable and Flexible Data Infrastructure
European organizations are generating increasing volumes of data due to digital transformation, cloud adoption, and big data analytics. Modular data centers allow these organizations to scale IT capacity quickly and cost-effectively, supporting rapid business growth and technological change.
Rise of Edge Computing and 5G Networks
The proliferation of IoT devices, smart cities, and 5G rollouts is driving the need for localized, low-latency data processing. Modular data centers are ideally suited for edge deployments, enabling faster data processing and supporting new digital services across Europe.
Increasing Focus on Energy Efficiency and Sustainability
With stringent EU regulations and corporate sustainability goals, European businesses are prioritizing energy-efficient and environmentally friendly data center solutions. Modular data centers are designed for optimized energy management and can integrate renewable energy sources, helping organizations reduce operational costs and carbon footprints.
Rapid Deployment and Cost Savings
Modular data centers can be prefabricated and deployed in a fraction of the time required for traditional builds, allowing businesses to respond quickly to market opportunities or regulatory changes. Their pay-as-you-grow model and lower upfront costs make them attractive to both large enterprises and SMEs.
Integration of Advanced Technologies
The adoption of AI, IoT, and advanced monitoring systems in modular data centers enhances operational efficiency, predictive maintenance, and resource optimization. These technological advancements are making modular solutions more attractive for organizations seeking intelligent, future-ready infrastructure.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Europe Modular Data Center Market in 2023?
What is the estimated market size in 2032?
What is the CAGR for the Europe Modular Data Center Market?
What are the key drivers for the growth of the modular data center market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 All-in-One Modules
- 1.2.2 Individual Modules
- 1.2.3 IT Modules
- 1.2.4 Power Modules
- 1.2.5 Cooling Modules
- 1.2.6 Design and Consulting Services
- 1.2.7 Integration and Deployment Services
- 1.2.8 Maintenance and Support Services
- 1.3 By Industry Vertical
- 1.3.1 Banking, Financial Services, and Insurance (BFSI)
- 1.3.2 IT & Telecom
- 1.3.3 Government & Defense
- 1.3.4 Healthcare
- 1.3.5 Others
- 1.4 By Organization Size
- 1.4.1 Large Enterprises
- 1.4.2 Small & Medium Enterprises (SMEs)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 9,019.25 million → 2032: USD 33,056.71 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Modular Data Center Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Modular Data Center Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Modular Data Center Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Modular Data Center Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Modular Data Center Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Modular Data Center Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Modular Data Center Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Modular Data Center Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 9,019.25 million → 2032: USD 33,056.71 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Modular Data Center Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 All-in-One Modules
- 12.3.7.2 Individual Modules
- 12.3.7.3 IT Modules
- 12.3.7.4 Power Modules
- 12.3.7.5 Cooling Modules
- 12.3.7.6 Design and Consulting Services
- 12.3.7.7 Integration and Deployment Services
- 12.3.7.8 Maintenance and Support Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Industry Vertical - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Banking, Financial Services, and Insurance (BFSI)
- 12.4.7.2 IT & Telecom
- 12.4.7.3 Government & Defense
- 12.4.7.4 Healthcare
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Organization Size - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Large Enterprises
- 12.5.7.2 Small & Medium Enterprises (SMEs)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Modular Data Center End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Modular Data Center Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Modular Data Center Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Modular Data Center Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Schneider Electric
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Vertiv Group Corp.
- 18.4 IBM Corporation
- 18.5 Dell Inc.
- 18.6 Eaton
- 18.7 Rittal GmbH & Co. KG
- 18.8 HPE Company
- 18.9 Bladeroom Group Ltd.
- 18.10 Baselayer Technology, LLC
- 18.11 ZTE Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

