
Market Overview
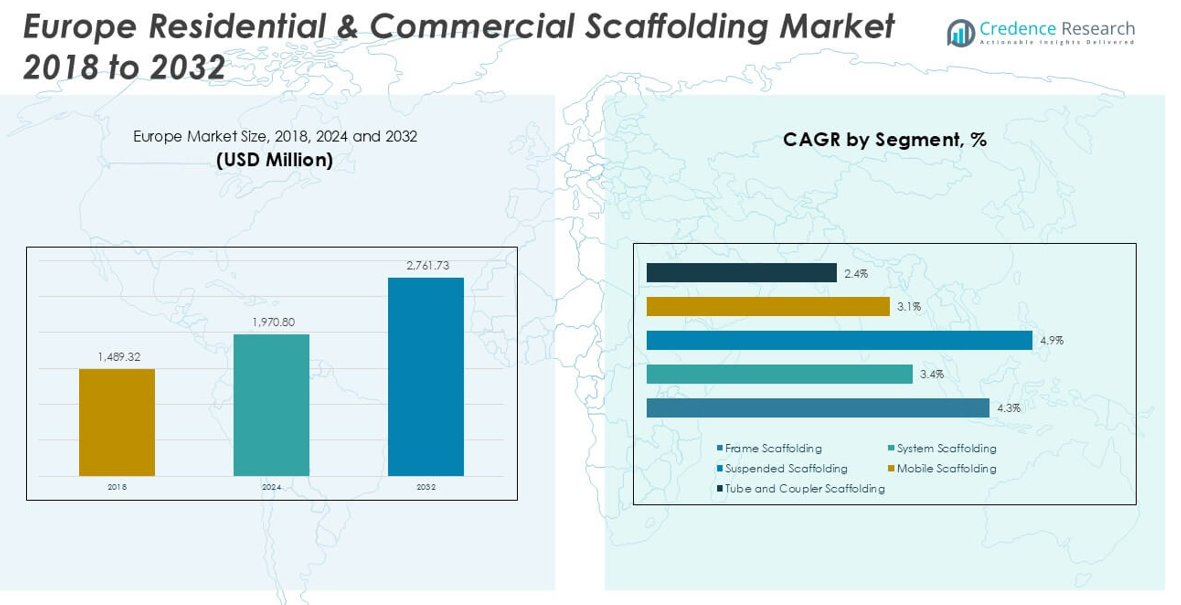
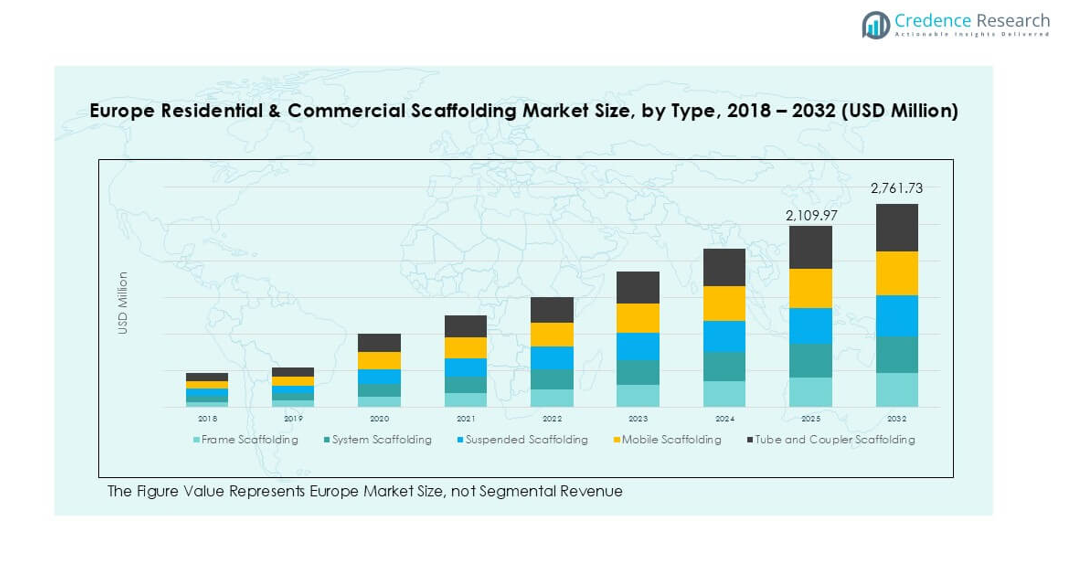
The Europe Residential & Commercial Scaffolding market size was valued at USD 1,489.32 million in 2018, increased to USD 1,970.80 million in 2024, and is anticipated to reach USD 2,761.73 million by 2032, at a CAGR of 3.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Residential & Commercial Scaffolding Market Size 2024 | USD 1,970.80 million |
| Europe Residential & Commercial Scaffolding Market, CAGR | 3.9% |
| Europe Residential & Commercial Scaffolding Market Size 2032 | USD 2,761.73 million |
The Europe Residential & Commercial Scaffolding market is led by key players such as Wilhelm Layher, Altrad Group, ULMA Corporation, and ADTO Industrial Group, who dominate through extensive product portfolios, advanced safety systems, and robust rental networks. These companies maintain a competitive edge by offering modular, lightweight, and compliant scaffolding solutions tailored to both residential and commercial applications. Other notable contributors include Brand Industrial Services, Inc., MJ-Gerüst GmbH, and Aluminium Scaffold Towers Limited, focusing on regional and specialized services. Germany stands as the leading region, commanding approximately 25% of the market share in 2024, driven by strong construction activity, regulatory compliance, and technological advancements in scaffolding systems.
Market Insights
- The Europe Residential & Commercial Scaffolding market was valued at USD 1,970.80 million in 2024 and is projected to reach USD 2,761.73 million by 2032, growing at a CAGR of 3.9% during the forecast period.
- Market growth is primarily driven by increasing urban infrastructure projects, stringent worker safety regulations, and rising demand for renovation across aging European buildings.
- A notable trend includes the growing adoption of modular and prefabricated scaffolding systems, along with digital integration such as Building Information Modeling (BIM) to streamline project planning.
- The competitive landscape is dominated by players like Wilhelm Layher, Altrad Group, ULMA Corporation, and ADTO Industrial Group, who are focusing on innovation, rental service expansion, and compliance with EU safety standards.
- Germany leads the regional market with a 25% share, followed by the UK (21%) and France (17%), while frame scaffolding and steel scaffolding are the leading segments by type and material respectively.
Market Segmentation Analysis:
By Type
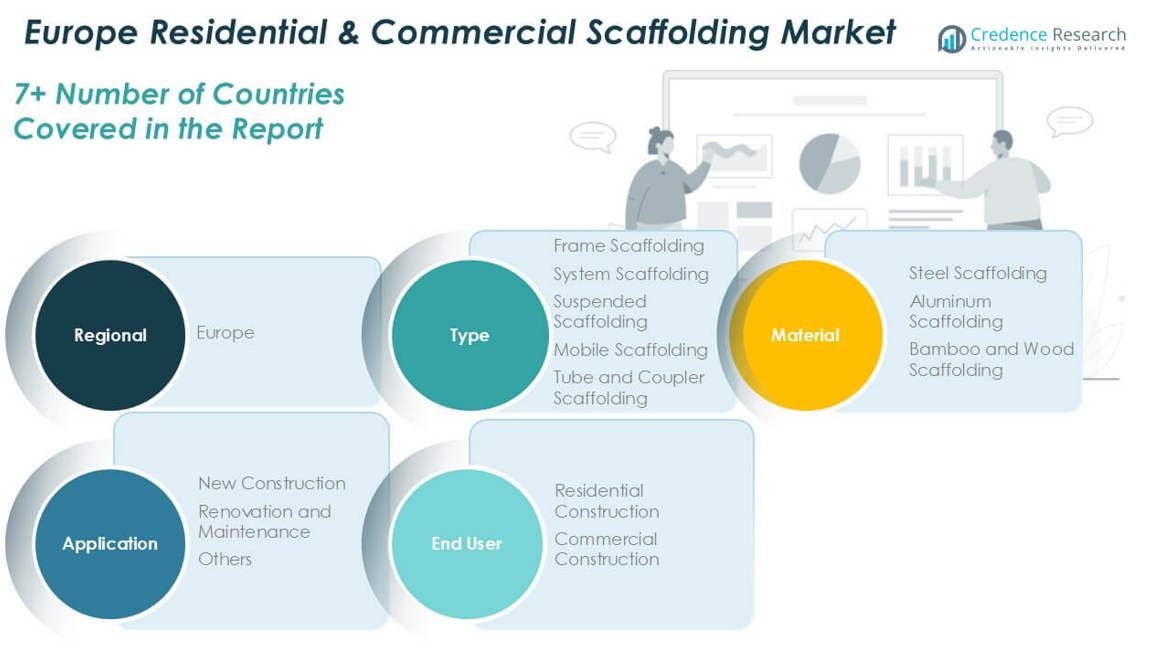
In the Europe Residential & Commercial Scaffolding market, frame scaffolding emerged as the dominant sub-segment, accounting for the largest market share in 2024. This type is widely used due to its ease of assembly, cost-effectiveness, and suitability for both residential and commercial construction. The growing number of mid-rise and high-rise building projects across Europe has further driven demand for frame scaffolding. System scaffolding also holds a significant share, supported by increasing adoption in complex architectural designs. Meanwhile, mobile and suspended scaffolding are gaining traction in maintenance and renovation tasks, especially in urban settings.
- For instance, Wilhelm Layher produces over 15,000 tons of frame and system scaffolding annually at its Güglingen-Eibensbach plant in Germany, supporting high-volume demand across Europe.
By Material
Steel scaffolding led the market by material type, holding the highest revenue share in 2024, owing to its superior strength, durability, and load-bearing capacity. It is highly preferred in large-scale commercial projects and high-rise constructions where safety and structural integrity are critical. Aluminum scaffolding follows as a growing segment, primarily driven by its lightweight nature and ease of transport, making it ideal for smaller residential projects and temporary works. Bamboo and wood scaffolding, although declining in popularity, still see limited use in traditional or low-cost construction areas, especially in Eastern Europe.
- For instance, Altrad Group operates multiple steel fabrication sites in Europe with a combined production output of over 20,000 metric tons annually, significantly contributing to the supply of steel scaffolding components.
By Application
The new construction segment dominated the market in terms of application, representing the largest share in 2024. The steady growth in residential housing developments and commercial infrastructure projects across Europe, particularly in countries like Germany, France, and the UK, has significantly contributed to this trend. Urban expansion, rising investments in public infrastructure, and government initiatives aimed at housing development have further bolstered this segment. Renovation and maintenance also constitute a considerable share, supported by increasing refurbishment activities in aging urban structures. The "Others" category includes niche applications, such as event setups and temporary access platforms.
Market Overview
Surge in Urban Infrastructure Development
The rising demand for urban infrastructure across Europe is a key growth driver for the residential and commercial scaffolding market. Rapid urbanization and increasing investments in high-rise buildings, commercial centers, and transport infrastructure are propelling scaffolding needs. Governments across major economies like Germany, France, and the UK are prioritizing infrastructure modernization and urban renewal projects, leading to increased construction activity. This surge necessitates scalable, safe, and efficient scaffolding systems to support construction timelines, thereby contributing significantly to market expansion.
- For instance, ULMA Construction provided over 250,000 square meters of scaffolding systems for a multi-year metro expansion project in Paris (Grand Paris Express), enabling complex multi-level access and support structures.
Stringent Worker Safety Regulations
Growing enforcement of workplace safety regulations in Europe has intensified the demand for high-quality scaffolding systems. Regulatory bodies such as the European Agency for Safety and Health at Work (EU-OSHA) mandate secure access platforms and fall protection measures during construction. As a result, construction companies are increasingly investing in compliant scaffolding solutions, especially in commercial and public infrastructure projects. This regulatory push is encouraging the adoption of modern scaffolding types like system scaffolding and mobile platforms, thereby driving market growth.
- For instance, MJ-Gerüst GmbH integrated advanced fall protection features in over 30,000 square meters of system scaffolding deployed in public infrastructure projects across Germany in 2023.
Increase in Renovation and Retrofitting Projects
Europe’s aging building stock is prompting a rise in renovation and retrofitting projects, particularly in urban centers. With many structures requiring upgrades for energy efficiency, safety, or aesthetic reasons, scaffolding is essential to provide safe access for workers and equipment. This is especially true in historical cities where preservation of older buildings is a priority. The increased focus on sustainability and green building practices further amplifies the need for temporary access systems, reinforcing scaffolding demand in the renovation segment.
Key Trends & Opportunities
Adoption of Modular and Prefabricated Scaffolding Systems
A growing trend in the Europe scaffolding market is the shift towards modular and prefabricated systems that offer improved flexibility, faster installation, and enhanced safety. These systems reduce labor intensity and downtime on construction sites, aligning with the increasing demand for time-efficient project delivery. Manufacturers are also introducing advanced modular scaffolds with interchangeable components and lighter materials, opening new opportunities in both residential and commercial sectors. This trend supports cost-efficiency while meeting evolving architectural and regulatory requirements.
- For instance, ADTO Industrial Group exported more than 12,000 modular scaffold units to European partners in 2024, helping reduce average assembly time on mid-scale construction sites by up to 40 hours per project.
Digital Integration and Smart Construction Practices
The integration of digital technologies in construction is creating new opportunities for scaffolding providers. Building Information Modeling (BIM), project tracking software, and digital safety compliance tools are transforming the way scaffolding is planned and managed. Contractors are increasingly seeking digitally integrated scaffolding solutions to improve site coordination, reduce errors, and optimize material use. This tech-driven transformation presents a promising opportunity for players offering innovative, data-enabled scaffolding products and services across the European market.
- For instance, Brand Industrial Services, Inc. implemented BIM-enabled planning tools across 120 construction projects in the UK and France during 2024, improving scaffolding layout efficiency by 25% and reducing material wastage by 18 tons across sites.
Key Challenges
Fluctuating Raw Material Prices
The Europe scaffolding market faces significant challenges due to volatility in raw material prices, particularly steel and aluminum. These fluctuations directly impact production costs and profit margins for manufacturers and rental companies. Unpredictable supply chain dynamics, influenced by global trade tensions or energy price changes, further exacerbate the issue. Companies are compelled to either absorb the cost or pass it on to customers, which may affect project budgets and lead to delays or cancellations in some cases.
Labor Shortages and Skilled Workforce Constraints
A persistent shortage of skilled labor in the construction sector is posing challenges to scaffolding operations. The assembly, disassembly, and inspection of scaffolding require trained professionals to ensure safety and efficiency. However, the aging workforce and limited influx of new skilled workers are straining project timelines and increasing labor costs. This gap in technical proficiency not only affects the quality of scaffolding installation but also raises safety risks, potentially hindering market growth.
Complex Regulatory Compliance Across Regions
Navigating the diverse regulatory frameworks across different European countries presents a compliance challenge for scaffolding manufacturers and service providers. While safety standards are generally high, variations in national building codes, certification processes, and equipment specifications create operational complexities. Companies operating in multiple countries must invest in extensive testing and documentation to meet localized requirements, slowing down market entry and expansion efforts. This fragmented regulatory landscape can deter new entrants and complicate cross-border projects.
Regional Analysis
United Kingdom
The United Kingdom holds a significant share in the Europe Residential & Commercial Scaffolding market, accounting for approximately 21% of the regional market in 2024. The country’s active residential housing programs and substantial investments in commercial infrastructure, such as office buildings and transport projects, are key growth drivers. London and other major cities are experiencing a surge in high-rise and mixed-use developments, boosting demand for safe and efficient scaffolding systems. Additionally, government regulations emphasizing worker safety have increased the adoption of system and frame scaffolding across both residential and commercial construction sectors.
France
France represents around 17% of the Europe Residential & Commercial Scaffolding market, supported by robust construction activity in both residential and commercial segments. Major urban development projects in Paris, Lyon, and Marseille, combined with energy-efficient building renovation initiatives, have accelerated scaffolding demand. The country also benefits from favorable government policies aimed at infrastructure modernization. The rising trend of restoring historic buildings and the promotion of sustainable construction practices have further reinforced the use of modern scaffolding technologies, particularly aluminum and modular systems that offer better adaptability and safety.
Germany
Germany dominates the European scaffolding market with a leading share of 24% in 2024. The country’s strong construction industry, driven by large-scale residential housing demand and continuous commercial infrastructure upgrades, contributes to its market leadership. Key metropolitan areas like Berlin, Munich, and Frankfurt are witnessing increased activity in high-rise and industrial construction, requiring advanced scaffolding systems. Additionally, Germany’s strict occupational safety regulations promote the adoption of high-quality scaffolding materials and modular configurations. Investments in smart cities and green building practices also support long-term growth in the German scaffolding sector.
Italy
Italy holds a moderate share of approximately 11% in the regional scaffolding market. The country’s market is primarily driven by renovation and restoration projects, especially in heritage-rich cities such as Rome, Florence, and Venice. The government’s tax incentives for building retrofits and seismic upgrades have supported consistent demand for scaffolding services. While new residential construction has shown modest growth, the extensive maintenance and refurbishment work in older urban areas ensure steady market activity. The adoption of lightweight and adaptable scaffolding systems, such as mobile and aluminum variants, is gradually increasing across Italian sites.
Spain
Spain accounts for around 9% of the Europe Residential & Commercial Scaffolding market. The market is experiencing recovery and growth, driven by new housing projects and rising commercial real estate investments. Regions like Madrid and Barcelona are central to this growth, where both public and private construction activity is gaining momentum. Additionally, the country’s focus on tourism infrastructure and urban regeneration initiatives supports scaffolding demand. Increased safety compliance and the growing use of prefabricated scaffolding components are contributing to enhanced productivity and wider adoption of modern systems in construction projects.
Russia
Russia contributes approximately 8% to the European scaffolding market, with growth largely supported by government-led infrastructure development and industrial construction projects. Despite economic challenges and geopolitical tensions, the construction sector remains active, particularly in urban centers such as Moscow and St. Petersburg. However, regulatory complexities and price fluctuations in raw materials affect market dynamics. Steel scaffolding remains dominant due to its durability and wide applicability, while modernization efforts in commercial sectors are gradually opening up opportunities for more efficient and lightweight scaffolding systems.
Rest of Europe
The Rest of Europe region collectively holds about 10% of the market share, encompassing countries such as the Netherlands, Poland, Sweden, and Belgium. These markets are characterized by growing construction output, urban renewal programs, and infrastructure modernization. Countries like Poland and the Czech Republic are seeing increased investments in residential and commercial building projects, while Northern European nations are leading in sustainable and energy-efficient construction practices. The demand for modular scaffolding systems and aluminum-based solutions is rising due to their environmental compatibility and compliance with evolving European construction standards.
Market Segmentations:
By Type
- Frame Scaffolding
- System Scaffolding
- Suspended Scaffolding
- Mobile Scaffolding
- Tube and Coupler Scaffolding
By Material
- Steel Scaffolding
- Aluminum Scaffolding
- Bamboo and Wood Scaffolding
By Application
- New Construction
- Renovation and Maintenance
- Others
By End User
- Residential Construction
- Commercial Construction
By Geography
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Competitive Landscape
The Europe Residential & Commercial Scaffolding market is characterized by the presence of several established players and regional manufacturers competing on the basis of product quality, safety standards, service offerings, and pricing. Key players such as Wilhelm Layher, Altrad Group, ULMA Corporation, and ADTO Industrial Group dominate the market through extensive product portfolios, strong distribution networks, and long-standing industry expertise. Companies are increasingly focusing on product innovation, lightweight materials, and modular scaffolding systems to meet evolving construction demands and stringent regulatory requirements. Strategic alliances, mergers, and acquisitions are being adopted to expand geographic reach and enhance service capabilities. Additionally, rental services are gaining traction, prompting companies to diversify their business models. The market also sees participation from specialized firms like Aluminium Scaffold Towers Limited and Euroscaffold Nederland, which cater to niche segments and smaller-scale projects. Overall, the competitive landscape is dynamic, with a strong emphasis on safety compliance, technological integration, and sustainable scaffolding solutions.
Key Player Analysis
- ADTO Industrial Group
- Altrad Group
- ULMA Corporation
- Aluminium Scaffold Towers Limited
- Euroscaffold Nederland
- MJ-Gerüst GmbH
- Waco Scaffolding and Equipment Company
- Brand Industrial Services, Inc.
- Wilhelm Layher
- GBM
Recent Developments
- In July 2025, ULMA Construction highlighted their "Smart Construction Technology" for ambitious residential projects, specifically mentioning the Symphony Village project in Rome. This technology likely involves innovative formwork systems and other solutions to enhance efficiency and quality in large-scale residential developments. The Symphony Village project, located near Rome, is a large-scale residential complex comprising 470 living units across multiple buildings.
- In June 2025, Altrad completed a €1.25 billion bond issue to support growth and optimize capital structure, signifying robust financial health and the ability to invest in industrial and construction scaffolding services.
- In April 2025, Brand Industrial Services is expected to maintain its strong position in the U.S. scaffolding contractors market, driven by sustained demand across various construction sectors. This includes commercial, infrastructure, and some residential applications. The construction industry in the U.S. is projected to experience continued growth, further contributing to the demand for scaffolding services.
Market Concentration & Characteristics
The Europe Residential & Commercial Scaffolding Market exhibits a moderately concentrated structure, with a mix of large multinational firms and regional players. Major companies such as Wilhelm Layher, Altrad Group, ULMA Corporation, and ADTO Industrial Group hold significant market shares due to their extensive product portfolios, advanced manufacturing capabilities, and strong distribution networks. It reflects characteristics of a mature market, driven by regulatory compliance, demand for safety, and growing infrastructure investments. The presence of well-established rental service models contributes to recurring revenue and customer retention. Technological advancements, including modular scaffolding systems and digital integration, support competitive differentiation. The market sees stable demand from both residential and commercial segments, with increased activity in renovation projects and urban development. While barriers to entry are moderate, compliance with strict safety and quality standards limits rapid new entrant growth. It operates in a framework shaped by EU safety directives and national building codes, reinforcing the need for standardized, high-performance scaffolding solutions.
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Europe residential and commercial scaffolding market is expected to grow steadily, driven by ongoing urban infrastructure development.
- Increasing renovation and retrofitting projects across aging European buildings will continue to boost scaffolding demand.
- Modular and prefabricated scaffolding systems will gain popularity due to their efficiency, safety, and ease of installation.
- The market will witness rising demand for aluminum scaffolding, particularly in residential and light commercial applications.
- Digital tools such as Building Information Modeling (BIM) will become more integrated into scaffolding planning and project management.
- Rental-based scaffolding services will expand as contractors seek cost-effective and flexible access solutions.
- Regulatory compliance and worker safety requirements will drive the adoption of high-quality, certified scaffolding systems.
- Cross-border infrastructure investments and EU-backed projects will create new opportunities for market expansion.
- Skilled labor shortages may lead to increased demand for user-friendly, easy-to-assemble scaffolding designs.
- Manufacturers will focus on sustainability by developing lightweight, reusable, and recyclable scaffolding materials.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Urban Infrastructure Development
Rapid urbanization and increased investments in high-rise buildings, commercial centers, and transport infrastructure across Europe are driving demand for scalable and efficient scaffolding systems to support construction timelines.
Stringent Worker Safety Regulations
Enforcement of strict workplace safety standards by European regulatory bodies is compelling construction firms to invest in high-quality, compliant scaffolding solutions, especially for commercial and public infrastructure projects.
Growth in Renovation and Retrofitting Projects
Europe’s aging building stock and the need for energy-efficient upgrades are fueling a rise in renovation and retrofitting activities, which require safe and adaptable scaffolding systems for access and worker safety.
Adoption of Modular and Prefabricated Systems
The shift towards modular and prefabricated scaffolding systems is improving installation speed, flexibility, and safety, aligning with the market’s demand for time- and cost-efficient project delivery.
Digital Integration in Construction
The integration of digital tools such as Building Information Modeling (BIM) and project management software is streamlining scaffolding planning and execution, reducing errors and optimizing material usage, thus supporting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Residential & Commercial Scaffolding, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Residential & Commercial Scaffolding market projected to grow between 2025 and 2032?
Who are the leading companies in the Europe Residential & Commercial Scaffolding market?
Which region commanded the largest share of the Europe Residential & Commercial Scaffolding market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Frame Scaffolding
- 1.2.2 System Scaffolding
- 1.2.3 Suspended Scaffolding
- 1.2.4 Mobile Scaffolding
- 1.2.5 Tube and Coupler Scaffolding
- 1.3 By End User
- 1.3.1 Residential Construction
- 1.3.2 Commercial Construction
- 1.4 By Material
- 1.4.1 Steel Scaffolding
- 1.4.2 Aluminum Scaffolding
- 1.4.3 Bamboo and Wood Scaffolding
- 1.5 By Application
- 1.5.1 New Construction
- 1.5.2 Renovation and Maintenance
- 1.5.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,970.80 million → 2032: USD 2,761.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Europe Residential & Commercial Scaffolding Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Europe Residential & Commercial Scaffolding Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Europe Residential & Commercial Scaffolding Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Europe Residential & Commercial Scaffolding Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Europe Residential & Commercial Scaffolding Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Europe Residential & Commercial Scaffolding Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Europe Residential & Commercial Scaffolding Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Europe Residential & Commercial Scaffolding Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,970.80 million → 2032: USD 2,761.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Europe Residential & Commercial Scaffolding Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Frame Scaffolding
- 12.3.7.2 System Scaffolding
- 12.3.7.3 Suspended Scaffolding
- 12.3.7.4 Mobile Scaffolding
- 12.3.7.5 Tube and Coupler Scaffolding
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential Construction
- 12.4.7.2 Commercial Construction
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Steel Scaffolding
- 12.5.7.2 Aluminum Scaffolding
- 12.5.7.3 Bamboo and Wood Scaffolding
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 New Construction
- 12.6.7.2 Renovation and Maintenance
- 12.6.7.3 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Europe Residential & Commercial Scaffolding End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Europe Residential & Commercial Scaffolding Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Europe Residential & Commercial Scaffolding Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Europe Residential & Commercial Scaffolding Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Wilhelm Layher
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Altrad Group
- 18.4 ULMA Corporation
- 18.5 ADTO Industrial Group
- 18.6 Brand Industrial Services, Inc.
- 18.7 MJ-Gerüst GmbH
- 18.8 Aluminium Scaffold Towers Limited
- 18.9 Euroscaffold Nederland
- 18.10 Waco Scaffolding and Equipment Company
- 18.11 GBM
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

