
Market Overview
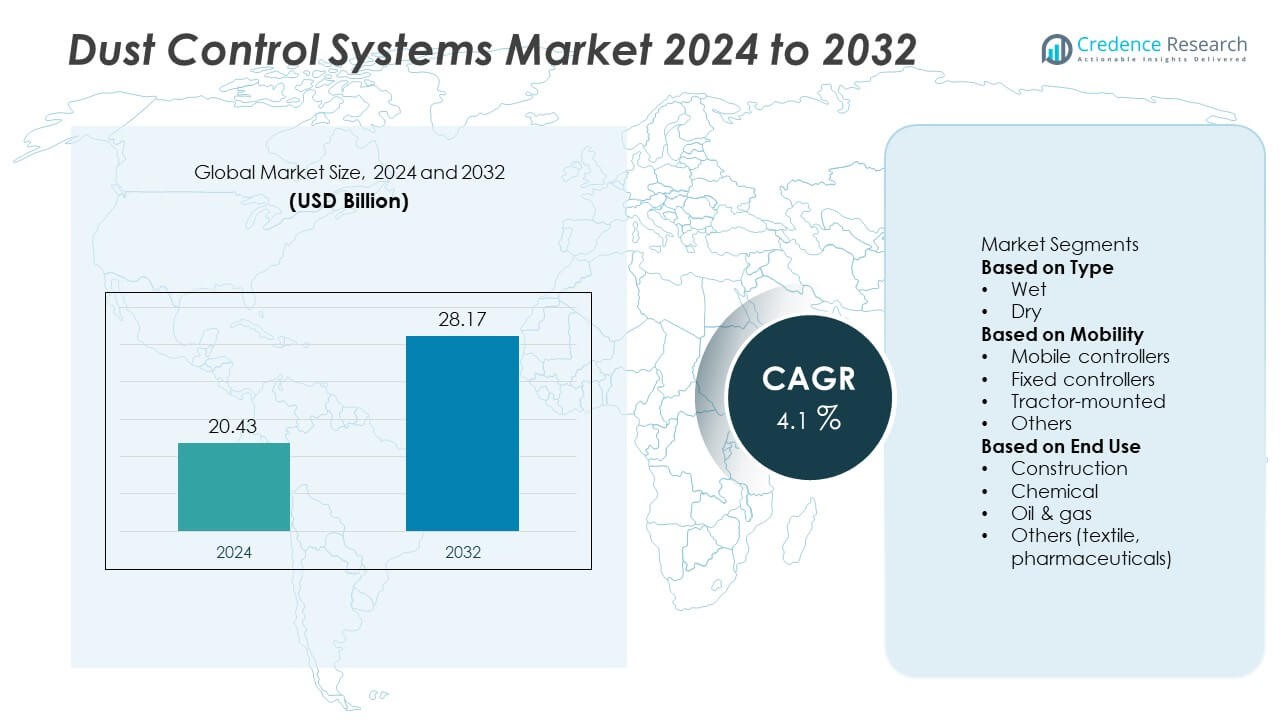
The global dust control systems market was valued at USD 20.43 billion in 2024. It is projected to reach USD 28.17 billion by 2032, registering a CAGR of 4.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dust Control Systems Market Size 2024 | USD 20.43 Billion |
| Dust Control Systems Market, CAGR | 4.1% |
| Dust Control Systems Market Size 2032 | USD 28.17 Billion |
The dust control systems market is led by key players including Donaldson, Nederman Holding, Dust Control Technologies, CW Machine Worx, Duztech, Spraying Devices, Illinois Tool Works, Sly Filters, Dust Control Systems, and Colliery Dust Control. These companies dominate through advanced product portfolios, global service networks, and continuous innovation in smart and water-efficient suppression technologies. Asia-Pacific emerged as the leading region, holding a 34% market share in 2024, driven by large-scale construction, mining, and industrial activities. North America followed with a 31% share, supported by stringent air quality regulations and strong technology adoption. Continuous investments in automation, sustainability, and compliance-focused solutions strengthen market competitiveness globally.
Market Insights
- The global dust control systems market was valued at USD 20.43 billion in 2024 and is projected to reach USD 28.17 billion by 2032, growing at a CAGR of 4.1% during the forecast period.
- Market growth is driven by strict air quality regulations, increasing construction and mining projects, and the need for safer workplaces.
- Key trends include the adoption of IoT-enabled smart monitoring systems, water-efficient suppression technologies, and sustainable dust control solutions.
- The competitive landscape is led by Donaldson, Nederman Holding, Dust Control Technologies, CW Machine Worx, and Duztech, focusing on automation and eco-friendly innovation.
- Regionally, Asia-Pacific held 34%, North America 31%, and Europe 27% market shares in 2024, while the wet systems segment dominated with 62% share due to its high dust capture efficiency across industries.
Market Segmentation Analysis:
By Type
The wet dust control systems segment dominated the market with a 62% share in 2024. This dominance is attributed to its higher efficiency in capturing fine particulate matter across mining, construction, and cement operations. Wet systems, such as misting and spray-based solutions, are preferred for handling large dust volumes and maintaining air quality compliance. The growing enforcement of emission control standards and demand for effective airborne dust suppression in bulk material handling facilities continue to drive adoption of wet systems over dry variants.
- For instance, BossTek developed the DustBoss DB-100 system, which has a 60 HP fan motor and a throw distance of 100 meters. It has 30 brass nozzles and uses between 67 and 147.6 liters of water per minute.
By Mobility
The mobile controllers segment held the largest share of 46% in 2024, driven by their flexibility and ease of deployment across construction sites, quarries, and mining operations. These units offer efficient dust suppression for temporary or remote locations where fixed installations are impractical. Growing use of self-propelled and trailer-mounted systems enhances on-site operational efficiency. Manufacturers are integrating IoT-enabled monitoring and automated control systems to improve spray precision and water usage optimization, supporting the segment’s strong growth outlook in high-dust industrial environments.
- For instance, Duztech AB introduced the D60 Mobile Dust Suppression Unit featuring an 18.5-kilowatt fan motor, a 50- to 60-meter throw capacity, and automatic 360-degree rotation. The system delivers a water flow rate of up to 60 liters per minute and includes a remote control option for easy operation.
By End Use
The construction sector accounted for a 38% share in 2024, emerging as the leading end-use segment. Rising urban infrastructure projects, road expansion, and cement plant activities are key contributors to demand. Dust suppression systems are widely deployed to comply with worker safety and environmental regulations at construction sites. Increased government investment in smart city and transport infrastructure projects, coupled with stricter air quality norms, continues to boost system installations. The need to reduce particulate emissions during demolition and material handling further supports segment dominance.
Key Growth Drivers
Stringent Environmental Regulations
Rising enforcement of air quality and emission control regulations is a key growth driver for the dust control systems market. Governments across North America, Europe, and Asia-Pacific are mandating dust suppression in mining, construction, and manufacturing sectors to limit particulate emissions. Compliance with standards such as OSHA and EU Industrial Emissions Directive has accelerated adoption. Industries are investing in high-efficiency filtration and suppression technologies to avoid penalties, strengthen environmental performance, and ensure worker safety.
- For instance, Donaldson Company introduced the iCue™ Connected Filtration Service, which monitors differential pressure, airflow, and particulate levels in real time across industrial dust collectors. The platform transmits over 10,000 sensor readings per hour to cloud-based dashboards, allowing maintenance teams to prevent emission breaches under OSHA and EU IED standards.
Expanding Mining and Construction Activities
Rapid infrastructure growth and increasing mineral extraction projects are boosting the demand for dust control systems. Expanding mining operations in countries such as China, Australia, and India generate significant airborne dust, driving installation of wet and dry suppression units. The construction industry also relies on these systems for road building, cement mixing, and demolition. Rising urbanization and government-funded projects are further supporting deployment of mobile and fixed dust suppression solutions to maintain compliance and operational efficiency.
- For instance, Dust Control Technologies engineered the DB-60 Fusion system with a 25-HP fan and integrated 45 kVA generator, producing a 60-meter atomized mist throw.
Increasing Focus on Worker Health and Safety
Growing awareness of occupational health hazards linked to airborne particulates is strengthening market demand. Dust inhalation is a leading cause of respiratory diseases such as silicosis, prompting stricter workplace safety protocols. Industries are prioritizing air quality management through advanced suppression and filtration systems. Continuous monitoring, coupled with automation in spray control, enhances protection for workers in mines, quarries, and production plants, aligning with global health and safety initiatives.
Key Trends & Opportunities
Adoption of IoT and Smart Monitoring Systems
Integration of IoT-enabled sensors and automated controls is transforming the performance of dust control systems. Smart controllers allow real-time data tracking on air quality, water consumption, and equipment performance. Manufacturers are introducing remote diagnostics and predictive maintenance features that reduce downtime and improve operational efficiency. This shift toward connected and data-driven dust suppression creates opportunities for system upgrades and service-based business models in industrial facilities.
- For instance, Nederman Holding launched the Insight Analytics platform that collects performance data from connected filtration systems. Through its cloud-based platform, Insight detects anomalies in fan speed, pressure drops, and filter load to enable predictive maintenance.
Shift Toward Sustainable and Water-Efficient Solutions
Rising environmental awareness is driving demand for water-efficient and eco-friendly dust suppression technologies. Companies are developing systems that recycle and reuse water, minimizing waste and operating costs. The introduction of biodegradable chemical suppressants also supports sustainability goals. Industries adopting closed-loop systems and automated spray controls benefit from reduced environmental footprints and improved compliance with green manufacturing standards, creating long-term growth potential.
- For instance, Spraying Systems Co. introduced the AutoJet® Dust Control System, which uses PulsaJet® nozzles and Precision Spray Control (PSC) to adjust flow rates automatically based on line speed.
Key Challenges
High Installation and Maintenance Costs
The significant capital investment required for advanced dust control systems remains a key restraint. Wet and dry suppression technologies, especially those with automated and IoT-enabled components, involve high setup and maintenance expenses. Small and medium enterprises often delay adoption due to budget constraints. Frequent nozzle replacements, water management issues, and regular cleaning further add to operational costs, affecting affordability in cost-sensitive regions.
Limited Awareness in Developing Regions
Lack of awareness about occupational hazards and air quality regulations in emerging economies hinders market expansion. Many small-scale construction and mining operations continue to rely on basic dust suppression methods or manual practices. Weak regulatory enforcement and limited access to technical expertise slow adoption of advanced systems. Efforts to improve training, policy enforcement, and public health awareness are essential to overcome this challenge and expand market penetration.
Regional Analysis
North America
North America held a 31% share in 2024, supported by strict regulatory frameworks and advanced industrial practices. The U.S. leads the market due to OSHA and EPA mandates for workplace air quality and emission control. Strong adoption across construction, mining, and manufacturing sectors drives steady growth. Technological innovations, such as IoT-enabled and automated dust suppression systems, are widely integrated to enhance compliance and efficiency. High infrastructure investment and demand for sustainable industrial operations further strengthen market performance across the region.
Europe
Europe accounted for a 27% share in 2024, driven by the EU Industrial Emissions Directive and emphasis on environmental sustainability. Germany, the U.K., and France are major contributors owing to strong manufacturing bases and strict workplace safety norms. Companies are adopting advanced wet suppression and filtration systems to comply with particulate emission limits. Growing focus on eco-friendly dust control technologies, including water-efficient and chemical-free systems, aligns with the region’s decarbonization goals. Infrastructure renovation and industrial modernization continue to sustain market expansion.
Asia-Pacific
Asia-Pacific dominated the global market with a 34% share in 2024, supported by rapid industrialization and expanding mining and construction activities. China, India, and Australia are key markets due to extensive mining operations and infrastructure growth. Government initiatives promoting air quality improvement and worker safety drive large-scale installations. Local manufacturers are introducing cost-effective mobile and fixed dust control systems to meet growing demand. Rising adoption of automation and water-saving technologies across industries further enhances regional market development.
Middle East & Africa
The Middle East & Africa captured a 5% share in 2024, led by increased industrial and oil & gas activities. The Gulf Cooperation Council countries are investing in large-scale infrastructure and mining projects that require efficient dust suppression. Rising awareness of environmental and occupational safety standards supports adoption of mobile and fixed systems. Countries such as Saudi Arabia and the UAE are integrating smart monitoring technologies in industrial zones. Ongoing construction under initiatives like Vision 2030 strengthens future market prospects.
Latin America
Latin America represented a 3% share in 2024, with steady growth across Brazil, Mexico, and Chile. Expanding mining and cement production activities are major demand drivers. Governments are reinforcing air quality regulations and promoting the adoption of environmentally safe dust suppression solutions. Local industries are increasingly using wet dust control systems for cost efficiency and regulatory compliance. Rising investments in construction and energy infrastructure projects are expected to create new opportunities for mobile and tractor-mounted systems in the coming years.
Market Segmentations:
By Type
- Wet
- Dry
By Mobility
- Mobile controllers
- Fixed controllers
- Tractor-mounted
- Others
By End Use
- Construction
- Chemical
- Oil & gas
- Others (textile, pharmaceuticals)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the dust control systems market features key players such as Donaldson, Dust Control Technologies, CW Machine Worx, Nederman Holding, Duztech, Spraying Devices, Illinois Tool Works, Sly Filters, Dust Control Systems, and Colliery Dust Control. These companies focus on expanding product portfolios, improving system efficiency, and integrating smart technologies to strengthen market presence. Leading manufacturers invest in R&D to develop water-efficient, automated, and eco-friendly suppression systems that meet global environmental standards. Strategic partnerships and acquisitions are common to enhance distribution networks and service capabilities. Firms are also emphasizing digital monitoring, remote operation, and predictive maintenance to increase operational uptime and reduce costs. As industrial emission standards tighten, competition intensifies around innovation and compliance-driven solutions. North America and Europe remain technology hubs, while Asia-Pacific offers high growth potential due to expanding mining and construction sectors, prompting global players to establish localized manufacturing and service facilities.
Key Player Analysis
- Donaldson
- Dust Control Technologies
- CW Machine Worx
- Nederman Holding
- Duztech
- Spraying Devices
- Illinois Tool Works
- Sly Filters
- Dust Control Systems
- Colliery Dust Control
Recent Developments
- In August 2024, Sly LLC highlighted its legacy in industrial filtration innovation, noting its pulse-jet baghouse dust collectors operate in environments up to 500 °F and employ a “no tools required” design for bag changes-underscoring its ongoing product development in dust collector technology.
- In 2024, Donaldson Company, Inc. launched the Downflo® Evolution Pre-assembled Small (DFPRE) dust collector, which integrates iCue™ Connected Filtration Technology for real-time performance analytics and aims to reduce filter replacements and unplanned downtime.
- In 2024, Nederman Holding AB reported that its Monitoring & Control Technology division achieved a sales record for a single quarter, while its Extraction & Filtration Technology unit secured large orders and its Duct & Filter Technology unit strengthened its U.S. production and logistics competitiveness.
- In 2024, Dust Control Technologies, Inc. emphasized its focus on fugitive dust and bulk material handling solutions for mining and material-processing industries, reinforcing its service footprint across USA, Canada, Mexico, Peru, Chile, Turkey, South Africa and Europe.
Report Coverage
The research report offers an in-depth analysis based on Type, Mobility, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with increasing enforcement of industrial emission and air quality standards.
- Adoption of automated and IoT-integrated dust suppression systems will continue to rise.
- Demand from mining and construction sectors will remain a major growth contributor.
- Manufacturers will invest more in developing water-efficient and eco-friendly suppression technologies.
- Integration of AI-based monitoring will enhance system performance and maintenance efficiency.
- Regional players in Asia-Pacific will strengthen their presence through cost-effective solutions.
- Stricter worker safety regulations will drive installations across industrial facilities.
- Collaboration between technology providers and equipment manufacturers will accelerate innovation.
- Mobile and tractor-mounted systems will gain wider adoption in temporary and remote operations.
- Sustainability-focused industries will prioritize dust control systems to meet environmental compliance goals.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Dust Control Systems market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Dust Control Systems market projected to grow between 2025 and 2032?
Which Dust Control Systems market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Dust Control Systems market?
Who are the leading companies in the Dust Control Systems market?
Which region commanded the largest share of the Dust Control Systems market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 20.43 billion → 2032: USD 28.17 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dust Control Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dust Control Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dust Control Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dust Control Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dust Control Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dust Control Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dust Control Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dust Control Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 20.43 billion → 2032: USD 28.17 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dust Control Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dust Control Systems Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Dust Control Systems Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Dust Control Systems Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

