
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Speciality Coffee Retail Packaged Goods Market Size 2023 | USD 23,451.98 Million |
| Europe Speciality Coffee Retail Packaged Goods Market, CAGR | 6.80% |
| Europe Speciality Coffee Retail Packaged Goods Market Size 2032 | USD 42,395.60 Million |
Market Overview
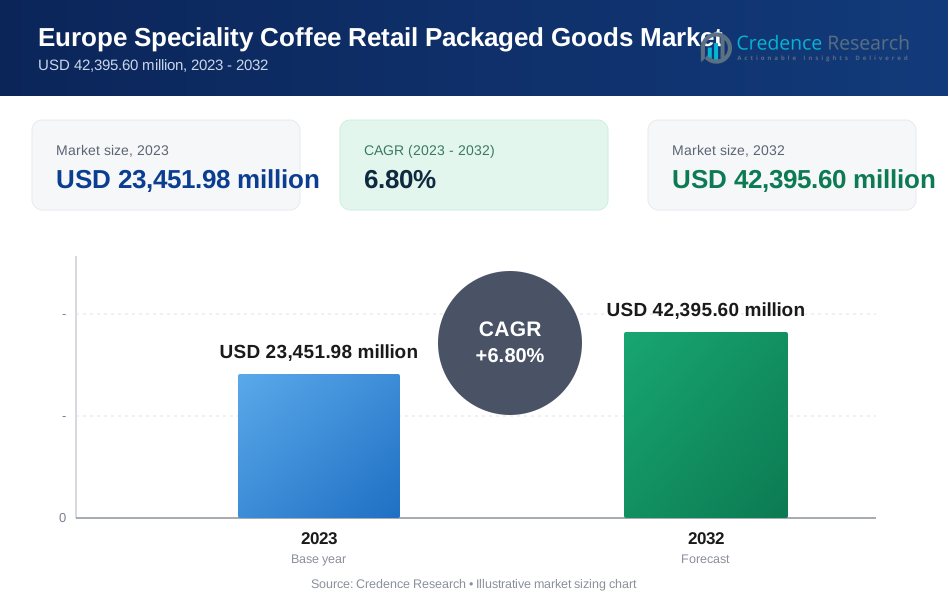
The Europe Speciality Coffee Retail Packaged Goods Market is projected to grow from USD 23,451.98 million in 2023 to an estimated USD 42,395.60 million by 2032, with a compound annual growth rate (CAGR) of 6.80% from 2024 to 2032. This substantial growth underscores the increasing consumer preference for premium coffee products that promise superior taste and quality. The market's robust expansion is fueled by the rising trend of coffee consumption among millennials and Gen Z, who are more inclined towards gourmet and artisanal coffee experiences. Additionally, the market benefits from the growing awareness and demand for sustainable and ethically sourced coffee, which has become a significant factor in purchasing decisions.
Several key drivers and trends are shaping the market's trajectory. Firstly, the increasing disposable income and urbanization across Europe are boosting the demand for high-quality coffee products. The convenience of packaged goods, coupled with the rise in home brewing culture, has significantly contributed to market growth. Furthermore, the advent of innovative packaging solutions that preserve the freshness and flavor of coffee has enhanced consumer appeal. The trend towards personalized coffee experiences, facilitated by advancements in technology such as smart coffee machines, is also propelling market growth. Moreover, the rising health consciousness among consumers is driving the demand for organic and specialty coffee products that offer added health benefits.
Geographically, Western Europe dominates the market, with countries like Germany, France, and the UK leading in consumption and retail sales. These countries have a well-established coffee culture and a high penetration of specialty coffee shops, which drives the demand for retail packaged goods. Eastern Europe is also witnessing significant growth, driven by the increasing popularity of specialty coffee among younger populations and the expansion of retail chains. Key players in the market include Nestlé S.A., JAB Holding Company, Luigi Lavazza S.p.A., and Starbucks Corporation. These companies are focusing on product innovation, strategic partnerships, and acquisitions to strengthen their market position and cater to the evolving consumer preferences in the region.
Market Drivers
Rising Disposable Income and Urbanization:
The continuous increase in disposable income across Europe significantly drives the growth of the specialty coffee retail packaged goods market. For instance, the median disposable income in the EU increased by 20% in real terms from 2010 to 2022. As consumers have more financial resources at their disposal, they are willing to spend more on premium and high-quality products, including specialty coffee. Urbanization has also played a crucial role in shaping consumer preferences. Urban areas, characterized by a fast-paced lifestyle and higher living standards, have seen a surge in demand for convenient, ready-to-use coffee products that do not compromise on quality. The confluence of increased spending power and the fast-paced urban lifestyle has thus created a fertile ground for the growth of the specialty coffee market in Europe. Moreover, the European market for specialty coffees is rapidly growing, partly driven by out-of-home consumption. The growing demand for specialty coffee follows the growing consumer interest in taste profiles and the coffee’s origin.
Growing Health Consciousness and Demand for Organic Products:
Health consciousness among consumers has seen a marked rise, leading to a greater demand for organic and specialty coffee products. For instance, a survey found that more than two-thirds (67.5%) of people aged 16 or over living in the European Union (EU) perceived their health status as very good or good. This growing health consciousness is driving the demand for healthier alternatives in their diet. Consumers are increasingly aware of the health benefits associated with high-quality coffee, such as antioxidants and essential nutrients. For example, coffee contains bioactive compounds that confer a protective factor against the development of chronic diseases. Coffee helps to increase mood through its main component, caffeine, which also allows for a feeling of well-being. Specialty coffee, often perceived as a healthier alternative to regular coffee due to its purer ingredients and ethical sourcing practices, appeals to health-conscious individuals. This shift towards health and wellness has driven the market for organic and specialty coffee, as consumers seek products that align with their health goals and ethical values.
Increasing Popularity of Home Brewing and Coffee Culture:
The trend towards home brewing has gained significant traction, particularly in the wake of the COVID-19 pandemic. For instance, a survey conducted in 2023 indicated that 45% of respondents reported brewing coffee at home more frequently than before the pandemic. This trend has encouraged consumers to explore and experiment with different coffee varieties and brewing methods, boosting the demand for specialty coffee retail packaged goods. In Europe, the coffee culture is growing rapidly. A study found that 60% of European consumers now consider themselves knowledgeable about coffee, and 70% express a preference for premium coffee experiences. This trend is further supported by the growing coffee culture in Europe, where consumers are becoming more knowledgeable and appreciative of premium coffee experiences. Specialty coffee shops and cafes have also contributed to this trend by promoting artisanal coffee and educating consumers about different brewing techniques and coffee origins.
Advancements in Packaging Technology and Sustainability Initiatives:
Innovations in packaging technology have greatly enhanced the appeal and shelf life of specialty coffee retail packaged goods. Advanced packaging solutions, such as vacuum-sealed bags and nitrogen-flushed containers, help preserve the freshness, aroma, and flavor of coffee, ensuring that consumers receive a high-quality product. Additionally, the growing emphasis on sustainability and ethical sourcing practices has driven the demand for environmentally friendly packaging. Consumers are increasingly choosing brands that prioritize sustainability, which has prompted key market players to adopt eco-friendly packaging solutions and ethical sourcing practices. This focus on sustainability not only meets consumer demand but also strengthens brand loyalty and market position.
Market Trends
Surge in Single-Origin Coffee Popularity:
One of the most notable trends in the Europe specialty coffee market is the growing preference for single-origin coffee. Consumers are increasingly interested in coffee that can be traced back to a specific farm or region, which offers unique flavor profiles and a more transparent supply chain. This trend is driven by a desire for authenticity and a deeper connection to the coffee's origins, enhancing the overall consumer experience and supporting ethical sourcing practices.
Rise of Ready-to-Drink (RTD) Specialty Coffee:
Ready-to-drink (RTD) specialty coffee beverages are gaining significant traction among European consumers, with a recent survey showing that 35% of consumers prefer RTD coffee beverages due to their convenience and quality. The segment, which includes cold brews, iced coffees, and specialty lattes, appeals to busy individuals looking for a quick and premium coffee experience. These products, often marketed as healthier, on-the-go alternatives to traditional coffee shop beverages, have seen a 25% increase in sales over the past year.
Emphasis on Sustainable and Ethical Practices:
Sustainability and ethical sourcing have become paramount in the specialty coffee market. A study found that 50% of European consumers consider the environmental and social impacts of their purchases when choosing coffee products. This growing consciousness has led to higher demand for certified organic, fair trade, and sustainably sourced coffee. Consequently, many brands are adopting eco-friendly packaging, supporting direct trade relationships with coffee farmers, and investing in sustainable farming practices to meet consumer expectations and drive market growth.
Growth in E-commerce and Direct-to-Consumer Sales:
The shift towards online shopping has significantly impacted the specialty coffee market, with online sales of specialty coffee products growing by 40% since the start of the COVID-19 pandemic. E-commerce platforms and direct-to-consumer (DTC) sales channels have made it easier for consumers to access a wide variety of specialty coffee products. Brands are now focusing on enhancing their online presence, with 60% offering subscription services and providing detailed information about their products to attract and retain customers.
Increased Focus on Health and Wellness:
Health and wellness trends are significantly influencing consumer choices in the specialty coffee market, with a growing demand for products offering additional health benefits. Sales of coffee enriched with vitamins, antioxidants, or functional ingredients like adaptogens and CBD have increased by 20% in the last year. This trend reflects a broader shift towards healthier lifestyles, with 55% of consumers seeking beverages that contribute to their overall well-being.
Innovation in Coffee Blends and Flavors:
Innovation in coffee blends and flavors is driving consumer interest in specialty coffee. Brands are experimenting with unique combinations and introducing limited-edition flavors to keep their offerings fresh and exciting. This includes the use of exotic ingredients, such as spices, fruits, and botanicals, to create distinct and memorable coffee experiences. Such innovations cater to adventurous consumers looking to explore new taste profiles.
Expansion of Specialty Coffee Shops and Cafés:
The proliferation of specialty coffee shops and cafés across Europe is a significant trend that supports the retail packaged goods market. These establishments serve as key touchpoints for consumers to experience high-quality coffee, learn about different brewing methods, and develop a preference for specialty products. The success of these cafes often translates to increased demand for retail packaged goods, as consumers seek to recreate the premium coffee experience at home.
Market Restraints and Challenges
High Costs of Premium Products:
One of the most significant restraints in the Europe Specialty Coffee Retail Packaged Goods Market is the high cost associated with premium products. Specialty coffee, known for its superior quality, ethical sourcing, and unique flavor profiles, often comes with a higher price tag. This cost is driven by various factors, including the labor-intensive cultivation and harvesting processes, stringent quality control measures, and the premium paid for ethically sourced beans. While affluent consumers and coffee aficionados are willing to pay a premium, the higher prices can deter cost-sensitive consumers, limiting the market's broader reach.
Intense Market Competition:
The specialty coffee market is highly competitive, with numerous established brands and new entrants vying for market share. This intense competition necessitates significant investment in marketing, product innovation, and distribution channels to differentiate and maintain a competitive edge. Smaller companies and new entrants may find it challenging to compete against well-established brands with extensive resources and market presence. Additionally, the constant need to innovate and offer unique products can strain resources and impact profitability.
Supply Chain Disruptions:
The specialty coffee market is particularly vulnerable to supply chain disruptions, which can significantly impact product availability and pricing. Factors such as climate change, political instability in coffee-producing regions, and global logistical challenges can disrupt the supply of high-quality coffee beans. These disruptions not only affect the consistency of supply but can also lead to increased costs, which are often passed on to consumers. Ensuring a stable and reliable supply chain is a critical challenge for market players.
Limited Consumer Awareness and Education:
While the appreciation for specialty coffee is growing, there is still a considerable segment of consumers who are unaware of the differences between specialty and regular coffee. This lack of awareness can hinder market growth, as potential consumers may not fully understand the value proposition of specialty coffee. Educating consumers about the benefits, quality, and unique characteristics of specialty coffee requires substantial effort and investment in marketing and consumer engagement initiatives.
Stringent Regulatory Environment:
The specialty coffee market in Europe is subject to stringent regulations related to food safety, labeling, and sustainability. Compliance with these regulations can be complex and costly, particularly for smaller companies with limited resources. The need to adhere to various national and EU-wide regulations can create administrative burdens and increase operational costs, posing a challenge for market participants.
Economic Uncertainty:
Economic fluctuations and uncertainties can impact consumer spending behavior, particularly for non-essential premium products like specialty coffee. During economic downturns, consumers may cut back on discretionary spending, opting for cheaper alternatives instead of premium specialty coffee products. This sensitivity to economic conditions poses a significant challenge, as market growth is closely tied to the overall economic environment.
Market Segmentation Analysis
By Type
The Europe Specialty Coffee Retail Packaged Goods Market is segmented into single-origin, blended, organic, and ready-to-drink (RTD) coffee. Single-origin coffee, sourced from specific regions or farms, appeals to consumers seeking unique flavor profiles and transparency in the supply chain. Blended coffee, which combines beans from various regions to create balanced and consistent flavors, caters to those desiring reliable taste profiles, especially in coffee shops and households. Organic coffee, grown without synthetic fertilizers or pesticides, attracts health-conscious and environmentally aware consumers, driven by the increasing emphasis on sustainability and health benefits. Meanwhile, RTD coffee products, such as cold brews and specialty lattes, offer convenience and quality for on-the-go consumption, experiencing significant growth due to the busy lifestyles of urban consumers and the trend towards premium convenience beverages.
By Application
The specialty coffee market is segmented by various applications, including home brewing, which is driven by consumers who prefer making coffee at home using specialty beans and equipment, gaining momentum with methods like pour-over and espresso machines. Cafés and coffee shops cater to those seeking high-quality coffee experiences outside their homes, benefiting from Europe's growing coffee culture. The office and commercial use segment meets the demand for specialty coffee in workplaces, enhancing employee satisfaction and productivity. Retail and supermarkets provide convenient access to premium coffee for everyday consumers, offering a wide range of products from whole beans and ground coffee to instant and ready-to-drink beverages, catering to diverse preferences.
Segments
Based on Type
- Single-Origin Coffee
- Blended Coffee
- Organic Coffee
- Ready-to-Drink (RTD) Coffee
Based on Application
- Home Brewing
- Cafés and Coffee Shops
- Office and Commercial Use
- Retail and Supermarkets
By Regional
- North America
- US.
- Canada
- Europe
- UK.
- Germany
- France
- Italy
- Spain
- Denmark
- Sweden
- Norway
- Asia Pacific
- Japan
- China
- India
- South Korea
- Australia
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
- Kuwait
Regional Analysis
Western Europe (45%):
Western Europe dominates the specialty coffee market, accounting for approximately 45% of the market share. This region's dominance is driven by countries such as Germany, France, the UK, and the Netherlands, where coffee culture is deeply ingrained. Consumers in these countries exhibit a high demand for premium and artisanal coffee products, supported by a well-established network of specialty coffee shops and retail outlets. The emphasis on quality, sustainability, and ethical sourcing resonates strongly with the environmentally conscious and health-aware population in this region. Additionally, the widespread adoption of home brewing practices further boosts the demand for retail packaged specialty coffee.
Northern Europe (25%):
Northern Europe holds around 25% of the market share, with significant contributions from countries like Sweden, Denmark, and Norway. These countries have a rich tradition of coffee consumption, often characterized by a preference for high-quality, sustainably sourced coffee. The market in Northern Europe is marked by a strong focus on organic and fair trade products, aligning with the region's robust commitment to environmental sustainability. The popularity of single-origin and organic coffee is particularly pronounced, reflecting the consumers' willingness to pay a premium for ethically produced coffee.
Southern Europe (15%):
Southern Europe contributes about 15% to the market share, with Italy, Spain, and Portugal being the key players. This region's coffee culture is influenced by its long-standing traditions of espresso and strong, full-bodied coffee flavors. While the specialty coffee market is still emerging in Southern Europe, there is a growing interest in premium and specialty coffee products, particularly among younger consumers and urban populations. The market is witnessing a gradual shift towards home brewing and the adoption of innovative coffee brewing methods, driven by increasing exposure to global coffee trends.
Eastern Europe (15%):
Eastern Europe, comprising countries like Poland, Czech Republic, and Hungary, accounts for approximately 15% of the market share. The specialty coffee market in this region is expanding rapidly, fueled by the rising popularity of specialty coffee among younger demographics and the proliferation of specialty coffee shops. Eastern European consumers are increasingly seeking out high-quality coffee experiences, supported by growing disposable incomes and a burgeoning coffee culture. The market is characterized by a mix of traditional preferences and a growing openness to innovative and premium coffee products.
Key players
- The J M Smucker Company
- Strauss Group Ltd.
Competitive Analysis
The Europe Specialty Coffee Retail Packaged Goods Market is highly competitive, with key players like The J M Smucker Company and Strauss Group Ltd. leading the industry. The J M Smucker Company leverages its extensive portfolio and strong brand recognition to maintain a significant market presence. Its strategic focus on innovation and quality has allowed it to capture a loyal consumer base. Strauss Group Ltd., on the other hand, emphasizes sustainability and ethical sourcing, appealing to environmentally conscious consumers. Both companies invest heavily in marketing and product development to differentiate their offerings. The competitive landscape is further intensified by regional players and new entrants striving to carve out market share through unique value propositions and niche targeting. This competitive environment drives continuous innovation and improvements in product quality, ultimately benefiting consumers with a diverse array of high-quality specialty coffee options.
Recent Developments
Strauss Group (TASE: STRS) recently presented its business strategy update for 2024-2026. Key strategy highlights include a focus on core businesses and planned investments of 5%-7% of revenues in plants and infrastructure in Israel. The strategy also emphasizes sustainable growth in key markets, including Israel, China, and Brazil, to reinforce its market position and drive long-term success.
In March 2023, Blue Bottle Coffee secured USD 700 million in funding. This substantial investment will be utilized to expand Blue Bottle's retail and wholesale operations and drive new product development. This funding aims to enhance the company's market presence and support its growth initiatives, ensuring continued innovation and offering high-quality coffee experiences to a broader customer base.
In February 2023, Peet's Coffee acquired Stumptown Coffee Roasters for USD 1.1 billion. This acquisition marks a significant consolidation in the specialty coffee industry, expected to spur increased competition and innovation. By combining resources and expertise, Peet's Coffee aims to strengthen its market position and offer diverse, premium coffee products to a wider audience.
In January 2023, Starbucks announced plans to open 3,000 new stores in China over the next five years. This substantial investment highlights the company's commitment to the Chinese market, anticipated to be one of the fastest-growing markets for specialty coffee. This expansion aims to cater to the rising demand for high-quality coffee experiences among Chinese consumers.
Market Concentration and Characteristics
The Europe Specialty Coffee Retail Packaged Goods Market is characterized by a moderate to high level of market concentration, with several dominant players such as The J M Smucker Company, Strauss Group Ltd., Nestlé S.A., and Starbucks Corporation holding significant market shares. These key players leverage strong brand recognition, extensive distribution networks, and continuous innovation to maintain their competitive edge. The market is defined by a growing consumer preference for premium, sustainably sourced, and ethically produced coffee products. Additionally, the rise of e-commerce and direct-to-consumer sales channels has enabled smaller niche brands to enter the market, contributing to increased competition and diversity of product offerings.
Report Coverage
The research report offers an in-depth analysis based on Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to sustain its growth trajectory, driven by increasing consumer demand for premium and specialty coffee products across Europe.
- Companies will continue to innovate, introducing new flavors, blends, and functional ingredients to cater to evolving consumer preferences and enhance the coffee experience.
- The ready-to-drink (RTD) segment will see significant expansion, with new and convenient coffee products appealing to busy, on-the-go consumers.
- Sustainability will remain a key focus, with more brands adopting eco-friendly packaging and sourcing practices to meet consumer demand for ethically produced coffee.
- E-commerce and direct-to-consumer channels will play an increasingly important role, providing consumers with easy access to a wide variety of specialty coffee products.
- Technological advancements in brewing and packaging will enhance product quality and shelf life, ensuring a superior coffee experience for consumers.
- The market will witness heightened competition as new entrants and smaller niche brands challenge established players, fostering innovation and diversity.
- Companies will explore opportunities in emerging markets within Europe, such as Eastern European countries, where coffee culture is rapidly evolving.
- The trend towards health and wellness will drive demand for coffee products enriched with vitamins, antioxidants, and other functional ingredients.
- Strategic partnerships and acquisitions will be crucial for companies looking to expand their market presence, enhance their product portfolios, and achieve sustainable growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the Europe Speciality Coffee Retail Packaged Goods Market by 2032?
What factors are driving the growth of the specialty coffee market in Europe?
How is the market for organic and specialty coffee products evolving in Europe?
Which regions in Europe dominate the specialty coffee retail packaged goods market?
What role does innovation play in the specialty coffee market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Speciality Coffee Retail Packaged Goods Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Speciality Coffee Retail Packaged Goods Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 23,451.98 million → 2032: USD 42,395.60 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Speciality Coffee Retail Packaged Goods Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Speciality Coffee Retail Packaged Goods Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Speciality Coffee Retail Packaged Goods Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Speciality Coffee Retail Packaged Goods Market Drivers
- 3.3 Europe Speciality Coffee Retail Packaged Goods Market Restraints & Challenges
- 3.4 Europe Speciality Coffee Retail Packaged Goods Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Speciality Coffee Retail Packaged Goods Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Speciality Coffee Retail Packaged Goods Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Speciality Coffee Retail Packaged Goods category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Speciality Coffee Retail Packaged Goods Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Speciality Coffee Retail Packaged Goods Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Speciality Coffee Retail Packaged Goods market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Speciality Coffee Retail Packaged Goods Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Speciality Coffee Retail Packaged Goods Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Speciality Coffee Retail Packaged Goods Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Speciality Coffee Retail Packaged Goods (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Speciality Coffee Retail Packaged Goods Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Speciality Coffee Retail Packaged Goods Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Speciality Coffee Retail Packaged Goods Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Speciality Coffee Retail Packaged Goods Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Speciality Coffee Retail Packaged Goods Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Speciality Coffee Retail Packaged Goods Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Speciality Coffee Retail Packaged Goods Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Speciality Coffee Retail Packaged Goods Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Speciality Coffee Retail Packaged Goods Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
