
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| EV Fleet Management System Market Size 2024 | USD 25,007.76 Million |
| EV Fleet Management System Market, CAGR | 5.40% |
| EV Fleet Management System Market Size 2032 | USD 39,257.92 Million |
Market Overview
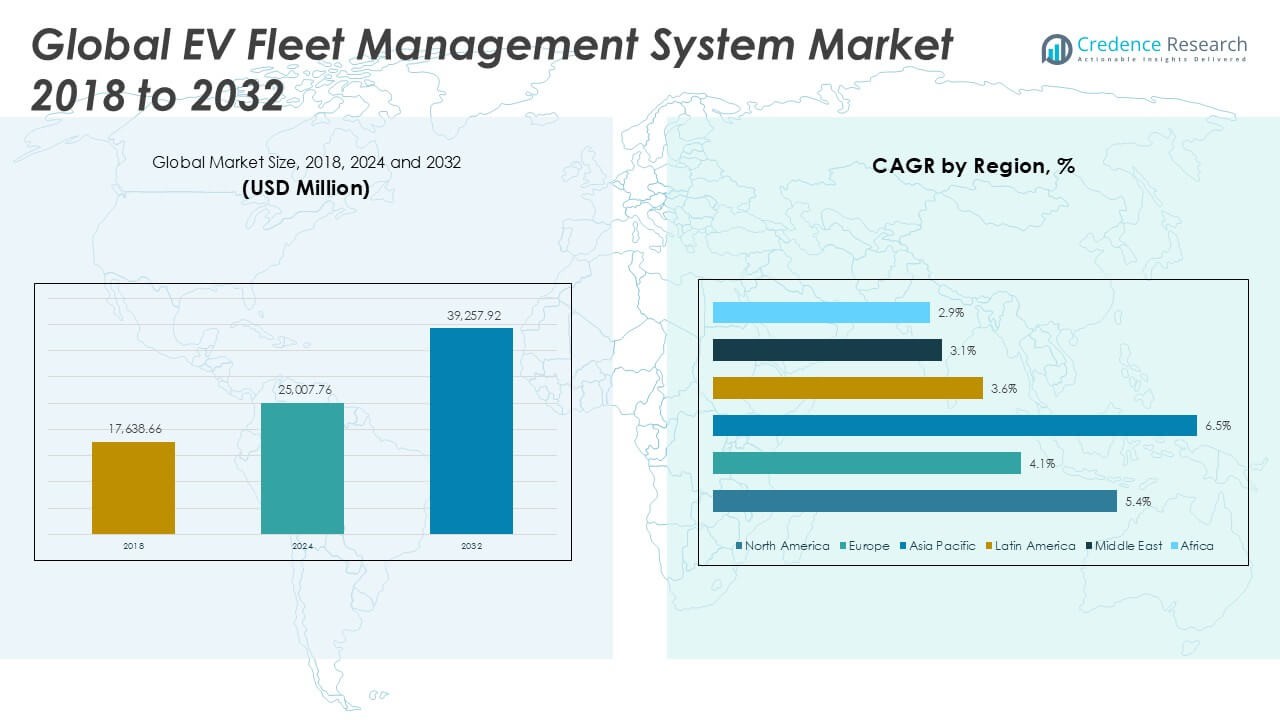
The EV Fleet Management System Market was valued at USD 17,638.66 million in 2018, increased to USD 25,007.76 million in 2024, and is anticipated to reach USD 39,257.92 million by 2032, at a CAGR of 5.40% during the forecast period.
The EV Fleet Management System Market is experiencing robust growth, driven by the rapid adoption of electric vehicles in commercial and public transport fleets. Organizations increasingly prioritize sustainability and operational efficiency, fueling demand for advanced fleet management solutions that optimize route planning, monitor real-time vehicle performance, and reduce maintenance costs. The integration of telematics, IoT, and cloud-based analytics enhances decision-making and supports predictive maintenance, leading to improved fleet utilization. Market growth is further supported by favorable government policies, incentives for electric vehicle adoption, and expanding charging infrastructure. Key trends include the rise of AI-powered data analytics, the shift toward Mobility-as-a-Service (MaaS) models, and the development of smart charging and energy management platforms. These trends enable fleet operators to streamline operations, minimize total cost of ownership, and comply with evolving environmental regulations, positioning the EV Fleet Management System Market for sustained expansion over the coming years.
The EV Fleet Management System Market demonstrates strong growth across key regions, with North America, Europe, and Asia Pacific emerging as leading hubs for technology adoption and fleet electrification. North America, led by the United States and Canada, benefits from robust government support, advanced charging infrastructure, and a mature electric vehicle ecosystem. Europe’s market is propelled by strict environmental regulations and progressive public transport initiatives, with Germany, the UK, and France playing major roles. In Asia Pacific, China, Japan, and South Korea drive rapid expansion through aggressive fleet electrification targets and digital innovation. Leading key players in the EV Fleet Management System Market include Geotab Inc., recognized for its advanced telematics solutions, Samsara, offering integrated fleet management platforms, and Verizon Connect, providing scalable, cloud-based systems. Webfleet (Bridgestone) also stands out, delivering comprehensive connectivity and energy management tools for diverse electric fleets.
Market Insights
- The EV Fleet Management System Market was valued at USD 17,638.66 million in 2018, reached USD 25,007.76 million in 2024, and is projected to hit USD 39,257.92 million by 2032, with a CAGR of 5.40% during the forecast period.
- Increasing adoption of electric vehicles in commercial, public, and logistics fleets is fueling market demand, as operators focus on reducing emissions and lowering operational costs.
- Growing government support, emission regulations, and investments in charging infrastructure are key drivers accelerating fleet electrification and management system deployments.
- Notable trends include the integration of telematics, IoT, and AI-powered analytics for real-time monitoring, predictive maintenance, and dynamic route optimization in electric fleets.
- Competitive activity remains intense, with leading companies such as Geotab Inc., Samsara, and Verizon Connect introducing advanced cloud-based platforms and energy management solutions.
- Key restraints for market growth involve integration challenges with legacy fleet management systems, limited charging infrastructure in certain regions, and concerns over data security and system interoperability.
- Regionally, North America and Asia Pacific show robust adoption, driven by supportive policies and rapid infrastructure growth, while Europe advances through strong regulatory frameworks and sustainable transport programs; Latin America, the Middle East, and Africa experience slower but steady progress due to ongoing infrastructure development and targeted fleet initiatives.
Market Drivers
Sustained Electrification of Commercial and Public Fleets Fuels Market Demand
Rising adoption of electric vehicles within commercial and public transportation sectors drives robust growth in the EV Fleet Management System Market. Businesses and government organizations seek to reduce carbon emissions and operating expenses by transitioning large vehicle fleets from internal combustion engines to electric powertrains. The shift creates demand for specialized management systems capable of monitoring battery status, optimizing charging schedules, and ensuring seamless integration with broader fleet operations. Increasing availability and diversity of electric vehicles across multiple classes, including delivery vans, buses, and service vehicles, further supports this expansion. Fleet operators require advanced tools for real-time tracking, route optimization, and energy management. These requirements position the market as essential for facilitating large-scale electrification initiatives.
- For instance, Geotab Inc. currently manages data for more than 4 million connected vehicles worldwide, supporting large-scale fleet transitions with real-time insights and EV-specific analytics.
Government Incentives and Regulatory Pressures Shape Market Direction
Strong regulatory mandates and supportive government policies significantly influence the EV Fleet Management System Market. Many regions implement ambitious emission reduction targets, creating compliance requirements for fleet operators and public transit authorities. Governments provide incentives, such as subsidies, tax credits, and grants, to accelerate electric fleet deployment and promote technology upgrades. Regulatory bodies also establish standards for fleet efficiency, data reporting, and environmental performance. These frameworks encourage organizations to invest in comprehensive management systems that support monitoring, reporting, and compliance with evolving rules. It benefits from policy-driven momentum and growing regulatory complexity.
- For instance, the United States allocated $5 billion through the National Electric Vehicle Infrastructure (NEVI) Formula Program to accelerate nationwide EV infrastructure deployment, boosting demand for advanced fleet management solutions.
Advancements in Connected Vehicle Technologies Transform Fleet Management
Technological innovations in telematics, IoT, and cloud-based analytics play a pivotal role in the evolution of the EV Fleet Management System Market. Integration of advanced sensors, real-time data analytics, and wireless communication networks enables predictive maintenance, proactive route adjustments, and remote diagnostics. Fleet managers leverage connected solutions to increase vehicle uptime, enhance driver safety, and optimize total cost of ownership. Access to granular data allows for informed decision-making and improved energy efficiency. The ability to seamlessly connect vehicles, charging infrastructure, and back-end systems creates operational synergies and new service opportunities. Technology advancements underpin market expansion by delivering measurable value to fleet operators.
Rising Focus on Operational Efficiency and Cost Reduction Drives Adoption
Organizations prioritize operational efficiency and cost reduction, driving adoption of EV fleet management solutions. The need to manage energy consumption, minimize charging downtime, and maximize asset utilization pushes demand for intelligent platforms. Advanced management systems facilitate automated scheduling, centralized control of charging operations, and dynamic resource allocation. These solutions enable fleet operators to track key performance indicators and implement data-driven strategies for maintenance and replacement. The EV Fleet Management System Market supports organizations in achieving sustainability objectives while maintaining financial performance. Focus on efficient resource management and long-term savings strengthens its market outlook.
Market Trends
Integration of Artificial Intelligence and Machine Learning Enhances Fleet Operations
AI and machine learning technologies are increasingly shaping the EV Fleet Management System Market, providing actionable insights for predictive maintenance, battery optimization, and driver behavior analytics. Fleet operators leverage these advanced analytics to forecast battery life, anticipate maintenance needs, and reduce operational risks. Smart algorithms enable automated route planning, dynamic energy management, and real-time adjustments to minimize delays and energy usage. The integration of AI supports continuous performance improvements across diverse fleet environments. It positions fleet management platforms as essential tools for proactive decision-making and cost control. Adoption of these technologies accelerates competitive differentiation among service providers.
- For instance, Samsara’s AI-powered platform processes over 5 trillion sensor data points annually, empowering fleet customers with predictive analytics and real-time safety interventions.
Expansion of Smart Charging and Energy Management Platforms
The development of sophisticated charging management solutions remains a defining trend in the EV Fleet Management System Market. Fleet operators demand platforms that support remote monitoring, automated billing, and real-time scheduling for multi-vehicle charging operations. Integration with renewable energy sources and grid-responsive charging further enhances flexibility and sustainability. Advanced platforms enable load balancing, reduce peak demand costs, and ensure efficient utilization of charging infrastructure. It supports seamless coordination between vehicles and charging networks, reducing downtime and improving energy efficiency. Growing importance of energy management drives continued investment in these platforms.
- For instance, ChargePoint’s network delivered over 188 million charging sessions as of 2023, providing fleet operators with real-time charging management and detailed energy analytics across 225,000 active charging ports.
Rise of Mobility-as-a-Service (MaaS) and Subscription-Based Fleet Solutions
Mobility-as-a-Service is transforming how organizations deploy and manage electric fleets, pushing the EV Fleet Management System Market toward flexible, subscription-based models. Fleet operators and service providers utilize centralized platforms to manage diverse vehicle types, usage scenarios, and customer needs. Subscription-based solutions facilitate scalable, on-demand fleet expansion without significant upfront investment. Integration of MaaS with fleet management systems supports streamlined bookings, usage tracking, and automated billing. The trend aligns with broader shifts toward asset-light operations and digital mobility ecosystems. It enhances accessibility and responsiveness for fleet customers.
Emphasis on Real-Time Data Integration and Interoperability
Demand for seamless data exchange across vehicles, charging stations, and enterprise systems is a key trend shaping the EV Fleet Management System Market. Open APIs and standardized protocols enable interoperability between disparate systems, allowing operators to centralize data management and analytics. Real-time data integration supports instant monitoring of fleet status, performance, and compliance. Enhanced connectivity enables quick response to operational disruptions, regulatory changes, or energy market fluctuations. The market sees growing adoption of unified platforms that aggregate, visualize, and analyze real-time information for improved operational control. Integration capabilities define future competitiveness and customer value.
Market Challenges Analysis
Complex Integration with Existing Legacy Systems Limits Adoption
The need to integrate EV fleet management solutions with legacy infrastructure presents a significant challenge for many organizations. Legacy systems often lack compatibility with modern telematics, IoT devices, and cloud-based platforms, making seamless data exchange difficult. Fleet operators face high costs and technical complexities in upgrading or replacing outdated hardware and software. The EV Fleet Management System Market faces resistance from organizations hesitant to disrupt established operations or invest in comprehensive overhauls. Disparate data sources, varying communication protocols, and security concerns further complicate system integration. Achieving full interoperability requires substantial planning, skilled resources, and ongoing technical support.
Limited Charging Infrastructure and Range Anxiety Hinder Scalability
Widespread deployment of EV fleets relies on access to reliable and scalable charging infrastructure, a challenge in many regions. Gaps in public and private charging station coverage create operational bottlenecks, limit route flexibility, and contribute to range anxiety among fleet operators. The EV Fleet Management System Market experiences delays in project rollouts when infrastructure development lags behind vehicle deployment. Operators must carefully plan charging schedules, manage peak loads, and address downtime risks. Infrastructure constraints may discourage potential adopters from transitioning to electric fleets. It faces mounting pressure to offer solutions that optimize charging utilization and address these logistical hurdles.
Market Opportunities
Expansion of Smart Cities and Government Sustainability Initiatives Creates Growth Potential
The rise of smart city projects and expanding government sustainability initiatives generate substantial opportunities for the EV Fleet Management System Market. Urban areas are prioritizing cleaner mobility solutions and efficient transportation networks, prompting investments in electric vehicle fleets and advanced management platforms. Governments allocate funding for public charging stations, digital infrastructure, and integrated mobility systems. The market can support city planners and fleet operators by offering real-time monitoring, predictive analytics, and dynamic route optimization. Partnerships with municipalities and transit agencies can unlock new revenue streams and strengthen market presence. It stands to benefit from increased policy alignment and public-private collaborations focused on sustainable urban mobility.
Integration with Renewable Energy and Advanced Analytics Supports Market Differentiation
Growing adoption of renewable energy sources in fleet operations opens new avenues for value creation in the EV Fleet Management System Market. Operators seek solutions that connect with solar panels, wind energy systems, and grid storage to reduce operational costs and carbon footprints. Advanced analytics and AI-driven insights help optimize energy consumption, forecast charging needs, and manage peak demand periods. The market can offer platforms that enable automated energy management, smart charging, and data-driven decision-making for fleet sustainability. Enhanced integration capabilities position vendors as essential partners for forward-thinking organizations. It gains a competitive edge by aligning fleet management with broader environmental and energy goals.
Market Segmentation Analysis:
By Component:
The market divides into hardware, software, and services. Hardware remains fundamental, driven by demand for telematics devices, GPS trackers, battery management units, and sensors essential for vehicle monitoring and real-time data collection. Software commands significant growth, propelled by rising adoption of cloud-based analytics, fleet optimization platforms, and mobile applications. Software solutions enable predictive maintenance, energy management, and compliance reporting, becoming central to modern fleet operations. Services such as system integration, maintenance, training, and technical support ensure continuous system performance and user adoption. The combined strength of these components supports end-to-end fleet management capabilities for organizations seeking operational efficiency.
- For instance, Verizon Connect supports more than 24,000 customers with its fleet management hardware and software, processing millions of data points per day to optimize operations.
By Deployment Mode:
The market segments into cloud-based and on-premises solutions. Cloud-based deployment dominates, favored for its scalability, flexibility, and remote accessibility. Fleet operators benefit from seamless updates, data synchronization, and lower upfront infrastructure costs. It also allows for centralized control of multiple sites and easy integration with third-party applications. On-premises deployment appeals to organizations with strict data security policies or specific regulatory requirements, offering greater control over sensitive operational data. Both deployment models meet distinct business needs and continue to coexist within the market landscape.
- For instance, Webfleet (Bridgestone) enables cloud-based fleet management for over 60,000 businesses globally, delivering real-time insights and seamless multi-site coordination for diverse operational requirements.
By Fleet Size:
The EV Fleet Management System Market addresses both large fleets and small and medium fleets. Large fleets, including public transportation, logistics, and delivery companies, represent a significant share, requiring advanced solutions for route planning, resource allocation, and multi-site coordination. These operators value automation, analytics, and integration with broader enterprise systems. Small and medium fleets demand cost-effective, easy-to-deploy solutions that support basic fleet tracking, maintenance scheduling, and performance monitoring. The market serves a wide spectrum of customers, ensuring scalability and adaptability to varying operational scales and complexities.
Segments:
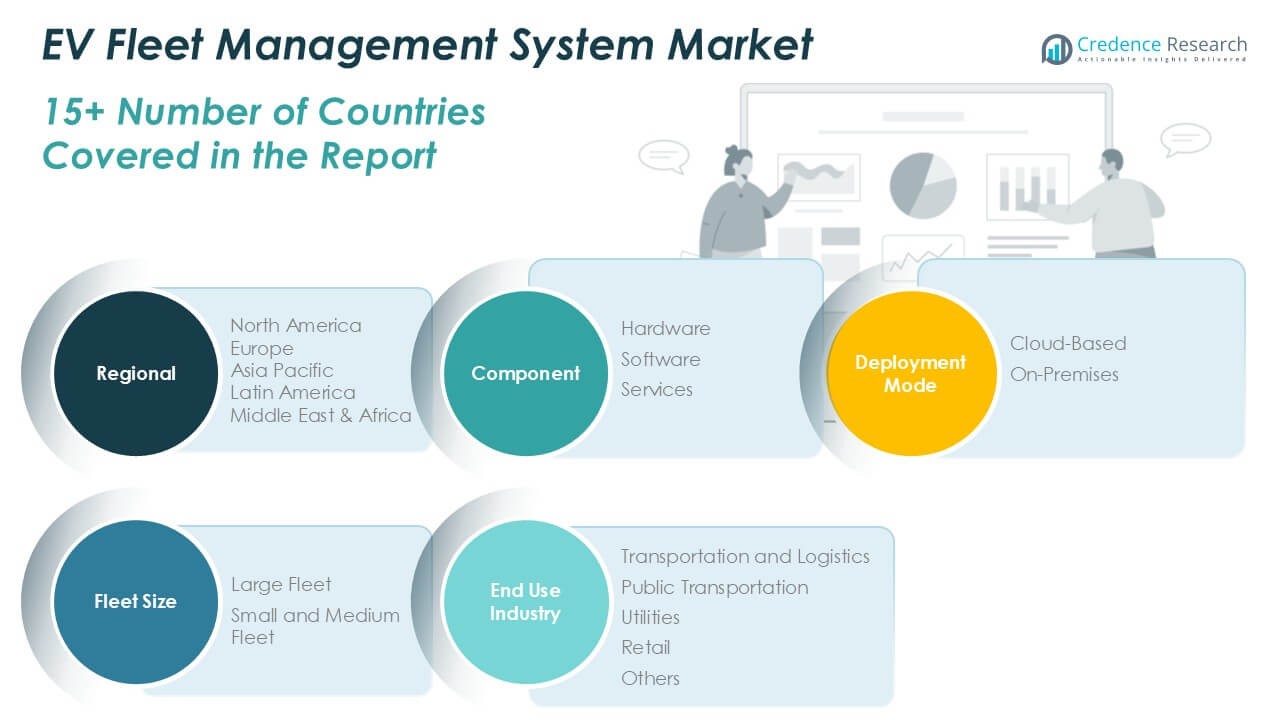
Based on Component:
- Hardware
- Software
- Services
Based on Deployment Mode:
- Cloud-Based
- On-Premises
Based on Fleet Size:
- Large Fleet
- Small and Medium Fleet
Based on End Use Industry:
- Transportation and Logistics
- Public Transportation
- Utilities
- Retail
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America EV Fleet Management System Market
North America EV Fleet Management System Market grew from USD 7,518.19 million in 2018 to USD 10,545.75 million in 2024 and is projected to reach USD 16,602.14 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.4%. North America is holding a 42% market share. The United States leads regional adoption, driven by strong government incentives, a well-developed charging infrastructure, and widespread corporate sustainability initiatives. Canada follows with growing investments in green transportation, while Mexico sees steady expansion in logistics and public fleet electrification. Market growth benefits from early adoption of advanced telematics, integration with renewable energy, and a high focus on reducing fleet emissions.
Europe EV Fleet Management System Market
Europe EV Fleet Management System Market grew from USD 3,284.92 million in 2018 to USD 4,401.53 million in 2024 and is set to reach USD 6,281.53 million by 2032, at a CAGR of 4.1%. Europe captures a 16% market share. Germany, the UK, and France serve as key contributors, supported by stringent emission regulations, robust EV infrastructure, and strong government policy alignment. The European Union’s climate targets drive rapid adoption in commercial fleets, public transport, and shared mobility programs. Companies leverage data analytics and smart charging to optimize operations and comply with environmental standards.
Asia Pacific EV Fleet Management System Market
Asia Pacific EV Fleet Management System Market grew from USD 5,264.36 million in 2018 to USD 7,867.22 million in 2024 and is anticipated to reach USD 13,435.28 million by 2032, achieving the highest CAGR of 6.5%. Asia Pacific holds a 34% market share. China dominates with large-scale fleet electrification across public transit and logistics sectors, supported by aggressive government targets and a massive domestic EV industry. Japan and South Korea see strong uptake in corporate and urban mobility fleets. Expanding charging networks and digital infrastructure underpin sustained regional growth.
Latin America EV Fleet Management System Market
Latin America EV Fleet Management System Market grew from USD 762.52 million in 2018 to USD 1,066.40 million in 2024 and is forecast to reach USD 1,463.64 million by 2032, reflecting a CAGR of 3.6%. Latin America claims a 4% market share. Brazil and Mexico drive regional activity, spurred by urban air quality initiatives and the gradual rollout of public charging infrastructure. Chile and Colombia demonstrate increasing interest in green fleet programs. Market momentum depends on policy support and growing awareness of the long-term economic benefits of electrification.
Middle East EV Fleet Management System Market
Middle East EV Fleet Management System Market grew from USD 480.37 million in 2018 to USD 620.88 million in 2024 and will likely reach USD 817.64 million by 2032, with a CAGR of 3.1%. The region accounts for a 2% market share. The United Arab Emirates leads adoption, investing in smart city initiatives and sustainable transportation solutions. Saudi Arabia follows, focusing on diversifying its economy and promoting clean mobility. Limited but growing infrastructure and government-driven pilot projects support steady market development across the Gulf states.
Africa EV Fleet Management System Market
Africa EV Fleet Management System Market grew from USD 328.29 million in 2018 to USD 505.98 million in 2024 and is estimated to reach USD 657.69 million by 2032, posting a CAGR of 2.9%. Africa maintains a 2% market share. South Africa remains at the forefront, supported by pilot EV projects and regional distribution hubs. Kenya and Egypt see emerging activity tied to public transport upgrades and renewable energy initiatives. The market faces challenges from infrastructure gaps and policy uncertainty but offers opportunities through targeted government and private sector collaboration.
Key Player Analysis
- Geotab Inc.
- Samsara
- Verizon Connect
- Motive
- Webfleet (Bridgestone)
- ChargePoint
- Driivz
- Ampcontrol
- Uffizio
- Fleet Complete
Competitive Analysis
The EV Fleet Management System Market is characterized by intense competition among leading technology providers focused on delivering advanced telematics, real-time analytics, and seamless energy management solutions. Key players include Geotab Inc., Samsara, Verizon Connect, Motive, Webfleet (Bridgestone), ChargePoint, Driivz, Ampcontrol, Uffizio, and Fleet Complete. These companies consistently invest in research and development to enhance their platforms with AI-driven predictive maintenance, dynamic route optimization, and integration capabilities for various electric vehicle models and charging networks. Companies differentiate their offerings through AI-powered predictive maintenance, dynamic route optimization, and advanced energy management features. Strategic partnerships with automotive manufacturers, energy providers, and technology firms are common, aiming to expand service portfolios and enhance customer reach. The market places a premium on platform scalability, user-friendly interfaces, and interoperability with various vehicle types and operational environments. Continuous innovation in security, compliance, and data privacy also plays a crucial role in building customer trust. Competitive intensity remains high, with organizations prioritizing research and development, strategic collaborations, and tailored solutions to meet the evolving needs of commercial, public, and logistics fleet operators worldwide.
Recent Developments
- In January 2024, MoveEV, an AI-powered EV transition platform, partnered with Geotab. The collaboration integrates MoveEV's flagship product, ReimburseEV, into the Geotab Marketplace, marking a significant step in advancing sustainable fleet management. In September 2023, Trimble partnered with transportation solution provider Next Generation Logistics to make its Engage Lane solution available to their base of shippers through the Transportation Cloud.
- In December 2023, Komatsu completed the acquisition of iVolve Holdings through its wholly-owned subsidiary in Australia. With this acquisition, the company expects to cater to iVolve’s customers in North America and Australia and target mid-tier operations.
- In December 2023, Traxall International, a sister company of Fleet Operations, completed the acquisition of Fleet Logistics Group. This acquisition was done to develop one of the largest independent mobility and fleet management providers with over 400,000 contracts under management in Europe.
- In June 2023, ZEVX, an EV systems provider, introduced OpenZEVX, a SaaS fleet management software dedicated to e-mobility solutions and battery-electric powertrains. The new launch is expected to enable fleet managers to enhance EV powertrains and charging systems to optimize EV range, performance, and driver safety.
- In June 2023, Webfleet, Bridgestone‘s fleet management software, introduced a trailer management solution, named Webfleet Trailer. The new solution is dedicated to supporting transport and logistics firms with trailer fleets operating long haul.
Market Concentration & Characteristics
The EV Fleet Management System Market exhibits moderate to high market concentration, with a handful of global technology leaders capturing significant market share through continuous innovation, strong brand presence, and comprehensive solution portfolios. It is defined by rapid adoption of cloud-based platforms, real-time telematics, and integration with advanced energy management systems. Leading companies set the standard for platform interoperability, security, and scalable architecture, appealing to both large enterprise fleets and smaller operators. The market is shaped by a demand for end-to-end fleet optimization, AI-driven analytics, and seamless connectivity with diverse vehicle models and charging networks. Emphasis on regulatory compliance, sustainability goals, and data-driven decision-making drives product differentiation and service development. It benefits from ongoing advancements in IoT, artificial intelligence, and smart charging technologies, positioning the market for sustained growth and technological leadership in fleet electrification and management.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Mode, Fleet Size, End Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of EV fleet management systems will grow as more companies transition to electric commercial vehicles.
- Governments across regions will continue offering incentives and regulations promoting EV fleet integration.
- Advancements in telematics and IoT will enhance real-time vehicle tracking and performance monitoring.
- Integration of AI and machine learning will improve predictive maintenance and route optimization.
- Fleet operators will increasingly focus on lowering operational costs through energy-efficient management systems.
- The rise of shared mobility and e-commerce will boost demand for EV fleet solutions across urban centers.
- Cloud-based platforms will gain popularity due to their scalability and remote accessibility.
- Partnerships between automakers and software providers will drive innovation in fleet intelligence.
- Growing concerns over carbon emissions will push companies to adopt cleaner, trackable fleet technologies.
- The market will witness increased demand for end-to-end platforms that offer vehicle, battery, and charging infrastructure management.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Sustained Electrification of Commercial and Public Fleets
The rapid transition of commercial and public transport fleets from internal combustion engines to electric vehicles is driving demand for specialized fleet management systems that can monitor battery health, optimize charging, and integrate with broader operations.
Government Incentives and Regulatory Pressures
Ambitious emission reduction targets, subsidies, and regulatory mandates are compelling fleet operators to adopt EV fleet management systems to ensure compliance, access incentives, and meet reporting requirements.
Advancements in Connected Vehicle Technologies
Integration of telematics, IoT, and cloud-based analytics enables real-time vehicle monitoring, predictive maintenance, and remote diagnostics, making EV fleet management systems essential for maximizing uptime and operational efficiency.
Rising Focus on Operational Efficiency and Cost Reduction
Organizations are adopting EV fleet management solutions to minimize energy consumption, reduce charging downtime, and maximize asset utilization, supporting both sustainability goals and financial performance.
Expansion of Smart Charging and Energy Management Platforms
The need for sophisticated charging management, including remote monitoring, automated billing, and integration with renewable energy, is fueling adoption of advanced EV fleet management systems that optimize energy use and reduce operational costs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the EV Fleet Management System Market?
What factors are driving the growth of the EV Fleet Management System Market?
What are the key segments within the EV Fleet Management System Market?
What are some challenges faced by the EV Fleet Management System Market?
Who are the major players in the EV Fleet Management System Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Hardware
- 1.2.2 Software
- 1.2.3 Services
- 1.3 By Fleet Size
- 1.3.1 Large Fleet
- 1.3.2 Small and Medium Fleet
- 1.4 By Deployment Mode
- 1.4.1 Cloud-Based
- 1.4.2 On-Premises
- 1.5 By End Use Industry
- 1.5.1 Transportation and Logistics
- 1.5.2 Public Transportation
- 1.5.3 Utilities
- 1.5.4 Retail
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 25,007.76 million → 2032: USD 39,257.92 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global EV Fleet Management System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global EV Fleet Management System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global EV Fleet Management System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global EV Fleet Management System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global EV Fleet Management System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global EV Fleet Management System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global EV Fleet Management System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global EV Fleet Management System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 25,007.76 million → 2032: USD 39,257.92 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global EV Fleet Management System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.7.3 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Fleet Size - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Large Fleet
- 12.4.7.2 Small and Medium Fleet
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cloud-Based
- 12.5.7.2 On-Premises
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End Use Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Transportation and Logistics
- 12.6.7.2 Public Transportation
- 12.6.7.3 Utilities
- 12.6.7.4 Retail
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global EV Fleet Management System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global EV Fleet Management System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global EV Fleet Management System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global EV Fleet Management System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Geotab Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Samsara
- 18.4 Verizon Connect
- 18.5 Motive
- 18.6 Webfleet (Bridgestone)
- 18.7 ChargePoint
- 18.8 Driivz
- 18.9 Ampcontrol
- 18.10 Uffizio
- 18.11 Fleet Complete
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

