
Market Overview
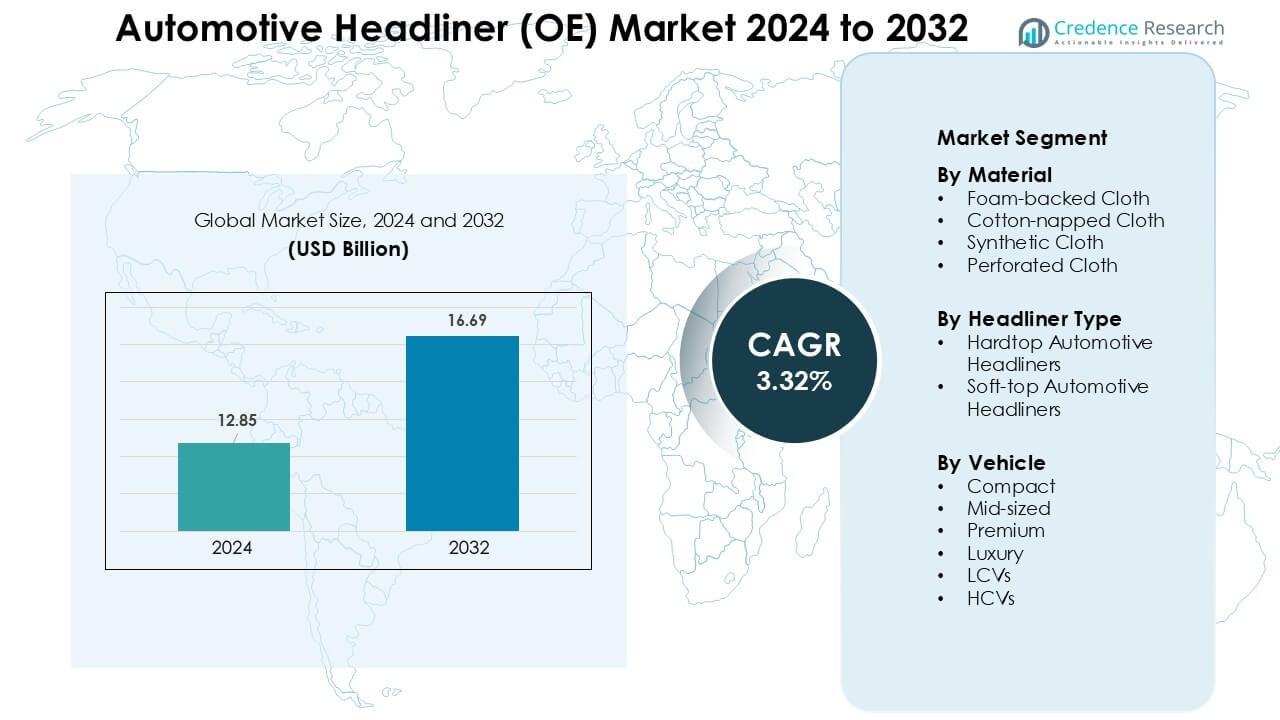
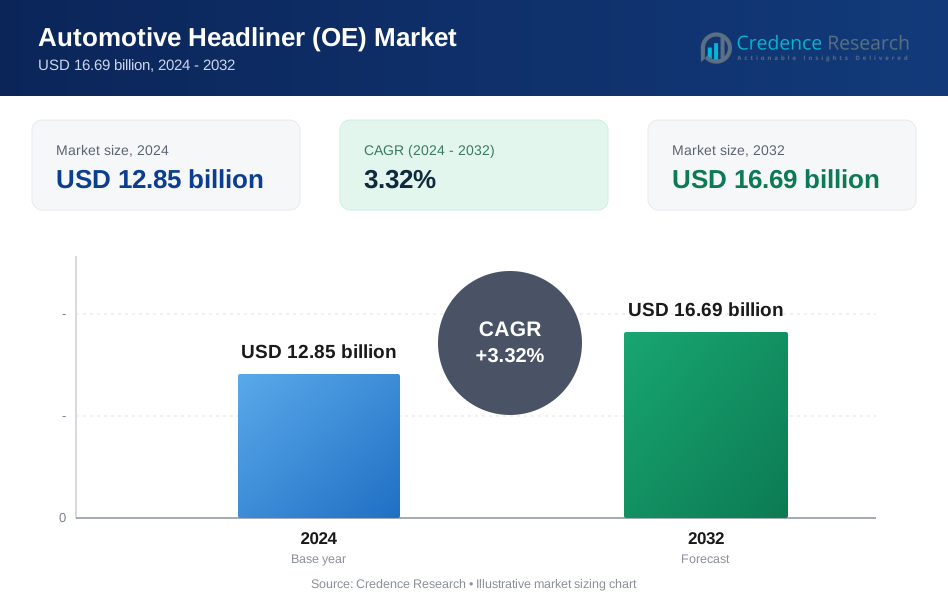
Automotive Headliner (OE) Market was valued at USD 12.85 billion in 2024 and is anticipated to reach USD 16.69 billion by 2032, growing at a CAGR of 3.32% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Anemia Treatment Drugs Market Size 2024 | USD 12.85 Billion |
| Anemia Treatment Drugs Market, CAGR | 3.32% |
| Anemia Treatment Drugs Market Size 2032 | USD 16.69 Billion |
The Automotive Headliner (OE) Market is driven by major players such as Freudenberg Performance Materials, Lear Corporation, Harodite Industries, Motus Integrated Technologies, Atlas Roofing Corporation, IAC Group, Grupo Antolin, Howa-Tramico, Adient plc, and Industrialesusd S.p.A. These companies strengthen their position through advanced lightweight materials, improved acoustic laminates, and automated manufacturing systems that support large-scale OEM programs. Strategic collaborations with global automakers help expand their regional supply networks and enhance product customization. Asia-Pacific remained the leading region in 2024 with about 39% share, supported by high vehicle production, rising EV adoption, and strong localization of headliner manufacturing.
Market Insights
- The automotive headliner (OE) market reached USD 12.85 billion in 2024 and is projected to hit USD 16.69 billion by 2032, growing at a CAGR of 3.32%.
- Rising demand for improved cabin comfort and better NVH control drives broader adoption of foam-backed cloth, which held 46% share in 2024.
- Trends include increased use of lightweight composites, integration of ambient lighting modules, and expansion of sustainable headliner materials across EV platforms.
- Leading players focus on automation, material innovation, and OEM partnerships, with companies such as Freudenberg Performance Materials and Lear advancing multi-layer acoustic systems to strengthen competitiveness.
- Asia-Pacific dominated the market with 39% share in 2024, supported by high passenger vehicle output, while compact vehicles led the segment with about 34% share due to strong adoption in China and India.
 Market Segmentation Analysis:
By Material
Foam-backed cloth dominated the material segment in 2024 with about 46% share due to strong use in passenger cars and light commercial vehicles. Automakers preferred this material because the foam layer improved cabin insulation and reduced vibration. Demand grew as OEMs upgraded interior comfort in mid-sized and compact models. Synthetic cloth gained steady traction through better durability, while cotton-napped cloth held a niche position in cost-focused trims. Perforated cloth advanced in premium cars, yet foam-backed cloth stayed ahead because it balanced cost, comfort, and acoustic control.
- For instance, Covestro a global supplier of polyurethane foam for automotive interiors reports that its PU-foam car-seat solutions are used in placements such as seats, headliners and instrument panels, and that PU foams dampen noise and vibrations while also insulating thermally and providing added comfort.
By Headliner Type
Hardtop automotive headliners led the segment in 2024 with nearly 71% share, supported by wide installation across compact, mid-sized, and SUV models. The structure offered better rigidity, thermal stability, and easy integration with wiring harnesses, airbags, and lighting modules. OEMs adopted hardtop designs to meet rising noise and vibration standards in urban markets. Soft-top headliners grew in convertibles and specialty vehicles, but adoption remained limited due to higher production cost and low global volume. Hardtop designs maintained clear leadership because they fit mainstream models.
- For instance, Industry reports indicate that the fabric segment holds the largest market share and is anticipated to maintain its dominant position. Soft-top, foam-backed cloth headliners are widely used because they offer a superior balance of aesthetics, functionality, cost, and weight reduction.
By Vehicle
Compact vehicles dominated the vehicle segment in 2024 with about 34% share, driven by high production volumes in Asia-Pacific and Europe. Buyers preferred compact models due to lower running costs and better fuel efficiency, which pushed OEMs to equip these cars with improved headliners for comfort and noise control. Mid-sized and premium vehicles grew at steady rates as brands added lightweight composites and better acoustic layers. Luxury, LCVs, and HCVs showed rising demand for durable headliners, yet compact vehicles held the lead because of their mass-market scale.
Key Growth Drivers
Rising Demand for Enhanced Cabin Comfort and NVH Performance
Automakers increased focus on better cabin insulation, which strengthened demand for advanced headliner materials. Buyers preferred vehicles with quieter interiors, stronger acoustic absorption, and improved temperature control, pushing OEMs to upgrade thermal-foam layers and composite laminates. Compact and mid-sized cars adopted improved NVH packages to match rising comfort expectations seen earlier only in premium vehicles. Urban driving conditions also raised noise exposure, leading manufacturers to integrate multi-layer headliners with better vibration damping. OEMs further invested in lighter materials that reduced vehicle weight while maintaining acoustic strength. These enhancements supported fuel efficiency goals and expansion of electrified models. The combined push for comfort, quieter cabins, and material innovation positioned upgraded headliners as a core interior component across global automotive platforms.
- For instance, Tecman a supplier of automotive acoustic insulation solutions offers multi-layer laminate headliner materials combining lightweight scrim and acoustic foam, specifically designed for electric and hybrid vehicles where high-frequency noise (from motors or inverters) becomes more pronounced.
Growth in Passenger Car Production Across Emerging Markets
Emerging markets such as India, China, Indonesia, and Mexico recorded strong passenger vehicle output, which boosted headliner demand. Compact and mid-sized segments expanded as rising incomes encouraged first-time car buyers. Governments introduced incentives for local manufacturing, prompting OEMs to increase plant capacity and launch regional models with enhanced interior fit and finish. Suppliers expanded their footprint near assembly plants to ensure faster delivery of headliner modules. Growing popularity of SUVs further supported volume, as these models required larger and more durable headliner structures. Automakers also customized materials to match climate variations across regions, increasing use of moisture-resistant and heat-stable headliners. This production growth created a sustained demand pipeline for OE headliners across multiple price segments.
- For instance, global data show that in 2024, total worldwide vehicle production reached over 92 million units.
Shift Toward Lightweight and Sustainable Interior Materials
Automotive brands accelerated the use of lightweight substrates and recycled fibers to meet emission norms and sustainability goals. Foam-backed cloth and composite laminates became popular as they reduced vehicle weight while retaining structural strength. OEMs explored natural fiber reinforcements such as hemp, jute, and kenaf for eco-friendly headliner solutions. Regulations in Europe and North America encouraged the use of recyclable materials and reduced VOC emissions inside cabins. Suppliers invested in bio-based adhesives and lighter foam formulations to support circular design. The shift toward electric vehicles further intensified the need for light, structurally stable headliners to extend driving range. This sustainability-driven transition created new opportunities for innovative material suppliers.
Key Trend & Opportunity
Integration of Electronics and Advanced Functional Modules
OEMs adopted multifunctional headliners that support embedded lighting, sensors, microphones, and wiring harnesses. Panoramic sunroof architectures and smart-cabin concepts increased the need for stronger, modular headliner shells. Voice-control systems and ambient lighting packages required precision-formed headliners with embedded mounts and heat-resistant zones. Advanced driver monitoring systems and cabin sensors expanded opportunities for integrated electronics. Automakers also explored thin-film lighting and printed circuits to reduce bulk while improving functionality. As EVs added smart interiors and connected features, suppliers shifted toward modular headliner assemblies that support plug-and-play integration. This trend positioned headliners as a functional electronics platform, not just a decorative surface.
- For instance, according to recent industry analysis, modern headliners are evolving into multifunctional structures housing lighting, microphones, antennas and airbag deployment mechanisms, enabling OEMs to integrate voice-command microphones, cabin-sensor wiring, and ambient lighting into the headliner assembly.
Expansion of EV and Premium Interior Upgrades
Electric vehicles pushed OEMs to redesign interiors with quieter cabins and improved material quality, creating new demand for premium headliners. EV platforms required better acoustic absorption to balance motor noise and road noise. Premium trims adopted suede-finish, perforated cloth, and composite-backed headliners to elevate cabin aesthetics. Automakers also invested in customizable interior themes, boosting use of stitched patterns and soft-touch materials. Growth in shared mobility services further encouraged durable and stain-resistant headliners to withstand high usage. The rise of luxury EVs in China, Europe, and the U.S. opened opportunities for suppliers offering advanced lightweight composites and eco-friendly linings.
- For instance, Autoneum’s Hybrid-Acoustics ECO+ headliner system (part of its broader interior product line) uses a multilayer PET-based composite structure that provides significant acoustic performance and can be up to 50 percent lighter than conventional solutions, contributing to a greater driving range for electric vehicles.
Localization of Headliner Manufacturing and Automation
OEMs increased localized sourcing to reduce logistics costs and meet regional manufacturing policies. Suppliers responded by setting up automated production lines for thermoforming, lamination, and cutting to improve consistency and reduce waste. High-volume models relied on robotic trimming and adhesive applications to deliver stable quality across batches. Localization also encouraged material innovation suited to local climate needs, such as humidity-resistant headliners for tropical markets. Automated plants helped shorten delivery cycles and supported just-in-time inventory for OEMs. This shift toward regionalized and automated production opened strong growth opportunities for established and new suppliers.
Key Challenge
Volatility in Raw Material Prices and Supply Chain Disruptions
Fluctuating costs of polyurethane foam, polyester fabrics, adhesives, and composite substrates created uncertainty for suppliers. Many raw materials depended on petrochemical feedstocks, which faced price swings due to geopolitical events and energy market shifts. Supply chain disruptions after global logistics delays further impacted material availability, forcing OEMs to adjust procurement plans. Tier-1 suppliers faced pressure to maintain quality while managing rising input costs, often reducing margins. Weather-related disruptions and trade restrictions also delayed shipments of specialty fabrics and resins. These factors created procurement challenges, especially for mass-production models that rely on stable material supply.
Increasing Technical Complexity and Compliance Requirements
Modern headliners needed higher precision, tighter tolerances, and compatibility with electronic systems, raising production complexity. OEMs imposed strict fire-resistance, VOC emission, and crash-safety requirements, which limited material choices. Suppliers investing in new tooling and manufacturing processes faced high capital costs. Integration of sensors and wiring required advanced engineering to prevent heat damage, vibration issues, or fitment errors. Premium and EV models demanded multi-layer structures that were harder to assemble at scale. Meeting varied global regulations increased design and testing timelines. This complexity challenged smaller suppliers and increased the need for continuous technological upgrades.
Regional Analysis
North America
North America held about 27% share in the Automotive Headliner (OE) Market in 2024, supported by strong production of SUVs, pickups, and premium vehicles. Automakers in the U.S. and Canada adopted lightweight headliners with improved acoustic control to meet rising comfort expectations. Major OEMs upgraded material specifications to support EV interiors, which boosted demand for thermally stable and vibration-resistant laminates. The region also expanded use of composite-backed and foam-backed cloth materials to enhance cabin quality. Investments in localized manufacturing and automation further strengthened supply reliability across major vehicle platforms.
Europe
Europe accounted for nearly 25% share in 2024, driven by high adoption of advanced interior materials and strict emission norms that encouraged lightweight headliner solutions. Germany, France, Italy, and the U.K. led innovation with composite laminates, eco-friendly fabrics, and low-VOC adhesives. Premium automakers expanded use of perforated and suede-like headliners to elevate cabin aesthetics in luxury models. Growth in EV production supported demand for better acoustic insulation to counter road and motor noise. Strong R&D investments and established Tier-1 suppliers helped Europe maintain its position as a leading market for high-spec headliners.
Asia-Pacific
Asia-Pacific dominated the market with about 39% share in 2024, supported by large-scale vehicle production in China, India, Japan, and South Korea. High demand for compact and mid-sized cars boosted installation of foam-backed cloth headliners due to cost efficiency and improved cabin comfort. Regional OEMs expanded facilities and adopted automated thermoforming technologies to meet rising export demand. Growth in electric vehicles and premium trims accelerated use of advanced materials and multi-layer acoustic headliners. Rising middle-class adoption and strong localization policies further strengthened Asia-Pacific as the fastest-growing region.
Latin America
Latin America captured around 6% share in 2024, supported by moderate growth in vehicle production across Brazil, Mexico, and Argentina. Automakers focused on cost-effective headliner materials such as synthetic and foam-backed cloth to serve compact and mid-sized models. Demand grew as OEMs introduced refreshed interiors with better NVH performance. Local suppliers expanded capacity to shorten delivery cycles and reduce import dependence. Economic fluctuations limited high-end material adoption, yet steady expansion in regional assembly plants supported ongoing headliner demand.
Middle East & Africa
The Middle East & Africa region held nearly 3% share in 2024, driven by rising vehicle assembly operations in South Africa, Morocco, and emerging Gulf markets. SUVs and light commercial vehicles dominated demand, encouraging the use of durable, heat-resistant headliner materials that withstand extreme temperatures. Governments promoted local manufacturing, which encouraged OEMs to invest in regional sourcing. Premium vehicle sales in GCC countries boosted adoption of high-quality headliners with enhanced insulation. While market size remained smaller, gradual expansion in localized production and rising mobility needs supported stable growth.
Market Segmentations:
By Material
- Foam-backed Cloth
- Cotton-napped Cloth
- Synthetic Cloth
- Perforated Cloth
By Headliner Type
- Hardtop Automotive Headliners
- Soft-top Automotive Headliners
By Vehicle
- Compact
- Mid-sized
- Premium
- Luxury
- LCVs
- HCVs
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Automotive Headliner (OE) Market is shaped by leading players such as Freudenberg Performance Materials, Lear Corporation, Harodite Industries, Motus Integrated Technologies, Atlas Roofing Corporation, IAC Group, Grupo Antolin, Howa-Tramico, Adient plc, and Industrialesusd S.p.A. These companies expanded material portfolios to include lightweight composites, foam-backed laminates, and eco-friendly fabrics that support modern interior designs. Suppliers invested in automated thermoforming, robotic trimming, and precise lamination systems to meet OEM requirements for consistent fitment and improved NVH performance. Partnerships with global automakers strengthened supply stability, while growth in EVs encouraged development of advanced acoustic and heat-resistant headliners. Many players enhanced regional manufacturing footprints to reduce logistics cost and support just-in-time delivery models. Continuous innovation in recyclable substrates and multi-layer structures helped companies maintain competitiveness and align with global sustainability goals.
Key Player Analysis
- Freudenberg Performance Materials
- Lear Corporation
- Harodite Industries
- Motus Integrated Technologies
- Atlas Roofing Corporation
- IAC Group
- Grupo Antolin
- Howa-Tramico
- Adient plc
- Industrialesusd S.p.A.
Recent Developments
- In 2025, Howa-Tramico, with Fibroline, moved a new solvent-free, dry-impregnated car headliner into full industrial production, targeting lighter and more recyclable OEM roof systems.
- In June 2025, Faway Adient adopted Lectra’s VectorAutomotive iP9 digital cutting solution to boost capacity and reduce costs for seating and interior trim manufacturing, supporting Adient’s supply of lightweight headliner and interior modules to global OEMs.
- In May 2025, Lear Corporation Reported Q1 2025 results and reiterated investments in automation, footprint optimisation and new business wins that support its seating and E-Systems businesses (moves that backstop its thermal-comfort and interior component capabilities closely related to headliner/overhead systems).
Report Coverage
The research report offers an in-depth analysis based on Material, Headliner Type, Vehicle and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will shift toward lighter multi-layer materials to support EV efficiency targets.
- OEMs will increase adoption of recycled and bio-based fabrics to meet sustainability goals.
- Smart headliners with embedded lighting, sensors, and microphones will gain wider use.
- Automation in thermoforming and trimming will expand to improve quality and reduce waste.
- Premium vehicles will drive demand for suede-like and advanced acoustic headliners.
- Regional manufacturing footprints will grow as OEMs localize sourcing for faster delivery.
- Improved NVH performance requirements will push suppliers to develop higher-density foam layers.
- Headliners designed for panoramic roofs and large glass areas will become more common.
- Material innovations will target heat resistance and durability for extreme climate markets.
- Collaboration between OEMs and Tier-1 suppliers will strengthen for modular headliner integration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enhanced Cabin Comfort and NVH Performance
Automakers are prioritizing improved cabin insulation and noise reduction, driving demand for advanced headliner materials that offer better acoustic absorption and thermal control. This trend is especially strong in compact and mid-sized vehicles, where consumers increasingly expect premium comfort features.
Growth in Passenger Car Production in Emerging Markets
Rapid expansion of vehicle manufacturing in countries like China, India, and Mexico is fueling demand for OE headliners, as OEMs equip high-volume compact and mid-sized models with upgraded interior components to attract first-time buyers and meet local preferences.
Shift Toward Lightweight and Sustainable Materials
Stricter emission regulations and sustainability goals are pushing OEMs to adopt lightweight composites and recycled fibers in headliner production. This not only helps reduce vehicle weight for better fuel efficiency and EV range, but also aligns with global trends toward eco-friendly automotive interiors.
Integration of Electronics and Functional Modules
The evolution of smart cabins and connected vehicles is increasing the need for headliners that can house embedded lighting, sensors, microphones, and wiring. This integration transforms headliners from simple trim pieces into multifunctional modules, expanding their value and complexity.
Localization and Automation of Manufacturing
OEMs and suppliers are investing in regionalized, automated production facilities to reduce logistics costs, improve supply chain resilience, and meet local content requirements. Automation in thermoforming and trimming processes also enhances quality and supports just-in-time delivery for large-scale OEM programs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Automotive Headliner (OE) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Automotive Headliner (OE) Market projected to grow between 2024 and 2032?
Which Automotive Headliner (OE) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of Automotive Headliner (OE) Market?
Who are the leading companies in Automotive Headliner (OE) Market?
Which region commanded the largest share of Automotive Headliner (OE) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vehicle
- 1.2.1 Compact
- 1.2.2 Mid-sized
- 1.2.3 Premium
- 1.2.4 Luxury
- 1.2.5 LCVs
- 1.2.6 HCVs
- 1.3 By Material
- 1.3.1 Foam-backed Cloth
- 1.3.2 Cotton-napped Cloth
- 1.3.3 Synthetic Cloth
- 1.3.4 Perforated Cloth
- 1.4 By Headliner Type
- 1.4.1 Hardtop Automotive Headliners
- 1.4.2 Soft-top Automotive Headliners
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12.85 billion → 2032: USD 16.69 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Headliner (OE) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Headliner (OE) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Headliner (OE) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Headliner (OE) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Headliner (OE) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Headliner (OE) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Headliner (OE) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Headliner (OE) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12.85 billion → 2032: USD 16.69 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Headliner (OE) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vehicle - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Compact
- 12.3.7.2 Mid-sized
- 12.3.7.3 Premium
- 12.3.7.4 Luxury
- 12.3.7.5 LCVs
- 12.3.7.6 HCVs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Foam-backed Cloth
- 12.4.7.2 Cotton-napped Cloth
- 12.4.7.3 Synthetic Cloth
- 12.4.7.4 Perforated Cloth
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Headliner Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hardtop Automotive Headliners
- 12.5.7.2 Soft-top Automotive Headliners
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Headliner (OE) Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Headliner (OE) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Headliner (OE) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Freudenberg Performance Materials
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Lear Corporation
- 17.4 Harodite Industries
- 17.5 Motus Integrated Technologies
- 17.6 Atlas Roofing Corporation
- 17.7 IAC Group
- 17.8 Grupo Antolin
- 17.9 Howa-Tramico
- 17.10 Adient plc
- 17.11 Industrialesusd S.p.A.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

