
Market Overview:
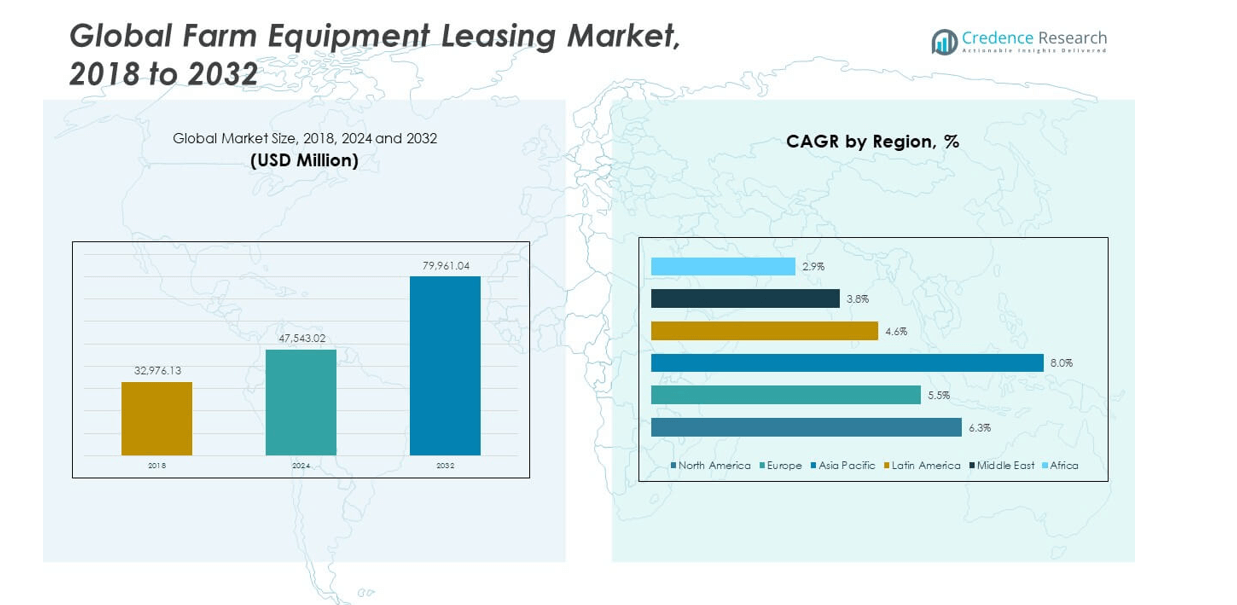
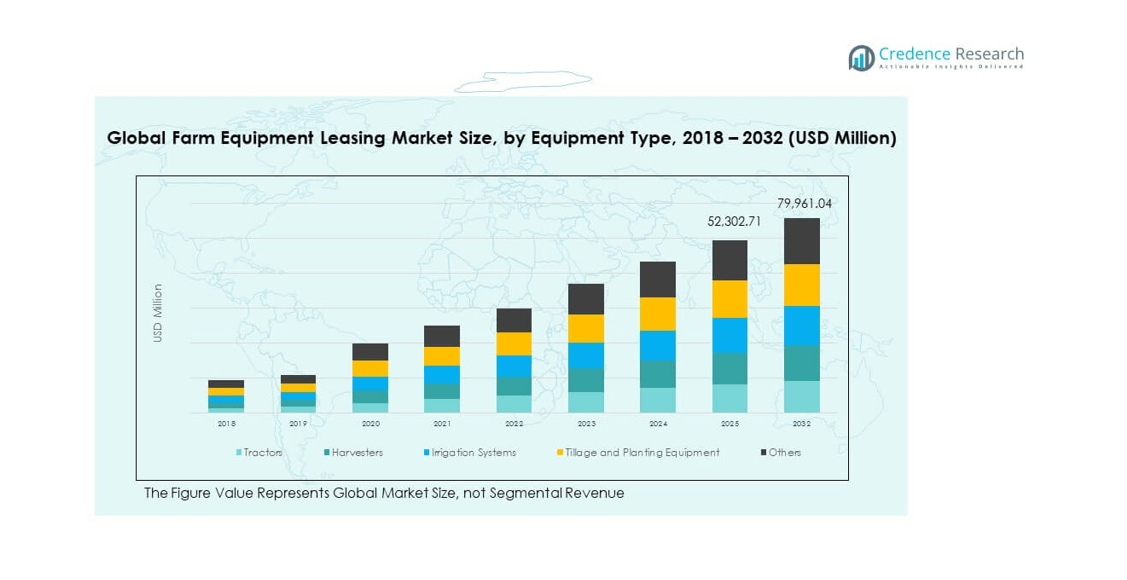
The Global Farm Equipment Leasing Market size was valued at USD 32,976.13 million in 2018 to USD 47,543.02 million in 2024 and is anticipated to reach USD 79,961.04 million by 2032, at a CAGR of 6.25% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Farm Equipment Leasing Market Size 2024 | USD 47,543.02 million |
| Farm Equipment Leasing Market, CAGR | 6.25% |
| Farm Equipment Leasing MarketSize 2032 | USD 79,961.04 million |
'
The market growth is driven by rising equipment costs, growing adoption of precision agriculture, and limited capital availability among small and mid-sized farmers. Leasing solutions enable farmers to access modern machinery such as tractors, harvesters, and irrigation systems without high upfront investments. Flexible lease terms and technological upgrades also support efficient farm operations and improve productivity, especially in mechanization-driven economies.
Regionally, North America and Europe lead due to strong leasing infrastructure, advanced farming technology, and established agricultural financing systems. Asia-Pacific is emerging rapidly, fueled by increasing mechanization in countries such as India and China and growing government initiatives supporting rural credit access. Latin America and Africa show steady growth with expanding agricultural modernization programs and rising demand for cost-effective leasing models.
Market Insights:
- The Global Farm Equipment Leasing Market was valued at USD 32,976.13 million in 2018, reached USD 47,543.02 million in 2024, and is projected to hit USD 79,961.04 million by 2032, growing at a CAGR of 6.25%.
- North America leads the market with about 9% share, driven by advanced mechanization and strong financing networks. Europe follows with 25.7%, supported by modernization programs, while Asia Pacific holds 23%, fueled by growing agricultural mechanization.
- Asia Pacific is the fastest-growing region, expanding due to rising demand for affordable leasing options, government support for precision farming, and increasing awareness among small and medium-scale farmers.
- Among equipment types, tractors account for approximately 38% of the total market share, reflecting their critical role in global agricultural mechanization and operational efficiency.
- Harvesters and irrigation systems together represent nearly 34% of the market, supported by demand for productivity-enhancing equipment and efficient water management solutions in developing economies.
Market Drivers:
Rising Demand for Cost-Efficient Access to Advanced Agricultural Machinery
The Global Farm Equipment Leasing Market benefits from the growing need for affordable machinery access among small and mid-sized farmers. High upfront costs of tractors, harvesters, and precision tools encourage leasing as a preferred financing option. It helps farmers upgrade to modern equipment without financial strain. Leasing also supports operational flexibility by enabling seasonal usage. The growing shift toward technology-driven agriculture increases leasing demand. Farmers are choosing short-term and renewable lease options to stay updated with evolving technologies. The presence of multiple leasing models, including operational and financial leases, further widens adoption. Continuous support from financial institutions strengthens leasing penetration across rural regions.
- For instance, CNH Industrial's 2024 Sustainability Report notes a significant year-over-year reduction in Scope 1 and Scope 2 emissions and an increase in renewable electricity usage in its facilities. The report highlights the use of environmentally minded technologies, such as alternative fuels and precision agriculture systems, to improve customer operations. The company also continues to offer financial services, including leasing options, to its customers.
Government Initiatives Supporting Agricultural Mechanization and Financing
Several governments promote leasing programs to enhance rural productivity and mechanization. Subsidized interest rates and credit guarantees encourage farmers to use lease-based machinery. The Global Farm Equipment Leasing Market gains from public-private partnerships fostering equipment accessibility. National rural credit agencies and cooperative banks extend leasing options to bridge funding gaps. It creates strong demand in developing economies where smallholders dominate. Public awareness programs educate farmers about the financial and operational advantages of leasing. Governments also incentivize leasing companies with tax benefits and relaxed lending norms. These measures collectively strengthen the agricultural equipment leasing ecosystem.
- For instance, Mahindra reports record tractor sales in India for rural mechanization, supported by NABARD’s credit plans and collaborative government schemes as documented in official NABARD and Mahindra Group reports for 2024.
Rising Mechanization Rate and Growing Demand for Sustainable Farming Solutions
The adoption of mechanized farming practices drives the market significantly. Farmers prefer leasing energy-efficient and sustainable machines to reduce operational costs. The Global Farm Equipment Leasing Market aligns with sustainability goals through the promotion of low-emission and precision farming tools. It supports optimized resource use while maintaining productivity levels. Leasing enables easier transition to renewable-powered machines like solar irrigation pumps and electric tractors. Growing environmental regulations push for cleaner agricultural machinery adoption. Equipment lessors also introduce green leasing schemes to attract eco-conscious users. The push toward sustainable farming creates long-term market resilience.
Digital Transformation and Integration of Data-Driven Leasing Models
The introduction of digital tools simplifies the leasing process and improves transparency. Online platforms help farmers compare lease rates, terms, and machinery options. The Global Farm Equipment Leasing Market integrates digital analytics to assess usage and creditworthiness efficiently. It accelerates approval processes and enhances customer experience. Smart contracts and blockchain-based leasing solutions ensure secure and transparent transactions. IoT-enabled equipment monitoring helps lessors track asset performance and maintenance schedules. It reduces default risks and promotes better equipment utilization. The digital ecosystem around leasing creates efficiency for both farmers and financial institutions.
Market Trends:
Growing Adoption of Short-Term and Seasonal Leasing Contracts
Farmers are increasingly opting for flexible leasing contracts that align with crop cycles. The Global Farm Equipment Leasing Market witnesses rising interest in short-term rentals due to uncertain weather and changing planting patterns. Seasonal leasing offers cost advantages by reducing idle equipment costs. It allows farmers to use machinery only during peak demand. Leasing companies respond by customizing plans for crop-specific operations. Shorter contracts also attract smallholders hesitant to commit long-term. It ensures efficient capital utilization and greater accessibility for diverse farm sizes. Such flexibility sustains consistent leasing activity year-round.
- For instance, John Deere Financial’s 2024 reports confirm declining sales and revenues, with worldwide net sales and revenues decreasing 16% for the full year due to softening demand in agricultural markets. The company continues to offer rental and leasing programs, including for combines and tractors, to support farmers during challenging market cycles.
Emergence of Equipment Sharing and Cooperative Leasing Platforms
Shared leasing platforms enable multiple farmers to access high-value equipment affordably. The Global Farm Equipment Leasing Market experiences strong growth in cooperative and group-based leasing. It reduces financial burden and ensures optimal use of machinery. Technology-driven platforms match equipment supply with regional farming needs. Farmers share maintenance and fuel costs, improving operational efficiency. This model supports collective ownership without heavy investment. It strengthens rural collaboration and sustainability. Leasing companies are investing in such models to expand reach in underpenetrated markets.
- For instance, Mahindra Trringo has expanded its digital equipment sharing platforms in India, allowing farmers to access tractors and harvesters on-demand through regionally managed hubs, as documented by Mahindra’s official releases and coverage in the Hindu Business Line.
Integration of Telematics and Predictive Maintenance in Leased Equipment
Telematics is transforming how leased farm equipment is managed and maintained. The Global Farm Equipment Leasing Market integrates GPS and sensor technologies to monitor usage and performance. It helps lessors plan preventive maintenance, reducing downtime and repair costs. Real-time tracking enhances operational safety and efficiency. Data-driven insights enable better asset management and contract optimization. Farmers benefit from reduced maintenance liability and improved reliability. Leasing companies use analytics to optimize equipment allocation. The trend ensures long-term trust and efficiency between farmers and service providers.
Expansion of Customized Leasing Packages and Subscription-Based Models
Leasing companies are creating tailored packages that cater to diverse farm sizes and operational needs. The Global Farm Equipment Leasing Market embraces subscription-based models where farmers pay monthly fees for bundled equipment and maintenance services. It simplifies budgeting and ensures regular upgrades. Subscription models attract younger farmers seeking financial flexibility. Customized contracts also include insurance and spare part services, improving convenience. It strengthens loyalty among customers seeking reliable long-term partnerships. This approach reshapes the equipment leasing ecosystem toward continuous engagement. Leasing firms that offer adaptable plans gain a competitive edge in dynamic agricultural markets.
Market Challenges Analysis:
High Default Risks and Limited Awareness Among Smallholder Farmers
The Global Farm Equipment Leasing Market faces challenges due to payment defaults and limited financial literacy among rural users. Small farmers often lack credit history, making risk assessment difficult for lessors. It restricts access to advanced equipment for many users. Awareness of leasing benefits remains low in developing regions, leading to underutilization. Poor understanding of contract terms sometimes results in disputes or misuse of machinery. Leasing companies invest in training programs and local partnerships to overcome trust gaps. Insurance-linked leasing models are emerging to mitigate credit risk. Expanding education and transparent agreements are vital to sustain adoption growth.
Regulatory Barriers and Complex Financial Compliance Structures
Varying tax laws and lease accounting standards across countries create operational hurdles for leasing firms. The Global Farm Equipment Leasing Market must navigate inconsistent regulatory frameworks that delay cross-border expansion. Financial compliance requirements increase administrative costs for small lessors. It also limits the scalability of innovative leasing products. Complex documentation discourages farmers unfamiliar with financial systems. Policymakers are working toward unified leasing guidelines to simplify approvals. Strengthening rural financial infrastructure can reduce legal complexity. Harmonized regulations would enable faster market growth and greater participation by new entrants.
Market Opportunities:
Growing Penetration of Smart and Autonomous Farming Equipment in Lease Portfolios
The Global Farm Equipment Leasing Market has strong potential through the integration of smart and autonomous machinery. Farmers seek access to advanced technology like GPS-guided tractors, drones, and precision irrigation systems. Leasing companies can expand offerings to include connected equipment with performance analytics. It encourages faster technology diffusion without high ownership costs. Manufacturers collaborate with lessors to promote automation-driven leasing programs. Demand for digitally controlled tools supports better efficiency and sustainability. This trend enables modernization across both small and large farming operations.
Rising Interest from Agritech Startups and Financial Institutions in Rural Leasing Solutions
The growing participation of agritech firms creates new leasing opportunities for digital equipment management and financing. The Global Farm Equipment Leasing Market benefits from banks and microfinance institutions entering rural leasing partnerships. It increases credit access for farmers and diversifies financial channels. Technology platforms simplify contract tracking, payments, and equipment scheduling. The inclusion of fintech-driven solutions ensures higher transparency and customer engagement. Expanding rural digitization enhances adoption among unbanked farmers. This collaboration strengthens the link between technology, finance, and agriculture-driven leasing growth.
Market Segmentation Analysis:
By Equipment Type
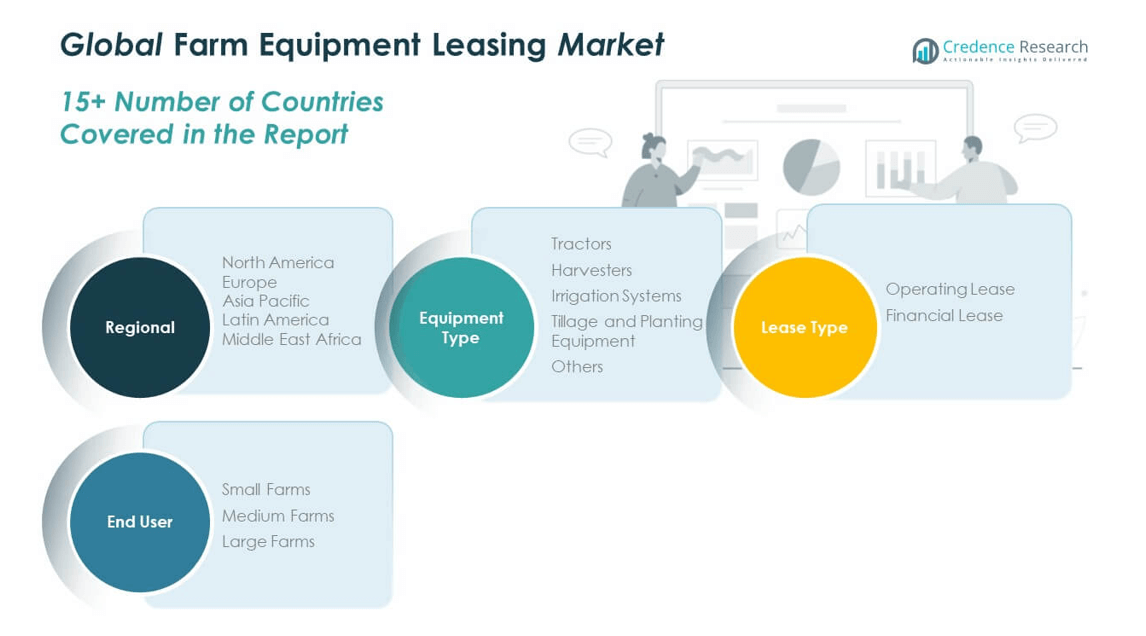
The Global Farm Equipment Leasing Market is segmented by equipment type into tractors, harvesters, irrigation systems, tillage and planting equipment, and others. Tractors hold the largest share due to their essential role in field preparation, transport, and multi-season operations. Harvesters follow, driven by growing demand for automation and labor efficiency. Irrigation systems gain traction in water-scarce regions seeking productivity improvement. Tillage and planting equipment support mechanized cultivation, promoting precision seeding and soil management. Other equipment types, including sprayers and loaders, contribute to operational diversity across farm sizes and applications.
- For instance, Fendt was confirmed to be the leader in tractor registrations in Germany in 2023, while its parent company, AGCO, documented increased adoption of its advanced tillage and harvesting equipment across Europe.
By Lease Type
The market includes operating and financial lease categories. Operating leases dominate due to flexibility, lower upfront costs, and short-term usage suitability for seasonal farming. It allows farmers to upgrade machinery regularly without long-term liabilities. Financial leases appeal to medium and large farms aiming for ownership after lease completion. Growing awareness of tax and depreciation benefits supports both models, encouraging wider adoption across developed and emerging economies.
- For instance, Kubota’s expansion in Asia and Africa is documented through increased participation in flexible lease programs, verified by recent industry news and company reports.
By End User
End users are divided into small, medium, and large farms. Small farms prefer leasing for cost-effective access to advanced equipment. Medium farms leverage leasing to scale operations while managing capital expenditure. Large farms adopt structured leasing contracts for fleet optimization and technology upgrades. The expanding mechanization trend across all segments drives consistent leasing growth, enhancing agricultural efficiency and sustainability.
Segmentation:
By Equipment Type
- Tractors
- Harvesters
- Irrigation Systems
- Tillage and Planting Equipment
- Others
By Lease Type
- Operating Lease
- Financial Lease
By End User
- Small Farms
- Medium Farms
- Large Farms
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Farm Equipment Leasing Market size was valued at USD 14,586.85 million in 2018 to USD 20,814.84 million in 2024 and is anticipated to reach USD 35,103.74 million by 2032, at a CAGR of 6.3% during the forecast period. North America holds around 36.2% of the global market share, driven by advanced agricultural infrastructure and strong equipment financing networks. The United States leads the region due to large-scale mechanized farming and high adoption of precision technologies. Canada and Mexico contribute through expanding agricultural modernization and flexible leasing regulations. It benefits from mature leasing institutions offering tailored financing packages to farmers. The trend of replacing old machinery with energy-efficient models strengthens demand. Agritech innovations and sustainability-focused leasing programs further drive growth. The presence of key equipment manufacturers and financiers sustains steady expansion in this region.
Europe
The Europe Global Farm Equipment Leasing Market size was valued at USD 9,442.57 million in 2018 to USD 13,127.50 million in 2024 and is anticipated to reach USD 20,799.33 million by 2032, at a CAGR of 5.5% during the forecast period. Europe accounts for nearly 25.9% of the global share, supported by advanced agricultural policies and government subsidies promoting leasing. Germany, France, and the U.K. are major contributors due to high mechanization and structured leasing markets. The European Union’s focus on sustainable farming equipment encourages eco-friendly leasing programs. It benefits from strict emission standards that drive replacement of older machinery. Leasing firms collaborate with local banks to simplify financing access for small and mid-sized farms. Precision agriculture and renewable-powered equipment adoption create new opportunities. Stable interest rates and robust rural financial infrastructure ensure market resilience.
Asia Pacific
The Asia Pacific Global Farm Equipment Leasing Market size was valued at USD 6,089.70 million in 2018 to USD 9,546.88 million in 2024 and is anticipated to reach USD 18,266.70 million by 2032, at a CAGR of 8.0% during the forecast period. Asia Pacific captures about 23% of the global market share, driven by rapid agricultural mechanization in emerging economies. China and India dominate due to extensive rural populations and government-backed leasing initiatives. Japan and South Korea contribute through advanced precision farming tools and automation adoption. It gains momentum from agritech startups and micro-leasing platforms improving accessibility. The region’s expanding food demand and labor shortages further boost adoption. Growing preference for operating leases among smallholders accelerates modernization. The combination of local manufacturing and financial digitization strengthens long-term prospects.
Latin America
The Latin America Global Farm Equipment Leasing Market size was valued at USD 1,524.62 million in 2018 to USD 2,170.19 million in 2024 and is anticipated to reach USD 3,221.37 million by 2032, at a CAGR of 4.6% during the forecast period. Latin America represents about 7.6% of the total market, led by Brazil and Argentina. Both nations focus on enhancing productivity through mechanization and flexible equipment financing. It benefits from strong agribusiness expansion in soybeans, sugarcane, and maize cultivation. Regional governments support rural financing to reduce ownership barriers. Local banks and leasing companies are extending low-interest programs for mid-sized farms. The market also witnesses adoption of precision machinery and irrigation systems to improve yield efficiency. Increasing partnerships between OEMs and financial institutions enhance equipment availability. The regional market outlook remains positive due to export-driven agriculture.
Middle East
The Middle East Global Farm Equipment Leasing Market size was valued at USD 868.76 million in 2018 to USD 1,138.11 million in 2024 and is anticipated to reach USD 1,594.30 million by 2032, at a CAGR of 3.8% during the forecast period. The region holds around 4% of the global share, supported by growing investment in controlled-environment agriculture and water-efficient systems. GCC countries lead with large-scale farm modernization projects and leasing incentives. It benefits from government initiatives focused on food security and sustainability. The leasing model helps farmers adopt irrigation and greenhouse technologies with reduced capital risk. Regional banks are partnering with agricultural machinery suppliers to launch customized financial products. The rise of agri-tech ventures further supports mechanized leasing adoption. Increasing awareness of renewable-powered farm machinery drives steady leasing demand.
Africa
The Africa Global Farm Equipment Leasing Market size was valued at USD 463.64 million in 2018 to USD 745.51 million in 2024 and is anticipated to reach USD 975.59 million by 2032, at a CAGR of 2.9% during the forecast period. Africa accounts for nearly 3.3% of the global market share, with growth led by South Africa, Nigeria, and Egypt. It gains traction through rural development programs promoting agricultural mechanization. Limited access to capital and low awareness of leasing benefits remain key barriers. International organizations and NGOs support leasing frameworks for smallholders. The expansion of micro-leasing and digital payment solutions improves accessibility. Increasing partnerships between equipment manufacturers and local financiers enhance adoption rates. Regional governments are emphasizing farm productivity to strengthen food security. Steady urbanization and agri-innovation projects sustain market growth prospects.
Key Player Analysis:
- John Deere (Deere & Company)
- Kubota Corporation
- CNH Industrial N.V.
- AGCO Corporation
- Mahindra & Mahindra Limited
- CLAAS KGaA mbH
- TAFE (Amalgamations Group)
- Buhler Industries Inc.
- Horsch Maschinen GmbH
- Yanmar Holdings Co., Ltd.
Competitive Analysis:
The Global Farm Equipment Leasing Market features a competitive landscape with established manufacturers, financial institutions, and specialized leasing providers. Leading companies such as John Deere, CNH Industrial, Kubota, and AGCO Corporation dominate through integrated leasing programs and tailored financial solutions. It focuses on expanding accessibility for small and medium farms by offering flexible lease terms and advanced machinery. Local players strengthen regional competitiveness with crop-specific leasing options. Strategic collaborations between equipment producers and banks enhance credit availability. The competition emphasizes technology integration, fleet management, and customer service efficiency. Continuous product upgrades and digital financing platforms shape differentiation strategies across the market.
Recent Developments:
- In 2025, John Deere unveiled its 2025 new equipment lineup, which includes the 6M and 6R series tractors, now equipped with enhanced engine options and new front hitch and PTO features. Notably, the new 9RX Series tractors offer improved tracks, cab comfort, and high-horsepower models, catering to modern farm demands with advanced precision agriculture integrations such as AutoTrac™ and JDLink™.
- In June 2025, Kubota Corporation announced a strategic partnership with Agtonomy to advance autonomous operations on its M5N tractors. This move focuses on commercializing automation capabilities, enabling practical autonomy for specialty crop growers, and is set to accelerate Kubota's technological presence in global agricultural equipment markets.
Report Coverage:
The research report offers an in-depth analysis based on Equipment Type, Lease Type, and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Leasing adoption will rise among small farms due to flexible financing options.
- Digital leasing platforms will expand accessibility across emerging markets.
- Integration of IoT and AI will improve equipment performance tracking.
- Sustainability-focused leasing models will attract eco-conscious farmers.
- Regional partnerships will strengthen supply chain and service networks.
- Subscription-based leasing will gain traction for precision farming equipment.
- OEM-led leasing programs will dominate with bundled maintenance services.
- Technological modernization will enhance productivity and reduce downtime.
- Government-backed initiatives will promote inclusive agricultural financing.
- Expansion into rural and semi-urban regions will sustain long-term growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Farm Equipment Leasing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Farm Equipment Leasing Market projected to grow between 2025 and 2032?
Which Global Farm Equipment Leasing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Farm Equipment Leasing Market?
Who are the leading companies in the Global Farm Equipment Leasing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 47,543.02 million → 2032: USD 79,961.04 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Farm Equipment Leasing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Farm Equipment Leasing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Farm Equipment Leasing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Farm Equipment Leasing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Farm Equipment Leasing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Farm Equipment Leasing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Farm Equipment Leasing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Farm Equipment Leasing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 47,543.02 million → 2032: USD 79,961.04 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Farm Equipment Leasing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Farm Equipment Leasing Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Farm Equipment Leasing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Farm Equipment Leasing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

