
Market Overview
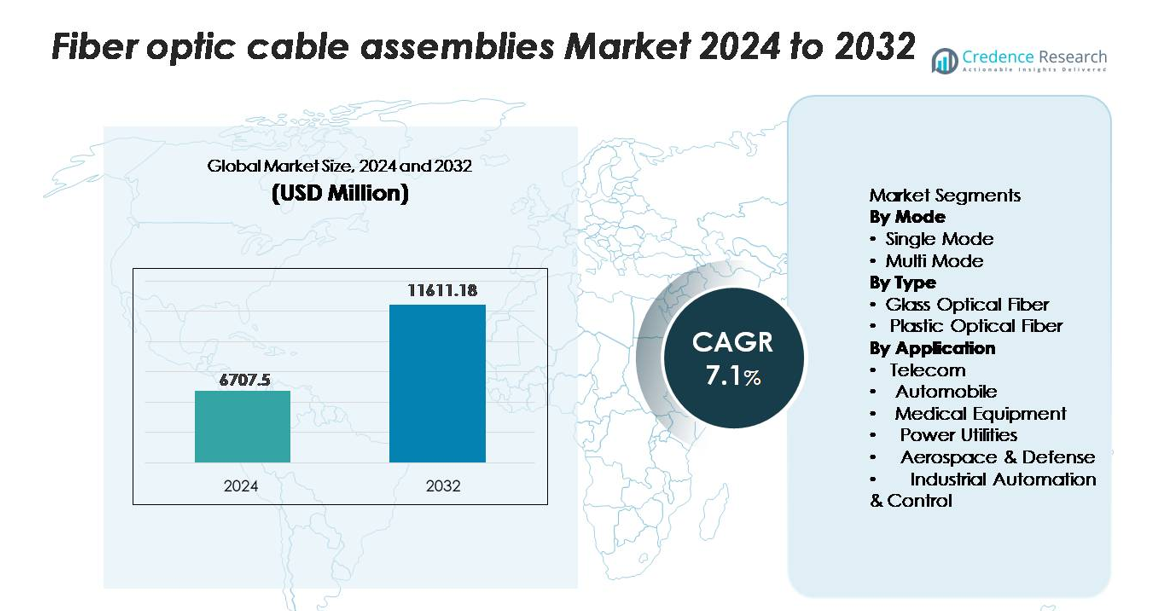
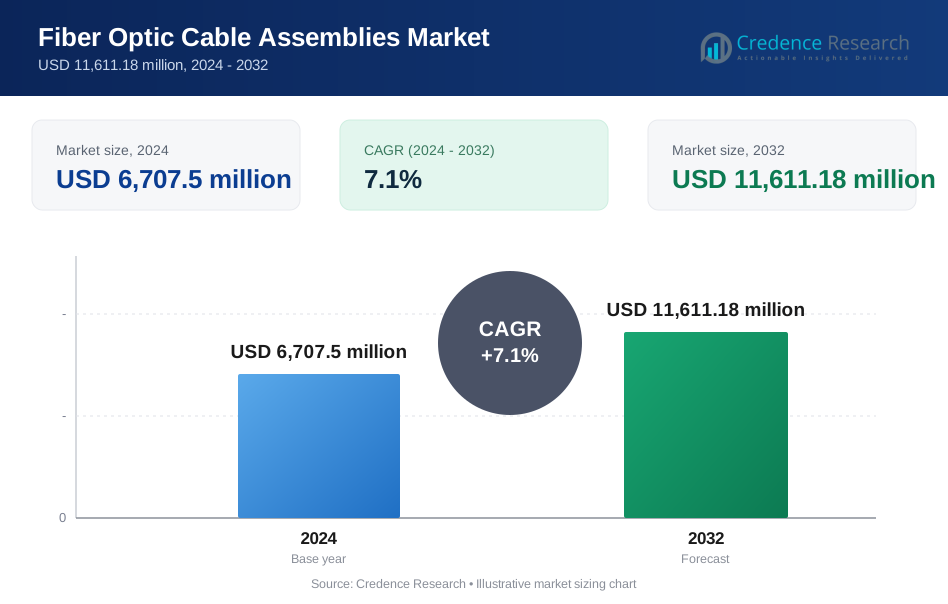
The fiber optic cable assemblies market was valued at USD 6,707.5 million in 2024 and is anticipated to reach USD 11,611.18 million by 2032, expanding at a CAGR of 7.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fiber Optic Cable Assemblies Market Size 2024 | USD 6,707.5 million |
| Fiber Optic Cable Assemblies Market, CAGR | 7.1% |
| Fiber Optic Cable Assemblies Market Size 2032 | USD 11,611.18 million |
The fiber optic cable assemblies market is led by major players such as Corning Incorporated, Prysmian Group, Fujikura Ltd., CommScope, Nexans, OFS, and Yangtze Optical Fibre and Cable (YOFC), each leveraging advanced optical technologies and strong global manufacturing capabilities. These companies dominate high-performance segments including single-mode assemblies, MPO/MTP high-density solutions, and ruggedized industrial fiber systems. Asia-Pacific holds the leading regional share at approximately 36%, driven by large-scale telecom upgrades, extensive 5G deployments, and strong domestic production capacity. North America and Europe follow, supported by data center expansion and accelerating FTTH rollouts.
Market Insights
- The fiber optic cable assemblies market reached USD 6,707.5 million in 2024 and is projected to hit USD 11,611.18 million by 2032, expanding at a CAGR of 7.1%.
- Strong demand for high-speed connectivity, 5G backhaul, and FTTH deployments drives rapid adoption, with single-mode fibers holding the dominant segment share due to superior long-distance performance.
- Market trends highlight increasing use of high-density MPO/MTP assemblies and rising adoption in data centers, industrial automation, and automotive electronics, supported by advances in bend-insensitive and low-loss fiber technologies.
- Competition intensifies among leaders such as Corning, Prysmian, Fujikura, CommScope, Nexans, and YOFC, while restraints include high installation costs and the need for skilled fiber technicians.
- Regionally, Asia-Pacific leads with 36% share, followed by North America at 32% and Europe at 27%, driven by telecom expansion, hyperscale data center growth, and accelerated fiber rollout initiatives worldwide.
Market Segmentation Analysis:
By Mode Single-mode fiber optic cable assemblies dominate the market, holding the largest share due to their ability to support significantly higher bandwidth and longer transmission distances with minimal signal loss. Telecom operators, hyperscale data centers, and 5G infrastructure providers increasingly favor single-mode solutions for high-capacity backbone networks and metro aggregation systems. Multi-mode fibers continue to serve short-distance applications such as enterprise LANs and data centers, but rising demand for ultra-long-reach connectivity and improved spectral efficiency keeps single-mode fibers in a leading position.
- For instance, Corning’s SMF-28® ULL (Ultra-Low-Loss) single-mode fiber delivers attenuation as low as 0.16 dB/km at 1550 nm, enabling ultra-long-haul transmission with lower amplifier spacing.
By Type (Glass Optical Fiber, Plastic Optical Fiber) Glass optical fiber leads the segment with the highest market share, driven by its superior transmission quality, low attenuation, and ability to handle high-speed data rates essential for telecom, cloud computing, and industrial automation. Its durability and performance in demanding environments make it the preferred choice for critical communication infrastructure. Plastic optical fiber grows steadily in consumer electronics and short-distance automotive applications due to its flexibility, ease of installation, and lower cost, but glass fiber remains dominant because of its unmatched optical performance across long-distance and high-bandwidth networks.
- For instance, Corning’s SMF-28® ULL glass fiber delivers attenuation as low as 0.16 dB/km at 1550 nm and supports coherent transmission using 100–800 Gb/s wavelengths in long-haul and metro networks.
By Application (Telecom, Automobile, Medical Equipment, Power Utilities, Aerospace & Defense, Industrial Automation & Control) Telecom emerges as the dominant application segment, accounting for the largest share owing to extensive investments in fiber-to-the-home (FTTH), 5G backhaul, and high-capacity
Key Growth Drivers
Rapid Expansion of High-Speed Broadband and 5G Infrastructure
The global rollout of high-speed broadband and 5G networks serves as a primary growth driver for fiber optic cable assemblies. Telecom operators are upgrading legacy copper networks to fiber-rich architectures to support rising bandwidth demand generated by cloud computing, video streaming, and smart home ecosystems. 5G deployment requires dense backhaul and fronthaul networks, where fiber offers low latency and high capacity essential for massive MIMO and network slicing. Government-backed national broadband missions in regions such as North America, Europe, and Asia further accelerate fiber expansion across urban and rural zones. As operators invest heavily in long-haul, metro, and FTTH infrastructure, fiber optic assemblies become indispensable for ensuring connectivity reliability and long-distance signal integrity, reinforcing their strong market momentum.
- For instance, CommScope’s NOVUX™ hardened fiber terminals support up to 12 fiber ports per terminal and are engineered for rapid deployment in 5G small-cell backhaul, reducing installation time by up to 70% through pre-terminated assemblies.
Growing Demand from Data Centers and Cloud Ecosystems
Modern data centers depend heavily on fiber optic cable assemblies to handle ever-increasing workloads associated with AI training, hyperscale cloud platforms, edge computing, and virtualized multi-tenant environments. Fiber’s superior bandwidth and low-loss characteristics support high-density server interconnects, storage area networks, and dynamic workload orchestration. Cloud service providers are expanding global footprints with new hyperscale facilities, driving demand for structured cabling systems, high-fiber-count assemblies, and next-generation connectors such as MPO/MTP. As data volumes surge and latency requirements tighten, operators increasingly rely on single-mode fiber assemblies for long-reach connections across campus architectures and inter-data-center networks. Additionally, the shift toward AI-centric data center designs significantly boosts the adoption of high-performance optical interconnects, ensuring sustained demand across the industry.
- For instance, Coherent Corp. (formerly Finisar) supplies QSFP-DD Active Optical Cables (AOCs) supporting 4 x 100 Gb/s PAM4 or 8 x 50 Gb/s PAM4 transmission with reaches up to 100 meters over multimode fiber, which are widely used for GPU-to-switch connectivity in AI training clusters.
Rising Adoption of Fiber in Industrial, Automotive, and Defense Systems
Industrial automation, automotive electronics, and defense communication systems increasingly adopt fiber optic assemblies due to their immunity to electromagnetic interference, high signal fidelity, and superior durability. Smart factories utilize fiber-based networks to support robotics, process automation, and real-time monitoring in harsh operating environments where copper may fail. The automotive sector integrates fiber for advanced driver-assistance systems, in-vehicle communication networks, and infotainment systems requiring ultra-fast data transfer. In defense and aerospace applications, fiber assemblies enable secure, high-bandwidth communication for radar systems, avionics, and mission-critical surveillance networks. As industries undergo digital transformation and integrate more high-speed communication modules, demand for rugged, miniaturized, and high-temperature-resistant fiber assemblies continues to rise, reinforcing their growing role across diverse applications.
Key Trends & Opportunities
Increasing Shift Toward High-Density and Pre-Terminated Fiber Assemblies
A major trend shaping the market is the rising preference for high-density and pre-terminated fiber assemblies that streamline installation and minimize deployment time. Enterprises and data centers increasingly adopt plug-and-play MPO/MTP assemblies to support rapid scalability, reduced labor requirements, and improved error-free installation. High-density fiber solutions address space constraints in modern racks, cross-connects, and cable management systems. As edge data centers, colocation facilities, and multi-cloud environments expand, demand grows for compact, modular, and fully tested assemblies that guarantee consistent performance. This trend presents significant opportunities for manufacturers offering factory-terminated, low-loss solutions designed for fast deployment in mission-critical networks.
- For instance, CommScope’s Propel™ high-density MPO platform supports up to 3,456 fibers per rack using modular cassettes and offers typical insertion loss of 0.35 dB on low-loss MTP connectors, enabling rapid plug-and-play deployment.
Rising Integration of Fiber in Smart Cities and IoT Ecosystems
Smart city initiatives and IoT deployments create substantial opportunities for fiber optic cable assemblies. Large-scale sensor networks, intelligent transportation systems, utility automation, and public safety monitoring require high-speed, low-latency communication channels that fiber delivers efficiently. Governments and municipalities worldwide invest in fiber-backed infrastructure to support smart lighting, traffic analytics, surveillance, and digital services. As IoT devices proliferate across industrial, commercial, and residential spaces, fiber serves as the backbone enabling massive data transfer and reliable connectivity. This expanding digital ecosystem opens new market avenues for robust outdoor-rated fiber assemblies designed for long-term performance in varied environmental conditions.
- For instance, CommScope's hardened NOVUX™ Prodigy® fiber terminals deployed in municipal networks support up to 12 hardened ports per unit and operate across a wide temperature range of –40 °C to +65 °C (–40 °F to +149 °F), enabling reliable outdoor connectivity for smart-city cameras and sensors.
Advancements in Fiber Connectivity Technologies
Ongoing innovations such as bend-insensitive fibers, low-loss connectors, and ultra-compact high-fiber-count cables create opportunities for manufacturers to deliver differentiated, performance-enhanced solutions. New connector formats designed for 400G and 800G networks support hyperscale data center upgrades, while ruggedized assemblies enable deployment in harsh industrial and military environments. Continuous R&D in optical materials and production technologies improves assembly quality, flexibility, and thermal resistance. As next-generation communication standards emerge, suppliers offering advanced fiber components gain a competitive advantage in high-growth application areas including photonics, quantum communication, and future AI-optimized networks.
Key Challenges
High Installation Costs and Complex Deployment Processes
Despite strong adoption, the fiber optic cable assemblies market faces challenges related to high installation costs and labor-intensive deployment processes. Fiber networks require skilled technicians, precision handling, and specialized splicing tools, making initial setup expensive compared to copper-based systems. In developing regions, limited technical expertise and inadequate infrastructure slow adoption, especially for large-scale outdoor deployments. The need for careful cable routing, environmental protection, and stringent testing further increases the overall project cost. These factors pose financial constraints for small enterprises and rural operators, creating barriers that providers must address through modular, pre-terminated, and easy-install solutions.
Vulnerability to Physical Damage and Harsh Environmental Conditions
Fiber optic assemblies, though highly efficient, remain susceptible to physical strain, bending, and micro-fractures that can degrade signal quality. Outdoor deployments face added risks from moisture, temperature fluctuations, and rodent damage, requiring costly protective measures such as armored cables and weatherproof enclosures. Industrial environments with high vibration and mechanical stress can accelerate wear unless reinforced assemblies are used. Repairing damaged fiber networks often requires advanced tools and expert intervention, contributing to downtime and operational costs. These vulnerabilities underscore the need for ruggedized designs, improved materials, and continuous investment in robust protective solutions.
Regional Analysis
North America
North America holds a strong position in the fiber optic cable assemblies market, accounting for around 32% of global share, driven primarily by extensive FTTH rollouts, 5G densification, and large-scale data center expansions led by hyperscale operators. The U.S. benefits from significant government-backed broadband investments aimed at bridging rural connectivity gaps, while cloud providers continue to deploy high-fiber-count networks across multi-state data center clusters. Demand also rises from defense modernization programs and industrial automation upgrades. The region maintains consistent growth momentum supported by technological innovation, high digital adoption, and increasing deployment of low-latency communication systems.
Europe
Europe represents approximately 27% of the market, supported by aggressive fiber deployment targets under EU digital transformation initiatives. Countries such as Germany, France, the U.K., and the Nordics are accelerating FTTH penetration and 5G backhaul infrastructure, driving continuous demand for high-performance fiber assemblies. The region’s automotive, industrial automation, and aerospace sectors adopt advanced optical interconnects to enhance communication reliability and operational efficiency. Strong regulatory focus on network modernization, combined with extensive investments by telecom operators and municipal broadband providers, positions Europe as a mature and steadily expanding market for fiber-based communication technologies.
Asia-Pacific
Asia-Pacific dominates the global market with the largest share of around 36%, propelled by massive telecom infrastructure upgrades in China, India, Japan, and South Korea. Rapid urbanization, expanding broadband user bases, and large-scale deployment of 5G, cloud computing, and hyperscale data centers significantly accelerate fiber demand. Manufacturing-driven economies further invest in industrial digitalization, creating additional opportunities for robust optical assemblies. Strong government programs promoting national fiber networks and smart city development reinforce the region’s leadership. Asia-Pacific continues to outpace other regions in both production and consumption, benefiting from mature supply chains and competitive manufacturing capabilities.
Latin America
Latin America contributes about 3–4% of global market share, showing steady growth as countries invest in expanding broadband connectivity and modernizing telecom infrastructure. Brazil, Mexico, Chile, and Colombia lead adoption due to rising demand for high-speed internet, data center development, and 5G preparation. The region’s increasing digital service consumption-driven by e-commerce, fintech, and cloud platforms-supports fiber backbone and metro network expansion. Despite challenges such as inconsistent regulatory frameworks and varying economic stability, investments from global telecom players and regional ISPs continue to accelerate fiber optic deployments across urban and semi-urban areas.
Middle East & Africa
The Middle East & Africa region holds around 2–3% market share, with growth concentrated in Gulf countries such as the UAE, Saudi Arabia, and Qatar, where large-scale smart city projects and 5G rollouts rely heavily on advanced fiber backbones. Africa shows rising adoption as digital transformation initiatives expand fiber connectivity to support enterprise networks, education platforms, and public services. While infrastructural limitations and high deployment costs remain challenges, increasing investments from telecom operators and government programs gradually strengthen regional fiber networks, positioning MEA for long-term growth as digital infrastructure modernizes.
Market Segmentations:
By Mode
- Single Mode
- Multi Mode
By Type
- Glass Optical Fiber
- Plastic Optical Fiber
By Application
- Telecom
- Automobile
- Medical Equipment
- Power Utilities
- Aerospace & Defense
- Industrial Automation & Control
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the fiber optic cable assemblies market is characterized by strong participation from leading global manufacturers that continuously invest in advanced optical technologies, high-density interconnect solutions, and large-scale production capabilities. Companies such as Corning, Prysmian Group, Fujikura, CommScope, Nexans, OFS, and YOFC maintain their leadership through extensive product portfolios covering single-mode, multi-mode, MPO/MTP, ruggedized, and specialty fiber assemblies. These players focus on improving insertion loss performance, durability, and interoperability to meet the evolving needs of telecom operators, hyperscale data centers, and industrial automation sectors. Strategic initiatives-such as capacity expansions, fiber design innovations, and collaborations with equipment vendors-strengthen their global footprint. Competitors also leverage regional manufacturing hubs across Asia-Pacific, North America, and Europe to optimize costs and reduce lead times. As demand intensifies from 5G, FTTH, and cloud infrastructure projects, market players increasingly emphasize scalable production, enhanced quality standards, and tailored solutions for emerging high-bandwidth communication applications.
Key Player Analysis
- CommScope
- Finisar
- Leoni
- Coherent
- Nexans
- Rockwell Collins
- Reflex Photonics
- Corning Inc.
- Hitachi Cable
- L. Gore & Associates
Recent Developments
- In July 2025, Leoni AG Sale/closing of its Automotive Cable Solutions division to Time Interconnect Group (Hong Kong), enabling the fibre/cable-solutions division (Leoni Cable Solutions) to grow with new partner.
- In June 2025, Coherent Corp. Launch of a new line of disposable surgical fibre assemblies for laser lithotripsy and advanced medical applications. This is fibre assemblies but for medical/laser-delivery rather than telecom/data-centre cable assemblies.
- In May 2025, Collaboration with Emtelle on a hardened connectivity + blowable fibre-optic micro-cable solution for North America: “CommScope’s Prodigy® solution … combined with Emtelle’s blowable fibre optic micro-cable as the first offering of its kind in North America.”
Report Coverage
The research report offers an in-depth analysis based on Mode, Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for fiber optic cable assemblies will accelerate as 5G, FTTH, and high-speed broadband networks expand globally.
- Data centers will increasingly adopt high-density MPO/MTP and single-mode solutions to support AI, cloud, and hyperscale workloads.
- Growth in industrial automation will drive adoption of rugged, interference-resistant fiber assemblies for mission-critical operations.
- Automotive applications will expand as vehicles integrate advanced driver-assistance systems and high-bandwidth in-vehicle networks.
- Medical imaging and diagnostic equipment will rely more on precision fiber assemblies for higher data accuracy.
- Smart city and IoT deployments will boost the need for reliable, low-latency fiber backbones.
- Advancements in bend-insensitive and low-loss fibers will enhance performance in dense and complex installations.
- Manufacturers will increase production of pre-terminated assemblies to reduce installation time and improve network scalability.
- Regional manufacturing expansion will continue to lower costs and strengthen global supply chains.
- Competitive pressure will push companies to innovate in miniaturized, high-fiber-count, and thermally resilient assemblies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of High-Speed Broadband and 5G Infrastructure
The global rollout of high-speed broadband and 5G networks is driving demand for fiber optic cable assemblies, as telecom operators upgrade legacy copper networks to fiber-rich architectures to support rising bandwidth needs and low-latency requirements. Government-backed broadband initiatives and 5G densification projects further accelerate fiber deployment in both urban and rural areas.
Growth of Data Centers and Cloud Ecosystems
Modern data centers require high-density, low-loss fiber assemblies to support hyperscale workloads, AI training, and cloud computing. The need for scalable, high-bandwidth interconnects in server farms and multi-tenant environments is fueling adoption of advanced single-mode and MPO/MTP fiber assemblies.
Industrial Automation and Digital Transformation
Industries such as manufacturing, automotive, and utilities are increasingly adopting fiber optic assemblies for robust, interference-resistant communication in harsh environments. The shift toward smart factories, real-time monitoring, and advanced driver-assistance systems in vehicles is boosting demand for ruggedized and miniaturized fiber solutions.
Smart City and IoT Deployments
The proliferation of IoT devices and smart city infrastructure requires reliable, high-speed fiber backbones to support large-scale sensor networks, intelligent transportation, and public safety systems. Investments in municipal fiber networks and outdoor-rated assemblies are expanding the market’s reach.
Advancements in Fiber Connectivity Technologies
Innovations such as bend-insensitive fibers, low-loss connectors, and pre-terminated high-density assemblies are enabling faster, more reliable installations and supporting next-generation network upgrades. These technological advancements are making fiber optic cable assemblies more attractive for a wider range of applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Fiber Optic Cable Assemblies market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fiber Optic Cable Assemblies market projected to grow between 2025 and 2032?
Who are the major players in the global fiber optic cable assemblies market?
What are the major market drivers of the fiber optic cable assemblies industry?
What are the major market restraints of the fiber optic cable assemblies industry?
What are the major market opportunities of the fiber optic cable assemblies industry?
Who are the leading companies in the Fiber Optic Cable Assemblies market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Mode
- 1.2.1 Single Mode
- 1.2.2 Multi Mode
- 1.3 By Type
- 1.3.1 Glass Optical Fiber
- 1.3.2 Plastic Optical Fiber
- 1.4 By Application
- 1.4.1 Telecom
- 1.4.2 Automobile
- 1.4.3 Medical Equipment
- 1.4.4 Power Utilities
- 1.4.5 Aerospace & Defense
- 1.4.6 Industrial Automation & Control
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,707.5 million → 2032: USD 11,611.18 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fiber Optic Cable Assemblies Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fiber Optic Cable Assemblies Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fiber Optic Cable Assemblies Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fiber Optic Cable Assemblies Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fiber Optic Cable Assemblies Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fiber Optic Cable Assemblies Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fiber Optic Cable Assemblies Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fiber Optic Cable Assemblies Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,707.5 million → 2032: USD 11,611.18 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fiber Optic Cable Assemblies Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Mode - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single Mode
- 12.3.7.2 Multi Mode
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Glass Optical Fiber
- 12.4.7.2 Plastic Optical Fiber
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Telecom
- 12.5.7.2 Automobile
- 12.5.7.3 Medical Equipment
- 12.5.7.4 Power Utilities
- 12.5.7.5 Aerospace & Defense
- 12.5.7.6 Industrial Automation & Control
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fiber Optic Cable Assemblies End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Fiber Optic Cable Assemblies Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Fiber Optic Cable Assemblies Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Fiber Optic Cable Assemblies Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Corning Incorporated
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Prysmian Group
- 18.4 Fujikura Ltd.
- 18.5 CommScope
- 18.6 Nexans
- 18.7 OFS
- 18.8 Yangtze Optical Fibre and Cable (YOFC)
- 18.9 Coherent Corp.
- 18.10 Leoni AG
- 18.11 Hitachi Cable
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

