
Market Overview:
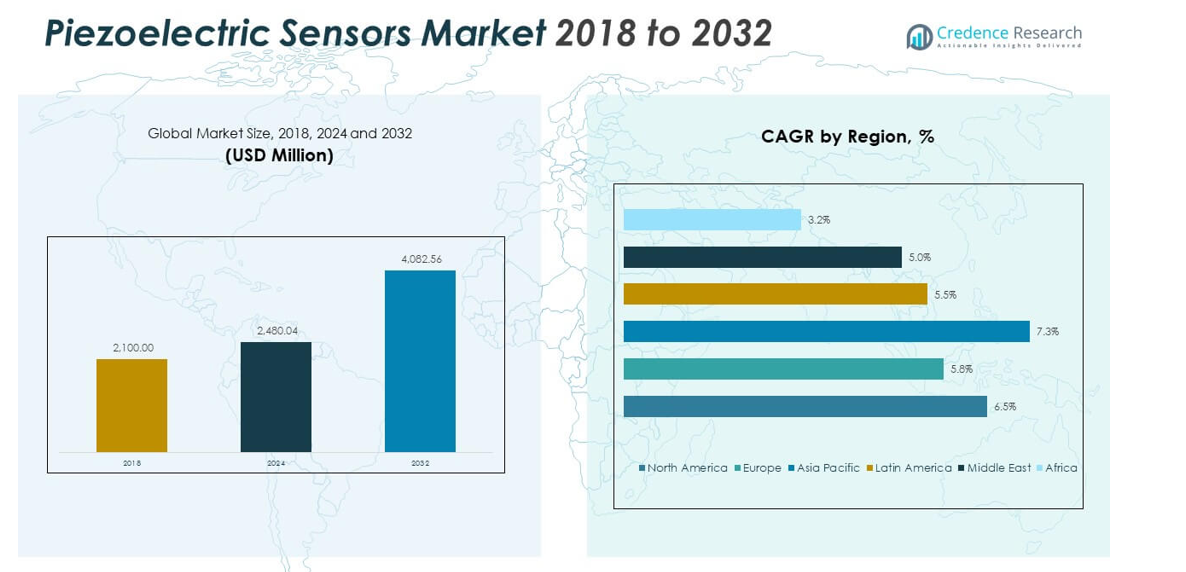
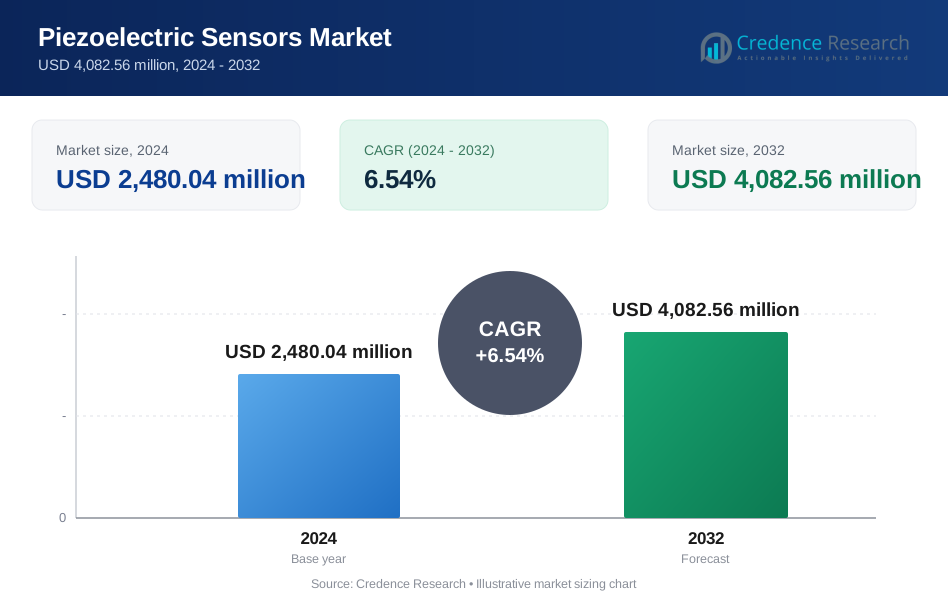
The Piezoelectric Sensors Market size was valued at USD 2,100.00 million in 2018, reached USD 2,480.04 million in 2024, and is anticipated to reach USD 4,082.56 million by 2032, at a CAGR of 6.54% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Piezoelectric Sensors Market Size 2024 | USD 2,480.04 million |
| Piezoelectric Sensors Market, CAGR | 6.54% |
| Piezoelectric Sensors Market Size 2032 | USD 4,082.56 million |
Strong adoption across automotive, aerospace, healthcare, and industrial sectors drives expansion. Manufacturers focus on miniaturization, high sensitivity, and energy efficiency to serve modern applications. Advancements in MEMS technology and new piezoelectric materials enhance sensor performance in harsh environments. The market benefits from increasing integration of sensors into IoT-based systems for real-time diagnostics and predictive maintenance. Demand for high-accuracy vibration, pressure, and force detection continues to rise across industries emphasizing safety, efficiency, and data-driven control.
Regionally, Asia Pacific leads the market due to rapid industrialization and growing electronics production in China, Japan, and South Korea. North America follows with strong demand from aerospace, defense, and healthcare sectors emphasizing innovation and precision monitoring. Europe maintains steady growth supported by strict quality standards and advanced industrial automation. Latin America and the Middle East show emerging potential with rising industrial modernization, while Africa experiences gradual adoption through expanding infrastructure and energy projects.
Market Insights:
- The Piezoelectric Sensors Market was valued at USD 2,100.00 million in 2018, reached USD 2,480.04 million in 2024, and is projected to hit USD 4,082.56 million by 2032, growing at a CAGR of 6.54%.
- Asia Pacific leads the market with a 46.38% share, driven by industrial automation, rising electronics output, and robust manufacturing expansion across China, Japan, and South Korea.
- Europe holds a 22.97% share, supported by advanced automotive systems, industrial modernization, and strong regulatory compliance for precision sensing. North America follows with a 20.85% share, led by aerospace, healthcare, and defense integration.
- Asia Pacific remains the fastest-growing region with a 7.3% CAGR, fueled by rapid technology adoption and strong government initiatives promoting smart manufacturing and IoT-based systems.
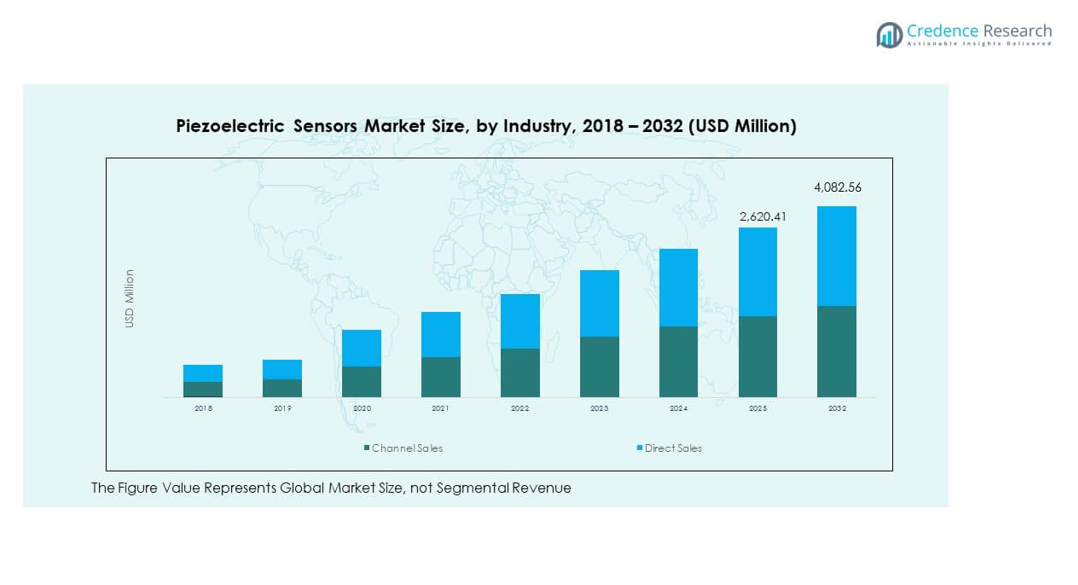
- By industry, direct sales dominate with 60% of market share due to OEM supply networks, while channel sales account for 40%, catering to small and mid-scale industrial customers worldwide.
Market Drivers
Expanding Adoption of Smart Technologies Across Industrial and Consumer Applications
The Piezoelectric Sensors Market benefits from rising demand in smart electronics, medical instruments, and automotive systems. It supports real-time feedback, vibration detection, and energy harvesting functions in connected environments. Manufacturers use sensors for precision control in autonomous vehicles and predictive maintenance in factories. The integration of piezoelectric sensors into IoT-enabled platforms strengthens operational reliability. Healthcare equipment, including ultrasound devices and wearable monitors, increasingly depends on these sensors. Their miniaturized design allows compact product development. Industries value these sensors for long-term stability and rapid response. This growth aligns with global adoption of automation and intelligent systems.
Increased Focus on Energy Efficiency and Sustainable Industrial Practices
Industries prioritize energy-efficient solutions that minimize waste and environmental impact. The Piezoelectric Sensors Market gains traction from this transition by offering self-powered and maintenance-free devices. These sensors generate electric charge from mechanical stress, reducing reliance on external power. Manufacturers incorporate them into energy monitoring and harvesting systems for low-power electronics. Automotive firms deploy piezoelectric components in fuel injection and brake monitoring for enhanced precision. The shift toward sustainable manufacturing increases investment in smart sensor integration. Their application extends into renewable energy sites, enabling real-time condition analysis. This efficiency-driven shift strengthens their role in next-generation industrial ecosystems.
- For instance, Texas Instruments offers vibration sensing reference designs such as the TIDA-01471, which feature 24-bit data conversion and up to 20 kHz bandwidth for precision vibration and energy monitoring applications. These designs support industrial condition monitoring and predictive maintenance in automated systems.
Strong Integration in Automotive Safety, Comfort, and Performance Systems
Vehicle manufacturers adopt piezoelectric sensors for detecting acceleration, pressure, and knock intensity in engines. It helps improve combustion efficiency, airbag deployment, and ride stability. The Piezoelectric Sensors Market experiences rapid adoption due to electric and autonomous vehicle expansion. The sensors provide high sensitivity and resistance to electromagnetic interference. Companies deploy these devices in tire pressure monitoring and vibration analysis for predictive diagnostics. The shift toward vehicle electrification increases reliance on real-time monitoring tools. Manufacturers prioritize compact and durable sensors suitable for harsh automotive environments. Rising investment in advanced driver-assistance systems accelerates their integration.
Advancements in Miniaturization and High-Precision Sensor Fabrication
Miniaturization drives broader acceptance across medical, aerospace, and wearable applications. The Piezoelectric Sensors Market benefits from progress in MEMS and nanomaterial technology. These innovations enhance sensitivity and enable multi-parameter sensing in compact designs. Manufacturers achieve mass production through refined wafer-level processes. Healthcare devices, drones, and robotics integrate these components for improved control accuracy. Their resistance to temperature and vibration supports demanding use cases. Research into advanced piezoelectric materials like PZT and PVDF improves efficiency and durability. These advancements position the sensors as critical enablers in next-generation smart environments.
- For instance, Texas Instruments’ PGA970 signal-conditioner integrates dual 24-bit ADCs and operates within a –40 °C to +125 °C temperature range. It provides precision signal conditioning for piezoelectric and resistive sensors used in industrial and automotive monitoring applications.
Market Trends
Growing Adoption of Wireless and IoT-Enabled Piezoelectric Sensors
The market shifts toward wireless sensor networks that offer seamless data transmission. The Piezoelectric Sensors Market aligns with IoT ecosystems to enable real-time monitoring. These sensors deliver precise feedback for asset tracking, vibration control, and smart building systems. Engineers implement them in machinery for condition-based maintenance. The removal of cables simplifies installation and lowers maintenance costs. Energy-harvesting piezoelectric devices reduce dependence on batteries. This integration enhances operational uptime and analytics accuracy. Manufacturers focus on scalable, interoperable sensor designs to support digital transformation.
Increasing Use of Piezoelectric Sensors in Medical and Healthcare Devices
Medical technology developers leverage piezoelectric sensors for diagnostic and therapeutic systems. The Piezoelectric Sensors Market benefits from their use in ultrasound, blood pressure monitors, and surgical instruments. These sensors provide accurate biological feedback and motion sensing. Miniaturized configurations support implantable and wearable medical devices. Hospitals use them for patient monitoring and advanced imaging systems. Their stability ensures long-term reliability in sensitive clinical environments. The demand for personalized health tracking fuels continuous innovation. Integration with digital health platforms improves predictive patient care.
Rising Role in Aerospace, Defense, and Industrial Automation Systems
Aerospace and defense sectors employ piezoelectric sensors for vibration, acceleration, and structural health monitoring. The Piezoelectric Sensors Market supports precision navigation and engine control under extreme conditions. Industrial automation incorporates these devices for detecting micro-movements in production lines. Their high reliability under stress makes them vital for mission-critical systems. Manufacturers adopt them in turbine control and robotic joints for accuracy. Continuous advancements in ruggedized packaging expand operational ranges. The sensors’ low power consumption enhances usability in remote and unmanned platforms. This broad utility reinforces their strategic role across high-performance industries.
- For instance, TE Connectivity’s piezoelectric film sensors operate within a temperature range of –40 °C to +85 °C and are engineered for dynamic strain and vibration sensing. These sensors are used in applications such as industrial equipment monitoring, vibration analysis, and energy harvesting systems.
Emergence of Advanced Materials and Hybrid Sensor Architectures
Material innovation shapes sensor evolution with enhanced durability and accuracy. The Piezoelectric Sensors Market benefits from hybrid composites combining polymers and ceramics. These materials improve flexibility, thermal resistance, and charge stability. Manufacturers explore lead-free alternatives to meet regulatory standards. Advanced coating techniques extend sensor life under corrosive or high-pressure conditions. Researchers develop multi-functional sensors capable of detecting vibration, strain, and temperature simultaneously. These next-generation designs cater to industrial and biomedical applications. Hybridization supports new form factors suited for flexible electronics and wearables.
- For instance, Ferro Corporation produces lead-free piezoelectric ceramics designed for sustainable performance and reduced environmental impact. These materials exhibit strong thermal stability and charge sensitivity, making them suitable for ultrasonic transducers and industrial sensing devices.
Market Challenges Analysis
High Production Costs and Complex Manufacturing Processes
The Piezoelectric Sensors Market faces constraints from high raw material and production costs. Advanced ceramics and precision machining increase capital requirements for mass manufacturing. Fabrication of thin-film piezoelectric layers demands specialized equipment and technical expertise. These cost barriers limit penetration in small and medium-scale industries. Scaling production while maintaining sensitivity and uniformity remains difficult. Supply chain volatility of rare materials further adds to expense fluctuations. Limited economies of scale slow down price competitiveness against alternative sensing technologies. This challenge pushes manufacturers to explore cost-effective material substitutes and automated production systems.
Technical Integration Barriers and Environmental Sensitivity
Integration of piezoelectric sensors into electronic circuits can be complex. The Piezoelectric Sensors Market must address compatibility issues with digital systems and signal conditioning hardware. Sensors are sensitive to extreme humidity, temperature, and vibration beyond calibrated limits. Their fragility under mechanical stress reduces lifespan in some industrial applications. Calibration drift impacts measurement accuracy in long-term operations. End users require consistent output stability to maintain operational reliability. Overcoming these integration and performance barriers demands ongoing R&D. Advances in encapsulation and adaptive electronics can help reduce these limitations.
Market Opportunities
Rising Demand for Smart Infrastructure and Predictive Maintenance Systems
Smart infrastructure development generates strong opportunities for the Piezoelectric Sensors Market. Cities adopt intelligent monitoring systems for bridges, railways, and industrial assets. These sensors detect structural strain, vibration, and pressure changes in real time. Predictive maintenance programs depend on continuous data from such systems. Manufacturers collaborate with infrastructure projects to embed sensors into critical components. Integration with cloud-based platforms enhances performance insights and safety compliance. The growing focus on preventive asset management drives commercial adoption.
Expanding Role in Consumer Electronics and Emerging Wearable Technologies
Consumer devices and wearables open lucrative paths for piezoelectric innovation. The Piezoelectric Sensors Market benefits from motion detection and haptic feedback applications. These sensors improve responsiveness in gaming, fitness tracking, and portable gadgets. Lightweight and flexible materials support seamless design integration. Developers leverage their self-powering capability for longer battery life. Expansion in 5G-enabled devices amplifies real-time interaction potential. Ongoing miniaturization and low-power operation enhance their fit for next-generation consumer products.
Market Segmentation Analysis:
The Piezoelectric Sensors Market is segmented by sensor type, industry, and end-user, reflecting diverse industrial and technological applications.
By sensor type, piezoelectric force sensors lead due to their precision in dynamic force measurement across manufacturing and automotive systems. Piezoelectric accelerometer sensors hold significant demand in vibration monitoring and predictive maintenance within aerospace, machinery, and defense sectors. Piezoelectric pressure sensors expand adoption in process control, fuel systems, and medical diagnostics, supported by compact design and high sensitivity. The “others” category includes torque and ultrasonic sensors used in niche applications such as robotics and industrial testing.
- For instance, HBM's PACEline CFTplus piezoelectric force transducers offer calibrated measuring capacities of 25, 50, 70, and 120 kN with an accuracy class of 0.5 and high fundamental frequency for precise measurement in fast processes like press-fit manufacturing. These sensors come pre-stressed and ready-to-use without recalibration, designed for industrial dynamic force measurement applications.
By industry, direct sales dominate through customized sensor supply to OEMs and automation integrators, while channel sales expand across regional distributors and online networks catering to small and medium manufacturers.
- For instance, Meggitt Sensing Systems develops piezoelectric accelerometers and vibration sensors for aerospace and defense applications, supporting flight testing and engine health monitoring. These high-performance sensors are designed for precise measurement in harsh environments, ensuring reliability for OEMs in critical aviation systems.
By end-user, the automotive sector remains the largest adopter, deploying sensors in engine monitoring, airbag systems, and tire pressure detection. Healthcare applications grow fast through integration in imaging, diagnostic, and patient monitoring equipment. Manufacturing uses these sensors for vibration analysis and process optimization, whereas aerospace and defense rely on them for flight testing, propulsion systems, and safety monitoring. It maintains steady growth across other industries, including energy and consumer electronics, supported by digital transformation and automation advances.
Segmentation:
By Sensors Type
- Piezoelectric Force Sensor
- Piezoelectric Accelerometer Sensor
- Piezoelectric Pressure Sensor
- Others
By Industry
- Direct Sales
- Channel Sales
By End-User
- Automotive
- Healthcare
- Manufacturing
- Aerospace & Defence
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Piezoelectric Sensors Market size was valued at USD 447.30 million in 2018, reached USD 517.32 million in 2024, and is anticipated to reach USD 849.59 million by 2032, at a CAGR of 6.5% during the forecast period. North America holds 20.85% of the global share, driven by strong industrial automation, automotive, and aerospace applications. It benefits from robust R&D activities and early adoption of smart sensor technologies. Key manufacturers focus on miniaturization and multi-axis measurement sensors for precision applications. Healthcare and defense sectors integrate these sensors to enhance safety and performance. Presence of companies like Honeywell and TE Connectivity strengthens the regional ecosystem. High standards for safety and reliability encourage technological innovation. The market maintains steady growth supported by advanced manufacturing and regulatory frameworks.
Europe
The Europe Piezoelectric Sensors Market size was valued at USD 533.40 million in 2018, grew to USD 604.57 million in 2024, and is projected to reach USD 937.98 million by 2032, at a CAGR of 5.8% during the forecast period. Europe accounts for 22.97% of the global share and demonstrates strong adoption across automotive and industrial machinery. Germany, France, and the U.K. lead in R&D focused on automated production and energy efficiency. The Piezoelectric Sensors Market in the region benefits from stringent regulations promoting precision monitoring in manufacturing and healthcare. Aerospace and defense programs integrate advanced sensor technologies for high-accuracy control systems. Renewable energy projects enhance sensor deployment for vibration and pressure tracking. Manufacturers prioritize lead-free materials to meet environmental directives. The region remains a major export hub for specialized sensor solutions.
Asia Pacific
The Asia Pacific Piezoelectric Sensors Market size was valued at USD 896.70 million in 2018, increased to USD 1,085.88 million in 2024, and is forecast to reach USD 1,895.54 million by 2032, at a CAGR of 7.3% during the forecast period. Asia Pacific dominates the global market with 46.38% share, led by China, Japan, and South Korea. Rapid industrialization and growth in consumer electronics accelerate sensor demand. It supports mass production of automotive, robotics, and semiconductor equipment using advanced sensor integration. Government incentives for smart manufacturing boost local development. Healthcare and aerospace segments expand due to improved infrastructure and technology transfer. Strong supply chains ensure competitive costs and production efficiency. Regional players focus on scalable designs for IoT and AI-driven applications.
Latin America
The Latin America Piezoelectric Sensors Market size was valued at USD 121.80 million in 2018, reached USD 142.33 million in 2024, and is expected to reach USD 215.84 million by 2032, at a CAGR of 5.5% during the forecast period. Latin America represents 5.28% of the global market share, driven by expanding automotive and manufacturing industries in Brazil and Mexico. It benefits from rising industrial automation and digital monitoring adoption. Manufacturers explore piezoelectric sensors for process optimization and equipment safety. Healthcare applications see gradual expansion due to improving infrastructure. Growing investment in smart energy and transportation adds new growth avenues. The region’s manufacturing capacity and favorable trade policies encourage foreign collaborations. It shows steady potential for long-term industrial growth.
Middle East
The Middle East Piezoelectric Sensors Market size was valued at USD 71.40 million in 2018, rose to USD 78.35 million in 2024, and is anticipated to reach USD 114.74 million by 2032, at a CAGR of 5.0% during the forecast period. The region holds 2.80% of the global market share, driven by increasing automation in oil and gas, defense, and infrastructure projects. The Piezoelectric Sensors Market in this region gains support from industrial modernization plans in GCC countries. Manufacturers adopt vibration and pressure monitoring for machinery efficiency. Healthcare and aerospace investments strengthen demand for high-precision devices. Technological partnerships with European firms enhance local production standards. The market favors robust, environment-resistant sensor designs for harsh climates. Steady infrastructure spending fuels moderate expansion across industries.
Africa
The Africa Piezoelectric Sensors Market size was valued at USD 29.40 million in 2018, increased to USD 51.59 million in 2024, and is expected to reach USD 68.87 million by 2032, at a CAGR of 3.2% during the forecast period. Africa captures 1.72% of the global market share and shows gradual growth across industrial and energy applications. South Africa and Egypt lead adoption with stronger automation initiatives. It benefits from increasing investment in manufacturing and infrastructure modernization. Mining and energy projects use sensors for safety and equipment monitoring. Healthcare integration is improving with imported medical devices using piezoelectric components. Limited local production keeps import reliance high, but demand rises steadily. Supportive government projects and training programs enhance regional readiness for technology adoption.
Key Player Analysis:
- TE Connectivity
- Honeywell International Inc.
- PCB Piezotronics (MTS Systems Corporation)
- APC International, Ltd.
- CeramTec GmbH
- CTS Corporation
- Kistler Group
- Meggitt PLC
- PI Ceramic GmbH (Physik Instrumente)
- Kyocera Corporation
Competitive Analysis:
The Piezoelectric Sensors Market features a concentrated field of global leaders and specialist players that vie based on innovation, global reach, and customer-specific solutions. Key firms such as TE Connectivity, Honeywell International Inc. and PCB Piezotronics (MTS Systems Corporation) hold strong positions owing to their broad product portfolios and robust distribution networks. These companies invest heavily in R&D to improve sensitivity, miniaturisation and integration capabilities. Smaller specialised players such as CeramTec GmbH, CTS Corporation and Kistler Group focus on niche applications and value-added services to boost their standings. Competitive pressures centre on providing high performance at lower cost, enabling multi-parameter sensing and leveraging regional manufacturing advantages. It drives consolidation, partnerships and regional expansion efforts among players. Continuous differentiation through customisation, advanced materials and end-user support marks the competitive landscape.
Recent Developments:
- In February 2025, TE Connectivity announced the acquisition of Richards Manufacturing Co., enhancing its position in the energy market by expanding its product portfolio and expertise in electrical utilities and underground electrical networks, aligning with grid modernization trends.
- In September 2024, Spectris plc made a significant acquisition by purchasing Piezocryst Advanced Sensorics GmbH for approximately €133.5 million, a move aimed at strengthening their position in advanced piezoelectric sensors for aerospace and structural health monitoring.
- In March 2024, KCF Technologies launched a new Piezo Sensing product as part of its SMARTsensing suite, designed to deliver precise measurements across various industrial applications including automotive and energy.
Report Coverage:
The research report offers an in-depth analysis based on sensor type, industry, and end-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market
Future Outlook:
- Expanding integration of piezoelectric sensors in electric vehicles and autonomous systems will drive performance reliability and safety enhancement.
- Rising deployment of IoT and AI-enabled platforms will strengthen real-time data utilization and predictive maintenance capabilities.
- Growing miniaturization and low-power design innovations will expand applications in wearables and implantable medical devices.
- Increasing investments in advanced materials such as lead-free ceramics and polymers will enhance sensor efficiency and sustainability.
- The rapid shift toward Industry 4.0 and smart manufacturing environments will boost demand for vibration and pressure monitoring systems.
- Expanding aerospace and defense programs will create strong opportunities for precision sensing in navigation and control systems.
- Rising emphasis on energy harvesting and self-powered sensors will accelerate adoption across remote monitoring networks.
- Healthcare modernization will increase sensor integration in diagnostic imaging, surgical equipment, and portable monitoring devices.
- Strategic collaborations between global manufacturers and regional suppliers will optimize production scalability and innovation speed.
- Continued automation in infrastructure and industrial systems will secure long-term growth momentum for the Piezoelectric Sensors Market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Adoption of Smart Technologies Across Industrial and Consumer Applications
Piezoelectric sensors are increasingly integrated into smart electronics, medical instruments, and automotive systems, enabling real-time feedback, vibration detection, and energy harvesting. Their miniaturized design and high sensitivity support precision control in autonomous vehicles, predictive maintenance in factories, and advanced healthcare equipment.
Increased Focus on Energy Efficiency and Sustainable Industrial Practices
Industries are prioritizing energy-efficient and self-powered solutions, and piezoelectric sensors generate electric charge from mechanical stress, reducing reliance on external power sources. This supports their use in energy monitoring, harvesting systems, and sustainable manufacturing, especially in automotive and renewable energy sectors.
Strong Integration in Automotive Safety, Comfort, and Performance Systems
Automotive manufacturers deploy piezoelectric sensors for engine monitoring, airbag deployment, and tire pressure detection, enhancing vehicle safety and performance. The shift toward electric and autonomous vehicles further accelerates demand for real-time, high-sensitivity monitoring tools.
Advancements in Miniaturization and High-Precision Sensor Fabrication
Progress in MEMS and nanomaterial technology has enabled the production of smaller, more sensitive piezoelectric sensors. These advancements allow for multi-parameter sensing in compact designs, expanding applications in wearables, medical devices, drones, and robotics.
Growing Adoption of Wireless and IoT-Enabled Piezoelectric Sensors
The integration of piezoelectric sensors into wireless and IoT-enabled platforms allows for seamless real-time monitoring and predictive maintenance. This trend supports digital transformation in industrial automation, smart infrastructure, and asset tracking, driving broader market adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Piezoelectric Sensors Market?
At what Compound Annual Growth Rate is the Piezoelectric Sensors Market projected to grow between 2024 and 2032?
What factors are driving the growth of the Piezoelectric Sensors market?
What are the key segments within the Piezoelectric Sensors market?
What is the base year considered for Piezoelectric Sensors Market?
Who are the leading companies in the Piezoelectric Sensors Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Automotive
- 1.2.2 Healthcare
- 1.2.3 Manufacturing
- 1.2.4 Aerospace & Defence
- 1.2.5 Others
- 1.3 By Industry
- 1.3.1 Direct Sales
- 1.3.2 Channel Sales
- 1.4 By Sensor Type
- 1.4.1 Piezoelectric Force Sensor
- 1.4.2 Piezoelectric Accelerometer Sensor
- 1.4.3 Piezoelectric Pressure Sensor
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,480.04 million → 2032: USD 4,082.56 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Piezoelectric Sensors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Piezoelectric Sensors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Piezoelectric Sensors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Piezoelectric Sensors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Piezoelectric Sensors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Piezoelectric Sensors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Piezoelectric Sensors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Piezoelectric Sensors Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,480.04 million → 2032: USD 4,082.56 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Piezoelectric Sensors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Automotive
- 12.3.7.2 Healthcare
- 12.3.7.3 Manufacturing
- 12.3.7.4 Aerospace & Defence
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Direct Sales
- 12.4.7.2 Channel Sales
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sensor Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Piezoelectric Force Sensor
- 12.5.7.2 Piezoelectric Accelerometer Sensor
- 12.5.7.3 Piezoelectric Pressure Sensor
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Piezoelectric Sensors End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Piezoelectric Sensors Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Piezoelectric Sensors Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Piezoelectric Sensors Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 TE Connectivity
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Honeywell International Inc.
- 18.4 PCB Piezotronics (MTS Systems Corporation)
- 18.5 APC International, Ltd.
- 18.6 CeramTec GmbH
- 18.7 CTS Corporation
- 18.8 Kistler Group
- 18.9 Meggitt PLC
- 18.10 PI Ceramic GmbH (Physik Instrumente)
- 18.11 Kyocera Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

